

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Reports Disposable Syringes Market to Reach $34M by 2032, Growing at 6.5% CAGR 2026-2032

Navigating the Next Wave: Strategic Insights into the Global Disposable Syringes Market (2026–2032)
The global healthcare landscape is undergoing a structural transformation, and the disposable syringes market stands at the intersection of clinical safety, regulatory tightening, and supply chain modernization. Over the past half-decade, the sector has demonstrated steady upward momentum, with historical revenue climbing from approximately 18.0 million USD in 2020 to 23.8 million USD in 2025. As we move through the forecast window extending to 2032, market projections indicate a trajectory toward 34.0 million USD, supported by a compound annual growth rate of 6.5 percent. These figures are not merely retrospective summaries; they are strategic signposts that reveal where procurement budgets, manufacturing capacity, and regulatory compliance investments will be allocated in the coming years.
For executives, investors, and supply chain leaders, the question is no longer whether the disposable syringes sector will grow, but how to position operations, partnerships, and product portfolios to capture disproportionate value within that expansion. The latest edition of our Disposable Syringes Market research is engineered to translate macroeconomic momentum into actionable intelligence. This article previews the analytical architecture of the report, outlines the competitive and regulatory currents shaping the landscape, and explains why a disciplined, data-grounded reading of this market is essential for 2026 decision-making.
Why 2026 Is a Inflection Point for Syringe Market Strategy
The forecast period opens against a backdrop of compounding forces. Procurement cycles are lengthening, safety-engineering mandates are widening, and immunization programs are recalibrating their supply specifications. Historical data from 2020 through 2025 shows a market that has resisted volatility and continued to expand, with 2025 closing at 23.8 million USD. The early forecast years project 24.74 million USD in 2026 and 27.3 million USD in 2027, signaling that growth is not being driven by a single temporary catalyst but by durable structural demand.
Three strategic realities make 2026 particularly consequential. First, regulatory frameworks across major markets are moving from voluntary safety adoption to codified performance requirements. Second, reimbursement adjustments in key regions are reshaping downstream unit demand for self-administered and clinical injectable therapies. Third, global health procurement agencies are institutionalizing long-term agreements that reward manufacturers and distributors who can demonstrate both compliance consistency and volume reliability. Companies that treat these shifts as isolated events will miss the compounding effect; those that map them to their product lines, sourcing strategies, and market-entry plans will secure a measurable advantage.
Our research is built to help decision-makers separate signal from noise. Rather than offering a static snapshot, the report is structured to show how historical baselines, forward projections, and operational milestones interact across the forecast horizon. The goal is to give leadership teams a shared analytical language for capacity planning, pricing strategy, and competitive positioning.
Inside the Report: Analytical Architecture and Practical Utility
This study is designed as a working intelligence asset, not a passive reference document. It combines top-down market sizing with bottom-up segmentation logic, then layers in competitive profiling, regulatory mapping, and procurement-signal tracking. The result is a multi-dimensional view that can be directly plugged into strategic planning cycles.
At the macro level, the report anchors on verified historical revenue from 2020 through 2025 and extends forward through 2032. The forecast pathway is constructed to reflect realistic adoption curves, procurement timing, and regional demand diffusion. This structure allows users to test scenarios against a consistent baseline and evaluate where incremental investment is most likely to yield returns.
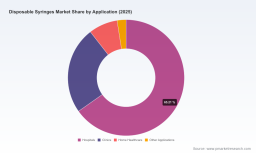
The segmentation framework is built to expose where value concentrates and where operational complexity rises. By volume class, the market spans a range of syringe formats, from lower-volume configurations that dominate high-frequency clinical use to larger-volume variants that serve specialized infusion and procedure settings. By end-use environment, the analysis tracks how institutional care settings, ambulatory and clinic-based networks, home healthcare channels, and other application streams each contribute to overall demand patterns. By geography, the report examines how mature markets, high-growth regions, and emerging procurement corridors differ in pricing sensitivity, regulatory pacing, and channel dynamics.
Importantly, the report does not stop at descriptive segmentation. It connects volume distributions and application footprints to strategic implications: which formats are most exposed to safety-engineering mandates, which care settings are most likely to expand procurement as reimbursement landscapes shift, and which geographic markets present the steepest compliance or distribution hurdles. This is the kind of connective analysis that helps teams prioritize product adaptation, sales-force deployment, and supplier qualification.
Beyond sizing and segmentation, the report integrates the operational pulse of the industry. It catalogues regulatory touchpoints that affect product design, labeling, and market access. It tracks reimbursement developments that influence downstream unit consumption. It monitors raw-material and procurement pricing signals that shape margin expectations. And it follows corporate activity—from trade show participation to regulatory clearances and tender announcements—that indicates where competitors are investing attention and capacity.
For each component, the report emphasizes practical application. Procurement teams can use the segmentation logic to validate sourcing mixes. Commercial leaders can use the competitive profiles to benchmark positioning and identify white space. Regulatory and quality functions can use the compliance mapping to anticipate documentation, testing, and certification requirements. Executive teams can use the forecast structure to align long-range planning with realistic growth pacing.
Competitive Landscape: Incumbents, Specialists, and Shifting Battle Lines
Market structure matters as much as market size. The disposable syringes sector is characterized by a concentrated core of large, globally integrated manufacturers alongside a broad tier of regional specialists and safety-focused innovators. Concentration metrics indicate that the top three players account for roughly 45 percent of market revenue, while the top five extend that share to about 65 percent. This hierarchy shapes pricing leverage, procurement relationships, and the speed at which new safety or design standards can be absorbed across the supply base.
At the center of the landscape are established medical technology and device manufacturers with broad hospital and clinic reach. Becton, Dickinson and Company stands as one of the largest providers of disposable syringes across conventional, safety, and auto-disable formats, serving immunization programs, acute care, and routine clinical use. Its scale and distribution footprint make it a reference point for compliance standardization and volume reliability. Terumo Corporation, based in Tokyo, is recognized as a pioneer and major producer of disposable syringes and needles with an emphasis on precision, clinical safety, and GMP-compliant sterile production. Nipro Corporation contributes a parallel strength in volume-based manufacturing for global healthcare supply chains, reinforcing the importance of scale, consistency, and export readiness.
European manufacturers add distinct engineering and safety-engineering perspectives. B. Braun SE produces disposable syringes and related medical devices with a clear focus on safety-engineered and infusion-compatible models, aligning product development with the needs of integrated care settings. CODAN Medizinische Geräte GmbH supplies safety and standard models designed to comply with international standards, while Gerresheimer AG brings material expertise through glass and polymer disposable syringes used in pharmaceutical and clinical applications. These firms illustrate how material science, device compatibility, and compliance assurance can become differentiators in markets where specification scrutiny is rising.
The specialist tier is equally important to watch. Retractable Technologies, Inc. focuses on retractable and safety disposable syringes designed to reduce needlestick injury risk, a positioning that directly intersects with occupational safety priorities and procurement criteria. ICU Medical, Inc. supplies sterile, single-use disposable syringes and infusion systems for clinical use, and Exelint International, Co. offers EXEL-branded disposable syringes with secure-touch safety needles, reinforcing the commercialization of ergonomic and safety-oriented design features. On the international supply side, Star Syringe Limited emphasizes quality and sterility in disposable and safety syringes, while Hindustan Syringes and Medical Devices Limited produces safety and auto-disable variants for both domestic and export markets. In Asia, KMED Kangyi Medical and Liaoning KANGYI Medical Equipment Co., Ltd. supply disposable syringes, infusion sets, and related medical disposables certified to MDR and ISO standards, reflecting the growing role of compliant Asian manufacturers in international procurement channels.
Recent corporate activity underscores how dynamic this landscape has become. In late 2025, Exelint International, Co. received FDA 510(k) clearance for EXEL Disposable Syringes with Needles, including models with Secure Touch safety needles, signaling continued U.S. market entry and product expansion. Trade channels have also been active: Liaoning KANGYI Medical Equipment Co., Ltd. presented disposable syringes and related medical devices at MEDICA 2025 in Düsseldorf, and Healthtopmed exhibited disposable syringes, insulin syringes, and auto-destroy syringes at Arab Health 2025. Looking ahead, YIZUMI is scheduled to exhibit at the 93rd CMEF 2026 in Shanghai, focusing on medical injection molding and production solutions relevant to disposable syringes. These events are not peripheral; they are indicators of where product roadmaps, manufacturing partnerships, and distribution alliances are being negotiated.
Worldwide Disposable Medical Syringe Market
For buyers and competitors alike, the strategic takeaway is that market leadership is increasingly defined by more than unit volume. It is defined by the ability to align product portfolios with safety mandates, maintain compliance documentation across jurisdictions, and demonstrate consistent supply performance in both institutional and programmatic procurement environments. The report's competitive profiling is designed to help users read these signals systematically rather than anecdotally.
Regulatory, Procurement, and Demand Dynamics Reshaping the Field
The disposable syringes market does not expand in a vacuum. It is being re-shaped by regulation, reimbursement, and programmatic procurement expectations that together influence product specification, pricing, and channel strategy. Understanding these dynamics is essential for anyone planning capacity, entering new markets, or renegotiating supplier relationships in 2026.
On the regulatory side, safety and performance requirements are becoming more explicit. The EU Medical Device Regulation classifies safety syringes as Class IIa devices and requires compliance with ISO 23908 performance testing, reinforcing a framework in which safety-engineered designs must meet documented performance benchmarks rather than general expectations. In parallel, WHO's Global Injection Safety Initiative mandates the exclusive use of auto-disable and safety syringes in immunization programs worldwide, elevating compliance from a procurement preference to a program-level prerequisite. UNICEF prequalification further tightens the specification environment by requiring auto-disable syringes to comply with ISO 7886-3 for fixed-dose immunization use. These standards do not merely restrict the market; they define the qualification threshold for participation in high-volume public health supply chains.
Reimbursement developments are adding another layer of demand influence. In the United States, CMS broadened reimbursement in 2025 for self-injectable anticoagulants, adding a meaningful number of prefilled units to annual demand. This kind of policy shift changes the downstream consumption environment for syringe formats used in self-administration and ambulatory care, and it illustrates how payer decisions can ripple into device demand with limited lead time. For manufacturers and distributors, the implication is clear: reimbursement calendars and clinical practice changes should be monitored as closely as production metrics.
Procurement behavior is also evolving. UNICEF's issuance of RFP-DAN-2025-503825 for long-term agreements to supply safe injection equipment, including disposable syringes and auto-disable syringes for 2026–2027 procurement, signals a preference for multi-year supply commitments that reward reliability, scale, and compliance consistency. At the same time, pricing dynamics remain a practical concern. UNICEF paid approximately 0.08 to 0.12 USD per auto-disable syringe unit in 2025, compared with about 0.05 USD for conventional designs. This gap highlights a persistent tension: safety and auto-disable features are increasingly non-negotiable in many programs, yet they carry higher unit costs and therefore place pressure on sourcing strategies, subsidy structures, and volume planning.
Disposable Syringes Market
Together, these dynamics create a market environment in which compliance, specification alignment, and procurement readiness are competitive assets. A company that can demonstrate ISO-aligned performance, maintain ready access to safe and auto-disable formats, and respond credibly to multi-year program tenders is better positioned to secure demand than one that competes on price alone. The report's dynamics section is built to map these forces to practical consequences for product design, market access, and commercial planning.
What This Means for 2026 Decision-Making
The strategic value of this research lies in its ability to convert market momentum into planning clarity. The forecast pathway to 34.0 million USD by 2032 implies that growth will continue, but it also implies that the composition of that growth will matter as much as the total. Volumes will shift across syringe formats. Demand will migrate across care settings. Regional procurement patterns will diverge as mature markets stabilize and emerging corridors scale. Regulatory expectations will continue to raise the bar for product qualification.
For leadership teams, the report is intended to support several concrete decisions. It can help determine which volume classes and application segments deserve closer commercial focus, which regulatory requirements must be built into product roadmaps, and which geographic markets require additional compliance preparation or distribution investment. It can help procurement leaders benchmark sourcing assumptions against broader market pricing and program-tender behavior. It can help competitive strategists understand where concentration gives incumbents leverage and where specialist innovation may open narrower but higher-value niches.
Most importantly, the report is built to be used. The segmentation logic supports scenario testing. The competitive profiles support benchmarking and partnership evaluation. The regulatory and procurement mapping supports risk prioritization. The forecast structure supports capacity and revenue planning that is grounded in realistic pacing rather than optimistic extrapolation.
Access the Full Intelligence Architecture
This preview is intended to demonstrate the depth and structure of the study, not to exhaust it. The complete Disposable Syringes Market research provides the detailed segmentation frameworks, full competitive profiling, regulatory timelines, procurement-signal tracking, and forecast calculations that decision-makers need to move from awareness to action. If your 2026 planning involves product positioning, sourcing strategy, market entry, or competitive response in the disposable syringes sector, the full report offers the evidence base required to make those choices with confidence.
We invite you to explore the complete research on our platform, where the full segmentation breakdowns, company profiles, developments timeline, and market dynamics analysis are available in their entirety. The macro trajectory is clear; the strategic opportunity lies in understanding exactly where to act within it.
For detailed analysis of this topic, please visit the official page: Disposable Syringes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com