

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
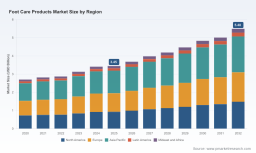
PW Consulting Forecasts Foot Care Market to Hit $5.48 Billion by 2032, Growing at 6.84% CAGR

Navigating the Next Wave: Strategic Intelligence in the Foot Care Products Market (2026–2032)
The global foot care products market stands at a critical inflection point. As consumer awareness of podiatric health rises and regulatory frameworks adapt to emerging clinical needs, the sector is no longer a niche retail category—it is a strategically vital landscape where personal wellness, sports performance, and clinical reimbursement intersect. PW Consulting's latest comprehensive market study maps this transformation across a six-year forecast horizon, equipping category managers, supply chain leaders, and strategic planners with the actionable intelligence required to make confident decisions in a rapidly evolving environment.
A Market Built on Sustained Structural Growth
Drawing on a rigorous historical analysis spanning 2020 through 2025, our research establishes a clear baseline of resilience. The global foot care products market has consistently expanded from approximately $2.7 billion in 2020 to an estimated $3.45 billion in 2025, reflecting both post-pandemic consumer re-engagement and a broadening appreciation for preventive foot health. More importantly, our forward-looking model projects a compound annual growth rate of 6.84% through 2032, with the overall market trajectory positioning it to surpass the $5 billion threshold before the decade concludes.
These figures are not merely retrospective markers. They represent a foundational reality: demand is compounding at a pace that outstrips many adjacent personal care segments. For organizations planning capacity expansions, brand portfolio allocations, or distribution network upgrades, understanding the velocity of this growth is essential. Yet the headline trajectory only tells part of the story. Our full study dissects the underlying drivers—demographic shifts, therapeutic innovation, retail channel migration, and policy-enabled clinical access—that will determine which market participants capture disproportionate share during this expansion phase.
Beyond the Headline: Where the Real Strategic Decisions Live
Scaling revenue requires more than confidence in a positive CAGR. It demands precision in segmentation, go-to-market architecture, and competitive positioning. Our report delivers a structured, decision-oriented breakdown across product types and end-use categories, enabling leadership teams to identify the highest-leverage opportunities within their specific operational context.
The product landscape encompasses established staples such as topical creams and lotions, alongside specialized interventional formats including shoe pads, moisturizing socks, and a growing array of adjacent solutions. Each format carries distinct cost structures, shelf-life considerations, consumer adoption curves, and clinical utility profiles. Likewise, the end-use segmentation reveals how personal and home-care demand compares against the performance-oriented sports and athletes segment, and how the medical and therapeutic category continues to gain structural support from evolving reimbursement pathways. Our analysis isolates the growth mechanics within each of these buckets without relying on superficial slice-and-dice reporting. Instead, we translate segmentation into strategic signal: where volume is concentrating, where margins are being defended, and where new entrants or incumbents are most likely to contest share.
Foot Care Products Market
For executives who need to prioritize capital allocation, the segmentation framework in our study serves as a roadmap for portfolio rebalancing. It identifies which subcategories are consolidating around established consumer habits, which are being reshaped by active-lifestyle purchasing behavior, and which are moving in lockstep with clinical guideline updates. Full segment-level intelligence—including unit economics proxies, demand elasticity observations, and regional appetite indicators—is provided in the complete report, enabling teams to move from high-level trend awareness to specific, defensible action plans.
Competitive Architecture: How the Market Is Being Shaped
The foot care products market remains notably fragmented at the top, with our data indicating that the three largest players account for roughly 22% of aggregate market revenue and the top five for approximately 26%. This concentration profile has important strategic implications. It suggests that no single enterprise currently dictates pricing, channel access, or innovation cadence across the entire category. Instead, competitive advantage is being won through specialization, brand trust, clinical credibility, and regionally attuned distribution strategies.
Our report profiles a representative set of organizations that illustrate how different strategic postures are playing out in the current environment. Aetrex Worldwide, Inc., based in Princeton, New Jersey, continues to demonstrate the value of aligning foot care products with footwear-adjacent engineering and consumer comfort standards, an approach that resonates strongly with performance-oriented and personal-use buyers. PediFix Inc., operating out of Hauppauge, New York, reflects a more therapeutic, solution-oriented positioning that emphasizes accessible over-the-counter interventions for common foot conditions. Alva-Amco Pharmacal Companies, Inc., headquartered in Sterling, Virginia, brings a pharmacological heritage to the category, reinforcing the bridge between everyday wellness products and clinically informed formulation expectations.
Anti Cellulite Care Products Market
Blistex Inc., based in Oak Brook, Illinois, continues to leverage its broader dermatological and personal care reputation to extend consumer trust into foot-specific care formats. Footlogix, headquartered in Sammamish, Washington, exemplifies the specialized, science-forward brand play that has gained traction among consumers and professionals seeking targeted efficacy claims. Further broadening the geographic and clinical lens, Diabetik Foot Care India Private Limited, based in Chennai, Tamil Nadu, illustrates how localized clinical need—particularly around at-risk foot management—is inspiring product strategies that align with both consumer education and medical guidance.
Each of these companies occupies a distinct strategic position within the broader market. Our study examines how their product focus, brand narratives, and channel strategies interact with the structural forces shaping demand. The goal is not to rank competitors, but to illuminate the playbooks that are currently generating momentum, so that your organization can identify analogous opportunities or anticipate competitive counter-moves.
Policy, Reimbursement, and the Clinicalization of Foot Care
One of the most consequential developments in the current market cycle is the gradual clinicalization of categories that were once dominated by general consumer retail. Regulatory and reimbursement evolutions are reshaping how foot care products are positioned, purchased, and valued by end users and care providers alike.
Recent regulatory activity underscores this shift. In May 2026, FDA granted supplement approval for NDA 209089/S-010 for OTC foot care products, a development with direct implications for labeling, claims substantiation, and competitive parity among manufacturers seeking to align their portfolios with recognized pathways. Around the same time, in April 2026, the American Podiatric Medical Association and the New York State Podiatric Medical Association engaged with NGS to address LCA changes allowing reimbursement for at-risk foot care by certified nurses. This policy dialogue reflects a broader movement toward formalizing which clinical professionals may deliver reimbursed foot care services, and under what certification and supervision conditions.
The reimbursement environment has been further clarified by CMS guidance. Updated billing and coding information indicates that the revised LCA for Medicare Part B allows a Registered Nurse holding a CFCN® credential to perform at-risk foot care under direct physician supervision, with proof of certification required upon request. Complementary recognition from WOCNCB confirms that the Foot Care Certification credential is acknowledged for reimbursement of eligible foot care services. Together, these developments create a more navigable pathway for clinical engagement in foot care, which in turn expands the addressable demand for products that complement nurse-administered or physician-supervised care.
On the device and product-handling side, infection-control expectations continue to sharpen. Industry guidance emphasizes that all foot care devices must be intended for human use and reprocessed according to Spaulding classification principles, with single-use emery bands and manufacturer-specified steam sterilization cycles applied where relevant. For manufacturers, formulators, and private-label partners, these standards influence packaging design, product claims, and operational compliance. Simultaneously, the APMA Seal of Acceptance program continues to evaluate footwear, insoles, and equipment for normal foot function and quality standards, reinforcing a trust signal that many consumers and procurement professionals increasingly treat as a baseline consideration.
These dynamics are not peripheral. They affect product architecture, claims strategy, retailer relationships, clinical distribution partnerships, and the long-term positioning of brands that aim to compete across both retail and care-adjacent channels. Our report integrates these developments into a coherent market dynamics framework, helping organizations anticipate where compliance, credibility, and clinical alignment will become decisive competitive factors.
What Decision-Makers Will Find Inside the Full Report
This market study is designed for teams that need to move from macro awareness to execution-ready intelligence. The report is structured to support a range of strategic tasks, including:
- Category and portfolio planning: A detailed segmentation lens that helps identify where to accelerate, where to defend, and where to experiment based on growth momentum and competitive saturation.
- Competitive benchmarking: Company-specific profiles that translate product focus and market behavior into actionable positioning insights, enabling more precise competitive monitoring and response planning.
- Regulatory and reimbursement readiness: An integrated view of recent approvals, policy discussions, certification recognition, and infection-control expectations that shape product claims, clinical adoption, and procurement confidence.
- Distribution and channel strategy: Analysis of how consumer purchasing pathways, retail formats, and care-adjacent access points are influencing product placement, basket economics, and brand visibility.
- Risk and compliance awareness: Practical context on sterilization, reprocessing expectations, and credentialing requirements that matter to manufacturers, brand owners, and clinical-facing partners.
By connecting top-line market sizing with the operational realities of product development, brand positioning, and channel execution, the report serves as a reference point for both near-term planning and longer-term portfolio strategy. It is especially relevant for organizations evaluating expansion into adjacent subcategories, assessing partnerships with clinical or retail intermediaries, or preparing for a market environment in which reimbursement and certification signals increasingly influence purchasing decisions.
Why This Study Matters for 2026 Strategy
The period ahead will reward organizations that can read the market at multiple levels simultaneously. At the macro level, sustained growth through 2032 creates the conditions for profitable expansion. At the segment level, the dispersion of demand across product formats and end-use categories requires disciplined prioritization rather than undifferentiated scaling. At the competitive level, a fragmented concentration profile means that differentiation, credibility, and channel precision can outweigh sheer scale. And at the policy level, regulatory approvals and reimbursement developments are broadening the clinical relevance of foot care products, creating new vectors for demand while also raising the bar for compliance and claims integrity.
In that context, the strategic question is not simply whether the market is growing, but where your organization can most effectively participate in that growth. Our study is built to help leadership teams answer that question with greater clarity and less guesswork. It combines historical rigor, forward-looking modeling, competitive profiling, and policy-aware market dynamics into a single decision-support framework.
To access the full segmentation intelligence, complete company profiles, and the entire forecast series underpinning this analysis, we invite you to explore the complete PW Consulting Foot Care Products Market research. The detailed dataset and executive insights are available through our report portal, where you can retrieve the full market model, download the segmentation breakdown, and align the findings directly with your internal planning cycles.
For detailed analysis of this topic, please visit the official page: Foot Care Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com