

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Healthy Lifestyle
PW Consulting: Endoscopy Ultrasound Market Hits $1,340M in 2025, Forecasts 7.1% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Endoscopy Ultrasound Market 2026–2032
The landscape of advanced gastrointestinal imaging is undergoing a structural transformation. Driven by rising oncology screening volumes, strategic partnerships accelerating imaging clarity, and an increasingly dense competitive field, the endoscopy ultrasound (EUS) sector demands rigorous, forward-looking intelligence. This analysis distills the foundational architecture of our latest Endoscopy Ultrasound Market research, a comprehensive study designed specifically to equip executive teams, product leaders, and strategy officers with actionable decision frameworks for 2026 and the forecasting window through 2032.
Policymakers, investors, and corporate planners navigating this space in 2026 face a dual imperative: capture the momentum of a maturing yet rapidly expanding market while navigating intricate reimbursement gradients, evolving regulatory clearances, and material-driven supply chain considerations. The study at the center of this article is constructed not merely to report historical trajectories, but to translate them into defensible strategic pathways. Several foundational market metrics anchor this intelligence. Tracing performance across the 2020–2025 historical window, the market closed 2020 at approximately 950.0 million USD and climbed through successive annual increments, reaching roughly 1,340.0 million USD by the 2025 base year. Looking ahead into the 2026–2032 forecast period, the trajectory sustains a compound annual growth rate of 7.1 percent. By the end of the window, projected market revenue approaches 2,170.0 million USD, with intermediate milestones mapping a steady expansion through 2026, 2027, and beyond. Revenue figures are presented in millions of USD. These aggregate indicators establish the scale of the opportunity; the study then deconstructs the underlying mechanics that truly drive investment rationale.
Decoding the Structural Pillars of Growth
Understanding why the EUS market expands requires more than top-line tracking. Our research dissects the ecosystem across three interlocking axes: product architecture, clinical application pathways, and geographic distribution of demand. Each axis introduces distinct commercial dynamics, procurement behaviors, and adoption curves that together dictate where margin expansion, market share capture, and capacity investments will materialize.
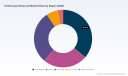
On the product side, the market is segmented across endoscopes, ultrasound processors, ultrasound needles, and ultrasound probes. These categories do not grow in isolation. Processors function as the technological core, dictating image fidelity, workflow integration, and upgrade cycles that influence downstream accessory purchasing. Endoscopic platforms and specialized probes determine diagnostic reach and therapeutic versatility, while needle systems represent a high-frequency consumable layer with direct implications for procedural throughput and cost-per-case economics. The interplay between capital equipment refreshes and recurring consumable demand creates a multi-layered revenue architecture that procurement teams must model carefully when forecasting share and pricing power.
Endoscopy Ultrasound Market
Application segmentation further clarifies where clinical volume concentrates. The market is anchored by two dominant clinical domains: oncology and gastroenterology. Oncology procedures drive substantial volume due to staging requirements, tissue acquisition protocols, and the expanding use of EUS in guiding minimally invasive interventions. Gastroenterology applications maintain steady, high-utilization pathways for diagnostic evaluation, biliary and pancreatic assessments, and therapeutic maneuvers. The study examines how procedural coding structures, outpatient reimbursement patterns, and institutional procurement guidelines shape demand elasticity in each domain, revealing where volume growth translates directly into durable revenue and where reimbursement variability introduces margin uncertainty.
Geographic distribution compounds these dynamics. Demand is not uniformly weighted across regions. The study maps concentration patterns that highlight mature, high-density markets alongside emerging regions exhibiting different adoption velocities, regulatory maturation timelines, and infrastructure readiness. Understanding which regions contribute the largest revenue pools, and which are positioned for accelerated procedural diffusion, is essential for clinical rollout planning, distributor partnerships, and localized pricing strategies.
Competitive Architecture and Tactical Positioning
The EUS marketplace is characterized by a concentrated yet highly competitive supplier ecosystem. Our research quantifies industry concentration, revealing a market where a small cohort of leading firms commands significant share, while a broader tier of specialized manufacturers, component suppliers, and emerging innovators competes for procedural footprint and hospital formulary placement. This concentration profile shapes bargaining dynamics, partnership opportunities, and barriers to entry in distinct ways.
At the forefront of comprehensive EUS portfolios stand organizations such as Olympus Corporation, Boston Scientific Corporation, Medtronic plc, FUJIFILM Holdings Corporation, and Pentax Medical. These players don't merely supply equipment; they engineer integrated diagnostic-therapeutic ecosystems. Olympus has consistently broadened its lineup with processors, echoendoscopes, miniature probes, and needle systems, while also advancing advanced imaging platforms through strategic technology partnerships. Recent activity underscores this momentum: in May 2026, Olympus introduced the Aplio i800 EUS Premium Ultrasound System in the United States via a partnership with Canon, targeting advanced imaging capabilities, and simultaneously showcased an expanded EUS solutions portfolio at Digestive Disease Week 2026. Earlier, in September 2025, FUJIFILM Holdings Corporation launched the Arietta 850 EUS processor alongside 700 Series linear scopes at the American College of Gastroenterology annual meeting, emphasizing enhanced image clarity for diagnostic and interventional workflows.
Worldwide Ultra HD Endoscope Market
Beyond the integrated giants, a specialized layer of players competes intensely around high-frequency consumables and targeted procedural tools. Companies including ConMed Corporation, Cook Medical, Medi-Globe Corporation, and B. Braun deliver EUS endoscopes, needles, stents, and accessories that intersect directly with the procedural cost structure. Needle technology, in particular, carries material and performance implications that ripple through both clinical adoption and procurement economics, with biopsy needles increasingly relying on medical-grade nitinol and multi-layer shear designs to secure consistent tissue acquisition.
Perhaps most strategically interesting is the emergence of innovators targeting workflow accessibility and technology democratization. EndoSound, Inc. exemplifies this approach with its Vision System, designed to transform standard upper GI endoscopes into full EUS-capable platforms. Meanwhile, auxiliary suppliers such as STERIS plc and Nihon Dempa Kogyo Co., Ltd. anchor the ecosystem through endoscope reprocessing and sterilization validation, and ultrasonic component supply, respectively. These enabling players illustrate how the competitive field extends well beyond the instrument manufacturer, encompassing sterilization compliance, component engineering, and clinical enablement services.
The presence of additional platform developers and therapeutic contributors—spanning entities like HUACO Healthcare Technologies, Limaca Medical, Philips, Smith & Nephew, and SonoScape Medical Corp.—further diversifies the landscape. Our study evaluates how this layered player base shapes pricing pressure, innovation cadence, procurement bundling behavior, and regional market entry strategies. It also assesses how certified clinical application specialists drive on-site training and procedural optimization, a factor that increasingly differentiates vendors in a market where adoption velocity hinges on skill transfer as much as hardware performance.
Market Dynamics: Reimbursement, Regulation, and Operational Realities
Strategic decision-making in EUS requires a clear grasp of the operational and regulatory scaffolding that governs commercialization. The study integrates these dynamics not as peripheral context, but as core variables that influence market entry timing, product clearance pathways, and the financial viability of procedural programs.
Reimbursement structures exert a direct influence on institutional adoption. EUS procedures are generally billed under standard outpatient CPT codes, yet Medicare national average payments vary, and coverage nuances differ across payer types and care settings. These reimbursement gradients affect hospital investment calculus, clinical volume projections, and the speed at which new technologies achieve cost neutrality within departmental budgets. The report maps how coding ambiguity and payment variability shape procurement risk and where service bundling, training support, and workflow efficiency arguments become essential to overcome reimbursement friction.
Regulatory pathways remain equally consequential. New EUS devices require FDA 510(k) clearance, a process that recent premarket notifications—such as those associated with Olympus EVIS EUS ENDOSCOPIC ULTRASOUND CENTER EU-ME3 and the EndoSound Vision System—demonstrate continues to gate innovation velocity and commercialization timelines. Clearance timelines, predicate strategy, and post-market compliance expectations are dissected within the report to help companies calibrate R&D investment cycles, regulatory filing sequencing, and market launch pacing. In parallel, infection prevention and device reprocessing have become non-negotiable compliance considerations. EUS equipment must satisfy standard endoscope reprocessing validation protocols overseen by manufacturers including STERIS, making sterilization compatibility and validation documentation integral to product acceptance in tightly regulated clinical environments.
Beyond regulatory and reimbursement mechanics, the report examines how material sourcing and clinical support economics intersect with product strategy. Needle construction materials, processing requirements, and component engineering influence both performance differentiation and supply chain resilience. Simultaneously, the role of on-site application specialists—who deliver training, optimize procedural workflows, and reinforce adoption—emerges as a strategic investment rather than a support function, directly influencing institutional satisfaction and repeat purchasing behavior.
What the Research Delivers for 2026 Decision-Making
This study is engineered as an executive-grade instrument for strategic allocation, competitive positioning, and market timing. It moves beyond descriptive market snapshots to provide an operational playbook for navigating a sector where technological differentiation, reimbursement navigation, and regional adoption patterns jointly determine success. The content is organized to support cross-functional planning across R&D, commercial strategy, finance, and operations.
At a strategic level, the report delivers:
- A validated historical-to-forecast trajectory that establishes baseline scale, growth velocity, and structural inflection points across the 2020–2032 horizon.
- A multidimensional segmentation framework that clarifies how product categories, clinical applications, and geographic markets interact to create differentiation opportunities and concentration risks.
- A competitive landscape assessment that evaluates market concentration, portfolio breadth, component enabling roles, and innovation pipelines across leading and emerging players.
- An integrated market dynamics module covering reimbursement variability, regulatory clearance requirements, reprocessing validation demands, material cost considerations, and clinical enablement economics.
- Actionable interpretive layers designed to help executive teams align product roadmaps, pricing architectures, partnership strategies, and regional entry priorities with observed demand behavior and procedural economics.
The report is particularly intended to support decision-makers who must answer questions that extend far beyond aggregate growth rates: which product categories hold the most defensible expansion potential, how reimbursement and regulatory realities reshape adoption timelines, where competitive intensity is likely to intensify or fragment, and how institutional procurement behavior responds to tool performance, workflow integration, and service support. By mapping these variables within a coherent analytical structure, the research equips leadership teams to construct scenarios, stress-test assumptions, and prioritize resource deployment with greater confidence.
Translating Intelligence into Strategic Action
The EUS market in 2026 presents both maturation and momentum. Established players are deepening portfolio integration and advancing imaging platforms through partnerships and product launches, while specialized manufacturers and emerging innovators continue to pressure differentiation through consumable innovation, procedural accessibility, and workflow enablement. At the same time, reimbursement variability, regulatory clearance requirements, sterilization compliance expectations, and material-driven supply considerations shape the pace at which new technologies scale within clinical institutions. Against this backdrop, aggregate market size and growth trajectories provide necessary context, but only granular segmentation, competitive analysis, and dynamic factor modeling can inform defensible strategy.
Our Endoscopy Ultrasound Market research is built to bridge that gap. It distills historical performance, forecast indicators, segmentation architecture, competitive positioning, and operational dynamics into a unified view that supports capital planning, product portfolio decisions, market entry timing, and partnership evaluation. Organizations seeking precise figures, segmentation splits, regional revenue distribution, and application-level breakdowns will find those detailed dimensions embedded within the full report. The executive architecture previewed here is intended to demonstrate analytical rigor while directing decision-makers toward the complete dataset required for granular execution.
For strategy, finance, and commercial leadership teams preparing 2026 planning cycles, this research provides the structural intelligence necessary to move from market awareness to market execution. The complete study supplies the quantitative resolution, competitive benchmarking, and dynamic factor analysis that translate high-level growth signals into specific investment priorities, pricing strategies, rollout sequencing, and competitive responses. In a market where imaging clarity, procedural efficiency, and compliance readiness increasingly determine commercial outcomes, the difference between reactive positioning and proactive advantage lies in the depth of intelligence behind the decision.
For detailed analysis of this topic, please visit the official page: Endoscopy Ultrasound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Home Appliances Market to Reach $1.495B by 2032, Growing at 6.98% CAGR
By pmarketresearch, 2026-09-15
Strategic Imperatives in a Reshaped Appliance Landscape: Why the 2026 Decision-Maker Needs Granular Intelligence
The global home appliances sector has entered a phase of structural transformation that renders traditional top-down planning inadequate for 2026 and beyond. Between 2020 and 2025, the industry navigated post-pandemic demand normalization, shifting urbanization patterns, and an accelerating wave of product digitization, emerging at a valuation exceeding nine hundred and thirty-eight million USD in our base year. More critically, the forward trajectory through 2032 points toward sustained expansion, with the broader market on pace to approach one trillion four hundred ninety-five million USD over the full forecast horizon. For executives, procurement leaders, and capital allocators, the operative challenge is no longer directional awareness but precise, scenario-ready intelligence. Our newly released Home Appliances Market research study delivers exactly that: a decision-grade framework engineered to translate macro momentum into executable strategy.
This article serves as a professional preview of the full publication. It establishes the analytical rigor, structural depth, and competitive granularity embedded in the report while intentionally reserving the most actionable segmented data for the complete intelligence package. Executives who require regional allocation models, application-specific demand curves, product-tier growth differentials, and firm-level positioning matrices will find those deliverables fully articulated in the source document. The objective here is to demonstrate the methodology, highlight the strategic architecture, and clarify what the study enables once the complete dataset is in hand.
The Macro Backbone: Momentum, Baselines, and the 2026 Inflection Point
Any credible strategic assessment begins with disciplined historical grounding. The sector's performance across the 2020 to 2025 evaluation window reflects a market that has absorbed volatility and re-emerged with clearer structural signals. Post-recovery consumption patterns have stabilized, replacement cycles are recalibrating around both durability expectations and technology upsell potential, and supply-side realignment continues to reshape cost architectures. By our base-year measurement in 2025, total industry revenue stood at approximately nine hundred thirty-eight point five million USD, establishing a robust foundation for the forward outlook.
The projected expansion through the 2026 to 2032 forecast period suggests a compound annual growth rate of 6.98 percent, a trajectory that carries meaningful implications for capacity planning, geographic prioritization, and innovation investment. The 2026 baseline itself approaches nine hundred seventy-nine million USD, confirming that the current operating year represents an inflection point rather than a transitional pause. Decision-makers who rely on fragmented secondary sources or backward-looking vendor narratives risk misjudging the pace and composition of this growth. Our research addresses that exposure by constructing a continuous series across historical and forecast intervals, enabling internal planners to benchmark sensitivity, test reorder-point assumptions, and align product roadmap timing with realistic market absorption curves.
Crucially, the report does not treat the headline trajectory as an end in itself. Instead, it uses the macro series as a scaffolding for layered decomposition. Growth is not uniform across product architectures, usage contexts, or geographic demand pools, and the strategic value of the study lies in its capacity to isolate where momentum concentrates and where headwinds intensify. The full publication unpacks those differentials in detail; what follows here is a structural overview of how the analysis is organized and why that organization matters for 2026 decision-making.
What the Study Delivers: An Operational Blueprint for Commercial and Capital Decisions
The Home Appliances Market research was designed for practitioners who need more than trend commentary. It integrates quantitative modeling, competitive intelligence, and regulatory context into a single analytical environment. The report's architecture reflects the actual workflow of strategic planning teams, from portfolio review and channel strategy to market-entry assessment and risk calibration.
Comprehensive Historical and Forecast Modeling
At its foundation, the study provides a continuous time series that connects the 2020 to 2025 historical record with the 2026 to 2032 forecast horizon. This continuity allows organizations to test demand scenarios against a consistent methodological baseline rather than reconciling disconnected estimates. The modeling framework supports internal forecasting reconciliation, making it possible to compare internal sales projections, capacity plans, and inventory targets against independently validated market trajectories. For capital-intensive planning cycles, that alignment reduces the probability of overcommitting to segments that are structurally decelerating while underallocating to faster-absorbing demand pools.
Multi-Dimensional Segmentation Architecture
The analysis decomposes the market across product configurations, usage contexts, and regional demand environments. Rather than presenting these as isolated tables, the report ties each segmentation axis to demand drivers, adoption constraints, and competitive accessibility. Decision-makers can use this structure to assess where portfolio exposure is concentrated, where substitution risk is emerging, and which segments offer the most defensible growth under varying macroeconomic assumptions. The complete publication contains the full segmentation reconciliation, including the granular splits that inform market-share arithmetic, pricing strategy, and channel allocation. Those details are reserved for the full report so that subscribing organizations can operationalize them without dilution or retrofitting.
Competitive Intelligence and Firm-Level Context
Strategic positioning cannot be inferred from aggregate sizing alone. The study profiles the organizations actively shaping market direction, tracking their product philosophies, geographic footprints, and recent strategic moves. Coverage spans established multinational incumbents and high-velocity manufacturers whose combined activity sets the pace for innovation cycles, pricing expectations, and distribution leverage. The competitive section does not merely catalog corporate summaries; it connects recent product introductions, partnership activity, and manufacturing investments to the broader dynamics that will influence competitive accessibility in 2026 and beyond.
Regulatory and Risk Contextualization
Market outcomes are increasingly mediated by policy mechanics and safety governance. The report embeds current regulatory developments into the strategic discussion so that planning teams can evaluate exposure before it becomes a financial event. Recent policy actions around trade and materials costs have introduced meaningful uncertainty into appliance production economics and downstream pricing. In April 2026, strengthened Section 232 tariffs on steel and aluminum imports expanded derivative coverage to include certain non-electric domestic cooking appliances, stoves, ranges, and washing machines, with duty structures reaching as high as fifty percent on full value or twenty-five percent on derivative content. That adjustment builds on the Department of Commerce's earlier inclusions process from April 2025, which had already broadened the program to additional derivative articles such as portable non-electric domestic cooking appliances and plate warmers. For manufacturers, importers, and channel operators, these shifts alter landed-cost calculations, sourcing flexibility, and competitive dynamics between domestically produced and imported lines.
Treatment is also given to product safety governance, which directly affects brand risk, recall exposure, and consumer trust. As of June 2026, the Consumer Product Safety Commission issued warnings tied to recalls of Vornado Air SRTH Small Room Tower Heaters due to fire hazard concerns, alongside multiple steam cleaners and hair dryers flagged for electrocution or burn risks. In parallel, USITC analysis has examined how Section 232 steel and aluminum tariffs may affect household appliance production, trade volumes, and pricing through reduced import volumes and increased domestic costs. The study integrates these threads into its dynamics assessment so that organizations can weigh compliance, sourcing, and product-safety strategy as part of the same planning environment.
Competitor Momentum and the 2026 Strategic Chessboard
The competitive landscape is defined by organizations that are simultaneously defending mature positions and pursuing targeted expansion through product innovation, geographic partnerships, and manufacturing investment. The report's competitor module tracks these moves as strategic signals rather than isolated press events, enabling readers to interpret how individual actions reshape addressable opportunity and competitive pressure.
Among the firms profiled are Whirlpool Corporation, headquartered in Benton Charter Township, Michigan, with a portfolio spanning major home appliances under recognized brands such as Whirlpool, KitchenAid, and Maytag. AB Electrolux, based in Stockholm, produces major home appliances including refrigerators, washing machines, dishwashers, and ovens. Haier Smart Home Co., Ltd., operating from Qingdao in Shandong, China, manufactures a wide range of major and small home appliances, including refrigerators, washing machines, and air conditioners. Midea Group, headquartered in Foshan, Guangdong, produces major home appliances including refrigerators, washing machines, and kitchen appliances. BSH Home Appliances Corporation, based in Irvine, California, offers premium major home appliances under the Bosch, Siemens, and Thermador brands, covering refrigerators, ovens, and laundry products. LG Electronics Inc., from Seoul, South Korea, develops and manufactures major home appliances including refrigerators, washing machines, and air conditioners. Samsung Electronics Co., Ltd., based in Suwon, South Korea, manufactures major home appliances such as refrigerators, washing machines, and dishwashers. Panasonic Corporation of North America, located in Secaucus, New Jersey, provides major home appliances including refrigerators, washing machines, and kitchen appliances. Gree Electric Appliances Inc., headquartered in Zhuhai, Guangdong, produces major home appliances like air conditioners, refrigerators, and washing machines.
Recent activity among these players illustrates the operating tempo the market now demands. In January 2026, BSH Home Appliances Corporation launched Bosch Cook AI for personalized kitchen guidance within the Home Connect app and introduced new Bosch Unlimited 9 and 10 Premium Cordless Stick Vacuums with MicroClean technology for North America. In March 2026, GE Appliances launched the FirstBuild Sourdough Sidekick collaboration with King Arthur Baking Company, now available nationwide for improved sourdough baking. That same company had previously announced, in August 2025, more than three billion USD in investment over five years to expand U.S. manufacturing, including new models of two-ton Vertical Zoneline air conditioners and demand-response electric water heaters. In April 2026, Electrolux Group formed a strategic partnership with Midea Group to accelerate growth and innovation in North America. Each move signals a different facet of competitive adaptation: connected-product differentiation, specialized use-case productization, domestic capacity expansion, and cross-border partnership for regional acceleration.
The report connects these developments to the market's structural realities, including the concentration dynamics observed across the industry. Current concentration metrics indicate that the top three firms account for approximately 48.5 percent of market share, while the top five reach roughly 62.3 percent. That degree of concentration has direct implications for pricing power, channel negotiation, and the feasibility of disruptive entry. Organizations evaluating partnership opportunities, acquisition targets, or defensive positioning can use the full study's competitive framework to assess where structural leverage resides and where smaller players can still carve out differentiated roles through niche specialization, service models, or regional focus.
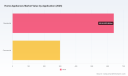
Worldwide Domestic Appliances Market
Why This Research Matters More in 2026 Than in Prior Cycles
The intersection of sustained demand growth, product-category evolution, competitive intensification, and policy-driven cost pressure makes 2026 a year in which decision quality is especially consequential. Forecast accuracy, portfolio alignment, and risk anticipation now depend on intelligence that is both broad enough to capture systemic momentum and granular enough to support segment-level action. Generalized market narratives cannot provide that. They tend to obscure the compositional differences that determine whether a strategy scales or stalls.
The Home Appliances Market study was built to close that gap. It gives executives a unified view of where the market has been, where it is headed, and how competitive and regulatory forces are reshaping the options available to firms operating within it. The full publication contains the complete segmentation breakdown, the detailed forecast intervals, and the comprehensive competitive mappings that planning teams need to build budgets, set targets, and stress-test assumptions. Those assets are presented in a format intended for direct use in internal reviews, investment committees, and strategic planning cycles.
Home Appliances Market
For leaders who must act on the current market environment rather than react to it, the value of the report lies in its readiness for application. It is not a retrospective commentary but a forward-oriented decision tool. The macro trajectory establishes confidence in the scale of the opportunity; the segmentation architecture reveals where that opportunity is concentrated; the competitive intelligence shows who is positioning to capture it; and the regulatory and safety context highlights where risk must be actively managed. Together, these layers form the basis for informed 2026 strategy.
Next Step: Accessing the Complete Intelligence Package
This preview demonstrates the analytical depth and strategic relevance of the Home Appliances Market research, but the most actionable content resides in the full report. Detailed regional demand environments, application-specific deployment patterns, product-tier growth differentials, segmentation reconciliations, and complete competitive profiles are available in the complete publication. Organizations that require the precise figures and structural breakdowns needed for allocation modeling, market-entry evaluation, and competitive benchmarking are encouraged to access the source webpage and retrieve the complete dataset. For 2026 planning, the difference between directional awareness and decision-ready intelligence is not abstract; it is the difference between a strategy that can withstand scrutiny and one that cannot. The full report is designed to provide exactly that standard.
For detailed analysis of this topic, please visit the official page: Home Appliances Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Disposable Gloves Market to Hit $31.69B in 2025, Growing at 8.7% CAGR to 2032
By pmarketresearch, 2026-09-15
Toward a Resilient Supply Chain: Strategic Insights from the 2026 Disposable Gloves Market Research
The global disposable gloves market has transitioned from a crisis-driven demand surge to a mature, structurally complex growth environment. As enterprises recalibrate procurement strategies, capacity plans, and sustainability commitments for the 2026–2032 horizon, the need for granular, forward-looking intelligence has never been more acute. Our latest market research publication dissects the competitive, regulatory, and operational forces shaping this essential category of personal protective equipment and industrial consumables.
Built on a rigorous historical reconstruction spanning 2020 through 2025 and a forward-modeled forecast extending to 2032, this study translates high-level market trajectories into actionable decision frameworks. The research is designed for procurement leaders, supply chain architects, product strategists, and corporate development teams seeking to navigate an increasingly polarized landscape—one defined by persistent capacity overhang, divergent regional cost structures, accelerating sustainability mandates, and intensifying product differentiation.
The Macro Trajectory: Growth Punctuated by Structural Tension
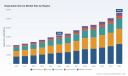
The surface narrative of the disposable gloves market is deceptively straightforward. From a 2020 baseline that reflected the early stages of pandemic-era procurement shocks, the market has expanded through a sustained upward arc, reaching a 2025 valuation of approximately 31.7 billion USD. The forecast period projects continued expansion, with the market expected to surpass 33.4 billion USD in 2026 and climb steadily toward 56.8 billion USD by 2032.
The implied compound annual growth rate of 8.7 percent positions disposable gloves above many adjacent industrial and healthcare consumables categories. Yet this headline figure belies the strategic complexity underneath. Growth is no longer a uniform tide lifting all manufacturers and end-users. Instead, it is being reshaped by a combination of oversupply dynamics, regional pricing asymmetries, material-specific substitution patterns, and compliance-driven procurement requirements that vary significantly across healthcare, industrial, and food service verticals.
Capacity Versus Demand: The Persistent Oversupply Equation
One of the most consequential structural themes for 2026 decision-making is the widening gap between global production capacity and realized demand. Industry analysis indicates that cumulative glove production capacity is on a trajectory to exceed 500 billion pieces annually within the next two years, while demand is estimated at roughly 400 billion pieces. This imbalance has direct implications for pricing strategies, inventory management, contract negotiations, and supplier diversification.
For procurement and sourcing teams, oversupply is not simply a short-term cost tailwind. It creates a bifurcated negotiation environment in which volume discounts, long-term supply agreements, and service-level commitments can be restructured—but only if organizations possess the operational readiness and supplier intelligence to act. For manufacturers, the same dynamic raises urgent questions about utilization rates, product mix optimization, and the economics of incremental capacity investment. The research unpacks how leading players are responding to this reality through material specialization, regionalized supply chains, and higher-value product architectures.
Regional and Cost Asymmetries in a Globalized Market
The disposable gloves market remains highly globalized, with production concentrated across a limited set of manufacturing hubs and demand distributed across diverse regulatory and clinical environments. This geographic tension is especially pronounced in the United States, where domestically produced, FDA-registered medical gloves carry distinct cost structures compared with imported alternatives. Labor cost differentials are substantial: foreign manufacturers in established production centers can offer disposable gloves at average prices as low as 0.02 USD per glove, while U.S.-based producers face significantly higher wage expectations.
Recent trade policy developments further complicate procurement planning. For example, U.S. Customs and Border Protection modified its Withhold Release Order in late 2024, lifting detention measures on certain disposable gloves produced in Malaysia provided that companies comply with other applicable trade laws. These regulatory adjustments, combined with the operational realities of validated production facilities, fair-wage employment commitments, and domestic manufacturing incentives, create a nuanced sourcing landscape. Organizations that rely on simplistic lowest-price heuristics risk exposure to compliance volatility, quality inconsistency, and supply continuity disruptions.
What the Research Delivers: A Practical Toolkit for Strategic Action
This study is engineered to move beyond macro-level commentary and provide decision-ready structure across the core dimensions that matter most to enterprise stakeholders.
Comprehensive Market Sizing and Forecast Architecture
The report maps historical performance across 2020–2025 and extends forward through 2032, using a disciplined methodology that captures the interplay between volume expansion, price normalization, material substitution, and end-user demand evolution. The forecast architecture is designed to support scenario planning, enabling teams to assess how shifts in regulatory requirements, procurement policy, or capacity utilization could alter growth paths in specific market environments.
Segmentation by Type, Application, and Region
The study examines the market through multiple lenses, including material types such as nitrile, natural rubber latex, polyvinyl chloride, and other variants, as well as application contexts spanning healthcare, industrial operations, food service, and adjacent use cases. Regional analysis provides a structured view of how demand and supply characteristics differ across major markets, helping organizations benchmark exposure, anticipate localization requirements, and identify growth pockets aligned with their strategic footprint.
Competitive Landscape and Company Profiles
A central contribution of the research is its detailed assessment of the competitive field. Rather than treating the market as a homogeneous set of producers and distributors, the study profiles leading organizations based on their strategic positioning, capacity orientation, product specialization, certifications, and recent operational developments. This enables readers to understand not just who competes in the market, but how competitive advantage is being constructed and defended.
Disposable Medical Gloves Market
Regulatory, Compliance, and Sustainability Dynamics
The research integrates regulatory and operational developments that directly affect sourcing, product selection, and supply continuity. This includes analysis of FDA-registered facility requirements, medical glove regulation, trade enforcement actions, reimbursement-linked procurement behaviors, and evolving sustainability expectations. The report also examines how traceability, material circularity, and chemical-exposure reduction are becoming increasingly relevant to procurement criteria in healthcare and industrial settings.
Recent Developments and Strategic Signal Extraction
To keep the analysis anchored in present-day momentum, the study incorporates recent corporate actions and industry events that signal where the market is heading. These include capacity expansions, product launches, sustainability recognitions, traceability platform expansions, and trade show participation that reflects regional market engagement. The emphasis is not on isolated news flow but on extracting durable strategic signals: where capacity is being committed, what product features are being prioritized, and how manufacturers are positioning for the next phase of differentiation.
Competitive Landscape: Strategic Positioning in a Concentrated Market
Market concentration remains a defining feature of the disposable gloves sector. The research notes a CR3 of approximately 40 percent and a CR5 of roughly 55 percent, indicating that a relatively small group of players exerts meaningful influence over pricing dynamics, capacity allocation, and category standards. At the same time, the presence of regionally anchored manufacturers, specialized material exporters, distributor-led healthcare providers, and sustainability-focused innovators ensures that competition plays out across multiple dimensions rather than through scale alone.
Disposable Gloves Market
Scale Leaders and Non-Latex Specialization
INTCO Medical has reinforced its position as a major global non-latex glove manufacturer, with annualized production capacity reaching 103 billion pieces by the end of 2025. Its recent 2025 annual report highlighted continued revenue growth and an expansion trajectory that underscores the strategic importance of nitrile and vinyl disposable gloves across healthcare, food safety, and industrial protection. For customers and competitors alike, INTCO exemplifies the scale-plus-material-specialization model, where volume capability is paired with a deliberate non-latex focus that aligns with broader industry substitution trends.
U.S. Manufacturing, Compliance Infrastructure, and Domestic Sourcing
Nephron Nitrile LLC operates a large U.S. production facility supplying powder-free nitrile and biodegradable polyurethane disposable gloves for medical, laboratory, industrial, food handling, and janitorial applications, with FDA registration and ISO-aligned practices. Its operating model illustrates a distinct competitive logic: domestic manufacturing capability, regulated medical glove compliance, and U.S.-based workforce deployment, all of which carry different cost and risk profiles compared with import-dependent sourcing. The study examines how this positioning intersects with procurement preferences for supply continuity, regulatory alignment, and domestic content considerations.
Established Global Players and Material Innovation
Ansell remains a leading provider of disposable nitrile and other material gloves, with advanced certifications and recent innovation activity in chemical-resistant and sustainable product options. In early 2026, Ansell launched the TouchNTuff 93-800 disposable glove, which offers up to 15 minutes of resistance to acetone and aggressive chemicals, and received the 2026 SEAL Business Sustainability Award for sustainable product innovation in the disposable gloves category. This dual focus—performance differentiation and sustainability recognition—reflects a broader competitive trend in which material performance and environmental positioning increasingly reinforce each other.
Malaysian Manufacturing Footprints and Compliance Emphases
Top Glove Corporation Bhd, Hartalega Holdings Berhad, and Kossan Rubber Industries Bhd each represent substantial manufacturing capacity and export-oriented participation in the global market. Their profiles highlight different strategic emphases within a shared regional base: strong compliance documentation and trade show engagement, emphasis on quality and global supply, and focus on non-sterile and medical disposable glove quality standards for export markets. The research situates these players within the wider context of Malaysian manufacturing’s role in global glove supply and the regulatory and pricing dynamics that shape their competitive environment.
Additional International Players and Channel-Focused Providers
The competitive set also includes Semperit AG Holding, which emphasizes innovation in nitrile and other disposable gloves for medical and industrial applications; B. Braun Melsungen AG, which focuses on healthcare-oriented disposable gloves as clinical and surgical consumables; and U.S.-based channel participants such as Medline Industries, Inc. and CARDINAL HEALTH, INC., which supply medical disposable gloves to healthcare institutions and hospitals and clinics. Together, these organizations demonstrate how the market is contested not only at the level of production capacity but also through distribution reach, clinical integration, and application-specific service models.
Industry Dynamics: Regulatory Shifts, Labor Economics, and Innovation Signals
The 2026 market environment is shaped by several overlapping forces that go beyond traditional supply-and-demand analysis. Regulatory developments continue to influence what can be imported, how medical gloves are validated, and which production facilities are eligible for certain procurement channels. At the same time, labor cost differentials and domestic manufacturing incentives introduce persistent tension into price formation and sourcing strategy.
Innovation activity provides another important read on market direction. Product launches are increasingly oriented toward chemical resistance, reduced chemical exposure, accelerator-free formulations, and sustainable material profiles. Traceability expansion is also gaining traction, with platforms extending to global latex and nitrile disposable gloves to advance circular materials and supply chain transparency. These developments matter because they signal how manufacturers are preparing for more demanding procurement specifications and more scrutinized supply chains.
A further dynamic is the growing relevance of sustainability as a procurement differentiator rather than a peripheral concern. Awards, certifications, and product-level innovation suggest that disposable gloves are increasingly being evaluated through a lens that combines occupational safety, chemical exposure management, and environmental performance. For enterprises, this raises practical questions about specification setting, supplier qualification, and the cost implications of shifting toward higher-differentiation gloves.
Strategic Implications for 2026 Decision-Makers
The disposable gloves market in 2026 is not simply larger than it was; it is more strategically layered. Growth remains robust at the aggregate level, but the value lies in understanding where growth is durable, where pricing power is eroding, and where competitive advantage is being rebuilt through compliance, material science, and supply chain transparency.
For procurement organizations, the most immediate implication is the need to move beyond single-threshold price comparisons. Oversupply can create attractive short-term pricing, but it also rewards buyers who have the internal capability to evaluate supplier reliability, regulatory status, material differentiation, and logistics resilience in an integrated way. For manufacturers and investors, the imperative is to clarify whether capacity additions are directed at commodity volume or at differentiated, higher-specification product segments with stronger margin defensibility.
For corporate strategy and market entry teams, the concentration structure of the market and the divergence between regional cost bases create both partnership opportunities and competitive risks. The presence of large-scale non-latex producers, U.S.-based regulated manufacturers, internationally certified exporters, and channel-oriented healthcare distributors means that market access strategies must be tailored to product category, end-user requirements, and regulatory context rather than treated as uniform global plays.
Why the Full Report Matters Now
This article offers a directional overview, but the full report is where the decision-grade detail lives. It provides the structured segmentation, company-level profiling, regulatory context, and forecast architecture needed to convert broad market awareness into concrete sourcing, investment, and product strategy decisions. The study is designed to support scenario-based planning across multiple what-if environments, from continued capacity overhang to shifting compliance requirements and accelerating sustainability-driven specification changes.
For organizations preparing for the 2026–2032 cycle, the strategic question is not whether disposable gloves remain essential—they clearly do—but how to position within a market where scale, compliance, material innovation, and transparency are increasingly inseparable from commercial performance.
To access the complete analysis, detailed segmentation discussion, competitive profiles, and forward-looking scenarios, visit the full Disposable Gloves Market research page from PW Consulting.
For detailed analysis of this topic, please visit the official page: Disposable Gloves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Insect Feed Market to Reach $425.8M by 2032 at 16.4% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence in the Insect Feed Market: Navigating the 2026 Outlook with PW Consulting
Executive Summary: A Market at an Inflection Point
The global insect feed market stands at a critical juncture where sustainability mandates, regulatory liberalization, and scaling production capacity converge. Drawing on PW Consulting's latest market research, this analysis provides strategic decision-makers with a structured view of the market's trajectory from the base year of 2025 through the forecast period extending to 2032. The report is designed not as a static data repository but as a decision-making toolkit for executives navigating capital allocation, supply chain restructuring, and competitive positioning in an industry expanding at a compound annual growth rate of 16.4 percent. With historical revenues measured in USD Million across the 2020 to 2025 window and a clear projection horizon, the research bridges retrospective performance with forward-looking scenario planning. This article previews the strategic architecture of the full report, highlighting how the intelligence contained within supports precise, evidence-based choices for 2026 and beyond.
Market Trajectory and Macro Drivers: The Numbers Behind the Momentum
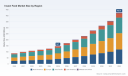
Historical performance reveals a market that has consistently outpaced conventional agricultural commodity growth. From a baseline valuation of approximately 88.5 in 2020, revenues climbed steadily through subsequent years, reaching 100.37 in 2021, 109.35 in 2022, 118.4 in 2023, and 126.68 in 2024. The base year 2025 closed at 147.0, setting the stage for a pronounced acceleration entering the forecast window. According to the full forecast, the market is projected to reach 172.94 in 2026, followed by 201.36 in 2027, 231.88 in 2028, 277.86 in 2029, 317.06 in 2030, 356.88 in 2031, and ultimately 425.8 by 2032. These figures reflect a double-digit CAGR of 16.4 percent that underscores both organic demand expansion and the compounding effect of capacity additions across key geographies.
Several macro forces are reinforcing this trajectory. Regulatory evolution is unlocking previously constrained feed categories. EU Regulation 767/2009 has long permitted insect proteins in aquaculture feed, and subsequent EU Official Journal approvals have extended commercial viability to pig and poultry applications, with inclusion limits reaching up to 20 percent in certain formulations. In parallel, the US FDA has completed GRAS determinations for insect proteins in select animal categories, and black soldier fly approvals for poultry and pet food have expanded during 2024 and 2025. These regulatory milestones remove friction from market entry and create a more predictable compliance environment for producers and feed formulators alike.
Cost dynamics further favor insect-based inputs. Production systems rely on upcycled organic waste substrates, including food processing byproducts, which can reduce material costs by up to 50 percent compared to conventional protein sources. This structural advantage, combined with life cycle assessments showing reductions in land and water use by 40 to 98 percent and lower CO2 emissions versus soy or fishmeal alternatives, strengthens the economic and sustainability case for adoption. As feed manufacturers and vertically integrated producers evaluate total cost of ownership, insect proteins are increasingly positioned as a resilient, low-impact feedstock rather than a niche supplement.
What the Report Delivers: Operational Intelligence for Corporate Strategy
The Insect Feed Market report from PW Consulting is structured to move beyond headline figures and equip stakeholders with actionable intelligence across multiple dimensions of the value chain. The analysis is built around a comprehensive segmentation framework that examines the market by region, by type, and by application, enabling users to isolate the segments most relevant to their operational footprint and growth ambitions. Rather than presenting generic aggregates, the report maps how each segment contributes to overall market momentum and where performance dispersion signals opportunity or risk.
At the operational level, the report details the technical and commercial parameters that shape competitiveness in this space. It examines how different insect species are positioned across feed categories, including aquaculture, poultry nutrition, swine nutrition, and pet food, and how production economics, substrate availability, and processing pathways influence margin structures. The research also tracks the interplay between historical performance and forecast assumptions, providing transparency into the drivers behind each projection interval. This allows strategy teams to stress-test their own forecasts, identify sensitivity points, and align internal planning with industry trajectory.
Beyond segmentation, the report incorporates a disciplined competitive analysis that maps the landscape of established and emerging players. It evaluates how firms are differentiating through biology, process engineering, geographic footprint, and commercial partnerships. Recent developments are contextualized within broader strategic patterns rather than treated as isolated events. The analysis is designed to help executives benchmark their position, anticipate competitive moves, and identify white spaces where first-mover advantage may still be attainable. All quantitative detail, including precise regional and application-level breaks and company-specific benchmarks, is reserved for the full report, ensuring that subscribers gain the granularity necessary for board-level and investment-grade decisions.
Competitive Landscape: Consolidating Players and Strategic Moves
The industry's competitive architecture reflects a mix of regional specialists, technology-driven biostartups, and firms pursuing scale through facility expansion and partnership strategies. The research profiles a core set of companies whose activities illustrate the strategic diversity shaping the market. EnviroFlight, headquartered in the United States, produces all-natural, locally sourced black soldier fly larvae feed ingredients for animal feed, pet food, and plants, with growing and processing operations based in the USA. Innovafeed, based in France, operates as a biotechnology company and leading insect producer for animal and plant nutrition, leveraging proprietary breakthrough technology for insect rearing. Protix, headquartered in the Netherlands, is recognized as a global leader in high-quality, low-impact insect solutions for feed and farming, with a focus on black soldier fly larvae across animal feed, pet food, aquaculture, and plant care. Entobel, a Singapore-based biotech company with operations in Vietnam since 2015, produces functional insect-based ingredients for animal feed and health.
Insect Feed Market
Additional profiles deepen the competitive picture. NextProtein, also based in France, produces insect-based protein for animal feed stocks by processing black soldier fly into dry protein powder, lipids, and fertilizer. Hexafly, from Ireland, combines nature and technology to bioconvert food waste into sustainably produced high-quality insect-based protein, oil, and fertilizer for animal feed. Beta Hatch, in the United States, industrializes insect agriculture within a regenerative food system, producing protein for plants and animals in a zero-waste system using mealworms. Nutrition Technologies, headquartered in Singapore, produces sustainable insect proteins, oils, and organic fertilizer for aquaculture, agriculture, and animal feed using black soldier fly. Together, these firms represent the spectrum of operational models currently driving market expansion.
Recent corporate actions reveal a market in which strategic positioning is being reinforced through tangible milestones. Innovafeed opened the North American Insect Innovation Center in Decatur, Illinois, as its first US facility for insect protein production, signaling a deliberate push into the North American market. Entobel became a Certified B Corp, aligning its operational model with formal sustainability credentials that increasingly matter to downstream customers and investors. Protix signed a multi-year supply agreement with Skretting for BSF meal in salmon feed formulations, illustrating how capacity and commercial partnerships are being structured to secure demand in high-value aquaculture channels. Nutrition Technologies rebranded as Sentara Group following expansion in insect protein production, reflecting a strategic recalibration as firms scale beyond single-product identities. For decision-makers, these developments are not merely news items; they are signals of where capital, technology, and customer relationships are concentrating.
Concentration, Regulation, and Cost Architecture: The Structural Underpinnings
A clear view of market structure is essential for assessing both opportunity and risk. Industry data indicate a moderately concentrated landscape, with the top three firms accounting for 32.5 percent of market share and the top five firms capturing 41.8 percent. This concentration profile suggests that while scale players have meaningful influence, there remains substantial room for regional specialists, niche innovators, and new entrants that can differentiate through biology, substrate economics, or vertical integration. For corporate strategy teams, this balance of concentration and fragmentation informs questions about partnership strategy, acquisition targets, and barrier-to-entry assessment in specific geographies or feed categories.
Regulatory and cost architectures are equally central to long-term planning. On the regulatory side, EU frameworks have progressively permitted insect proteins in aquaculture and, more recently, approved farmed insect proteins for pig and poultry feed with inclusion limits of up to 20 percent in certain formulations. In the United States, FDA GRAS determinations and expanding black soldier fly approvals for poultry and pet food during 2024 and 2025 have reduced uncertainty for market participants seeking to serve multiple animal nutrition channels. These developments collectively widen the addressable application base while creating a more uniform compliance foundation for production and reformulation.
On the cost side, the reliance on upcycled organic waste substrates provides a structural advantage that is difficult for conventional protein sources to replicate at comparable scale. By converting food processing byproducts and related organic streams into high-value feed ingredients, insect production can lower input costs while simultaneously addressing waste management and resource efficiency objectives. This dual benefit strengthens the value proposition for feed manufacturers, integrated agribusinesses, and sustainability-focused buyers. The report examines these dynamics in depth, connecting substrate economics, processing intensity, and end-market pricing to help executives identify where margin resilience is likely to be strongest across the forecast horizon.
Why This Report Matters for 2026 Decision-Making
For organizations making capital, procurement, and portfolio decisions in 2026, the market's pace of change leaves little room for lagging intelligence. The forecast period from 2026 through 2032 is characterized by sustained growth, regulatory opening, and increasing competition among producers with varying degrees of scale, geography, and technological differentiation. In this environment, strategic advantage depends on the ability to interpret macro trends through the lens of segment-specific dynamics, competitive moves, and operational feasibility. The PW Consulting Insect Feed Market report is designed to deliver exactly that interpretive layer.
Decision-makers will find value in the report's structured treatment of where growth is concentrating, which application categories are expanding most rapidly, and how regional markets compare in terms of demand intensity and competitive activity. The analysis also supports scenario thinking by linking historical performance to forecast assumptions, enabling teams to assess the implications of different growth paths, substrate availability scenarios, and regulatory developments. For investors and executives evaluating market entry, expansion, or partnership opportunities, the report provides the evidentiary foundation needed to prioritize initiatives and allocate resources with confidence.
Aqua Feed Market
Conclusion: From Insight to Action
The insect feed market is no longer an emerging curiosity; it is a scaling industry with clearly identifiable growth vectors, an evolving regulatory landscape, and a competitive field that rewards both biological innovation and operational discipline. PW Consulting's latest market research synthesizes the historical record, forecast trajectory, segmentation detail, and competitive intelligence into a single, decision-ready framework. The 16.4 percent CAGR and the progression from 147.0 in the base year 2025 toward 425.8 by 2032 are not just headline indicators; they are the starting point for a deeper conversation about where value will be created and how to position for it. The full report unpacks the segment-level breakdowns, regional comparisons, application-specific dynamics, and company-level analysis that leaders need to convert strategic intent into executed plans. For those responsible for shaping 2026 decisions and beyond, the complete intelligence is available through the source page, where the detailed dataset and proprietary analysis can be accessed in full.
For detailed analysis of this topic, please visit the official page: Insect Feed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Chlorogenic Acid Market Hits $215M in 2025, Projects 5.69% CAGR to 2032
By pmarketresearch, 2026-09-15
Chlorogenic Acid Market 2026–2032: Strategic Intelligence for Formulation, Procurement, and Competitive Positioning
Why This Study Matters in the 2026 Decision Cycle
The chlorogenic acid market enters the 2026–2032 forecast window at a structural inflection point. After a decade of steady value accumulation, total market revenue reached an estimated USD 215.0 Million in 2025, extending a clear upward trajectory from USD 163.06 Million in 2020. The forward view projects a compound annual growth rate of 5.69 percent, translating the base-year position into an anticipated USD 226.87 Million in 2026 and a long-term valuation pathway that approaches USD 316.72 Million by 2032. These headline figures do more than chart volume; they signal a market that has graduated from niche botanical ingredient to a strategically contested category across nutraceuticals, functional beverages, cosmetics, and pharmaceuticals. For senior teams calibrating sourcing commitments, formulation roadmaps, or go-to-market timing, the 2026 environment demands a refined reading of supply-side leverage, regulatory direction, and competitive clustering—precisely the intelligence architecture built into this report.
A strategic reading of this growth curve must also account for concentration dynamics. The category is shaped by a moderately consolidated supplier base, where the top three players command an estimated 52.5 percent of revenue and the top five reach 60.0 percent. That concentration pattern matters because it compresses negotiation windows, amplifies the impact of capacity moves by leading firms, and determines which buyers can secure priority allocation during periods of raw-material stress. The full study unpacks how these concentration bands interact with regional sourcing patterns, type-level supply positioning, and application-level demand pull, but the core message for 2026 planners is straightforward: advantage in this market increasingly flows from the ability to map supplier leverage, not simply to track category growth.
Structural Forces Shaping the 2026–2032 Trajectory
Several converging dynamics are re-grading the risk-return profile of chlorogenic acid sourcing and product development. On the raw-material side, the category remains structurally tethered to global coffee and botanical supply chains. In 2024, global coffee production exceeded 11 million tons, with roughly 8 million tons traded internationally and Brazil and Vietnam accounting for nearly half of output. That concentration creates persistent exposure to weather variability, logistics friction, and regional policy shifts—variables that cascade directly into chlorogenic acid cost structures and availability. At the same time, the botanical component of the value chain extends beyond coffee beans into honeysuckle and eucommia-based pathways, which broadens the category’s raw-material mosaic but also introduces additional quality and traceability considerations.
Regulatory and trade signals add a second layer of strategic complexity. In specific food products such as coffee substitutes, the European Commission has implemented regulation setting chlorogenic acid limits below 100 mg/L, placing formulation ceilings on certain applications and nudging innovation toward compliant concentration strategies. In contrast, the FDA has recorded chlorogenic acid as a dietary substance with no specific quantity restrictions identified in its latest database, sustaining a comparatively permissive environment for dietary supplement and functional food development in the United States. Layered onto that divergence is a trade environment that continues to shift: in 2026, green coffee tariffs in the United States are being rolled back following reciprocal tariff adjustments, influencing import expenditures and altering the cost calculus for key producing regions. These are not peripheral details; they are the kinds of boundary conditions that determine whether a 2026 launch plan scales smoothly or encounters compliance and cost friction downstream.
Chlorogenic Acid Market
Where Demand Is Concentrating: Applications, Types, and Regional Pull
The demand architecture of the chlorogenic acid category is diversifying in ways that reward formulation teams willing to look beyond single-use assumptions. Nutraceutical applications continue to anchor a substantial share of value, reflecting sustained interest in metabolic health, antioxidant positioning, and functional wellness portfolios. Food and beverage applications represent a robust second engine, driven by the pursuit of clean-label functionality and the integration of bioactive ingredients into everyday consumption occasions. Cosmetics and personal care contribute a meaningful demand layer as well, leveraging chlorogenic acid’s relevance to skin-care efficacy narratives and premium botanical positioning. Pharmaceutical applications, while smaller in relative scale, carry outsized strategic importance because they demand higher purity standards, clinical-grade documentation, and API-grade consistency.
Ferulic Acid Market
On the supply composition side, green coffee beans remain the dominant type-level source for chlorogenic acid extraction, reinforcing the category’s continued dependence on coffee-sector dynamics. Honeysuckle and eucommia-based pathways further diversify the type landscape, enabling brand owners and ingredient suppliers to differentiate on botanical origin, extraction profile, and compliance story. Regionally, the market’s footprint is distributed across a broad set of demand centers rather than consolidated in a single geography, which means that procurement strategies must account for differing logistics costs, regulatory expectations, and supplier proximity advantages. The study provides a detailed map of how these type- and region-level structures interact with application-specific buying behavior, including where formulation needs are tilting toward standardized extracts, where cosmetic-grade consistency is becoming a gating requirement, and where pharmaceutical-adjacent documentation is reshaping supplier qualification.
Competitive Landscape: Concentration, Capability, and Recent Moves
The competitive field in chlorogenic acid is defined by a blend of global botanical extract specialists, science-backed API-oriented manufacturers, and high-volume producers with expanding international reach. Naturex, operating under Givaudan and headquartered in Avignon, France, continues to emphasize standardized green coffee bean extracts rich in chlorogenic acid for nutraceutical, functional beverage, and cosmetic applications, with a stated emphasis on traceability and quality compliance. Its recent operational moves illustrate how leading players are trying to harden supply resilience while simultaneously opening new formulation doors. In March 2024, Naturex expanded its Ecuador and Vietnam raw-material hubs to tighten supply security and traceability. In June 2023, it launched PureBrew Bioactives with high CGA concentration to accelerate beverage flavor solutions. For procurement and R&D teams, these moves are signals: they indicate where supply assurance is being invested and where beverage-oriented application development is being actively scored.
Applied Food Sciences, based in Austin, Texas, takes a more brand-and-formulation-centric stance, focusing on branded green coffee bean extracts with defined chlorogenic acid content for dietary supplements, weight-management, and metabolic health formulations. EUROMED SA, headquartered in Barcelona, Spain, positions around high-purity botanical extracts including chlorogenic acid-rich plant extracts for pharmaceutical APIs, dietary supplements, and clinical-grade nutraceutical formulations—an orientation that matters wherever purity and documentation form the basis of supplier selection. Sabinsa Corporation, in New Jersey, continues to advance science-backed herbal and botanical APIs including chlorogenic acid extracts with clinical validation for pharmaceutical, nutraceutical, and preventive healthcare products, reinforcing the category’s credibility thread in evidence-led markets.
On the high-volume production side, several China-based manufacturers have built substantial export-oriented footprints. Zhejiang Skyherb supplies green coffee bean and honeysuckle-based HPLC 98 percent chlorogenic acid extracts to over 45 countries. Nutragreen Biotechnology similarly focuses on green coffee bean and honeysuckle-based HPLC 98 percent extracts, with an estimated 13 percent global market share. Chenguang Biotech has developed a portfolio of 37 chlorogenic acid product variants, holds an estimated 11 percent global market share, and supplies markets across more than 45 countries. Changsha E.K. HERB focuses on natural ingredients including chlorogenic acid extracts for nutraceutical and functional food applications, while Nanjing Zelang extends into medical technology and botanical extracts including chlorogenic acid for pharmaceutical and supplement uses. Cymbio Pharma, based in India, rounds out the competitive picture with a focus on herbal and botanical APIs including chlorogenic acid extracts for pharmaceutical and nutraceutical markets.
Together, these profiles highlight a competitive environment in which differentiation is being built on extraction purity, botanical origin, traceability, clinical or regulatory substantiation, and geographic supply reach. The report examines how these company-level strategies map onto the broader concentration pattern and where their combined movements are likely to influence pricing power, supply security, and formulation availability across the forecast period.
What the Report Delivers: Operational Intelligence for 2026 Planning
This market research is designed as a decision tool rather than a purely descriptive overview. It integrates historical performance from 2020 through 2025 with a forecast window spanning 2026 to 2032, anchored in a base-year valuation of USD 215.0 Million and projected toward long-range market sizing in the vicinity of USD 316.72 Million by 2032. The study organizes that trajectory around the segmentation dimensions most relevant to formulation, procurement, and market-entry planning: regional demand distribution, type-level supply positioning across green coffee beans, honeysuckle, and eucommia, and application-level behavior across nutraceuticals, food and beverage, cosmetics and personal care, and pharmaceuticals.
Beyond the macro sizing, the report advances practical analysis in several areas that directly affect 2026 execution. It examines how concentration patterns shape bargaining dynamics and allocation risk, where supplier expansion and product launches are altering capability ceilings, and how regulatory divergence across key markets is reshaping formulation boundaries and documentation requirements. It also situates the category within wider raw-material and trade currents, including the structural dependence on coffee-sector output, the impact of evolving tariff and import-expenditure conditions, and the implications of regulatory limits in certain food applications. The objective is to help teams answer operational questions with greater precision: where demand is deepening versus broadening, which supply routes are becoming more resilient or more exposed, and which competitive capabilities are likely to set the pace for category standards over the next several years.
To keep the analysis usable for cross-functional teams, the study translates market structure into strategic implications. For procurement leaders, it clarifies where supplier concentration and capacity activity are most likely to affect availability and negotiation leverage. For R&D and brand teams, it connects application trends and regulatory signals to formulation choices and launch timing. For competitive-intelligence functions, it maps the major players’ orientations and recent moves against the concentration and segmentation landscape, enabling more informed benchmarking and scenario planning.
How to Use This Intelligence Before the 2026 Cycle Closes
The chlorogenic acid market is not simply expanding; it is reconfiguring around purity expectations, regulatory interpretation, botanical sourcing strategy, and supplier concentration. The headline growth path—moving from a 2025 base of USD 215.0 Million toward a multi-year trajectory above USD 300 Million—masks a more important story for operators: the same market that rewards scale and consistency also punishes undifferentiated sourcing in a landscape where traceability, compliance, and application-specific quality are increasingly decisive. The strategic winners in 2026 will be those who can pair demand insight with supply-side realism, using concentration data, type-level positioning, and competitive capability mapping to reduce uncertainty rather than simply track it.
This report provides the framework for that kind of decision-making, but the full segmentation detail, regional demand mapping, type-level value distribution, application-level breakdowns, and company-specific strategic positioning are presented in depth only in the complete study. For teams that need the underlying numbers, scenario-ready segmentation, and the analytical logic behind supplier and regulatory implications, the complete market intelligence is available through the PW Consulting research portal. Accessing the full report will allow your team to move from directional confidence to execution-ready precision before the 2026 planning cycle advances further.
For detailed analysis of this topic, please visit the official page: Chlorogenic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Orally Disintegrating Tablets to Reach $344.8M by 2032, 8.5% CAGR
By pmarketresearch, 2026-09-15
Unlocking the Future of Patient-Centric Dosage: Strategic Insights into the Orally Disintegrating Tablet Market 2026–2032
The pharmaceutical industry is undergoing a quiet but profound transformation in how therapies are delivered. Patient adherence, ease of administration, and rapid onset of action are no longer secondary considerations; they are central pillars of modern drug development and commercial strategy. At the forefront of this shift is the orally disintegrating tablet (ODT) segment, a dosage form that bridges the gap between traditional solid oral dosage and advanced patient-centric delivery systems. As we step into 2026, decision-makers across pharmaceutical manufacturers, CDMOs, excipient suppliers, and life sciences investors require a clear, data-grounded view of where this market has been, where it is accelerating, and which structural forces will reshape competitive advantage over the next seven years.
This article introduces PW Consulting’s newly released Orally Disintegrating Tablet Market research, a comprehensive strategic briefing designed to equip executive teams with actionable intelligence for 2026 planning and beyond. Rather than offering surface-level aggregates, the study maps the interplay between historical trajectory, regulatory evolution, formulation innovation, and competitive positioning. Below, we preview the analytical framework, highlight the macro dynamics fueling growth, and outline the practical deliverables that make this research a critical asset for enterprise strategy.
Historical Trajectory and Forecast Horizon: A Resilient Growth Arc
Understanding the ODT market’s momentum begins with a disciplined look at its recent performance. Between 2020 and 2025, the global market expanded from approximately 163.15 million USD to 215.0 million USD, reflecting steady adoption across therapeutic categories and sustained investment in patient-friendly formulations. This historical progression is not merely a sequence of annual increments; it reveals a structural inflection in how manufacturers approach dose design, commercialization pathways, and end-user compliance.
Looking forward, the forecast window spans 2026 through 2032, a period expected to deliver continued expansion at a compound annual growth rate of 8.5 percent. By the close of the projection horizon, market revenue is anticipated to surpass 344.8 million USD. These figures provide a macro foundation for resource allocation, capacity planning, and partnership strategy. More importantly, they signal that ODT adoption is transitioning from a niche convenience to a mainstream formulation preference, particularly where rapid disintegration, swallowing difficulty mitigation, and taste-masked delivery create measurable clinical and commercial value.
For 2026 decision-making, this growth trajectory matters because it frames the window of opportunity for first-mover advantage in emerging indications, regional commercialization, and manufacturing scale-up. Companies that align their pipeline priorities, contract manufacturing relationships, and dosing platform investments with this forecasted cadence will be better positioned to capture share as the market matures.
Segment Architecture: Where Value Is Being Created
The ODT landscape is not a monolith. Value creation is distributed across therapeutic classes, disease indications, and regional ecosystems, each carrying distinct adoption drivers, formulation challenges, and reimbursement dynamics. A 500 mg weight ceiling and a 30-second disintegration expectation, as defined in longstanding FDA guidance, remain active commercial constraints that shape formulation strategy and directly influence manufacturing feasibility.
Within drug class segmentation, the market reflects a diversified portfolio spanning central nervous system therapies, anti-epileptic treatments, and a broad category of additional indications that collectively drive volume. The distribution of revenue across these classes underscores how ODT technology has moved beyond a single therapeutic niche to become a cross-indication platform. Similarly, disease indication mapping reveals that CNS disorders represent the largest demand pool, followed by gastrointestinal conditions, cardiovascular disorders, and allergy-related formulations. This spread matters because each indication carries its own clinical urgency, prescribing patterns, and patient demographics, which in turn shape lifecycle management strategies and commercialization sequencing.
Regional dynamics further complicate the picture. North America, Europe, and Asia Pacific each present distinct pathways shaped by regulatory calendars, reimbursement architectures, manufacturing localization trends, and evolving standard-of-care expectations. Europe, for example, benefits from favorable reimbursement policies supporting chronic disease treatments, while North America remains a hub for formulation innovation and branded ODT launches. Asia Pacific reflects expanding manufacturing capacity and growing access to advanced dosage forms. Latin America and the Middle East and Africa, though smaller in relative scale, represent emerging adoption corridors where access, affordability, and supply chain flexibility increasingly determine market entry success.
Because these segmentation layers interact with pricing, bioequivalence requirements, and sourcing logic, a superficial read of regional or therapeutic shares can be misleading. The full study provides the structured comparisons necessary to identify where differentiation is genuinely achievable and where competition is likely to compress margins.
Regulatory and Operational Dynamics Shaping 2026
No ODT strategy is complete without accounting for the regulatory and operational environment that governs formulation choices, approval pathways, and commercial viability. In late 2025, the FDA revised product-specific guidance for Primidone Oral Tablet ODT and recommended product-specific guidance for Escitalopram Oxalate ODT, reinforcing standardized bioequivalence study expectations with and without water. These updates matter because they directly influence generic approval pathways, development timelines, and the design of comparative studies. For manufacturers pursuing ANDA filings or evaluating lifecycle extensions, the guidance landscape can accelerate or constrain entry strategies depending on how formulation parameters align with bioequivalence expectations.
Operational realities are equally important. Generic ODT production depends on disciplined cost control around excipients, with multi-supplier sourcing strategies increasingly viewed as essential to maintaining competitive pricing and supply continuity. Meanwhile, the broader industry continues to grapple with formulation limits, disintegration performance targets, and the need to balance patient experience with manufacturing throughput. These operational forces create a natural filter: companies that treat ODT development as a pure formulation exercise often miss the broader commercial equation involving sourcing resilience, scale-up economics, and regulatory timing.
Recent developments also highlight the pace of innovation entering the market. In 2026, Emalex Biosciences received a US patent for an ODT formulation of ecopipam and initiated process development for cGMP manufacturing targeted for late 2026 or early 2027. Such milestones illustrate how formulation IP, process readiness, and manufacturing sequencing now converge to determine commercial readiness. For competitive analysts and pipeline strategists, tracking these events provides early signals about which therapeutic categories may see new ODT entrants, where differentiation can be established, and how manufacturing bottlenecks could affect launch timing.
Competitive Landscape: Platforms, Capabilities, and Positioning
The ODT competitive field is defined by a mix of technology providers, contract manufacturers, branded product owners, and excipient specialists. Each player contributes a distinct layer to the value chain, and understanding their capabilities is essential for mapping partnership opportunities, outsourcing strategies, and competitive threats.
Catalent Pharma Solutions, based in Swindon, United Kingdom, manufactures Zydis orally disintegrating tablets with cGMP production exceeding 1.5 billion doses annually at dedicated facilities. This scale positions the company as a significant capacity and technology reference point for ODT manufacturing. Adare Pharma Solutions, headquartered in Chicago, Illinois, offers AdvaTab ODT technology designed to deliver rapid-disintegrating tablets that are bioequivalent to conventional formulations, an attribute directly relevant to regulatory navigation and product equivalence strategies.
LGM Pharma, operating in the United States, functions as a CDMO offering contract manufacturing of high-dose ODTs, including recent ANDA filings for complex formulations. Its work highlights the growing intersection between formulation complexity and contract manufacturing demand. Vitaquest, based in New Jersey, specializes in nutraceutical ODT manufacturing with custom formulations for supplements, illustrating how ODT technology extends beyond prescription pharmaceuticals into consumer health and wellness categories.
In Europe, Dec Group, based in Switzerland, manufactures ODTs using Lyopan technology in collaboration with Rohrer for rapid-disintegrating solid doses, while Roquette, located in Lestrem, France, supplies excipients and two-component platforms that simplify ODT formulation and manufacturing. These technology and material enablers demonstrate that competitive advantage increasingly depends on integrated formulation platforms rather than isolated manufacturing claims.
Otsuka Pharmaceutical, headquartered in Tokyo, Japan, continues to develop and market branded ODT products such as Abilify Discmelt and Abilify Maintena ODT, reflecting the strategic role of brand owners in shaping prescribing familiarity and patient acceptance. At the market structure level, concentration metrics indicate a moderately consolidated field: CR3 reaches 36.0 percent and CR5 reaches 48.0 percent. This distribution suggests that while leading players hold meaningful share, there remains sufficient fragmentation to support new entrants, specialized CDMOs, and niche formulation providers that can compete on speed, customization, or therapeutic focus.
The strategic implication for 2026 is clear. Companies must assess where they sit within this value chain and how they intend to compete. For CDMOs, differentiation may come from high-dose capability, bioequivalence support, or regulatory acceleration. For branded manufacturers, the priority may be lifecycle extension, patient adherence programs, and indication expansion. For excipient and technology providers, the opportunity lies in platform simplicity, supply resilience, and manufacturing compatibility. The report’s competitive analysis is designed to help each player identify the right leverage points.
Inside the Report: What Decision-Makers Will Gain
PW Consulting’s Orally Disintegrating Tablet Market study is built to translate macro trends into operational decision support. The report goes beyond headline figures to provide a structured, cross-referenced view of market size, growth drivers, segmentation logic, regulatory touchpoints, and competitive positioning. It is designed for teams that need to align commercial planning, R&D prioritization, manufacturing strategy, and investment decisions with a consistent evidence base.
Key components of the research include a detailed market size and forecast framework spanning the base year through the 2032 projection period, with historical context that clarifies the pace and composition of growth. The segmentation analysis maps demand across drug classes and disease indications while preserving enough analytical discipline to avoid oversimplified conclusions. Regional perspectives are integrated to show how reimbursement, access, and manufacturing localization affect adoption paths without reducing the discussion to static share tables.
The report also provides a competitive profiling section that situates major players within the value chain, highlighting technology platforms, manufacturing scale, formulation strengths, and strategic orientation. Recent developments are incorporated to connect market structure with live industry events, including patent activity, guidance updates, and manufacturing timelines that can alter near-term competition. In addition, the study addresses operational considerations such as excipient sourcing, weight and disintegration constraints, and the practical implications of bioequivalence study expectations.
For executive teams, these elements combine into a practical toolkit. Commercial leaders can use the forecast framework to test demand scenarios and prioritize indication expansion. R&D and formulation teams can reference the regulatory and technical discussion to anticipate development constraints and align platform decisions with approval pathways. Procurement and supply chain stakeholders can evaluate sourcing logic and capacity considerations in the context of cost control and flexibility. Investors and strategy teams can use the competitive and concentration analysis to assess where consolidation pressure is likely to intensify and where specialized capabilities may command premium positioning.
Strategic Takeaways for 2026 Planning
As 2026 unfolds, the ODT market offers a clear example of how patient-centric formulation strategy can translate into durable commercial relevance. Several themes should anchor enterprise planning.
- Growth is structural, not cyclical. The combination of historical momentum and an 8.5 percent CAGR through 2032 suggests that ODT adoption will continue to expand across multiple therapeutic and patient-access contexts, making formulation flexibility a long-term asset rather than a short-term tactic.
- Regulatory clarity shapes speed. Recent FDA guidance revisions and product-specific recommendations influence bioequivalence design, generic pathways, and development sequencing. Teams that integrate regulatory trajectory into early formulation decisions can reduce downstream rework and accelerate commercialization readiness.
- Operational discipline determines margin resilience. With formulation weight limits, disintegration targets, and excipient sourcing requirements in play, competitive advantage increasingly depends on manufacturing efficiency, supplier flexibility, and cost-aware design.
- Platform capability outweighs one-off scale. The presence of multiple technology providers, CDMOs, and excipient specialists indicates that integrated formulation platforms and process readiness are becoming central to differentiation, especially for complex or high-dose products.
- Concentration leaves room for targeted positioning. With a moderately consolidated market structure, there is meaningful space for specialized players that can serve specific indications, formulation challenges, or regional access needs without attempting to compete solely on scale.
These themes point toward a practical conclusion: the organizations that will capture the most value in the ODT market are those that treat dosage form strategy as a multi-dimensional business decision, connecting clinical need, regulatory risk, manufacturing feasibility, and competitive positioning into a single coherent plan.
Conclusion: From Market Intelligence to Actionable Strategy
The Orally Disintegrating Tablet Market is entering a phase where informed strategic choices will separate scalable growth from marginal participation. Themacro trajectory, segmentation diversity, regulatory dynamics, and competitive structure described in this preview reflect a market that is both expanding and maturing. That combination creates opportunity, but only for teams equipped with detailed, current, and operationally relevant intelligence.
PW Consulting’s full market research is designed to provide that level of clarity. It translates broad growth signals into segment-level logic, regulatory context, competitive mapping, and development-ready insight, enabling decision-makers to move from awareness to action with confidence. For organizations planning 2026 pipeline prioritization, manufacturing partnerships, regional expansion, or competitive responses, the complete study offers the depth required to support decisive strategy.
To access the full forecast framework, segmentation analysis, competitive profiles, and operational insights, request the complete Orally Disintegrating Tablet Market report and integrate its findings directly into your 2026 strategic planning process.
Orally Disintegrating Tablet Market
Worldwide Oral Solid Dosage Medicine Market
For detailed analysis of this topic, please visit the official page: Orally Disintegrating Tablet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Car Care Products Market Hits USD 11.5B in 2025, Projected 4.5% CAGR to 2032
By pmarketresearch, 2026-09-15
Navigating the Next Wave of Automotive Care: Strategic Intelligence for 2026 and Beyond
The automotive care sector has matured into a complex, multi-faceted ecosystem where chemical innovation, consumer behavior, and regulatory shifts intersect. As we step into 2026, market participants face a landscape defined by steady expansion, evolving formulation standards, and intensifying competitive positioning. At PW Consulting, we have synthesized five years of historical tracking alongside a forward-looking horizon through 2032 to deliver a comprehensive market research publication that moves beyond surface-level market sizing. This document serves as an introduction to our latest Car Care Products Market study, outlining the strategic architecture, analytical rigor, and decision-ready intelligence embedded within the full report.
Historically, the segment demonstrated resilience even amid supply chain volatility and shifting retail channels. Our baseline tracking anchored in 2025 captures the current inflection point, with prior-year data reflecting the broader recovery and stabilization patterns observed across the industry. The revenue trajectory from 2020 through 2025 illustrates a market that has consistently adapted, recalibrating product offerings, channel strategies, and pricing structures in response to macroeconomic and behavioral forces. Looking ahead, our forecast horizon extends through 2032, providing a structured lens through which to evaluate growth trajectories, scenario planning, and long-term capital allocation.
The Strategic Case for Data-Driven Decision Making in 2026
For executives, product managers, and investment strategists, 2026 represents a pivotal planning cycle. The early part of the decade is characterized by a convergence of demand-side normalization, supply-side optimization, and the gradual integration of new performance and safety standards. In this environment, reliance on fragmented data sources or outdated industry narratives introduces material risk to product roadmaps, geographic prioritization, and portfolio rebalancing. A rigorous market study functions as a clarifying instrument: it aligns cross-functional teams around a shared data baseline, surfaces structural opportunities that are not immediately visible in operational metrics, and provides the analytical scaffolding necessary to evaluate strategic trade-offs.
The full report is built with this operational mandate in mind. Rather than presenting static point estimates in isolation, the analysis constructs a multi-dimensional view of how product categories, application channels, end-use requirements, and regional dynamics interact with each other under different market conditions. The objective is to equip decision-makers with a defensible framework for resource allocation, competitive positioning, and strategic timing—particularly important as organizations prepare for the next phase of growth through the end of the decade.
Macro Trajectory and Structural Momentum
The broader market has reached a scale that demands strategic attention. Our baseline year of 2025 establishes the starting point for the analysis, and the historical sequence from 2020 through 2025 reflects a market that has expanded materially over that period. The progression from early-cycle figures in 2020 to the 2025 baseline underscores a sustained upward path, punctuated by the kinds of year-to-year variations typical of a mature consumer and commercial B2B category.
Our forecast interval for 2026 through 2032 is constructed using a disciplined methodological approach, incorporating demand-side indicators, channel evolution, and structural enablers of future growth. The compounded annual growth rate for the forecast period is projected at 4.5 percent, reflecting a moderate but durable expansion profile. By 2026, revenue is expected to cross the twelve-billion-dollar threshold in terms of market scale, and the subsequent trajectory through 2032 points toward continued expansion, with notable step-ups along the way as category demand, retail penetration, and professional service utilization advance. This growth narrative is not uniform; it is shaped by category-specific momentum, regional demand patterns, and the evolving balance between consumer-led and professionally delivered segments.
Deep Dive: Competitive Architecture and Key Players
No market of this scale operates without a clearly defined competitive hierarchy. The study profiles a set of organizations that consistently influence category standards, pricing benchmarks, and innovation pacing. Our profiles span U.S.-based manufacturers with broad retail and commercial footprints, as well as internationally active specialists that have cultivated reputations around formulation quality and professional-grade performance.
- Turtle Wax, Inc. operates as a manufacturer of award-winning car care products, offering a portfolio that spans washes, waxes, coatings, and detailing supplies. The company's breadth of offering position makes it a reference point for accessibility and brand recognition within the consumer-facing dimension of the market.
- Meguiar's, Inc. has built its identity around high-quality car care chemicals, polishes, waxes, and appearance products for both interior and exterior applications. Its specialization in finish care and enhancement products places it at the center of the performance-oriented consumer and enthusiast conversation.
- SONAX GmbH is recognized as a supplier of premium automotive chemical products for vehicle maintenance and detailing. Its positioning reflects the premiumization trend within European and export-oriented channels, where chemical precision and professional results carry strong market weight.
- Stinger Chemicals functions as a developer and marketer of retail and commercial product lines for detailing and protection. Its dual orientation toward retail and professional users is particularly relevant for understanding how product architectures are designed to serve both channels simultaneously.
- 3M Company contributes a broad range of abrasives, cleaners, polishes, waxes, and detailing compounds tied to automotive appearance. Its scale, technical heritage, and cross-industry capability give it a distinctive role in the supply chain and in the broader context of performance materials.
- Calumet, Inc. manufactures specialty solvents, waxes, and petrolatums used in consumer car care product formulation. Its role highlights the upstream chemistry dimension of the market, where raw material innovation and formulation inputs shape downstream performance, cost structures, and product differentiation.
These profiles do not merely summarize corporate positioning; they are integrated into a larger competitive assessment that examines how players differentiate across formulation, channel strategy, geographic presence, and service orientation. The report also evaluates competitive intensity, market concentration, and the structural forces that shape pricing power, merger and acquisition logic, and brand elasticity.
Car Care Cosmetics for Petrol Channel Market
Recent Developments That Reshape the Playing Field
The competitive landscape is not static. Strategic moves in recent months demonstrate how companies are actively repositioning to capture emerging demand and to strengthen channel relevance. In March 2025, Luminous introduced its 2025 catalog of premium car care products, showcasing advanced detailing and protection formulas. The launch signals a continued push toward premium performance narratives, visual differentiation, and formulation advancements that appeal to detail-oriented end users and professional service providers.
In October 2025, Stinger Chemicals announced plans to launch the Quantum Car Care Line at the SEMA Show, targeting commercial users with specialized retail products. This development is indicative of a broader pattern: companies are increasingly calibrating product lines for commercial-grade durability, service-channel compatibility, and cross-channel appeal. The SEMA Show setting further emphasizes the importance of industry forums as launch platforms, where new developments are positioned directly in front of trade audiences and influential aftermarket stakeholders.
Regulatory and Macroeconomic Overlays Shaping 2026 Strategy
One of the defining features of the current environment is the interplay between product innovation and policy-driven market dynamics. Trade policy adjustments in the United States have introduced new cost considerations and planning complexity for imported vehicles, parts, and related supply flows. On March 26, 2025, a presidential proclamation adjusted imports of automobiles and automobile parts into the United States, imposing a 25 percent tariff on imported passenger vehicles, light trucks, and key parts. The framework incorporated modifications for USMCA-compliant goods, applying duties only to non-U.S. content. This structure illustrates how compliance architecture, sourcing footprint, and content origin now matter more sharply in cost planning and product positioning.
Further layers of duty exposure were established for heavier vehicle categories. As of November 1, 2025, U.S. imports of medium and heavy-duty vehicles and their parts face new Section 232 duties ranging from 10 percent to 25 percent, with exemptions available for USMCA-qualified goods. Taken together, these developments reinforce a core strategic reality: supply chain design, compliance positioning, and content localization have become integral to cost competitiveness and to the broader economics of automotive-related product categories. In the car care market specifically, these overlays influence formulation sourcing, packaging considerations, and the relative attractiveness of domestic versus cross-border supply strategies. Our study addresses these dynamics within the broader market environment analysis so readers can interpret competitive moves and channel behaviors in light of policy realities rather than in isolation.
Inside the Report: What Decision-Makers Will Receive
The study is designed to be actionable at multiple organizational levels. It begins with a comprehensive market definition and scope framework, then builds out the historical baseline and forecast architecture that underpins the full analysis. Beyond aggregate sizing, the report decomposes demand across the structural dimensions that matter most to commercial planning. Readers will find a detailed treatment of product-type evolution, an assessment of how different body-part care categories perform and interact, and a nuanced view of application dynamics distinguishing between self-directed and professionally delivered treatment patterns.
Regional analysis is presented with an emphasis on relative market weight, directional growth behavior, and the structural factors that shape local demand. The report also examines market concentration through the lens of competitive influence, including concentration metrics that help stakeholders interpret the balance between consolidated leadership and open competition. Importantly, the report integrates these structural views with the regulatory and industry context described above, allowing users to connect demand-side insights with policy overlays, competitive moves, and formulation trends.
In addition to quantitative architecture, the report provides qualitative intelligence on strategic imperatives. This includes category dynamics, channel evolution considerations, and the emerging performance expectations that are reshaping product development priorities. By connecting structure to behavior, the study enables users to translate market-level intelligence into operating-level implications: where to focus innovation resources, which customer segments warrant deeper engagement, and how to interpret competitor actions within a broader competitive logic.
Translating Intelligence into 2026 Action
Strategy in this market depends on the ability to connect long-term trends with near-term execution. The full report is constructed to support that translation. Product teams can use the structural decomposition to prioritize formulation investment and portfolio sequencing. Commercial leaders can use the demand segmentation insights to refine channel strategy and customer targeting. Market entry and M&A groups can use the concentration and competitive profiles to assess where value creation is most attainable and where risk is most concentrated.
Because the forecast horizon extends through 2032, the study also supports longer-range scenario planning. Organizations can evaluate how current positioning aligns with later-cycle growth, how category momentum may shift under different demand assumptions, and where structural advantages are likely to matter most as the market continues to scale. This longer view is particularly valuable for businesses that must reconcile short-term sales objectives with multi-year investment commitments.
Car Care Products Market
Why the Full Study Is Essential for Strategic Confidence
A press release-style summary can point toward direction, but it cannot substitute for the analytical depth required for confident decisions. The full Car Care Products Market report from PW Consulting delivers a complete data architecture, a rigorous methodological framework, and a practical mapping of market structure to strategic action. It is designed to reduce uncertainty around size, growth, competitive positioning, and regulatory exposure, while giving executives the evidence base needed to justify capital deployment and strategic timing.
The study is also built to be used, not merely read. Its structure supports internal presentations, cross-functional alignment, and board-level discussion, because it connects the numbers to the interpretations that matter in practice. By presenting the market through multiple lenses—product, application, body-part focus, regional dynamics, competitive concentration, and external regulation—the report provides a holistic operating picture that stands apart from narrow single-metric summaries.
Strategic Readiness in an Evolving Category
The car care market in 2026 rewards organizations that combine category awareness with disciplined analysis. Growth is expected to continue at a measured pace, competitive differentiation is intensifying, and external policy overlays are adding new complexity to cost and sourcing decisions. In that context, a comprehensive, forward-looking study is not a supplementary document; it is a strategic asset. PW Consulting's Car Care Products Market research provides the depth, clarity, and structured insight needed to navigate this environment with confidence, from the current planning cycle through the long-range horizon.
To access the full dataset, scenario analysis, and complete competitive and structural breakdowns, we invite you to review the complete report. The underlying detail that supports every directional insight in this overview is available in the full publication, providing the evidence base necessary to convert market intelligence into decisive, well-supported strategy.
For detailed analysis of this topic, please visit the official page: Car Care Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Disposable Lighters Market Hits $215M in 2025, Projects 4% CAGR to 2032
By pmarketresearch, 2026-09-15
The Disposable Lighters Market in 2026: Strategic Intelligence for Navigating Growth, Regulation, and Competition
Executive Overview
The disposable lighter market stands at a pivotal juncture as it enters the 2026 forecasting horizon. Built on six years of historical tracking from 2020 through 2025 and projected forward to 2032, our latest Disposable Lighters Market research offers decision-makers a rigorous, data-grounded view of where the industry is headed and how to position for durable advantage. This article previews the strategic architecture of that study, highlights the macro trajectory that shapes corporate planning, and illustrates why full-report access is essential for precise, actionable execution.
At the aggregate level, the sector has demonstrated resilient expansion through a period marked by shifting consumer habits, tightening safety mandates, and evolving material economics. Measured in millions of USD, the market moved from an estimated 163.15 million in 2020 to 171.54 million in 2021, 182.71 million in 2022, and 193.98 million in 2023. A brief plateau near 194.2 million in 2024 gave way to a stronger rebound to 215.0 million in 2025, signaling renewed demand momentum and pricing normalization after post-pandemic supply adjustments. Looking ahead, the base year of 2025 anchors a forecast that reaches 228.11 million in 2026, 253.39 million in 2027, and 257.58 million in 2028 before continuing its upward course toward 281.65 million in 2029, 307.56 million in 2030, 325.93 million in 2031, and 344.8 million in 2032. Across the full forecast window, the market is projected to compound at a steady 4.0 percent CAGR, reflecting a sector that is expanding with discipline rather than volatility.
For executives, this trajectory is not simply a line on a chart. It is a frame for capital allocation, product mix decisions, supplier negotiations, and regulatory preparedness. The report is designed to convert these macro signals into operational clarity across geographies, product types, and end-use segments, all while preserving the analytical depth required to test assumptions and stress scenarios.
The 2026 Decision Environment
The year 2026 introduces a distinct set of decision points for manufacturers, distributors, and category investors. Demand has recovered beyond pre-plateau levels, yet the operating terrain has grown more complex. Companies must now reconcile volume growth with compliance burdens, cost pressure on plastics and metals, and the strategic positioning of product lines ranging from commodity flint designs to specialty utility and premium offerings. In this environment, aggregate growth alone does not dictate winners. Advantage accrues to organizations that can decompose the market precisely, identify where value is actually generated, and align product roadmaps with enforceable safety and material standards.
Our study is built for that complexity. It translates historical momentum into a structured forward view, allowing leadership teams to test capacity expansions, prioritize regional entries, and evaluate whether to compete on cost, compliance, durability, or brand equity. The forecast framework covers the full 2026 to 2032 arc, which is especially valuable when programs require multi-year lead times and long-cycle supplier commitments. Rather than forcing decisions on anecdotal momentum, the report grounds them in a consistent methodology and clearly defined base assumptions.
What the Report Delivers
The core objective of this research is to turn top-level demand signals into practical decision intelligence. The report combines a long-run historical baseline with a structured forecast and a granular breakdown of the market across dimensions that matter operationally. Readers will find a comprehensive market sizing narrative that traces the 2020 to 2025 evolution and extends through 2032, supported by a transparent view of how growth compounds over time. Beyond the headline figures, the study provides segmentation architecture that separates the market by geography, by product type, and by application, so teams can assess where volume concentrates and where value pools diverge.
Equally important, the report addresses the structural forces influencing those segments. It examines regulatory developments that affect product design, import logic, and producer obligations, alongside raw material dynamics that shape unit economics and sustainability exposure. The study also evaluates manufacturing scale, labor cost sensitivity, and supply-chain vulnerability in key production regions, helping leaders distinguish between apparent volume opportunities and economically viable ones. In practical terms, this means the report supports a wider range of decisions than simple growth planning. It informs SKU rationalization, packaging strategies, compliance roadmaps, distribution partnerships, and competitive positioning with respect to the dominant branded players and their specialized niches.
Because the research is designed as a decision tool rather than a static reference, it integrates scenario-ready thinking. Senior teams can use the forecast structure to model how demand might respond to pricing shifts, regulatory timing, or channel mix changes. That flexibility is essential in a market where one size rarely fits all and where regional or product-level dynamics can diverge materially from the global average. The full report makes those divergences visible without diluting the central narrative, enabling users to focus on the segments most relevant to their specific objectives.
Market Dynamics: Regulation, Materials, and Supply
Several concurrent forces define the current operating landscape. On the regulatory side, safety and material policy are reshaping what can be sold, where it can be sourced, and who bears the compliance burden. In the United States, enforcement of child-resistant lighter standards under 16 CFR part 1210 requires disposable lighters to incorporate mechanisms that reduce accidental ignition by children, a requirement that influences design, manufacturing, and quality assurance across the supply base. At the same time, the EU Single-Use Plastics Directive, together with equivalent legislation in the UK, Canada, and Australia, introduces phased restrictions and extended producer responsibility obligations on single-use plastic lighters. These measures raise compliance costs and encourage manufacturers to reconsider material choices, packaging, and product longevity.
Trade policy adds another layer of complexity. Rules advanced by the U.S. International Trade Commission and the Consumer Product Safety Commission on disposable pocket lighters have begun to limit imports from certain countries, affecting pricing, domestic production margins, and sourcing strategies. These import constraints can create localized supply advantages for compliant producers while raising cost and availability pressure for others. The result is a market in which regulatory alignment increasingly determines access as much as product quality or brand strength.
Disposable Lighters Market
Materials and production economics remain central to unit economics. Each year, more than 15 billion disposable lighters are produced worldwide, primarily using non-recyclable plastic and metal components that contribute to plastic pollution. This scale is both a demand signal and a sustainability challenge, particularly as extended producer responsibility regimes mature. Manufacturing capacity expansion in China by major players has increased production scale, yet it has also exposed the sector to volatile labor and supply-chain costs for plastic and metal components. For global buyers and producers alike, this means that capacity abundance does not automatically translate into stable margins or predictable lead times.
These dynamics are not peripheral notes. They are market-shaping conditions that affect product architecture, sourcing strategy, and regional profitability. The report treats them as integral to the forecast rather than as separate commentary, so users can see how regulatory timing, compliance cost, and material exposure interact with the demand trajectory from 2026 onward.
Competitive Landscape: Leadership, Specialization, and the Path to Enduring Advantage
The structural concentration of the market underscores the importance of competitive intelligence. The top three firms account for about 65.0 percent of the market, while the top five reach roughly 75.0 percent, indicating a landscape where scale, brand recognition, and distribution reach matter significantly. Yet concentration does not imply uniformity. The competitive field is diversified by purpose, with players pursuing distinct value propositions across mainstream utility, safety-focused design, premium branding, and OEM supply.
Disposable Masks Market
Among the leaders, Société BIC S.A., headquartered in France, stands as the world’s largest branded pocket lighter manufacturer, with over 30 billion units sold. Its strength lies in child-resistant disposable flint lighters and multi-purpose utility lighters, positioning it at the intersection of safety compliance and broad consumer accessibility. Tokai Corporation, based in Japan, operates as a major global supplier of disposable and refillable lighters with a strong emphasis on OEM production. Its focus on safety, child-resistant features, and cost-efficient flint designs makes it a critical partner for brands and distributors seeking reliable manufacturing scale. Flamagas S.A., from Spain, is known for durable, windproof disposable lighters under the Clipper brand, emphasizing robust flint ignition and multi-use utility applications that appeal to both retail consumers and professional users.
Swedish Match, headquartered in Sweden, leads with Cricket-branded disposable lighters and specializes in reliable, child-resistant flint lighters for global retail and utility markets. Zippo Manufacturing Company, from the United States, occupies a distinct niche with classic metal-bodied disposable and hybrid lighters built on windproof flint technology, targeting premium and everyday-carry utility segments. In China, NingBo Xinhai Electric Co., Ltd. plays a major role as a manufacturer of disposable flint and electronic lighters, supplying windproof arc and traditional models for global distribution and reinforcing the country’s importance as a production hub. Calico Brands, Inc., also based in the United States, serves as a wholesale supplier of diverse disposable lighter SKUs, including multi-purpose, spark-wheel, and value-priced flint designs, with a clear focus on retail and institutional bulk distribution. Finally, S.T. Dupont, from France, operates in the luxury tier with high-end disposable and metal lighters, offering premium flint and torch-style utility models for high-end markets where branding and finish command price premiums.
The competitive story is therefore one of layered positioning. Scale and compliance expertise sit alongside durability, windproof performance, OEM flexibility, and premium differentiation. The report examines how these players are structured, where their strengths align with regulatory and consumer trends, and which segments are most contested or most open. Full competitive profiling in the study goes further than brand recognition by connecting product strategy to market structure, so readers can identify where to defend share, where to build differentiated offerings, and where to pursue partnership or acquisition opportunities.
Why the Full Study Matters for 2026 Planning
For executives planning around 2026, the difference between good strategy and great strategy is often granularity. Aggregate growth and a steady CAGR frame the opportunity, but the real decisions lie in understanding how demand, regulation, materials, and competition interact in specific contexts. The complete Disposable Lighters Market report provides that context through detailed segmentation insight, structural analysis, and competitor scaffolding, all organized to support practical action. It helps teams answer questions that aggregate summaries cannot resolve on their own: where growth is most defensible, which compliance trajectories carry the highest operational cost, which product types balance demand with margin potential, and how major players are likely to respond as the forecast window progresses.
The study also provides the roadmap for reading the market beyond the headline. With a forecast that extends to 2032, decision-makers can align investment timing, production commitments, and go-to-market plans with a realistic growth arc instead of reacting to short-term fluctuations. That longer view is especially valuable when safety mandates, trade constraints, and material obligations continue to evolve in parallel, because it allows organizations to anticipate change rather than simply absorb it.
Access the Intelligence
This article previews the strategic logic and structural clarity behind our latest market research. The full Disposable Lighters Market report goes further by combining historical depth, a rigorous 2026 to 2032 forecast, segmentation detail, competitive profiling, and regulatory and materials analysis into a single decision-ready framework. For leadership teams that need to move from directional confidence to precise execution, the complete study offers the granularity required to plan with conviction. Access the source page to obtain the full intelligence set, detailed segmentation findings, and the competitive context needed to shape 2026 strategy with precision.
For detailed analysis of this topic, please visit the official page: Disposable Lighters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oxygenator Market Hits $211.5M in 2025, Projects 5.8% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Breathing Room: Navigating the Oxygenator Market Amidst 2026 Regulatory and Reimbursement Shifts
The global medical device landscape is witnessing a critical juncture in extracorporeal life support technologies. As healthcare systems grapple with evolving reimbursement codes, regulatory scrutiny, and increasing demand for advanced cardiopulmonary solutions, the Oxygenator Market stands at the forefront of strategic investment decisions. Our latest comprehensive market research report provides a definitive roadmap for stakeholders aiming to capitalize on the projected growth trajectory through 2032.
For executives and investors operating in the medtech sector, understanding the nuances of this market is no longer optional—it is imperative. The period from 2026 to 2032 represents a transformative era where technological innovation intersects with complex policy changes. This article serves as a strategic overview, highlighting the macro-economic drivers and competitive dynamics while outlining the depth of intelligence available in our full proprietary study.
Market Trajectory and Macro-Economic Fundamentals
The Oxygenator Market has demonstrated resilience and steady expansion over the past half-decade. Historical data from 2020 through 2025 indicates a consistent upward trend in revenue generation, reflecting the essential nature of oxygenation technologies in critical care and surgical settings. In 2020, the market valuation stood at 165.5 million USD, a figure that has climbed year-over-year to reach 211.5 million USD in 2025. This growth underscores the increasing reliance on extracorporeal membrane oxygenation (ECMO) and cardiopulmonary bypass (CPB) procedures globally.
Looking forward, the forecast period from 2026 to 2032 suggests continued momentum. The market is projected to surpass the 220 million USD mark in 2026, escalating towards 312.0 million USD by 2032. This expansion is supported by a Compound Annual Growth Rate (CAGR) of 5.8 percent. Such a rate indicates a mature yet healthy growth environment, driven by epidemiological shifts, aging populations, and advancements in membrane technology that enhance biocompatibility and gas exchange efficiency.
However, raw growth figures only tell part of the story. The strategic value for decision-makers lies in understanding the velocity of this growth relative to specific regulatory timelines and reimbursement landscapes that are shifting dramatically in 2026. Our report isolates these variables to provide a nuanced forecast that goes beyond simple linear extrapolation.
The 2026 Decision Matrix: Reimbursement and Regulation
The year 2026 is poised to be a watershed moment for market dynamics, primarily due to significant adjustments in how procedures involving oxygenators are reimbursed and regulated. Strategic planning for the upcoming fiscal years must account for the complex interplay between CMS payment policies and FDA regulatory actions.
Reimbursement Landscape Changes
Effective April 1, 2026, the Healthcare Common Procedure Coding System (HCPCS) established code Q0238 for TYENNE® ECMO treatment under the Medicare Hospital Outpatient Prospective Payment System. This inclusion signals a broader acceptance and categorization of ECMO therapies within outpatient frameworks, potentially influencing hospital procurement decisions. Conversely, the CMS implemented MS-DRG assignment changes for ECMO procedures effective for Calendar Year 2026. Industry analysis suggests these changes could reduce hospital reimbursement by 40 to 80 percent for peripheral VA and VV ECMO procedures.
Oxygenator Market
Worldwide Oxygen Regulator Market
Furthermore, the Medicare Program CY 2026 Payment Policies final rule updated payment rates for inpatient and outpatient procedures involving oxygenators in ECMO and CPB settings, as finalized in November 2025. These financial pressures may drive hospitals to seek more cost-effective oxygenation solutions or consolidate purchasing around vendors who can demonstrate superior outcomes relative to cost.
Regulatory Scrutiny and Clearances
Regulatory oversight remains intense. In November 2025, the FDA issued a Class 2 recall for Medtronic Affinity NT Oxygenator units due to performance issues with CO2 gas transfer rates. This event highlights the critical importance of quality assurance and supply chain reliability in vendor selection processes. Simultaneously, the regulatory pathway continues to accommodate innovation. Sorin Group Italia S.r.l. received FDA 510(k) clearance for the Inspire 8F oxygenator integrated with a hard-shell reservoir for cardiopulmonary bypass in November 2025. More recently, in February 2026, Lifemotion Medical Technology Co., Ltd. received FDA 510(k) clearance for their Disposable Membrane Oxygenator under K253838.
These contrasting events—recalls versus clearances—create a dynamic environment where risk assessment and compliance verification become central to procurement strategies. Our report analyzes how these regulatory signals impact market share distribution and product lifecycle management.
Competitive Landscape: Leadership and Innovation
The Oxygenator Market exhibits a high degree of concentration, which presents both barriers to entry and stability for established players. The concentration ratio for the top three competitors (CR3) is 72.5 percent, while the top five competitors account for 82.0 percent of the market. This oligopolistic structure suggests that strategic partnerships or acquisitions may be necessary for new entrants seeking significant market share, while incumbents must defend their positions through continuous innovation and regulatory compliance.
Key industry players are pursuing distinct technological pathways to differentiate their offerings. Sorin Group Italia S.r.l., based in Mirandola, Italy, focuses on the Inspire series hollow fiber oxygenators for cardiopulmonary bypass and EOS ECMO oxygenators with plasma-tight membrane technology for long-term support. Their recent FDA clearance reinforces their position in the US hospital markets.
Terumo Cardiovascular Systems, headquartered in Ann Arbor, Michigan, USA, manufactures hollow-fiber membrane oxygenators such as the Capiox FX series. Their strategy emphasizes internal fiber production to ensure superior gas exchange and biocompatibility in CPB and ECMO circuits. Medtronic, Inc., from Minneapolis, Minnesota, provides the Nautilus and Affinity NT oxygenators with Balance Biosurface for ECMO and cardiopulmonary bypass applications, though recent recall events necessitate a deeper analysis of their risk mitigation strategies.
European and Asian manufacturers are also carving out significant niches. Eurosets S.r.l. in Medolla, Italy, specializes in ECMO and pediatric newborn oxygenators with integrated designs for extracorporeal life support. Spectrum Medical S.R.L. in Italy develops the Quantum Perfusion blood oxygenator using laminated membrane construction for reduced priming volume and pressure drop. In Asia, MicroPort Kewei Medical Instrument Co., Ltd. in Dongguan, China, produces the Vitasprings Spiral Diversion Integrated Membrane Oxygenator with advanced hydrodynamic design. Lifemotion Medical Technology Co., Ltd. in China manufactures disposable membrane oxygenators for cardiopulmonary bypass surgery, having recently secured FDA clearance. Additionally, Chalice Medical Ltd. in the United Kingdom offers the CMO8 adult PMP oxygenator and Paragon series for ECMO and extracorporeal bypass, maintaining ISO 13485 and FDA 510(k) compliance.
Our full report provides a granular evaluation of these companies, including their strategic moves, R&D pipelines, and vulnerability to regulatory shifts. Understanding the specific technological advantages—such as plasma-tight membranes versus hollow fiber designs—is crucial for predicting future market share reallocation.
Segmentation Insights: Technology and Application Drivers
While overall market size is important, the divergence in performance across different segments offers the most actionable intelligence for product managers and investors. The market is broadly categorized by technology type and clinical application, each facing unique adoption drivers.
In terms of technology, the market is divided primarily between Bubble Oxygenators and Membrane Oxygenators. Membrane technology has gained significant traction due to improved biocompatibility and reduced risk of complications during long-term support, such as ECMO. However, Bubble Oxygenators maintain relevance in specific cardiopulmonary bypass scenarios where cost and simplicity are paramount. Our research quantifies the revenue contribution of each type without exposing the precise figures here, but the trend indicates a gradual shift towards advanced membrane solutions as critical care protocols evolve.
Regarding clinical applications, the market serves Respiratory, Cardiac, and Extracorporeal Cardiopulmonary Resuscitation (ECPR) needs. The Cardiac application segment remains a cornerstone of demand, driven by the volume of open-heart surgeries requiring CPB. Respiratory support, particularly through ECMO, has seen sustained interest following global health challenges that strained ventilator capacities. ECPR represents a high-growth niche, albeit from a smaller base, as protocols for resuscitation improve. The interplay between these applications dictates inventory strategies for hospitals and distributors.
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each region faces distinct regulatory hurdles and reimbursement environments. For instance, the establishment of specific HCPCS codes in the US influences North American growth differently than the MS-DRG changes affect hospital budgets. Our analysis details the relative weight of these regions in the total market composition, helping stakeholders identify where to allocate sales resources or manufacturing capacity.
Strategic Recommendations for Stakeholders
Based on the preliminary findings outlined in our introduction, several strategic imperatives emerge for 2026 and beyond.
Risk Mitigation in Procurement: Given the recent class 2 recall involving a major player, hospitals and procurement officers must diversify their supplier base or demand more rigorous performance data before locking in long-term contracts. Vendors who can demonstrate consistent gas exchange rates and compliance history will gain leverage.
Reimbursement-Aligned Product Development: Manufacturers should align their R&D efforts with the reimbursement landscape. With potential reimbursement reductions for certain ECMO procedures, products that reduce overall procedure costs or improve patient turnover times may offer better value propositions. Understanding the new HCPCS codes is essential for marketing strategies in the US market.
Monitoring Regulatory Pipelines: The frequency of FDA clearances and recalls indicates a highly active regulatory environment. Companies must maintain robust vigilance systems to anticipate recalls or clearance delays that could disrupt supply chains. Keeping abreast of updates like the CMS CY 2026 Payment Policies final rule is critical for financial planning.
Focus on High-Concentration Dynamics: With over 72 percent of the market controlled by the top three firms, new entrants or smaller players need to identify underserved niches, such as pediatric-specific designs or regions with lower penetration rates, to achieve growth without directly challenging the incumbents in mature segments.
Global Expansion with Local Compliance: While North America and Europe represent significant revenue volumes, the Asia Pacific region and emerging markets offer growth potential. However, success requires navigating local regulations and aligning with regional reimbursement structures that may differ significantly from Western models.
Conclusion: The Value of Deep Intelligence
The Oxygenator Market is moving from a phase of steady expansion into a period of complex refinement driven by policy and technology. While the headline numbers project growth from 211.5 million USD in 2025 to over 312.0 million USD by 2032, the true opportunity lies in navigating the friction points created by reimbursement cuts, regulatory recalls, and technological differentiation.
General market data provides a compass, but detailed intelligence provides the map. Our comprehensive report goes beyond these summaries to offer specific revenue splits, competitive benchmarking, and scenario-based forecasts that allow your organization to model outcomes under different regulatory conditions. We dissect the exact impact of the MS-DRG changes on hospital purchasing power and evaluate how the new FDA clearances alter the competitive balance.
For decision-makers committed to securing a strategic advantage in the medtech sector, access to granular data is the difference between reactive management and proactive leadership. We invite you to explore the full Oxygenator Market research study to equip your team with the precise intelligence needed to navigate 2026 and the forecast period through 2032. The future of extracorporeal life support is being written now, and informed strategy is the key to leading it.
For detailed analysis of this topic, please visit the official page: Oxygenator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Chemotherapy Induced Peripheral Neuropathy Treatment Market Hits $1.46 Billion in 2025, Growing at 6.5% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Chemotherapy-Induced Peripheral Neuropathy Treatment Market: Navigating the 2026 Decision Landscape
The chemotherapy-induced peripheral neuropathy (CIPN) treatment market stands at a critical inflection point. As oncology regimens grow more aggressive and survival rates improve, the long-term management of treatment-related neurotoxicity has transitioned from a secondary concern to a central strategic priority for pharmaceutical companies, investors, and healthcare systems. For decision-makers operating in 2026, the window to align portfolio strategies, partnership architectures, and commercialization roadmaps with emerging clinical and regulatory realities is narrow. Our newly released market research captures this transformation in granular detail, offering a structured intelligence framework designed to convert complex clinical trajectories, competitive signals, and macroeconomic indicators into actionable business strategy.
This article provides a strategic preview of the full report. It outlines the market's foundational trajectory, examines the competitive and regulatory forces reshaping development pipelines, and demonstrates how the research equips executives with the analytical tools required to mitigate uncertainty, prioritize high-probability opportunities, and time market entry with precision.
The Market Trajectory: A Decade of Structural Growth and Strategic Timing
Historical performance and forward-looking projections establish a clear baseline for evaluating where capital, research, and commercial effort should be directed. Between 2020 and 2025, the global CIPN treatment market expanded from 1.1 billion USD to approximately 1.46 billion USD, reflecting steady adoption of symptomatic management protocols and incremental clinical validation of targeted interventions. Looking ahead, the forecast period from 2026 through 2032 outlines a market poised to reach 2.28 billion USD by the end of the projection window, supported by a compound annual growth rate of 6.5 percent.
This trajectory is not merely a function of volume expansion. It reflects deepening clinical recognition that neuropathy management directly influences treatment adherence, quality of life, and long-term oncology outcomes. As chemotherapy protocols continue to evolve toward higher efficacy and personalized dosing, the demand for reliable neuroprotective and symptomatic therapies will intensify across care settings. The research translates these macro-level movements into scenario-ready intelligence, enabling strategists to model capacity planning, investment prioritization, and partnership sequencing without relying on static assumptions. Because therapeutic adoption patterns, clinical readiness timelines, and regional care infrastructure differences create meaningful variation in how growth materializes, the full report deconstructs these dynamics across comprehensive segmentation dimensions, providing the granular reference points required for precise resource allocation.
Competitive Landscape: Innovation Clusters, Pipeline Positioning, and Strategic Differentiation
The CIPN treatment landscape is characterized by a concentrated core of established players and a highly active frontier of specialized developers pursuing distinct pharmacological approaches. Our analysis maps these participants not as isolated profiles, but as interconnected nodes within a broader innovation ecosystem, highlighting where mechanism-of-action differentiation, regulatory positioning, and clinical milestone sequencing may determine future market leadership.
At the forefront of small-molecule and peptide-based development, Dogwood Therapeutics has advanced Halneuron, a tetrodotoxin-based Nav1.7 inhibitor, through a Phase 2b program targeting CIPN. Interim data from an ongoing study involving nearly one hundred patients have reinforced confidence in the program’s therapeutic signal, with enrollment progress surpassing the halfway mark and top-line outcomes anticipated later this year. In parallel, Dogwood’s licensing arrangement with Serpin Pharma for SP16, an LRP1 agonist peptide, has unlocked a complementary pathway into neuropathy management. The SP16 program secured FDA investigational new drug clearance and is positioned to begin Phase 1b enrollment in the middle of the year, supported by a dedicated research grant that reduces early-stage funding risk. Serpin Pharma itself remains a strategically significant entity in this ecosystem, operating at the intersection of early-stage peptide innovation and asset licensing, with its SP16 program representing a clear example of how targeted molecular approaches are being de-risked through structured clinical and regulatory steps.
Beyond peptide and channel-inhibition strategies, several organizations are pursuing topical and targeted biologic approaches that reflect the market’s demand for localized, tolerability-optimized therapies. WinSanTor continues to advance WST-057, a topical pirenzepine formulation, following completed Phase 2 evaluation in CIPN. While the company’s broader clinical focus has expanded toward diabetic peripheral neuropathy, its compassionate use framework for CIPN indicates sustained commercial and clinical interest in repurposing and extending therapeutic applicability. AlgoTherapeutix, meanwhile, has generated meaningful clinical insights from its Phase 2 evaluation of topical amitriptyline, even as the organization’s near-term development cadence in this indication remains under reassessment. These programs illustrate a recurring strategic theme: topical and localized delivery modalities are attracting sustained R&D attention because they may offer differentiated safety profiles and reduced systemic burden, qualities that can be strategically valuable in supportive oncology care.
The pipeline also reflects a notable push toward preventive and mechanism-specific interventions. Asahi Kasei Pharma has initiated a Phase 3 study of ART-123, a recombinant thrombomodulin alfa formulation, specifically designed to prevent sensory neuropathy symptoms in colorectal cancer patients receiving oxaliplatin-based regimens. By targeting prevention rather than symptom management alone, the program exemplifies a broader industry shift toward upstream intervention, where success could redefine product positioning and reimbursement narratives. Simultaneously, Sironax has drawn regulatory attention for SIR2501, a SARM1 allosteric inhibitor developed for CIPN treatment, after receiving Fast Track designation from the FDA. This designation signals regulatory recognition of the unmet need and may accelerate development timelines, creating meaningful strategic implications for partnership valuation, clinical trial design, and eventual market access planning.
These developments are not isolated. They collectively illustrate a market where competitive advantage increasingly derives from differentiated mechanisms, regulatory pathway optimization, and the credibility of clinical data packages. Because detailed participant benchmarking, pipeline risk assessments, and strategic positioning matrices require structured comparison across multiple development stages and therapeutic approaches, the full report provides the analytical depth necessary to evaluate each player’s likely trajectory without relying on surface-level announcements.
Regulatory and Clinical Dynamics: Shaping the Framework for Commercial Readiness
Regulatory evolution is rapidly reshaping how CIPN therapies are developed, evaluated, and positioned for adoption. In early 2025, the FDA released draft guidance focused on the prevention and treatment of chemotherapy-induced peripheral neuropathy, outlining expectations for drug and biological product development in oncology. This guidance carries strategic significance because it introduces clearer normative reference points for endpoint selection, trial design, and clinical evidence standards. For companies operating in this space, alignment with evolving regulatory expectations can influence investigator recruitment, trial complexity, and the persuasiveness of dossiers submitted for later-stage review.
Recent regulatory milestones further reinforce the sector’s growing visibility. The FDA’s Fast Track designation for SIR2501 and the IND clearance enabling the SP16 Phase 1b trial both reflect an environment in which neuropathy-focused programs are receiving structured regulatory engagement rather than ad hoc evaluation. These events matter strategically because they affect development pacing, investor confidence, and the credibility of clinical narratives during partnership discussions. At the same time, clinical progress across multiple candidates demonstrates that the pipeline is advancing beyond exploratory interest into evidence-generating execution. Enrollment milestones, interim data readouts, and prevention-focused Phase 3 initiation collectively indicate that the field is maturing in ways that will increasingly reward disciplined trial execution and differentiated clinical positioning.
From a strategic standpoint, these dynamics create both opportunity and complexity. Companies must interpret regulatory signals in the context of shifting endpoint expectations, anticipate how prevention-oriented versus treatment-oriented programs may be valued differently by payers and providers, and assess where clinical evidence will need to be strongest to support adoption. The research report situates these regulatory and clinical developments within a wider market architecture, helping decision-makers connect policy shifts and trial milestones to commercialization timing, partnership strategy, and portfolio risk management.
What the Full Report Delivers: Operational Intelligence for 2026 Decision-Making
This research is designed to function as a working intelligence asset rather than a static market description. It provides a structured exploration of the CIPN treatment market that connects high-level growth indicators with the operational considerations leadership teams face when allocating resources, selecting partners, or preparing for market entry. The report integrates historical performance, forward-looking forecasts, segmentation analysis, competitive profiling, and regulatory context into a unified analytical framework, allowing readers to evaluate opportunities through multiple strategic lenses.
Key operational components include:
Neuropathy Pain Treatment Market
- A comprehensive market sizing and forecast structure that places current valuation in the context of a multi-year growth path, with scenario-ready projections extending through the end of the decade.
- Segment-level analysis that clarifies how therapeutic categories, application settings, and geographic demand patterns interact to shape utilization, procurement behavior, and commercialization priorities.
- Competitive and pipeline intelligence that evaluates active developers, mechanism differentiation, trial stage progression, and regulatory milestones, supporting strategic benchmarking and partnership screening.
- Regulatory and clinical development context that links guidance, designations, and trial activity to implications for trial design, evidence generation, and market access positioning.
- Strategic synthesis materials intended to help executives translate data into decisions, including considerations for portfolio alignment, partnership timing, and risk-adjusted entry strategies.
Because the value of market intelligence lies in its specificity, the full report contains the detailed breakdown, comparative analysis, and structured datasets necessary for precise planning. Readers seeking to build investment cases, evaluate licensing opportunities, or refine pipeline prioritization will find the deeper segmentation and benchmarking material essential for reducing uncertainty and improving decision quality.
Strategic Implications for 2026 and Beyond
For executives, investors, and development leaders, 2026 represents a year in which early signals must be converted into disciplined strategy. The CIPN treatment market is expanding within a supportive macroeconomic trajectory, but the real strategic challenge lies in identifying where growth will be most durable, where clinical differentiation will command premium positioning, and where regulatory and reimbursement frameworks will reward specific development approaches.
The research emphasizes several decision-critical themes. First, growth is likely to be uneven across therapeutic categories and care settings, meaning that aggregate market figures should be supplemented with segment-level insight before committing capital or forming partnership assumptions. Second, pipeline progress is becoming increasingly driven by mechanism differentiation and regulatory alignment, which suggests that competitive advantage will depend on clinical credibility as much as on commercial execution. Third, the emergence of prevention-oriented programs and localized therapy modalities indicates that future market leadership may be shaped by how well organizations anticipate shifts in treatment philosophy rather than by reacting to current prescribing patterns alone.
Organizations that integrate clinical, regulatory, and commercial intelligence into a single decision framework will be better positioned to time asset acquisitions, structure collaborations, and prepare launch strategies with greater confidence. The full report is built to support that integration by providing the breadth and depth required to evaluate the market from multiple strategic angles.
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Conclusion: Turning Market Complexity into Actionable Strategy
The chemotherapy-induced peripheral neuropathy treatment market is entering a phase where disciplined analysis can materially influence outcomes. With a clear growth trajectory, an expanding and increasingly diverse pipeline, and evolving regulatory expectations, the environment rewards organizations that approach strategy with both ambition and precision. Our latest market research is designed to meet that need by offering a structured, evidence-based view of where the market is heading and how leaders can position themselves to act decisively in 2026 and beyond.
To explore the full segmentation architecture, detailed competitive profiling, regulatory implications, and scenario-ready forecast data, access the complete report through our official research portal. The depth contained in the full publication is essential for teams seeking to convert market intelligence into executable strategy with confidence.
For detailed analysis of this topic, please visit the official page: Chemotherapy Induced Peripheral Neuropathy Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com