

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Orally Disintegrating Tablets to Reach $344.8M by 2032, 8.5% CAGR

Unlocking the Future of Patient-Centric Dosage: Strategic Insights into the Orally Disintegrating Tablet Market 2026–2032
The pharmaceutical industry is undergoing a quiet but profound transformation in how therapies are delivered. Patient adherence, ease of administration, and rapid onset of action are no longer secondary considerations; they are central pillars of modern drug development and commercial strategy. At the forefront of this shift is the orally disintegrating tablet (ODT) segment, a dosage form that bridges the gap between traditional solid oral dosage and advanced patient-centric delivery systems. As we step into 2026, decision-makers across pharmaceutical manufacturers, CDMOs, excipient suppliers, and life sciences investors require a clear, data-grounded view of where this market has been, where it is accelerating, and which structural forces will reshape competitive advantage over the next seven years.
This article introduces PW Consulting’s newly released Orally Disintegrating Tablet Market research, a comprehensive strategic briefing designed to equip executive teams with actionable intelligence for 2026 planning and beyond. Rather than offering surface-level aggregates, the study maps the interplay between historical trajectory, regulatory evolution, formulation innovation, and competitive positioning. Below, we preview the analytical framework, highlight the macro dynamics fueling growth, and outline the practical deliverables that make this research a critical asset for enterprise strategy.
Historical Trajectory and Forecast Horizon: A Resilient Growth Arc
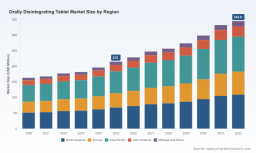
Understanding the ODT market’s momentum begins with a disciplined look at its recent performance. Between 2020 and 2025, the global market expanded from approximately 163.15 million USD to 215.0 million USD, reflecting steady adoption across therapeutic categories and sustained investment in patient-friendly formulations. This historical progression is not merely a sequence of annual increments; it reveals a structural inflection in how manufacturers approach dose design, commercialization pathways, and end-user compliance.
Looking forward, the forecast window spans 2026 through 2032, a period expected to deliver continued expansion at a compound annual growth rate of 8.5 percent. By the close of the projection horizon, market revenue is anticipated to surpass 344.8 million USD. These figures provide a macro foundation for resource allocation, capacity planning, and partnership strategy. More importantly, they signal that ODT adoption is transitioning from a niche convenience to a mainstream formulation preference, particularly where rapid disintegration, swallowing difficulty mitigation, and taste-masked delivery create measurable clinical and commercial value.
For 2026 decision-making, this growth trajectory matters because it frames the window of opportunity for first-mover advantage in emerging indications, regional commercialization, and manufacturing scale-up. Companies that align their pipeline priorities, contract manufacturing relationships, and dosing platform investments with this forecasted cadence will be better positioned to capture share as the market matures.
Segment Architecture: Where Value Is Being Created
The ODT landscape is not a monolith. Value creation is distributed across therapeutic classes, disease indications, and regional ecosystems, each carrying distinct adoption drivers, formulation challenges, and reimbursement dynamics. A 500 mg weight ceiling and a 30-second disintegration expectation, as defined in longstanding FDA guidance, remain active commercial constraints that shape formulation strategy and directly influence manufacturing feasibility.
Within drug class segmentation, the market reflects a diversified portfolio spanning central nervous system therapies, anti-epileptic treatments, and a broad category of additional indications that collectively drive volume. The distribution of revenue across these classes underscores how ODT technology has moved beyond a single therapeutic niche to become a cross-indication platform. Similarly, disease indication mapping reveals that CNS disorders represent the largest demand pool, followed by gastrointestinal conditions, cardiovascular disorders, and allergy-related formulations. This spread matters because each indication carries its own clinical urgency, prescribing patterns, and patient demographics, which in turn shape lifecycle management strategies and commercialization sequencing.
Regional dynamics further complicate the picture. North America, Europe, and Asia Pacific each present distinct pathways shaped by regulatory calendars, reimbursement architectures, manufacturing localization trends, and evolving standard-of-care expectations. Europe, for example, benefits from favorable reimbursement policies supporting chronic disease treatments, while North America remains a hub for formulation innovation and branded ODT launches. Asia Pacific reflects expanding manufacturing capacity and growing access to advanced dosage forms. Latin America and the Middle East and Africa, though smaller in relative scale, represent emerging adoption corridors where access, affordability, and supply chain flexibility increasingly determine market entry success.
Because these segmentation layers interact with pricing, bioequivalence requirements, and sourcing logic, a superficial read of regional or therapeutic shares can be misleading. The full study provides the structured comparisons necessary to identify where differentiation is genuinely achievable and where competition is likely to compress margins.
Regulatory and Operational Dynamics Shaping 2026
No ODT strategy is complete without accounting for the regulatory and operational environment that governs formulation choices, approval pathways, and commercial viability. In late 2025, the FDA revised product-specific guidance for Primidone Oral Tablet ODT and recommended product-specific guidance for Escitalopram Oxalate ODT, reinforcing standardized bioequivalence study expectations with and without water. These updates matter because they directly influence generic approval pathways, development timelines, and the design of comparative studies. For manufacturers pursuing ANDA filings or evaluating lifecycle extensions, the guidance landscape can accelerate or constrain entry strategies depending on how formulation parameters align with bioequivalence expectations.
Operational realities are equally important. Generic ODT production depends on disciplined cost control around excipients, with multi-supplier sourcing strategies increasingly viewed as essential to maintaining competitive pricing and supply continuity. Meanwhile, the broader industry continues to grapple with formulation limits, disintegration performance targets, and the need to balance patient experience with manufacturing throughput. These operational forces create a natural filter: companies that treat ODT development as a pure formulation exercise often miss the broader commercial equation involving sourcing resilience, scale-up economics, and regulatory timing.
Recent developments also highlight the pace of innovation entering the market. In 2026, Emalex Biosciences received a US patent for an ODT formulation of ecopipam and initiated process development for cGMP manufacturing targeted for late 2026 or early 2027. Such milestones illustrate how formulation IP, process readiness, and manufacturing sequencing now converge to determine commercial readiness. For competitive analysts and pipeline strategists, tracking these events provides early signals about which therapeutic categories may see new ODT entrants, where differentiation can be established, and how manufacturing bottlenecks could affect launch timing.
Competitive Landscape: Platforms, Capabilities, and Positioning
The ODT competitive field is defined by a mix of technology providers, contract manufacturers, branded product owners, and excipient specialists. Each player contributes a distinct layer to the value chain, and understanding their capabilities is essential for mapping partnership opportunities, outsourcing strategies, and competitive threats.
Catalent Pharma Solutions, based in Swindon, United Kingdom, manufactures Zydis orally disintegrating tablets with cGMP production exceeding 1.5 billion doses annually at dedicated facilities. This scale positions the company as a significant capacity and technology reference point for ODT manufacturing. Adare Pharma Solutions, headquartered in Chicago, Illinois, offers AdvaTab ODT technology designed to deliver rapid-disintegrating tablets that are bioequivalent to conventional formulations, an attribute directly relevant to regulatory navigation and product equivalence strategies.
LGM Pharma, operating in the United States, functions as a CDMO offering contract manufacturing of high-dose ODTs, including recent ANDA filings for complex formulations. Its work highlights the growing intersection between formulation complexity and contract manufacturing demand. Vitaquest, based in New Jersey, specializes in nutraceutical ODT manufacturing with custom formulations for supplements, illustrating how ODT technology extends beyond prescription pharmaceuticals into consumer health and wellness categories.
In Europe, Dec Group, based in Switzerland, manufactures ODTs using Lyopan technology in collaboration with Rohrer for rapid-disintegrating solid doses, while Roquette, located in Lestrem, France, supplies excipients and two-component platforms that simplify ODT formulation and manufacturing. These technology and material enablers demonstrate that competitive advantage increasingly depends on integrated formulation platforms rather than isolated manufacturing claims.
Otsuka Pharmaceutical, headquartered in Tokyo, Japan, continues to develop and market branded ODT products such as Abilify Discmelt and Abilify Maintena ODT, reflecting the strategic role of brand owners in shaping prescribing familiarity and patient acceptance. At the market structure level, concentration metrics indicate a moderately consolidated field: CR3 reaches 36.0 percent and CR5 reaches 48.0 percent. This distribution suggests that while leading players hold meaningful share, there remains sufficient fragmentation to support new entrants, specialized CDMOs, and niche formulation providers that can compete on speed, customization, or therapeutic focus.
The strategic implication for 2026 is clear. Companies must assess where they sit within this value chain and how they intend to compete. For CDMOs, differentiation may come from high-dose capability, bioequivalence support, or regulatory acceleration. For branded manufacturers, the priority may be lifecycle extension, patient adherence programs, and indication expansion. For excipient and technology providers, the opportunity lies in platform simplicity, supply resilience, and manufacturing compatibility. The report’s competitive analysis is designed to help each player identify the right leverage points.
Inside the Report: What Decision-Makers Will Gain
PW Consulting’s Orally Disintegrating Tablet Market study is built to translate macro trends into operational decision support. The report goes beyond headline figures to provide a structured, cross-referenced view of market size, growth drivers, segmentation logic, regulatory touchpoints, and competitive positioning. It is designed for teams that need to align commercial planning, R&D prioritization, manufacturing strategy, and investment decisions with a consistent evidence base.
Key components of the research include a detailed market size and forecast framework spanning the base year through the 2032 projection period, with historical context that clarifies the pace and composition of growth. The segmentation analysis maps demand across drug classes and disease indications while preserving enough analytical discipline to avoid oversimplified conclusions. Regional perspectives are integrated to show how reimbursement, access, and manufacturing localization affect adoption paths without reducing the discussion to static share tables.
The report also provides a competitive profiling section that situates major players within the value chain, highlighting technology platforms, manufacturing scale, formulation strengths, and strategic orientation. Recent developments are incorporated to connect market structure with live industry events, including patent activity, guidance updates, and manufacturing timelines that can alter near-term competition. In addition, the study addresses operational considerations such as excipient sourcing, weight and disintegration constraints, and the practical implications of bioequivalence study expectations.
For executive teams, these elements combine into a practical toolkit. Commercial leaders can use the forecast framework to test demand scenarios and prioritize indication expansion. R&D and formulation teams can reference the regulatory and technical discussion to anticipate development constraints and align platform decisions with approval pathways. Procurement and supply chain stakeholders can evaluate sourcing logic and capacity considerations in the context of cost control and flexibility. Investors and strategy teams can use the competitive and concentration analysis to assess where consolidation pressure is likely to intensify and where specialized capabilities may command premium positioning.
Strategic Takeaways for 2026 Planning
As 2026 unfolds, the ODT market offers a clear example of how patient-centric formulation strategy can translate into durable commercial relevance. Several themes should anchor enterprise planning.
- Growth is structural, not cyclical. The combination of historical momentum and an 8.5 percent CAGR through 2032 suggests that ODT adoption will continue to expand across multiple therapeutic and patient-access contexts, making formulation flexibility a long-term asset rather than a short-term tactic.
- Regulatory clarity shapes speed. Recent FDA guidance revisions and product-specific recommendations influence bioequivalence design, generic pathways, and development sequencing. Teams that integrate regulatory trajectory into early formulation decisions can reduce downstream rework and accelerate commercialization readiness.
- Operational discipline determines margin resilience. With formulation weight limits, disintegration targets, and excipient sourcing requirements in play, competitive advantage increasingly depends on manufacturing efficiency, supplier flexibility, and cost-aware design.
- Platform capability outweighs one-off scale. The presence of multiple technology providers, CDMOs, and excipient specialists indicates that integrated formulation platforms and process readiness are becoming central to differentiation, especially for complex or high-dose products.
- Concentration leaves room for targeted positioning. With a moderately consolidated market structure, there is meaningful space for specialized players that can serve specific indications, formulation challenges, or regional access needs without attempting to compete solely on scale.
These themes point toward a practical conclusion: the organizations that will capture the most value in the ODT market are those that treat dosage form strategy as a multi-dimensional business decision, connecting clinical need, regulatory risk, manufacturing feasibility, and competitive positioning into a single coherent plan.
Conclusion: From Market Intelligence to Actionable Strategy
The Orally Disintegrating Tablet Market is entering a phase where informed strategic choices will separate scalable growth from marginal participation. Themacro trajectory, segmentation diversity, regulatory dynamics, and competitive structure described in this preview reflect a market that is both expanding and maturing. That combination creates opportunity, but only for teams equipped with detailed, current, and operationally relevant intelligence.
PW Consulting’s full market research is designed to provide that level of clarity. It translates broad growth signals into segment-level logic, regulatory context, competitive mapping, and development-ready insight, enabling decision-makers to move from awareness to action with confidence. For organizations planning 2026 pipeline prioritization, manufacturing partnerships, regional expansion, or competitive responses, the complete study offers the depth required to support decisive strategy.
To access the full forecast framework, segmentation analysis, competitive profiles, and operational insights, request the complete Orally Disintegrating Tablet Market report and integrate its findings directly into your 2026 strategic planning process.
Orally Disintegrating Tablet Market
Worldwide Oral Solid Dosage Medicine Market
For detailed analysis of this topic, please visit the official page: Orally Disintegrating Tablet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com