

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Chlorogenic Acid Market Hits $215M in 2025, Projects 5.69% CAGR to 2032

Chlorogenic Acid Market 2026–2032: Strategic Intelligence for Formulation, Procurement, and Competitive Positioning
Why This Study Matters in the 2026 Decision Cycle
The chlorogenic acid market enters the 2026–2032 forecast window at a structural inflection point. After a decade of steady value accumulation, total market revenue reached an estimated USD 215.0 Million in 2025, extending a clear upward trajectory from USD 163.06 Million in 2020. The forward view projects a compound annual growth rate of 5.69 percent, translating the base-year position into an anticipated USD 226.87 Million in 2026 and a long-term valuation pathway that approaches USD 316.72 Million by 2032. These headline figures do more than chart volume; they signal a market that has graduated from niche botanical ingredient to a strategically contested category across nutraceuticals, functional beverages, cosmetics, and pharmaceuticals. For senior teams calibrating sourcing commitments, formulation roadmaps, or go-to-market timing, the 2026 environment demands a refined reading of supply-side leverage, regulatory direction, and competitive clustering—precisely the intelligence architecture built into this report.
A strategic reading of this growth curve must also account for concentration dynamics. The category is shaped by a moderately consolidated supplier base, where the top three players command an estimated 52.5 percent of revenue and the top five reach 60.0 percent. That concentration pattern matters because it compresses negotiation windows, amplifies the impact of capacity moves by leading firms, and determines which buyers can secure priority allocation during periods of raw-material stress. The full study unpacks how these concentration bands interact with regional sourcing patterns, type-level supply positioning, and application-level demand pull, but the core message for 2026 planners is straightforward: advantage in this market increasingly flows from the ability to map supplier leverage, not simply to track category growth.
Structural Forces Shaping the 2026–2032 Trajectory
Several converging dynamics are re-grading the risk-return profile of chlorogenic acid sourcing and product development. On the raw-material side, the category remains structurally tethered to global coffee and botanical supply chains. In 2024, global coffee production exceeded 11 million tons, with roughly 8 million tons traded internationally and Brazil and Vietnam accounting for nearly half of output. That concentration creates persistent exposure to weather variability, logistics friction, and regional policy shifts—variables that cascade directly into chlorogenic acid cost structures and availability. At the same time, the botanical component of the value chain extends beyond coffee beans into honeysuckle and eucommia-based pathways, which broadens the category’s raw-material mosaic but also introduces additional quality and traceability considerations.
Regulatory and trade signals add a second layer of strategic complexity. In specific food products such as coffee substitutes, the European Commission has implemented regulation setting chlorogenic acid limits below 100 mg/L, placing formulation ceilings on certain applications and nudging innovation toward compliant concentration strategies. In contrast, the FDA has recorded chlorogenic acid as a dietary substance with no specific quantity restrictions identified in its latest database, sustaining a comparatively permissive environment for dietary supplement and functional food development in the United States. Layered onto that divergence is a trade environment that continues to shift: in 2026, green coffee tariffs in the United States are being rolled back following reciprocal tariff adjustments, influencing import expenditures and altering the cost calculus for key producing regions. These are not peripheral details; they are the kinds of boundary conditions that determine whether a 2026 launch plan scales smoothly or encounters compliance and cost friction downstream.
Chlorogenic Acid Market
Where Demand Is Concentrating: Applications, Types, and Regional Pull
The demand architecture of the chlorogenic acid category is diversifying in ways that reward formulation teams willing to look beyond single-use assumptions. Nutraceutical applications continue to anchor a substantial share of value, reflecting sustained interest in metabolic health, antioxidant positioning, and functional wellness portfolios. Food and beverage applications represent a robust second engine, driven by the pursuit of clean-label functionality and the integration of bioactive ingredients into everyday consumption occasions. Cosmetics and personal care contribute a meaningful demand layer as well, leveraging chlorogenic acid’s relevance to skin-care efficacy narratives and premium botanical positioning. Pharmaceutical applications, while smaller in relative scale, carry outsized strategic importance because they demand higher purity standards, clinical-grade documentation, and API-grade consistency.
Ferulic Acid Market
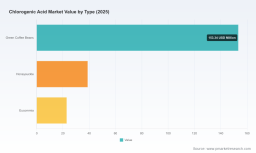
On the supply composition side, green coffee beans remain the dominant type-level source for chlorogenic acid extraction, reinforcing the category’s continued dependence on coffee-sector dynamics. Honeysuckle and eucommia-based pathways further diversify the type landscape, enabling brand owners and ingredient suppliers to differentiate on botanical origin, extraction profile, and compliance story. Regionally, the market’s footprint is distributed across a broad set of demand centers rather than consolidated in a single geography, which means that procurement strategies must account for differing logistics costs, regulatory expectations, and supplier proximity advantages. The study provides a detailed map of how these type- and region-level structures interact with application-specific buying behavior, including where formulation needs are tilting toward standardized extracts, where cosmetic-grade consistency is becoming a gating requirement, and where pharmaceutical-adjacent documentation is reshaping supplier qualification.
Competitive Landscape: Concentration, Capability, and Recent Moves
The competitive field in chlorogenic acid is defined by a blend of global botanical extract specialists, science-backed API-oriented manufacturers, and high-volume producers with expanding international reach. Naturex, operating under Givaudan and headquartered in Avignon, France, continues to emphasize standardized green coffee bean extracts rich in chlorogenic acid for nutraceutical, functional beverage, and cosmetic applications, with a stated emphasis on traceability and quality compliance. Its recent operational moves illustrate how leading players are trying to harden supply resilience while simultaneously opening new formulation doors. In March 2024, Naturex expanded its Ecuador and Vietnam raw-material hubs to tighten supply security and traceability. In June 2023, it launched PureBrew Bioactives with high CGA concentration to accelerate beverage flavor solutions. For procurement and R&D teams, these moves are signals: they indicate where supply assurance is being invested and where beverage-oriented application development is being actively scored.
Applied Food Sciences, based in Austin, Texas, takes a more brand-and-formulation-centric stance, focusing on branded green coffee bean extracts with defined chlorogenic acid content for dietary supplements, weight-management, and metabolic health formulations. EUROMED SA, headquartered in Barcelona, Spain, positions around high-purity botanical extracts including chlorogenic acid-rich plant extracts for pharmaceutical APIs, dietary supplements, and clinical-grade nutraceutical formulations—an orientation that matters wherever purity and documentation form the basis of supplier selection. Sabinsa Corporation, in New Jersey, continues to advance science-backed herbal and botanical APIs including chlorogenic acid extracts with clinical validation for pharmaceutical, nutraceutical, and preventive healthcare products, reinforcing the category’s credibility thread in evidence-led markets.
On the high-volume production side, several China-based manufacturers have built substantial export-oriented footprints. Zhejiang Skyherb supplies green coffee bean and honeysuckle-based HPLC 98 percent chlorogenic acid extracts to over 45 countries. Nutragreen Biotechnology similarly focuses on green coffee bean and honeysuckle-based HPLC 98 percent extracts, with an estimated 13 percent global market share. Chenguang Biotech has developed a portfolio of 37 chlorogenic acid product variants, holds an estimated 11 percent global market share, and supplies markets across more than 45 countries. Changsha E.K. HERB focuses on natural ingredients including chlorogenic acid extracts for nutraceutical and functional food applications, while Nanjing Zelang extends into medical technology and botanical extracts including chlorogenic acid for pharmaceutical and supplement uses. Cymbio Pharma, based in India, rounds out the competitive picture with a focus on herbal and botanical APIs including chlorogenic acid extracts for pharmaceutical and nutraceutical markets.
Together, these profiles highlight a competitive environment in which differentiation is being built on extraction purity, botanical origin, traceability, clinical or regulatory substantiation, and geographic supply reach. The report examines how these company-level strategies map onto the broader concentration pattern and where their combined movements are likely to influence pricing power, supply security, and formulation availability across the forecast period.
What the Report Delivers: Operational Intelligence for 2026 Planning
This market research is designed as a decision tool rather than a purely descriptive overview. It integrates historical performance from 2020 through 2025 with a forecast window spanning 2026 to 2032, anchored in a base-year valuation of USD 215.0 Million and projected toward long-range market sizing in the vicinity of USD 316.72 Million by 2032. The study organizes that trajectory around the segmentation dimensions most relevant to formulation, procurement, and market-entry planning: regional demand distribution, type-level supply positioning across green coffee beans, honeysuckle, and eucommia, and application-level behavior across nutraceuticals, food and beverage, cosmetics and personal care, and pharmaceuticals.
Beyond the macro sizing, the report advances practical analysis in several areas that directly affect 2026 execution. It examines how concentration patterns shape bargaining dynamics and allocation risk, where supplier expansion and product launches are altering capability ceilings, and how regulatory divergence across key markets is reshaping formulation boundaries and documentation requirements. It also situates the category within wider raw-material and trade currents, including the structural dependence on coffee-sector output, the impact of evolving tariff and import-expenditure conditions, and the implications of regulatory limits in certain food applications. The objective is to help teams answer operational questions with greater precision: where demand is deepening versus broadening, which supply routes are becoming more resilient or more exposed, and which competitive capabilities are likely to set the pace for category standards over the next several years.
To keep the analysis usable for cross-functional teams, the study translates market structure into strategic implications. For procurement leaders, it clarifies where supplier concentration and capacity activity are most likely to affect availability and negotiation leverage. For R&D and brand teams, it connects application trends and regulatory signals to formulation choices and launch timing. For competitive-intelligence functions, it maps the major players’ orientations and recent moves against the concentration and segmentation landscape, enabling more informed benchmarking and scenario planning.
How to Use This Intelligence Before the 2026 Cycle Closes
The chlorogenic acid market is not simply expanding; it is reconfiguring around purity expectations, regulatory interpretation, botanical sourcing strategy, and supplier concentration. The headline growth path—moving from a 2025 base of USD 215.0 Million toward a multi-year trajectory above USD 300 Million—masks a more important story for operators: the same market that rewards scale and consistency also punishes undifferentiated sourcing in a landscape where traceability, compliance, and application-specific quality are increasingly decisive. The strategic winners in 2026 will be those who can pair demand insight with supply-side realism, using concentration data, type-level positioning, and competitive capability mapping to reduce uncertainty rather than simply track it.
This report provides the framework for that kind of decision-making, but the full segmentation detail, regional demand mapping, type-level value distribution, application-level breakdowns, and company-specific strategic positioning are presented in depth only in the complete study. For teams that need the underlying numbers, scenario-ready segmentation, and the analytical logic behind supplier and regulatory implications, the complete market intelligence is available through the PW Consulting research portal. Accessing the full report will allow your team to move from directional confidence to execution-ready precision before the 2026 planning cycle advances further.
For detailed analysis of this topic, please visit the official page: Chlorogenic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com