

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Home Appliances Market to Reach $1.495B by 2032, Growing at 6.98% CAGR

Strategic Imperatives in a Reshaped Appliance Landscape: Why the 2026 Decision-Maker Needs Granular Intelligence
The global home appliances sector has entered a phase of structural transformation that renders traditional top-down planning inadequate for 2026 and beyond. Between 2020 and 2025, the industry navigated post-pandemic demand normalization, shifting urbanization patterns, and an accelerating wave of product digitization, emerging at a valuation exceeding nine hundred and thirty-eight million USD in our base year. More critically, the forward trajectory through 2032 points toward sustained expansion, with the broader market on pace to approach one trillion four hundred ninety-five million USD over the full forecast horizon. For executives, procurement leaders, and capital allocators, the operative challenge is no longer directional awareness but precise, scenario-ready intelligence. Our newly released Home Appliances Market research study delivers exactly that: a decision-grade framework engineered to translate macro momentum into executable strategy.
This article serves as a professional preview of the full publication. It establishes the analytical rigor, structural depth, and competitive granularity embedded in the report while intentionally reserving the most actionable segmented data for the complete intelligence package. Executives who require regional allocation models, application-specific demand curves, product-tier growth differentials, and firm-level positioning matrices will find those deliverables fully articulated in the source document. The objective here is to demonstrate the methodology, highlight the strategic architecture, and clarify what the study enables once the complete dataset is in hand.
The Macro Backbone: Momentum, Baselines, and the 2026 Inflection Point
Any credible strategic assessment begins with disciplined historical grounding. The sector's performance across the 2020 to 2025 evaluation window reflects a market that has absorbed volatility and re-emerged with clearer structural signals. Post-recovery consumption patterns have stabilized, replacement cycles are recalibrating around both durability expectations and technology upsell potential, and supply-side realignment continues to reshape cost architectures. By our base-year measurement in 2025, total industry revenue stood at approximately nine hundred thirty-eight point five million USD, establishing a robust foundation for the forward outlook.
The projected expansion through the 2026 to 2032 forecast period suggests a compound annual growth rate of 6.98 percent, a trajectory that carries meaningful implications for capacity planning, geographic prioritization, and innovation investment. The 2026 baseline itself approaches nine hundred seventy-nine million USD, confirming that the current operating year represents an inflection point rather than a transitional pause. Decision-makers who rely on fragmented secondary sources or backward-looking vendor narratives risk misjudging the pace and composition of this growth. Our research addresses that exposure by constructing a continuous series across historical and forecast intervals, enabling internal planners to benchmark sensitivity, test reorder-point assumptions, and align product roadmap timing with realistic market absorption curves.
Crucially, the report does not treat the headline trajectory as an end in itself. Instead, it uses the macro series as a scaffolding for layered decomposition. Growth is not uniform across product architectures, usage contexts, or geographic demand pools, and the strategic value of the study lies in its capacity to isolate where momentum concentrates and where headwinds intensify. The full publication unpacks those differentials in detail; what follows here is a structural overview of how the analysis is organized and why that organization matters for 2026 decision-making.
What the Study Delivers: An Operational Blueprint for Commercial and Capital Decisions
The Home Appliances Market research was designed for practitioners who need more than trend commentary. It integrates quantitative modeling, competitive intelligence, and regulatory context into a single analytical environment. The report's architecture reflects the actual workflow of strategic planning teams, from portfolio review and channel strategy to market-entry assessment and risk calibration.
Comprehensive Historical and Forecast Modeling
At its foundation, the study provides a continuous time series that connects the 2020 to 2025 historical record with the 2026 to 2032 forecast horizon. This continuity allows organizations to test demand scenarios against a consistent methodological baseline rather than reconciling disconnected estimates. The modeling framework supports internal forecasting reconciliation, making it possible to compare internal sales projections, capacity plans, and inventory targets against independently validated market trajectories. For capital-intensive planning cycles, that alignment reduces the probability of overcommitting to segments that are structurally decelerating while underallocating to faster-absorbing demand pools.
Multi-Dimensional Segmentation Architecture
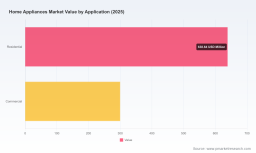
The analysis decomposes the market across product configurations, usage contexts, and regional demand environments. Rather than presenting these as isolated tables, the report ties each segmentation axis to demand drivers, adoption constraints, and competitive accessibility. Decision-makers can use this structure to assess where portfolio exposure is concentrated, where substitution risk is emerging, and which segments offer the most defensible growth under varying macroeconomic assumptions. The complete publication contains the full segmentation reconciliation, including the granular splits that inform market-share arithmetic, pricing strategy, and channel allocation. Those details are reserved for the full report so that subscribing organizations can operationalize them without dilution or retrofitting.
Competitive Intelligence and Firm-Level Context
Strategic positioning cannot be inferred from aggregate sizing alone. The study profiles the organizations actively shaping market direction, tracking their product philosophies, geographic footprints, and recent strategic moves. Coverage spans established multinational incumbents and high-velocity manufacturers whose combined activity sets the pace for innovation cycles, pricing expectations, and distribution leverage. The competitive section does not merely catalog corporate summaries; it connects recent product introductions, partnership activity, and manufacturing investments to the broader dynamics that will influence competitive accessibility in 2026 and beyond.
Regulatory and Risk Contextualization
Market outcomes are increasingly mediated by policy mechanics and safety governance. The report embeds current regulatory developments into the strategic discussion so that planning teams can evaluate exposure before it becomes a financial event. Recent policy actions around trade and materials costs have introduced meaningful uncertainty into appliance production economics and downstream pricing. In April 2026, strengthened Section 232 tariffs on steel and aluminum imports expanded derivative coverage to include certain non-electric domestic cooking appliances, stoves, ranges, and washing machines, with duty structures reaching as high as fifty percent on full value or twenty-five percent on derivative content. That adjustment builds on the Department of Commerce's earlier inclusions process from April 2025, which had already broadened the program to additional derivative articles such as portable non-electric domestic cooking appliances and plate warmers. For manufacturers, importers, and channel operators, these shifts alter landed-cost calculations, sourcing flexibility, and competitive dynamics between domestically produced and imported lines.
Treatment is also given to product safety governance, which directly affects brand risk, recall exposure, and consumer trust. As of June 2026, the Consumer Product Safety Commission issued warnings tied to recalls of Vornado Air SRTH Small Room Tower Heaters due to fire hazard concerns, alongside multiple steam cleaners and hair dryers flagged for electrocution or burn risks. In parallel, USITC analysis has examined how Section 232 steel and aluminum tariffs may affect household appliance production, trade volumes, and pricing through reduced import volumes and increased domestic costs. The study integrates these threads into its dynamics assessment so that organizations can weigh compliance, sourcing, and product-safety strategy as part of the same planning environment.
Competitor Momentum and the 2026 Strategic Chessboard
The competitive landscape is defined by organizations that are simultaneously defending mature positions and pursuing targeted expansion through product innovation, geographic partnerships, and manufacturing investment. The report's competitor module tracks these moves as strategic signals rather than isolated press events, enabling readers to interpret how individual actions reshape addressable opportunity and competitive pressure.
Among the firms profiled are Whirlpool Corporation, headquartered in Benton Charter Township, Michigan, with a portfolio spanning major home appliances under recognized brands such as Whirlpool, KitchenAid, and Maytag. AB Electrolux, based in Stockholm, produces major home appliances including refrigerators, washing machines, dishwashers, and ovens. Haier Smart Home Co., Ltd., operating from Qingdao in Shandong, China, manufactures a wide range of major and small home appliances, including refrigerators, washing machines, and air conditioners. Midea Group, headquartered in Foshan, Guangdong, produces major home appliances including refrigerators, washing machines, and kitchen appliances. BSH Home Appliances Corporation, based in Irvine, California, offers premium major home appliances under the Bosch, Siemens, and Thermador brands, covering refrigerators, ovens, and laundry products. LG Electronics Inc., from Seoul, South Korea, develops and manufactures major home appliances including refrigerators, washing machines, and air conditioners. Samsung Electronics Co., Ltd., based in Suwon, South Korea, manufactures major home appliances such as refrigerators, washing machines, and dishwashers. Panasonic Corporation of North America, located in Secaucus, New Jersey, provides major home appliances including refrigerators, washing machines, and kitchen appliances. Gree Electric Appliances Inc., headquartered in Zhuhai, Guangdong, produces major home appliances like air conditioners, refrigerators, and washing machines.
Recent activity among these players illustrates the operating tempo the market now demands. In January 2026, BSH Home Appliances Corporation launched Bosch Cook AI for personalized kitchen guidance within the Home Connect app and introduced new Bosch Unlimited 9 and 10 Premium Cordless Stick Vacuums with MicroClean technology for North America. In March 2026, GE Appliances launched the FirstBuild Sourdough Sidekick collaboration with King Arthur Baking Company, now available nationwide for improved sourdough baking. That same company had previously announced, in August 2025, more than three billion USD in investment over five years to expand U.S. manufacturing, including new models of two-ton Vertical Zoneline air conditioners and demand-response electric water heaters. In April 2026, Electrolux Group formed a strategic partnership with Midea Group to accelerate growth and innovation in North America. Each move signals a different facet of competitive adaptation: connected-product differentiation, specialized use-case productization, domestic capacity expansion, and cross-border partnership for regional acceleration.
The report connects these developments to the market's structural realities, including the concentration dynamics observed across the industry. Current concentration metrics indicate that the top three firms account for approximately 48.5 percent of market share, while the top five reach roughly 62.3 percent. That degree of concentration has direct implications for pricing power, channel negotiation, and the feasibility of disruptive entry. Organizations evaluating partnership opportunities, acquisition targets, or defensive positioning can use the full study's competitive framework to assess where structural leverage resides and where smaller players can still carve out differentiated roles through niche specialization, service models, or regional focus.
Worldwide Domestic Appliances Market
Why This Research Matters More in 2026 Than in Prior Cycles
The intersection of sustained demand growth, product-category evolution, competitive intensification, and policy-driven cost pressure makes 2026 a year in which decision quality is especially consequential. Forecast accuracy, portfolio alignment, and risk anticipation now depend on intelligence that is both broad enough to capture systemic momentum and granular enough to support segment-level action. Generalized market narratives cannot provide that. They tend to obscure the compositional differences that determine whether a strategy scales or stalls.
The Home Appliances Market study was built to close that gap. It gives executives a unified view of where the market has been, where it is headed, and how competitive and regulatory forces are reshaping the options available to firms operating within it. The full publication contains the complete segmentation breakdown, the detailed forecast intervals, and the comprehensive competitive mappings that planning teams need to build budgets, set targets, and stress-test assumptions. Those assets are presented in a format intended for direct use in internal reviews, investment committees, and strategic planning cycles.
Home Appliances Market
For leaders who must act on the current market environment rather than react to it, the value of the report lies in its readiness for application. It is not a retrospective commentary but a forward-oriented decision tool. The macro trajectory establishes confidence in the scale of the opportunity; the segmentation architecture reveals where that opportunity is concentrated; the competitive intelligence shows who is positioning to capture it; and the regulatory and safety context highlights where risk must be actively managed. Together, these layers form the basis for informed 2026 strategy.
Next Step: Accessing the Complete Intelligence Package
This preview demonstrates the analytical depth and strategic relevance of the Home Appliances Market research, but the most actionable content resides in the full report. Detailed regional demand environments, application-specific deployment patterns, product-tier growth differentials, segmentation reconciliations, and complete competitive profiles are available in the complete publication. Organizations that require the precise figures and structural breakdowns needed for allocation modeling, market-entry evaluation, and competitive benchmarking are encouraged to access the source webpage and retrieve the complete dataset. For 2026 planning, the difference between directional awareness and decision-ready intelligence is not abstract; it is the difference between a strategy that can withstand scrutiny and one that cannot. The full report is designed to provide exactly that standard.
For detailed analysis of this topic, please visit the official page: Home Appliances Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com