

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Oxygenator Market Hits $211.5M in 2025, Projects 5.8% CAGR to 2032

Strategic Breathing Room: Navigating the Oxygenator Market Amidst 2026 Regulatory and Reimbursement Shifts
The global medical device landscape is witnessing a critical juncture in extracorporeal life support technologies. As healthcare systems grapple with evolving reimbursement codes, regulatory scrutiny, and increasing demand for advanced cardiopulmonary solutions, the Oxygenator Market stands at the forefront of strategic investment decisions. Our latest comprehensive market research report provides a definitive roadmap for stakeholders aiming to capitalize on the projected growth trajectory through 2032.
For executives and investors operating in the medtech sector, understanding the nuances of this market is no longer optional—it is imperative. The period from 2026 to 2032 represents a transformative era where technological innovation intersects with complex policy changes. This article serves as a strategic overview, highlighting the macro-economic drivers and competitive dynamics while outlining the depth of intelligence available in our full proprietary study.
Market Trajectory and Macro-Economic Fundamentals
The Oxygenator Market has demonstrated resilience and steady expansion over the past half-decade. Historical data from 2020 through 2025 indicates a consistent upward trend in revenue generation, reflecting the essential nature of oxygenation technologies in critical care and surgical settings. In 2020, the market valuation stood at 165.5 million USD, a figure that has climbed year-over-year to reach 211.5 million USD in 2025. This growth underscores the increasing reliance on extracorporeal membrane oxygenation (ECMO) and cardiopulmonary bypass (CPB) procedures globally.
Looking forward, the forecast period from 2026 to 2032 suggests continued momentum. The market is projected to surpass the 220 million USD mark in 2026, escalating towards 312.0 million USD by 2032. This expansion is supported by a Compound Annual Growth Rate (CAGR) of 5.8 percent. Such a rate indicates a mature yet healthy growth environment, driven by epidemiological shifts, aging populations, and advancements in membrane technology that enhance biocompatibility and gas exchange efficiency.
However, raw growth figures only tell part of the story. The strategic value for decision-makers lies in understanding the velocity of this growth relative to specific regulatory timelines and reimbursement landscapes that are shifting dramatically in 2026. Our report isolates these variables to provide a nuanced forecast that goes beyond simple linear extrapolation.
The 2026 Decision Matrix: Reimbursement and Regulation
The year 2026 is poised to be a watershed moment for market dynamics, primarily due to significant adjustments in how procedures involving oxygenators are reimbursed and regulated. Strategic planning for the upcoming fiscal years must account for the complex interplay between CMS payment policies and FDA regulatory actions.
Reimbursement Landscape Changes
Effective April 1, 2026, the Healthcare Common Procedure Coding System (HCPCS) established code Q0238 for TYENNE® ECMO treatment under the Medicare Hospital Outpatient Prospective Payment System. This inclusion signals a broader acceptance and categorization of ECMO therapies within outpatient frameworks, potentially influencing hospital procurement decisions. Conversely, the CMS implemented MS-DRG assignment changes for ECMO procedures effective for Calendar Year 2026. Industry analysis suggests these changes could reduce hospital reimbursement by 40 to 80 percent for peripheral VA and VV ECMO procedures.
Oxygenator Market
Worldwide Oxygen Regulator Market
Furthermore, the Medicare Program CY 2026 Payment Policies final rule updated payment rates for inpatient and outpatient procedures involving oxygenators in ECMO and CPB settings, as finalized in November 2025. These financial pressures may drive hospitals to seek more cost-effective oxygenation solutions or consolidate purchasing around vendors who can demonstrate superior outcomes relative to cost.
Regulatory Scrutiny and Clearances
Regulatory oversight remains intense. In November 2025, the FDA issued a Class 2 recall for Medtronic Affinity NT Oxygenator units due to performance issues with CO2 gas transfer rates. This event highlights the critical importance of quality assurance and supply chain reliability in vendor selection processes. Simultaneously, the regulatory pathway continues to accommodate innovation. Sorin Group Italia S.r.l. received FDA 510(k) clearance for the Inspire 8F oxygenator integrated with a hard-shell reservoir for cardiopulmonary bypass in November 2025. More recently, in February 2026, Lifemotion Medical Technology Co., Ltd. received FDA 510(k) clearance for their Disposable Membrane Oxygenator under K253838.
These contrasting events—recalls versus clearances—create a dynamic environment where risk assessment and compliance verification become central to procurement strategies. Our report analyzes how these regulatory signals impact market share distribution and product lifecycle management.
Competitive Landscape: Leadership and Innovation
The Oxygenator Market exhibits a high degree of concentration, which presents both barriers to entry and stability for established players. The concentration ratio for the top three competitors (CR3) is 72.5 percent, while the top five competitors account for 82.0 percent of the market. This oligopolistic structure suggests that strategic partnerships or acquisitions may be necessary for new entrants seeking significant market share, while incumbents must defend their positions through continuous innovation and regulatory compliance.
Key industry players are pursuing distinct technological pathways to differentiate their offerings. Sorin Group Italia S.r.l., based in Mirandola, Italy, focuses on the Inspire series hollow fiber oxygenators for cardiopulmonary bypass and EOS ECMO oxygenators with plasma-tight membrane technology for long-term support. Their recent FDA clearance reinforces their position in the US hospital markets.
Terumo Cardiovascular Systems, headquartered in Ann Arbor, Michigan, USA, manufactures hollow-fiber membrane oxygenators such as the Capiox FX series. Their strategy emphasizes internal fiber production to ensure superior gas exchange and biocompatibility in CPB and ECMO circuits. Medtronic, Inc., from Minneapolis, Minnesota, provides the Nautilus and Affinity NT oxygenators with Balance Biosurface for ECMO and cardiopulmonary bypass applications, though recent recall events necessitate a deeper analysis of their risk mitigation strategies.
European and Asian manufacturers are also carving out significant niches. Eurosets S.r.l. in Medolla, Italy, specializes in ECMO and pediatric newborn oxygenators with integrated designs for extracorporeal life support. Spectrum Medical S.R.L. in Italy develops the Quantum Perfusion blood oxygenator using laminated membrane construction for reduced priming volume and pressure drop. In Asia, MicroPort Kewei Medical Instrument Co., Ltd. in Dongguan, China, produces the Vitasprings Spiral Diversion Integrated Membrane Oxygenator with advanced hydrodynamic design. Lifemotion Medical Technology Co., Ltd. in China manufactures disposable membrane oxygenators for cardiopulmonary bypass surgery, having recently secured FDA clearance. Additionally, Chalice Medical Ltd. in the United Kingdom offers the CMO8 adult PMP oxygenator and Paragon series for ECMO and extracorporeal bypass, maintaining ISO 13485 and FDA 510(k) compliance.
Our full report provides a granular evaluation of these companies, including their strategic moves, R&D pipelines, and vulnerability to regulatory shifts. Understanding the specific technological advantages—such as plasma-tight membranes versus hollow fiber designs—is crucial for predicting future market share reallocation.
Segmentation Insights: Technology and Application Drivers
While overall market size is important, the divergence in performance across different segments offers the most actionable intelligence for product managers and investors. The market is broadly categorized by technology type and clinical application, each facing unique adoption drivers.
In terms of technology, the market is divided primarily between Bubble Oxygenators and Membrane Oxygenators. Membrane technology has gained significant traction due to improved biocompatibility and reduced risk of complications during long-term support, such as ECMO. However, Bubble Oxygenators maintain relevance in specific cardiopulmonary bypass scenarios where cost and simplicity are paramount. Our research quantifies the revenue contribution of each type without exposing the precise figures here, but the trend indicates a gradual shift towards advanced membrane solutions as critical care protocols evolve.
Regarding clinical applications, the market serves Respiratory, Cardiac, and Extracorporeal Cardiopulmonary Resuscitation (ECPR) needs. The Cardiac application segment remains a cornerstone of demand, driven by the volume of open-heart surgeries requiring CPB. Respiratory support, particularly through ECMO, has seen sustained interest following global health challenges that strained ventilator capacities. ECPR represents a high-growth niche, albeit from a smaller base, as protocols for resuscitation improve. The interplay between these applications dictates inventory strategies for hospitals and distributors.
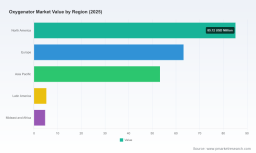
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each region faces distinct regulatory hurdles and reimbursement environments. For instance, the establishment of specific HCPCS codes in the US influences North American growth differently than the MS-DRG changes affect hospital budgets. Our analysis details the relative weight of these regions in the total market composition, helping stakeholders identify where to allocate sales resources or manufacturing capacity.
Strategic Recommendations for Stakeholders
Based on the preliminary findings outlined in our introduction, several strategic imperatives emerge for 2026 and beyond.
Risk Mitigation in Procurement: Given the recent class 2 recall involving a major player, hospitals and procurement officers must diversify their supplier base or demand more rigorous performance data before locking in long-term contracts. Vendors who can demonstrate consistent gas exchange rates and compliance history will gain leverage.
Reimbursement-Aligned Product Development: Manufacturers should align their R&D efforts with the reimbursement landscape. With potential reimbursement reductions for certain ECMO procedures, products that reduce overall procedure costs or improve patient turnover times may offer better value propositions. Understanding the new HCPCS codes is essential for marketing strategies in the US market.
Monitoring Regulatory Pipelines: The frequency of FDA clearances and recalls indicates a highly active regulatory environment. Companies must maintain robust vigilance systems to anticipate recalls or clearance delays that could disrupt supply chains. Keeping abreast of updates like the CMS CY 2026 Payment Policies final rule is critical for financial planning.
Focus on High-Concentration Dynamics: With over 72 percent of the market controlled by the top three firms, new entrants or smaller players need to identify underserved niches, such as pediatric-specific designs or regions with lower penetration rates, to achieve growth without directly challenging the incumbents in mature segments.
Global Expansion with Local Compliance: While North America and Europe represent significant revenue volumes, the Asia Pacific region and emerging markets offer growth potential. However, success requires navigating local regulations and aligning with regional reimbursement structures that may differ significantly from Western models.
Conclusion: The Value of Deep Intelligence
The Oxygenator Market is moving from a phase of steady expansion into a period of complex refinement driven by policy and technology. While the headline numbers project growth from 211.5 million USD in 2025 to over 312.0 million USD by 2032, the true opportunity lies in navigating the friction points created by reimbursement cuts, regulatory recalls, and technological differentiation.
General market data provides a compass, but detailed intelligence provides the map. Our comprehensive report goes beyond these summaries to offer specific revenue splits, competitive benchmarking, and scenario-based forecasts that allow your organization to model outcomes under different regulatory conditions. We dissect the exact impact of the MS-DRG changes on hospital purchasing power and evaluate how the new FDA clearances alter the competitive balance.
For decision-makers committed to securing a strategic advantage in the medtech sector, access to granular data is the difference between reactive management and proactive leadership. We invite you to explore the full Oxygenator Market research study to equip your team with the precise intelligence needed to navigate 2026 and the forecast period through 2032. The future of extracorporeal life support is being written now, and informed strategy is the key to leading it.
For detailed analysis of this topic, please visit the official page: Oxygenator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com