

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Disposable Lighters Market Hits $215M in 2025, Projects 4% CAGR to 2032

The Disposable Lighters Market in 2026: Strategic Intelligence for Navigating Growth, Regulation, and Competition
Executive Overview
The disposable lighter market stands at a pivotal juncture as it enters the 2026 forecasting horizon. Built on six years of historical tracking from 2020 through 2025 and projected forward to 2032, our latest Disposable Lighters Market research offers decision-makers a rigorous, data-grounded view of where the industry is headed and how to position for durable advantage. This article previews the strategic architecture of that study, highlights the macro trajectory that shapes corporate planning, and illustrates why full-report access is essential for precise, actionable execution.
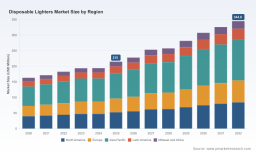
At the aggregate level, the sector has demonstrated resilient expansion through a period marked by shifting consumer habits, tightening safety mandates, and evolving material economics. Measured in millions of USD, the market moved from an estimated 163.15 million in 2020 to 171.54 million in 2021, 182.71 million in 2022, and 193.98 million in 2023. A brief plateau near 194.2 million in 2024 gave way to a stronger rebound to 215.0 million in 2025, signaling renewed demand momentum and pricing normalization after post-pandemic supply adjustments. Looking ahead, the base year of 2025 anchors a forecast that reaches 228.11 million in 2026, 253.39 million in 2027, and 257.58 million in 2028 before continuing its upward course toward 281.65 million in 2029, 307.56 million in 2030, 325.93 million in 2031, and 344.8 million in 2032. Across the full forecast window, the market is projected to compound at a steady 4.0 percent CAGR, reflecting a sector that is expanding with discipline rather than volatility.
For executives, this trajectory is not simply a line on a chart. It is a frame for capital allocation, product mix decisions, supplier negotiations, and regulatory preparedness. The report is designed to convert these macro signals into operational clarity across geographies, product types, and end-use segments, all while preserving the analytical depth required to test assumptions and stress scenarios.
The 2026 Decision Environment
The year 2026 introduces a distinct set of decision points for manufacturers, distributors, and category investors. Demand has recovered beyond pre-plateau levels, yet the operating terrain has grown more complex. Companies must now reconcile volume growth with compliance burdens, cost pressure on plastics and metals, and the strategic positioning of product lines ranging from commodity flint designs to specialty utility and premium offerings. In this environment, aggregate growth alone does not dictate winners. Advantage accrues to organizations that can decompose the market precisely, identify where value is actually generated, and align product roadmaps with enforceable safety and material standards.
Our study is built for that complexity. It translates historical momentum into a structured forward view, allowing leadership teams to test capacity expansions, prioritize regional entries, and evaluate whether to compete on cost, compliance, durability, or brand equity. The forecast framework covers the full 2026 to 2032 arc, which is especially valuable when programs require multi-year lead times and long-cycle supplier commitments. Rather than forcing decisions on anecdotal momentum, the report grounds them in a consistent methodology and clearly defined base assumptions.
What the Report Delivers
The core objective of this research is to turn top-level demand signals into practical decision intelligence. The report combines a long-run historical baseline with a structured forecast and a granular breakdown of the market across dimensions that matter operationally. Readers will find a comprehensive market sizing narrative that traces the 2020 to 2025 evolution and extends through 2032, supported by a transparent view of how growth compounds over time. Beyond the headline figures, the study provides segmentation architecture that separates the market by geography, by product type, and by application, so teams can assess where volume concentrates and where value pools diverge.
Equally important, the report addresses the structural forces influencing those segments. It examines regulatory developments that affect product design, import logic, and producer obligations, alongside raw material dynamics that shape unit economics and sustainability exposure. The study also evaluates manufacturing scale, labor cost sensitivity, and supply-chain vulnerability in key production regions, helping leaders distinguish between apparent volume opportunities and economically viable ones. In practical terms, this means the report supports a wider range of decisions than simple growth planning. It informs SKU rationalization, packaging strategies, compliance roadmaps, distribution partnerships, and competitive positioning with respect to the dominant branded players and their specialized niches.
Because the research is designed as a decision tool rather than a static reference, it integrates scenario-ready thinking. Senior teams can use the forecast structure to model how demand might respond to pricing shifts, regulatory timing, or channel mix changes. That flexibility is essential in a market where one size rarely fits all and where regional or product-level dynamics can diverge materially from the global average. The full report makes those divergences visible without diluting the central narrative, enabling users to focus on the segments most relevant to their specific objectives.
Market Dynamics: Regulation, Materials, and Supply
Several concurrent forces define the current operating landscape. On the regulatory side, safety and material policy are reshaping what can be sold, where it can be sourced, and who bears the compliance burden. In the United States, enforcement of child-resistant lighter standards under 16 CFR part 1210 requires disposable lighters to incorporate mechanisms that reduce accidental ignition by children, a requirement that influences design, manufacturing, and quality assurance across the supply base. At the same time, the EU Single-Use Plastics Directive, together with equivalent legislation in the UK, Canada, and Australia, introduces phased restrictions and extended producer responsibility obligations on single-use plastic lighters. These measures raise compliance costs and encourage manufacturers to reconsider material choices, packaging, and product longevity.
Trade policy adds another layer of complexity. Rules advanced by the U.S. International Trade Commission and the Consumer Product Safety Commission on disposable pocket lighters have begun to limit imports from certain countries, affecting pricing, domestic production margins, and sourcing strategies. These import constraints can create localized supply advantages for compliant producers while raising cost and availability pressure for others. The result is a market in which regulatory alignment increasingly determines access as much as product quality or brand strength.
Disposable Lighters Market
Materials and production economics remain central to unit economics. Each year, more than 15 billion disposable lighters are produced worldwide, primarily using non-recyclable plastic and metal components that contribute to plastic pollution. This scale is both a demand signal and a sustainability challenge, particularly as extended producer responsibility regimes mature. Manufacturing capacity expansion in China by major players has increased production scale, yet it has also exposed the sector to volatile labor and supply-chain costs for plastic and metal components. For global buyers and producers alike, this means that capacity abundance does not automatically translate into stable margins or predictable lead times.
These dynamics are not peripheral notes. They are market-shaping conditions that affect product architecture, sourcing strategy, and regional profitability. The report treats them as integral to the forecast rather than as separate commentary, so users can see how regulatory timing, compliance cost, and material exposure interact with the demand trajectory from 2026 onward.
Competitive Landscape: Leadership, Specialization, and the Path to Enduring Advantage
The structural concentration of the market underscores the importance of competitive intelligence. The top three firms account for about 65.0 percent of the market, while the top five reach roughly 75.0 percent, indicating a landscape where scale, brand recognition, and distribution reach matter significantly. Yet concentration does not imply uniformity. The competitive field is diversified by purpose, with players pursuing distinct value propositions across mainstream utility, safety-focused design, premium branding, and OEM supply.
Disposable Masks Market
Among the leaders, Société BIC S.A., headquartered in France, stands as the world’s largest branded pocket lighter manufacturer, with over 30 billion units sold. Its strength lies in child-resistant disposable flint lighters and multi-purpose utility lighters, positioning it at the intersection of safety compliance and broad consumer accessibility. Tokai Corporation, based in Japan, operates as a major global supplier of disposable and refillable lighters with a strong emphasis on OEM production. Its focus on safety, child-resistant features, and cost-efficient flint designs makes it a critical partner for brands and distributors seeking reliable manufacturing scale. Flamagas S.A., from Spain, is known for durable, windproof disposable lighters under the Clipper brand, emphasizing robust flint ignition and multi-use utility applications that appeal to both retail consumers and professional users.
Swedish Match, headquartered in Sweden, leads with Cricket-branded disposable lighters and specializes in reliable, child-resistant flint lighters for global retail and utility markets. Zippo Manufacturing Company, from the United States, occupies a distinct niche with classic metal-bodied disposable and hybrid lighters built on windproof flint technology, targeting premium and everyday-carry utility segments. In China, NingBo Xinhai Electric Co., Ltd. plays a major role as a manufacturer of disposable flint and electronic lighters, supplying windproof arc and traditional models for global distribution and reinforcing the country’s importance as a production hub. Calico Brands, Inc., also based in the United States, serves as a wholesale supplier of diverse disposable lighter SKUs, including multi-purpose, spark-wheel, and value-priced flint designs, with a clear focus on retail and institutional bulk distribution. Finally, S.T. Dupont, from France, operates in the luxury tier with high-end disposable and metal lighters, offering premium flint and torch-style utility models for high-end markets where branding and finish command price premiums.
The competitive story is therefore one of layered positioning. Scale and compliance expertise sit alongside durability, windproof performance, OEM flexibility, and premium differentiation. The report examines how these players are structured, where their strengths align with regulatory and consumer trends, and which segments are most contested or most open. Full competitive profiling in the study goes further than brand recognition by connecting product strategy to market structure, so readers can identify where to defend share, where to build differentiated offerings, and where to pursue partnership or acquisition opportunities.
Why the Full Study Matters for 2026 Planning
For executives planning around 2026, the difference between good strategy and great strategy is often granularity. Aggregate growth and a steady CAGR frame the opportunity, but the real decisions lie in understanding how demand, regulation, materials, and competition interact in specific contexts. The complete Disposable Lighters Market report provides that context through detailed segmentation insight, structural analysis, and competitor scaffolding, all organized to support practical action. It helps teams answer questions that aggregate summaries cannot resolve on their own: where growth is most defensible, which compliance trajectories carry the highest operational cost, which product types balance demand with margin potential, and how major players are likely to respond as the forecast window progresses.
The study also provides the roadmap for reading the market beyond the headline. With a forecast that extends to 2032, decision-makers can align investment timing, production commitments, and go-to-market plans with a realistic growth arc instead of reacting to short-term fluctuations. That longer view is especially valuable when safety mandates, trade constraints, and material obligations continue to evolve in parallel, because it allows organizations to anticipate change rather than simply absorb it.
Access the Intelligence
This article previews the strategic logic and structural clarity behind our latest market research. The full Disposable Lighters Market report goes further by combining historical depth, a rigorous 2026 to 2032 forecast, segmentation detail, competitive profiling, and regulatory and materials analysis into a single decision-ready framework. For leadership teams that need to move from directional confidence to precise execution, the complete study offers the granularity required to plan with conviction. Access the source page to obtain the full intelligence set, detailed segmentation findings, and the competitive context needed to shape 2026 strategy with precision.
For detailed analysis of this topic, please visit the official page: Disposable Lighters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com