

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Healthy Lifestyle
PW Consulting: Emergency Weatherproof Batten Market to Reach USD 603.7 Million by 2032 at 5.5% CAGR; Asia Pacific Leads with USD 135 Million
By pmarketresearch, 2026-08-18
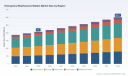
Emergency Weatherproof Batten Market: Strategic Preview for 2026 Decision‑Making
PW Consulting’s latest industry briefing offers a focused, strategic preview of the Emergency Weatherproof Batten market as companies prepare decisions for 2026. Built on a proprietary market model with a 2025 base year, the analysis synthesizes historical performance (2020–2025), near‑term dynamics, and a seven‑year forecast horizon (2026–2032). At the macro level, the market is expanding steadily — from an estimated USD 415 million in 2025 and growing at a compound annual growth rate (CAGR) of approximately 5.5% to reach roughly USD 604 million by 2032 — driven by energy‑efficiency transitions, tightening compliance requirements, and increased specification activity in harsh‑environment projects.
Flip Chip Packages Market
Why this preview matters to 2026 strategy
- The emergency weatherproof batten category sits at the intersection of safety regulation, energy transition, and resilient infrastructure spending. Procurement cycles for industrial, public infrastructure, and commercial projects commonly run on multi‑year timelines; the decisions made in 2026 will shape installation and retrofit volumes for the remainder of the decade.
- Regulatory alignment is becoming a commercial edge. Mandatory and best‑practice standards (for example, national emergency‑lighting codes and international fixture safety standards) are raising the bar on battery chemistry, ingress protection, and testing protocols — turning compliance from a checkbox into a supplier selection criterion.
- Operational cost reductions from LED migration and remote monitoring are now quantifiable and widely used in business cases for retrofits. Stakeholders who can demonstrate lower total cost of ownership (TCO) can capture specification wins in a market with measured supplier concentration (CR3 ≈ 22.5%, CR5 ≈ 31.8%).
What the market dynamics mean in practice
- Energy and operational efficiency are primary demand drivers. LED‑based emergency battens offer material energy savings and extended service lives versus legacy technologies, translating to lower lifecycle costs for asset owners and stronger ROI for retrofits.
- Battery technology and product robustness are differentiators. Adoption of LiFePO4 chemistry, longer warranty terms, and higher ingress/impact ratings (IP65/IP66, IK08) are de‑risking installations in outdoor and industrial settings and are increasingly required by specifiers.
- Compliance and testability influence procurement. Local and international standards (including national emergency‑lighting codes and IEC fixture safety requirements) directly affect product design, labelling, and post‑installation maintenance regimes; suppliers that provide straightforward compliance documentation and remote testing capabilities are favored.
- Supply‑chain and material trends are non‑trivial. For example, upstream price movements for engineering plastics used in housings and diffusers are creating episodic cost pressure; observed pricing data from China in early 2026 show downward price signals for polycarbonate driven by softer demand in adjacent sectors — a factor that affects margin planning and sourcing strategies.
Competitive landscape — positioning and tactical moves
Our competitive scan combines product profiling, recent product and compliance developments, and a supplier capability lens. The field features a mix of regional specialists and international OEMs, with clear segmentation between premium, compliance‑led players and cost‑focused manufacturers that serve OEM/ODM channels.
CCD Image Sensors Market
- Regional specialists with compliance‑led portfolios: Several established Australian manufacturers have built reputations on products engineered for harsh environments and code compliance. Their offerings increasingly include LiFePO4 batteries, selectable colour/output options, and “maintained” emergency operation modes to suit car parks, warehouses, and other critical facilities.
- Feature‑rich LED innovators: Vendors are differentiating through features such as white‑tuning, dimmability, wireguard/diffuser options, and integrated wireless monitoring platforms for remote diagnostics — all of which reduce onsite maintenance costs and support portfolio premiumization.
- China‑based OEM/ODM scale players: Industrial producers in Shenzhen and elsewhere continue to supply robust IP65/IP66 fixtures at competitive price points for large‑volume infrastructure projects (tunnels, workshops, outdoor sites), often offering native emergency systems and private‑label partnerships.
- Recent signals to watch: updates published in early 2026 by compliance‑active vendors and product launches announced in 2025–2026 indicate accelerating focus on enhanced emergency classifications, wireless monitoring, and temporary outdoor safety lighting — each reflecting different go‑to‑market plays.
Strategic implications and recommended actions for 2026
Based on our synthesis of market growth, regulatory drivers, supplier capabilities, and supply‑chain noise, PW Consulting recommends the following practical moves for firms participating in the emergency weatherproof batten value chain.
Reptile Heating and Lighting Supplies Market
- Manufacturers — prioritize certifiable robustness and TCO messaging. Product roadmaps should emphasize LiFePO4 battery integration, higher IP/IK ratings, and extended warranties. Equip product sheets with compliance evidence and lifetime cost calculators to convert specifiers focused on evacuation safety and lifecycle economics.
- Distributors & wholesalers — evolve from logistics to solutions provision. Expand capabilities to offer specification packages, on‑site testing services, and firmware/remote monitoring bundles. These value adds protect margins as price competition intensifies and enable recurring service revenue.
- Project owners & facility managers — build retrofit prioritization frameworks. Use energy‑and‑safety KPIs to rank retrofit candidates; target facilities where LED upgrades plus smart monitoring yield the fastest payback. Incorporate compliance audit clauses into procurement to ensure installed fixtures meet code and insurer expectations.
- Specifiers & consultants — demand testability and documentation. Insist on suppliers that provide clear evidence of compliance with national standards and international safety norms, as well as remote diagnostic capability for scheduled verification without full site interventions.
- Procurement & sourcing teams — mitigate material and logistics risk. Establish dual sourcing for critical plastics and battery components and negotiate flexible pricing clauses tied to a transparent input‑cost index. Consider regional manufacturing partnerships to shorten lead times for emergency projects.
What PW Consulting’s full report delivers (practical contents)
The full Emergency Weatherproof Batten Market report is structured to be actionable for commercial strategy and procurement decisions. Key deliverables include:
- Proprietary market model (historical 2020–2025, base year 2025) and scenario‑based forecasts through 2032, with sensitivity analysis covering demand shocks and regulatory tightening.
- Market segmentation across regions, product types, and applications with demand drivers and adoption curves (note: headline segmentation summaries are discussed in this preview; detailed segment figures are available in the full report).
- Supplier scorecards and comparative feature matrix covering design robustness, battery chemistry, monitoring capability, compliance documentation, warranty terms, and go‑to‑market strength.
- Commercial playbook including specification templates, procurement contract clauses, retrofit prioritization tool, and sample ROI models for LED + monitoring upgrades.
- Supply‑chain risk register and raw‑material sensitivity assessment with recommended sourcing mitigations and inventory strategies.
- Innovation radar and roadmap — from battery evolution to wireless remote testing — highlighting technology inflection points and expected timelines for wider adoption.
- Regulatory impact analysis covering national emergency lighting codes and IEC fixture safety requirements, plus a compliance checklist for specifiers and installers.
Near‑term watchlist (Q1–Q4 2026)
- Regulatory clarifications and enforcement activity in major markets — any updates to national emergency‑lighting codes will alter procurement requirements and retrofit schedules.
- Advances in remote monitoring platforms and standardized remote test protocols — early adopters will capture maintenance savings and long‑term contract wins.
- Raw material pricing trajectories for engineering plastics and battery cell supply dynamics — these will affect supplier margins and may trigger contract renegotiations or localized sourcing moves.
- Competitive product rollouts that bundle compliance documentation, longer warranties, and remote testability — expect suppliers that combine these features to expand spec share in safety‑sensitive verticals.
Concluding perspective
The Emergency Weatherproof Batten market is maturing into a solutions‑oriented sector where safety compliance, durability, and lifecycle economics govern commercial outcomes as much as unit price. With steady growth projected through 2032 at an approximate 5.5% CAGR, the commercial opportunity is meaningful for firms that can align product design, regulatory readiness, and service‑led go‑to‑market approaches. PW Consulting’s full report provides the granular segmentation, supplier benchmarking, and procurement tools needed to operationalize these insights. This press release intentionally omits detailed segment‑level data to protect the tactical intelligence contained in the full study; decision‑makers seeking the complete dataset, segmented forecasts, and supplier matrices are invited to access the full report on the PW Consulting website.
For detailed analysis of this topic, please visit the official page: Emergency Weatherproof Batten Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Degradable Implants Market to Expand from USD 6.85 Billion in 2025 to USD 11.93 Billion by 2032, Backed by an 8.25% CAGR
By pmarketresearch, 2026-08-18
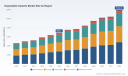
PW Consulting Releases Strategic Brief: Degradable Implants Market — A 2026 Playbook for Market Leaders and Challengers
PW Consulting today publishes a strategic briefing drawn from our forthcoming Degradable Implants Market report, designed to equip executive teams with the evidence and decision frameworks they need as they allocate R&D, regulatory and commercial capital in 2026. The degradable implants market has moved from scientific promise to commercial reality: after a market value of USD 4,608.7 million in 2020, PW’s model projects continual expansion—reaching USD 6,850.5 million in 2025 and accelerating into the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 8.25%, with our 2032 projection exceeding USD 11.9 billion. For leaders preparing budgets, partnerships and regulatory dossiers for next year, this report translates high-level growth into executable options while preserving the detailed segment data behind a gated model.
Rare Earth Battery Alloys Market
Why this report matters for 2026 decision-making
- Translating growth into strategy: The macro expansion is real, but winning requires choices—material selection, clinical evidence prioritization and commercialization sequencing—that determine whether a program is accretive or dilutive to enterprise value.
- Regulatory and evidence timing: The regulatory pathway for bioresorbables is now characterized by heightened scrutiny on long-term biocompatibility and mechanical performance across degradation timelines; timing of clinical milestones materially affects market access windows and ROI.
- Supply chain and cost management: Specialized magnesium alloys and precision manufacturing materially raise component costs versus conventional implants; supply concentration in primary magnesium production adds a volatility premium that must be hedged.
- Competitive posture: The market displays a moderate concentration (CR3 ≈ 42.5%; CR5 ≈ 56.8%)—enough room for scale players to defend incumbency but also for focused innovators to create lucrative niches.
What the PW Consulting report delivers (practical outputs)
- Comprehensive market sizing and 2026–2032 forecast with bottom-up and scenario-based projections that isolate demand drivers and sensitivity to reimbursement and pricing.
- Technology and materials mapping—polymers, ceramics, magnesium alloys and emerging biological matrices—linked to manufacturing cost envelopes and scale economics.
- Regulatory and clinical roadmap: stepwise requirements (including ISO 10993 biocompatibility frameworks), recommended study designs to demonstrate mechanical equivalence through degradation, and timing templates for FDA/EMA submissions.
- Supplier and OEM intelligence: vendor scorecards, margin corridor analyses, and contract manufacturing profiles to accelerate production scale-up without compromising regulatory traceability.
- Commercial playbooks: GTM sequencing, hospital procurement strategies, value dossiers for payers and clinicians, and launch KPIs for trauma, orthopedic reconstruction and cardiovascular scaffold applications.
- Deal and investment suite: M&A heatmaps, licensing models, and joint-venture archetypes informed by CR3/CR5 concentration and technology ownership.
- Interactive financial model and data annex (gated): full segment splits, unit economics, and sensitivity levers available to subscribers and licensed users.
Competitive landscape: how incumbents and specialists are positioning
The competitive topology is bifurcating along two axes: large orthopedics/medtech incumbents leveraging commercial reach and regulatory expertise, and specialist innovators driving material-level differentiation.
Paper Coffee Filter Market
- Specialist innovators — Firms such as Bioretec Ltd and Syntellix AG have staked leadership in magnesium-based solutions and are translating clinical-first positioning into regulatory milestones. Bioretec’s RemeOs magnesium alloy portfolio earned the industry’s first FDA De Novo clearance in its class and has since accrued further regulatory momentum (including a Breakthrough Device designation for a RemeOs DrillPin and CE approvals supporting European commercialization). These regulatory achievements shorten commercial lead times for novel metallic resorbable fixation and create a reference set for competitors. Syntellix’s MAGNEZIX line similarly demonstrates how metallic degradables can scale clinically when combined with strong device-level evidence and regional certifications.
- Polymer specialists and platform owners — Companies such as Inion Oy have commercialized polymer-based, bioabsorbable plates, screws and anchors across multiple specialties and boast substantial clinical usage; their strengths lie in integrated polymer platforms and well-developed clinical adoption pathways.
- Large medtech incumbents — Major OEMs (including Medtronic, Johnson & Johnson / DePuy Synthes, Stryker, Zimmer Biomet and Smith+Nephew) are actively incubating or acquiring bioresorbable capabilities to protect franchise value and address surgeon demand for absorption-enabled workflows. These players bring scale in distribution, hospital contracting and payer engagement—critical advantages when converting clinical approvals into unit volumes.
- Cardiovascular niche players — Biotronik’s resorbable scaffold programs underscore that the cardiovascular use-case has a distinct evidence and reimbursement arc compared with orthopedics, requiring dedicated registries and HTA engagement strategies.
Regulatory, material and supply dynamics to watch in 2026
- Regulatory rigor is the new baseline: FDA and EMA expectations now routinely include long-term in vivo degradation studies and proof of mechanical equivalence across the degradation lifecycle; sponsors should budget for multi-year programs and plan staged submissions to sustain investor confidence.
- Magnesium economics and sourcing: Development of medical-grade magnesium alloys increases unit production costs—our analysis shows a meaningful premium relative to conventional materials—and primary magnesium supply is regionally concentrated. China’s dominance in upstream magnesium production drives a potential price and availability volatility that can distort margin models for manufacturers absent mitigation strategies.
- Clinical evidence and HCP adoption: Surgeon familiarity, instrumentation compatibility and real-world registries will be decisive in adoption speed, especially for pediatric and trauma applications where device removal avoidance is a clear clinical value proposition.
Strategic actions for 2026: a practical playbook
- Secure material supply and manufacturing continuity: Negotiate multi-year supply contracts with quality clauses, explore geographic diversification for critical alloys, and assess vertical integration where scale economics justify capex.
- Invest early in degradation-focused evidence: Prioritize preclinical and early clinical studies that demonstrate mechanical competence through critical healing windows—this de-risks reimbursement conversations and accelerates regulatory acceptance.
- Design commercialization pilots intelligently: Launch in clinical centers of excellence to build registry data, refine surgical technique training, and create KOL advocates before broad roll-out.
- Align pricing to differentiated value: Account for production cost differentials (notably for magnesium-based implants) and build payer dossiers that quantify savings from avoided hardware removal, reduced secondary procedures and shortened care pathways.
- Consider partnership-first approaches: For many innovators, licensing to or co-developing with a larger OEM reduces time-to-scale and leverages established sales channels while preserving upside through milestone and royalty structures.
- Model multiple scenarios: Run downside and upside scenarios tied to regulatory timelines, magnesium price shocks and hospital adoption rates; use contingent investment tranches to protect cash runway.
How PW’s intelligence accelerates your 2026 roadmap
Executives who use PW’s degradable implants intelligence gain access to a practical combination of macro forecasts, competitive scorecards and executable playbooks that reduce uncertainty at three critical decision gates: R&D prioritization, regulatory sequencing and commercialization sequencing. The report’s gated models allow clients to interrogate unit economics under custom assumptions—isolating the impact of material costs, scaling efficiencies and pricing strategies on IRR and payback.
Portable LED Light Facial Device Market
Access and next steps
This release is a strategic synopsis designed to demonstrate the report’s analytic depth while preserving the granular segment tables, regional splits and company-level scorecards that form the paywalled core. Firms planning capital allocation, M&A or partnership strategies for 2026 should engage PW Consulting for a tailored briefing and demo of the interactive forecast model.
To request a briefing, licensing terms for the interactive model, or to arrange a private strategy workshop for your leadership team, contact PW Consulting’s Life Sciences Strategy practice. Our consultants can map the outputs of this study to your product portfolio, regulatory timelines and commercial channels so you can move from insight to action in 2026 with confidence.
For detailed analysis of this topic, please visit the official page: Degradable Implants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tongbianling Jiaonang Market Set to Reach USD 126.6 Million by 2032 at a 5.85% CAGR, China Commanding 78% Share
By pmarketresearch, 2026-08-18
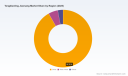
Tongbianling Jiaonang Market Outlook 2026: Strategic Implications for Pharma Leaders
PW Consulting’s latest Tongbianling Jiaonang Market report synthesizes primary research, regulatory mapping, and scenario modeling to equip executives with the insight required to make decisive 2026 choices. The market for Tongbianling Jiaonang has shown steady expansion in recent years — moving from an estimated USD 75.8 million in 2023 to USD 85.0 million in 2025 — and is forecast to grow to approximately USD 126.55 million by 2032. This trajectory corresponds to a compound annual growth rate (CAGR) of 5.85% across the 2026–2032 forecast window, underscoring persistent demand and a stable runway for strategic investment.
Thymosin Enteric Coated Tablets Market
Why 2026 is a Pivotal Year for Decision-Making
-
Regulatory inflection points are accelerating market access opportunities. Cross-border registrations and targeted approvals are beginning to unlock export channels beyond domestic consumption, creating actionable commercialization pathways for established manufacturers and new entrants alike.
Peripheral Supportive Guide Wire Market -
Distribution dynamics continue to evolve: traditional hospital and retail channels remain important for clinical credibility, while digital channels are driving direct-to-consumer reach and international sales. Firms that can orchestrate a hybrid channel strategy will capture disproportionate share of near-term growth.
Outdoor Lighting Signs Market -
Price competition and generics pressure remain a structural force. Managing cost-to-serve, product differentiation through formulation or bundled services, and selective premium positioning are immediate priorities.
-
Quality assurance and regulatory compliance are non-negotiable. Recent public advisories in certain Southeast Asian markets have highlighted enforcement risks for unregistered imports, raising the bar for firms pursuing export-led strategies.
Top-Line Strategic Takeaways for Boards and CEOs
-
Treat 2026 as a “registration and channel optimization” year. With the market continuing to expand, a focused investment in international registrations and e-commerce capability offers high ROI compared with undifferentiated capacity expansion.
-
Align portfolio economics to differentiated value. Generic pressure favours deeper SKU rationalization and a two-tier product strategy: defend mass volumes with cost-efficient SKUs while layering higher-margin, clinically supported variants or services.
-
Prioritize quality and traceability investments. Strengthened QA/QC, serialization, and third-party verification will reduce market access friction and protect brand reputation in export markets.
-
Make M&A and partnership moves early. The market’s moderate concentration and the emergence of new regulatory corridors mean that targeted acquisitions or licensing deals can accelerate access and scale without the lead time of greenfield investments.
-
Embed adaptive pricing and promotional playbooks. Dynamic channel economics demand real-time pricing experiments and a performance-driven promotional mix focused on lifetime value rather than one-off sales.
Competitive Landscape: What Leading Players Signal About Future Moves
Our report profiles incumbent manufacturers and newer challengers and distills implications for competitive strategy. Key observations include:
-
Shaanxi Buchang Pharmaceutical Co., Ltd. is leveraging regulatory validation to expand export presence — most notably securing an overseas drug registration late in 2025. This move is emblematic of a broader shift: domestic manufacturers are increasingly pursuing cross-border regulatory pathways to diversify revenue streams.
-
Shijiazhuang Yiling Pharmaceutical Co., Ltd. is combining traditional distribution with e-commerce to reach international consumers directly. Firms that can marry domestic channel strength with global digital reach are well positioned to accelerate top-line growth without proportionate OPEX expansion.
-
Lunan Pharmaceutical Group’s orientation toward clinical supply and research collaborations highlights a route to differentiate through evidence generation. For players targeting hospital and institutional channels, investment in clinical partnerships remains a high-leverage strategy.
-
Other listed and regional manufacturers maintain supply footprint and standard-compliant SKUs under national specifications. Their presence sustains baseline market coverage and underscores the need for distinct competitive playbooks for scale vs. specialty players.
Together, these behaviors indicate a marketplace where capability in regulatory execution, digital commercialization, and evidence-driven differentiation will separate winners from laggards.
Operational Playbook: 6-Step Framework for 2026 Execution
-
1. Validate addressable opportunity: Reconcile internal sales data with independent market sizing to identify over- and under-served channels.
-
2. Map regulatory pathways by priority market: Sequence registration investments based on time-to-market, enforcement risk, and revenue potential.
-
3. Pilot hybrid channel pilots: Run controlled experiments that combine hospital liaison efforts, retail incentives, and targeted e-commerce campaigns with measurable KPIs.
-
4. Harden supply chain and manufacturing: Stress-test critical suppliers, establish dual-sourcing where feasible, and optimize batch sizes to manage working capital.
-
5. Screen M&A and partnership targets: Use a capability-first filter to prioritise assets that plug gaps in registration capability, digital capability, or manufacturing scale.
-
6. Invest in clinical and KOL engagement: Commission post-marketing studies or real-world evidence projects to support differentiated label claims for selected indications.
Regulatory and Market Risks — and How to Mitigate Them
-
Unregistered product advisories: Several regulators in the region have issued warnings around unregistered imports. Mitigation: institutionalize regulatory intelligence and pre-clearance protocols for any export activity.
-
Quality incidents and counterfeit risk: OTC herbal products can be targets for counterfeiters; reputational damage has immediate commercial consequences. Mitigation: adopt serialization, third-party testing, and transparent supply chain disclosures.
-
Price erosion: Generic entrants exert downward pressure on margins. Mitigation: prioritize operational cost-out programs and brand/clinical differentiation investments that sustain premium positioning.
-
Channel conflict: Expanding e-commerce can cannibalize traditional distribution partners. Mitigation: design channel governance and revenue-sharing models that align incentives across stakeholders.
What the Full Report Contains (Practical Deliverables)
The PW Consulting Tongbianling Jiaonang Market report is built for immediate boardroom use and includes:
-
Detailed market sizing and historical trend analysis (2020–2025) and a scenario-based forecast through 2032, including modeled sensitivities to pricing, channel mix, and regulatory timelines.
-
Channel and customer archetypes with go-to-market blueprints tailored to hospital, retail, and digital pathways — plus pilot budgets and performance benchmarks.
-
Regulatory dossiers and a jurisdictional risk matrix that highlights registration requirements, likely timelines, and enforcement posture across priority export destinations.
-
Competitive benchmarking with strategic profiles for major manufacturers, documented recent developments, and a pragmatic M&A target-screen with valuation heuristics.
-
Operational playbooks: SKU rationalization templates, supply chain risk maps, and QA/QC upgrade roadmaps aligned to expected regulatory scrutiny.
-
Primary research appendices — including stakeholder interview summaries, clinician feedback, and distribution partner assessments — and an accessible model workbook for in-house scenario testing.
Note: To preserve the actionable value of our analysis for clients, the public summary intentionally omits granular regional and channel split tables and the underlying unit economics. Subscribers and licensed purchasers receive the complete segmentation schedule and model outputs.
How This Report Supports 2026 Budgeting and M&A Priorities
-
Scenario-based forecasting enables CFOs to stress-test investment cases under conservative and aggressive registration timelines, directly informing 2026 capex and OPEX allocations.
-
Commercial due diligence templates accelerate M&A timelines by providing pre-scored target profiles and integration blueprints focused on regulatory, digital, and manufacturing fit.
-
Market-entry playbooks shorten time-to-revenue for international launches by sequencing registration and channel investments against expected payback horizons.
Next Steps
For leaders preparing 2026 business plans, the strategic reading is clear: the Tongbianling Jiaonang market presents a durable growth opportunity, but realization requires disciplined execution across regulatory, commercial, and operational vectors. PW Consulting’s full report provides the granular segmentation, valuation models, and tactical playbooks necessary to translate market potential into locked-in revenue.
To access the complete analysis, model workbook, and company dossiers, visit PW Consulting’s report page or contact our pharmaceutical practice lead for an executive briefing. Our team is available to run tailored scenario workshops that map the findings directly to your 2026 P&L and balance-sheet priorities.
For detailed analysis of this topic, please visit the official page: Tongbianling Jiaonang Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Nystatin API Market Poised for 3.85% CAGR Through 2032 as Dermatology Demand Fuels Growth
By pmarketresearch, 2026-08-18
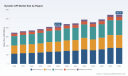
Nystatin API Market Outlook 2026: Strategic Imperatives for Pharmaceutical Leaders
Executive summary
As pharmaceutical supply chains stabilize from pandemic-era disruptions and manufacturers recalibrate portfolios, Nystatin API is re-emerging as a steady, specialty antibiotic ingredient with clear risk–reward characteristics for 2026 planning cycles. PW Consulting’s new Nystatin API Market report uses a harmonized historical series (2020–2025) and a forward-looking forecast window (2026–2032) to quantify supply dynamics, pricing trajectories, and competitive positioning. The global market was valued at approximately USD 417.3 million in our base year (2025) and — under our central case — is projected to expand at a compound annual growth rate (CAGR) of 3.85% through the forecast horizon, reaching roughly USD 543.7 million by 2032.
UHMWPE Powder for Battery Separator Market
This press briefing outlines the report’s strategic value for 2026 decision-making: where to prioritize supplier due diligence, how to align quality investments with regulatory expectations, and which moves (commercial, operational, and M&A) can de-risk supply while protecting margin. To preserve commercial confidentiality and to follow our “trailer” principle, full regional and application-level splits, as well as company-level volume/price schedules, are reserved for the full report.
Can Leakage Tester Market
Why 2026 is a pivotal planning horizon
-
Mid-cycle industry reset. With the market entering a moderate growth phase—supported by steady clinical demand in dermatology and gastroenterology formulations—2026 becomes a decision point for firms that postponed capital allocation in 2023–2025.
Worldwide Air Clean Tooth Machine Market -
Regulatory tightening around fermentation-derived APIs. Nystatin production remains subject to strict USP/EP/ICH controls, and regulators are increasingly focused on impurity profiles specific to fermentation routes. Compliance investments made in 2026 will influence market access and tender performance through the rest of the decade.
-
Supply-chain concentration risks. Production clustering in a limited set of countries and facility types makes 2026 the year to convert supply-chain assessments into contractual mitigations and sourcing rebalancing.
Market dynamics and outlook
Our consolidated analytics indicate that global Nystatin API production in 2025 reached approximately 128 metric tons, with an average market price near USD 298 per kilogram. Price and volume movements remain sensitive to fermenter availability, raw-material fermentation inputs, and GMP/CEP/USDMF inspection cycles. Over the forecast window, we model a base-case CAGR of 3.85%, while stress-tested scenarios examine the impact of a regulatory-driven production shock and an accelerated demand scenario driven by new formulation uptake.
Key demand drivers include continued use in topical dermatology and selected gastroenterology segments, stable generics substitution dynamics, and routine hospital procurement cycles. On the supply side, a handful of established manufacturers with mature fermentation platforms and recognized certifications dominate meaningful share. This creates a marketplace where quality and certification credentials materially affect commercial access to high-regulation markets.
Regulatory and supply-chain constraints
-
Standards and inspection regimes. Nystatin API production must satisfy USP, EP and ICH expectations, including tighter controls on fermentation-derived impurities and robust batch traceability. Manufacturers without strong regulatory dossiers face barriers to entry in major markets.
-
Input sourcing vulnerabilities. Fermentation feedstocks and certain process reagents have limited suppliers; lead times and spot-price volatility for these inputs amplify operational risk for API facilities concentrated in specific geographies.
-
Certification refreshes matter. Recent updates—such as a CEP refresh for a major European producer in December 2025—illustrate how certification timelines can influence short-term tender eligibility and longer-term contract negotiations.
Competitive landscape — where scale, certification and fermentation know‑how meet
The Nystatin API competitive set combines legacy API houses and specialized fermentation-focused producers. Market concentration metrics indicate that the top three players control a substantial minority of market share, while the top five expand that influence meaningfully—creating an environment where a small set of suppliers can steer pricing and capacity availability during periods of tight supply.
-
Antibiotice S.A. (Iași, Romania) — A long-established fermentation specialist with decades of experience, Antibiotice combines scale with multiple regulatory approvals (including FDA and EU GMP recognitions) and an established global customer base across finished formulations and API supply channels.
-
VUAB Pharma a.s. (Roztoky u Prahy, Czech Republic) — An integrated fermentation API producer and part of the Safichem Group with active CEP/USDMF/FDA-GMP credentials; recent certification maintenance in late 2025 underscores its continued access to regulated markets.
-
Olon S.p.A. (Italy) — A European API manufacturer with GMP capabilities and an active supplier profile in Nystatin; their integrated European supply footprint provides an on‑continent sourcing option.
-
Selected Chinese and Indian producers — Several manufacturers in China and India offer Nystatin API and provide important capacity options for global buyers; some are WHO-GMP certified and actively participate in export markets. These suppliers are essential for price flexibility but may require enhanced supplier qualification for high-regulation tenders.
-
Large integrated players — Historical involvement by multinational pharmaceutical groups also shapes secondary supply dynamics and can influence spot availability during demand spikes.
For procurement and strategic sourcing teams, the implication is clear: certification credentials (CEP, USDMF, FDA, WHO-GMP) and fermentation process control are primary sourcing filters. The full report contains a supplier matrix that cross-references certifications, capacity indicators, and market reach to support rapid shortlisting; this matrix is not reproduced in this release.
What PW Consulting’s Nystatin API report delivers (practical content)
-
Proprietary forecast model (2026–2032) with scenario toggles for regulatory disruption and accelerated adoption—drive “what-if” decision-making for procurement, manufacturing and commercial teams.
-
Supplier assessment toolkit: an audited checklist covering regulatory dossiers, fermentation impurity profiles, capacity utilization signals, and audit-readiness scoring.
-
Commercial playbook for tendering and contracting: recommended contract clauses, quality escape provisions, and price-escalation mechanisms tailored for fermentation-derived APIs.
-
Regulatory heatmap and compliance timelines: practical guidance on dossier maintenance, CEP/USDMF synchronisation strategies and investment prioritisation to maintain market access.
-
Risk-adjusted M&A and partnership screen: identification of target archetypes (bolt-on capacity vs. capability buys) and illustrative valuation multipliers based on market concentration and certification value.
-
Inventory & manufacturing contingency playbook: tiered stocking strategies and contract manufacturing options to preserve continuity during supply interruptions.
Strategic recommendations for 2026 decision-makers
-
Prioritize supplier qualification over spot-price optimization. Given certification gating and impurity control requirements, a smaller set of pre-qualified suppliers can be worth a premium when continuity is at stake.
-
Execute dual-track sourcing: secure a core certified supplier for regulated markets while maintaining a flexible backup pool for lower-regulated channels. Ensure contractual rights to audit and capacity visibility.
-
Invest in dossier lifecycle management. Synchronising CEP/USDMF/FDA filings and proactive impurity monitoring will shorten approval lead times and improve tender performance.
-
Adopt scenario-driven inventory policies. Use our stress-test outputs to define minimum safe stocks and trigger points for rapid supplier escalation or toll-manufacturing activation.
-
Targeted M&A or strategic partnerships can be catalytic. For companies seeking control over fermentation know‑how, acquiring bolt-on capacity with verified compliance credentials is the fastest route to insulate supply.
-
Embed quality-by-design in procurement. Contract clauses that require vendor process-change notifications and joint change-control protocols reduce the risk of unexpected supply interruptions.
How to use the full PW Consulting report
The document serves as both an analytic reference and an operational playbook. Senior leaders will use the high-level scenarios and supplier matrices to inform capital allocation, while procurement and regulatory teams will extract checklists and heatmaps to operationalize supplier transitions. The report is intentionally modular so teams can extract the sections most relevant to their 2026 plans: forecasting, procurement, regulatory, or M&A.
For decision-makers preparing 2026 budgets, the key takeaways are actionable: plan for moderate market expansion (CAGR ~3.85% in our central case), assume tightness in certified fermentation capacity will periodically re-price the market, and treat regulatory dossier maintenance as a strategic lever rather than a compliance cost.
Next steps
PW Consulting is offering tailored briefings and scenario workshops for a limited number of clients in Q3–Q4 2026 to translate the report’s insights into procurement playbooks and investment roadmaps. The full report includes the confidential regional and application-level splits, granular supplier matrices, and downloadable forecast model spreadsheets required for precise budgeting and sourcing commitments.
Contact PW Consulting to schedule a briefing and obtain access to the full Nystatin API Market report and accompanying tools. Our team will help you convert the market outlook into a 90–180 day action plan that aligns with your 2026 objectives.
— PW Consulting, Senior Strategy & Industry Analysis
For detailed analysis of this topic, please visit the official page: Nystatin API Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HNB Heater Market Poised for Robust Growth — 8% CAGR Forecast Through 2032
By pmarketresearch, 2026-08-18
HNB Heater Market 2026 Strategic Brief: Navigating Growth, Supply-Chain Friction, and Competitive Consolidation
As PW Consulting’s lead industry analyst, I present a concise yet strategically rich preview of our HNB (heat-not-burn) heater market study — produced with the intent to inform C-suite decisions for 2026. The global HNB heater market has moved from an early-stage innovation curve into a scale-up phase: total market value rose meaningfully between 2020 and 2025 and, under our core forecast, is projected to continue expanding at roughly an 8.0% compound annual growth rate through the 2026–2032 horizon. This trajectory positions the sector as a high-priority growth vector for tobacco manufacturers, EMS suppliers, and precision-component vendors that can execute rapid industrialization while managing regulatory and supply-chain complexity.
Shoe Wrap Machine Market
Why this matters for 2026 strategic planning
-
Macro momentum provides optionality: With multi-year expansion built into the market base case, executives can justify near-term investments in product refinement, scale manufacturing, and commercialization pilots — but only if those investments are aligned to resilient supply-chain strategies and regulatory scenarios.
Nuclear Decommissioning Services Market -
Consolidation and concentration are shaping power dynamics: The sector exhibits a materially concentrated competitive structure at the top, with the leading groups controlling a clear majority of market activity. For incumbents and challengers alike, this consolidation creates both barriers and partnership opportunities that should inform M&A, JV, and contract-manufacturing choices in 2026.
Drum Turner Market -
Operational resilience is now a competitive differentiator: Elevated component and material pressure, trade-policy friction, and evolving compliance regimes mean that the winners will be those with diversified sourcing, localized manufacturing flex, and proactive regulatory engagement.
What PW Consulting’s HNB Heater report delivers (practical contents)
Our full study is engineered to be operationally actionable for management teams. It combines quantitative modeling, primary vendor benchmarking, and scenario-based playbooks so that clients can move from insight to execution within quarters rather than years. Key deliverables include:
-
Market sizing and demand model — base year anchored to 2025 with historical trend analysis (2020–2025) and scenario-driven forecasts (2026–2032) that reconcile top-down market drivers with bottom-up unit economics.
-
Competitive landscape heatmap — an evidence-based assessment of product portfolios, technology roadmaps, go-to-market strategies, and manufacturing footprints for leading tobacco groups and EMS suppliers.
-
Supplier and component scorecards — qualitative and quantitative ratings for heating element producers, precision component manufacturers, and contract assemblers, including risk indices for tariffs, single-source exposures, and inventory velocity.
-
Commercial playbooks — tested approaches for field trials, retail conversion (including demo and trial mechanics), pricing strategies under different regulatory tax regimes, and aftermarket/replacement channel optimization.
-
Regulatory tracker and scenario suite — line-by-line interpretive guidance on how major jurisdictions’ tobacco product frameworks could influence product configuration, labeling, and permissible marketing tactics through 2026 and beyond.
-
Transaction advisory annex — valuation sensitives and negotiation levers for M&A or strategic supply agreements, informed by our market-concentration analysis and forecasted margin trajectories.
Competitive dynamics: who matters and why
Assessing competitive intent requires reading beyond devices to the capabilities behind them. The market’s top commercial players — leading multinational tobacco groups and specialized EMS partners — pursue complementary but distinct strategies.
-
Global tobacco leaders are focusing on ecosystem control. Major groups have moved from single-device concepts to platform plays that combine proprietary heating technologies, tailored consumables, and branded retail experiences. Recent product rollouts and targeted market expansions demonstrate an emphasis on rapid consumer adoption through trial mechanics and hybrid channel strategies.
-
Electronics manufacturers and contract assemblers are the structural enablers. Tier-1 EMS firms and regional precision manufacturers provide the scale, quality control, and cost engineering necessary to move from boutique production to mass supply. Their willingness to co-invest in tooling, IP-protected subsystems, and localized assembly is a primary determinant of who can price, iterate, and deliver at scale.
-
Specialized component suppliers and niche entrants remain critical for differentiation. Firms that control advanced heating element materials, induction modules, or high-reliability connectors can create effective switching costs — which is why manufacturing partnerships and long-term purchase agreements are now central bargaining chips.
Recent market moves and strategic implications
Notable 2024–2025 developments — including flagship product launches and geographic rollouts — confirm the top players’ intent to treat HNB as a core business line. These tactical initiatives have three strategic consequences for 2026 planning:
-
Speed-to-market is a competitive lever. Publicized product launches and trial campaigns show that consumer adoption can be accelerated through concentrated local activations; consequently, companies that can align channel readiness with localized manufacturing will convert trials into sustainable share faster.
-
Market entry is costly but defensible. Launches in developed markets signal both opportunity and constraint: the latter driven by regulatory scrutiny and tariff exposure. Cost-plus models without supply-chain hedging will compress margins where import duties apply.
-
Brand and device ecosystems are becoming the battleground. Device hardware alone is not the moat — integrated consumable availability, retail experience, and post-sale service are the elements that determine retention and lifetime value.
Regulation, tariffs, and materials: operational risks to prioritize
Three cross-cutting pressures will materially influence decisions in 2026:
-
Regulatory frameworks: Jurisdictions that have codified pathways for HNB products create commercialization opportunity, but compliance obligations (product disclosures, testing regimes, and marketing limits) materially affect time-to-revenue and go-to-market design. Companies should plan regulatory submission timelines as critical path milestones.
-
Trade and tariff exposure: Import levies on electronic components can materially shift landed costs. Our clients should evaluate manufacturing localization or near-shore assembly to mitigate tariff impact and shorten replenishment cycles.
-
Raw material availability: Although general stabilization has occurred versus the acute shortages of prior years, procurement complexity remains elevated. Component lead times and material premiums should be stress-tested in any supply agreement or capacity expansion plan.
Actionable recommendations for 2026
Based on our integrated modeling and vendor assessments, PW Consulting recommends a prioritized set of actions for executives formulating their 2026 agendas:
-
Adopt a dual-sourcing manufacturing posture. Maintain a fast-follow capacity capability in low-capex facilities while securing long-term partnerships with tiered EMS partners for volume scale and cost optimization.
-
Invest in modular device architectures. Designing platforms that decouple heating modules from control electronics reduces obsolescence risk and shortens new-format commercialization cycles.
-
Implement conditional go-to-market pilots. Run geographically bounded trials that mirror the regulatory complexity and supply constraints of target rollouts — and use those pilots to refine channel economics and post-sale service models.
-
Prioritize regulatory and trade scenario planning. Integrate legal and policy milestones into the commercial roadmap and model tariff-driven cost offsets so pricing and margin targets remain robust under adverse scenarios.
-
Explore strategic partnerships over outright vertical integration when speed-to-market and capital efficiency are paramount. Joint development agreements with specialty component suppliers and EMS firms can secure priority capacity without the full burden of asset ownership.
What we conceal here — and why you should read the full report
In keeping with our “trailer” approach, this briefing intentionally surfaces strategic conclusions and high-level data points to build confidence and stimulate action — but it does not disclose the granular subsegment splits, regional share tropes, or proprietary unit-cost tables that underlie our valuation. Those detailed breakouts — including detailed technology mixes, channel economics, supplier-level pricing, and scenario-sensitive financial models — are proprietary to the full PW Consulting HNB Heater Market report and are indispensable for transaction-level decisions, tender bids, and market-entry timing.
If your 2026 strategy requires precise inputs — whether for capital allocation, M&A diligence, or operational playbooks — the full dataset and model will materially reduce execution risk and improve deal outcomes.
Conclusion: positioning for the next wave
As the HNB heater market transitions from demonstration to durable commercialization, the strategic imperative for 2026 is clear: act where you can secure supply, design platforms for iteration, and engage regulators proactively. The sector’s growth profile, underpinned by a sustained mid-single-digit-plus CAGR through the 2026–2032 forecast window, rewards disciplined deployment of capital and a bias toward operational resilience. Companies that move first to lock priority supply, optimize manufacturing footprints, and orchestrate retail-to-aftermarket ecosystems will convert market growth into durable economic returns.
PW Consulting’s comprehensive report — anchoring its base year in 2025 and spanning historical trends (2020–2025) and forward-looking scenarios (2026–2032) — is built to be the playbook for executives who must translate market potential into realized advantage. For access to the full modeling, competitive scorecards, and executable annexes, please consult the official report page.
For detailed analysis of this topic, please visit the official page: HNB Heater Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flexible Surgical Robot Market Hits USD 620 Million in 2025, Poised for Rapid Expansion
By pmarketresearch, 2026-08-18
Flexible Surgical Robot Market 2026: Strategic Imperatives for Executives
PW Consulting’s new market study on Flexible Surgical Robots positions 2026 as the inflection year for strategic decisions across medtech OEMs, hospital systems, investors, and policy makers. Our analysis shows the flexible surgical-robotics sector moving from a promising niche into a commercially meaningful market: the industry is forecast to grow from a 2025 base of USD 620.0 million to roughly USD 1.6 billion by 2032, reflecting a compound annual growth rate (CAGR) of 14.5% over the 2026–2032 forecast period. That trajectory is underpinned by accelerating clinical validation, focused capital deployment, and emerging reimbursement and regulatory frameworks that collectively lower adoption barriers.
Worldwide Open Peripheral Pump Market
Why 2026 Matters: Convergence of Clinical, Capital, and Policy Catalysts
Several concurrent dynamics elevate 2026 from a planning year to a decisive year for resource allocation and strategic repositioning. Clinically, flexible platforms are moving from feasibility and early efficacy demonstrations to multicenter trials and more complex procedures. Industry capital flows are following: venture and strategic funding rounds have expanded R&D runway for differentiated platforms. Regulators and payers are, in parallel, crystallizing the environment for commercialization—clarifying pathways and early reimbursement signals that materially affect hospital purchasing decisions.
Atosiban Acetate API Market
- Clinical validation acceleration: First-in-class clinical milestones and Institutional Review Board–backed trials are enabling stronger surgeon acceptance and establishing comparative-effectiveness hypotheses for follow-on studies.
- Targeted capital deployment: Follow-on rounds and strategic investments are concentrating on platforms that can convert clinical wins into repeatable, cost-effective workflows.
- Regulatory & reimbursement tailwinds: Recent regulatory activity emphasizes modular, indication-specific flexible designs, while new CPT codes and payer dialogues are creating early pathways to monetize advanced procedures.
Market Structure and Competitive Dynamics
The flexible surgical-robotics market is already displaying a clear structure: innovation is concentrated among a handful of technology-driven entrants and a few established strategic players that leverage distribution scale. Our concentration analysis highlights this consolidation: the top three firms account for roughly 58% of the market, and the top five approach 77%, signaling both a high barrier to scale and concentrated competitive power among incumbents and well-funded challengers.
Smart Power Line Inspection System Market
Key company archetypes identified in the report illustrate strategic variety:
- First-mover, indication-focused innovators: Companies developing platform technologies that enable specific endoluminal or single-incision procedures. These firms emphasize clinical trials, modular instrument suites, and direct surgeon engagement to establish clinical utility.
- Miniaturization and component specialists: Entrants that focus on sub-millimeter to millimeter-scale actuation and flexible instrumentation—positioned as upstream suppliers or niche-system OEMs with easier integration into existing endoscopes.
- Platform-and-channel incumbents: Larger medtech companies that incorporate flexible capabilities into broader portfolios and leverage global sales channels to accelerate adoption for high-volume indications.
Representative companies and recent developments are discussed in our competitive dossier. Highlights to note include early pivotal procedures and significant funding rounds that materially de-risk product advancement and commercial scale-up, as well as regulatory milestones that validate clinical trial pathways for flexible platforms.
What the Report Contains: Operationally Actionable Intelligence
PW Consulting’s report is built as a decision-support toolkit for 2026 initiatives. It blends quantitative market sizing with qualitative frameworks so that each class of stakeholder can convert insight into action without wading through raw datasets alone. The report’s operational elements include:
- Top-line market sizing and seven-year forecasts (2026–2032), including scenario-tested downside and upside cases tied to clinical and reimbursement milestones.
- Technology deep-dives that map platform architectures, instrument modalities, and integration vectors—highlighting where performance trade-offs exist (e.g., dexterity versus miniaturization) and which approaches are clinic-ready.
- Clinical evidence inventory and trial-mapping, pinpointing the lead indications, trial phases, and time-to-evidence thresholds that matter for hospital adoption.
- Regulatory and reimbursement playbooks that translate FDA pathways and CPT developments into commercialization timelines and pricing levers.
- Buyer economics and hospital procurement modeling that incorporate capital cost, maintenance, and per-procedure disposables—enabling ROI gates tied to volume thresholds and reimbursement realization.
- Competitive landscaping and capability matrices for leading firms, with strategic scenarios including M&A targets, partnership archetypes, and white-space opportunities.
- Go-to-market blueprints for OEMs and service providers, including a channel assessment, surgeon training pathways, and institutional adoption roadmaps.
To preserve competitive integrity and invite deeper engagement, the report intentionally provides rich, actionable frameworks while the full granular segmentation tables and line-item forecast sheets (region-by-region, mechanism-by-mechanism, and application-level dollars) are available through our primary subscription channel.
Strategic Implications by Stakeholder
PW Consulting synthesizes the market implications into clear strategic moves for the primary stakeholders who need to act in 2026.
- OEMs and new entrants: Prioritize platforms that can demonstrate both procedure-level clinical advantage and manageable unit economics. Invest in second-order capabilities—data connectivity, modular disposables, and service models—that convert single-procedure wins into recurring revenue.
- Hospital systems and health networks: Develop cross-disciplinary adoption committees that assess flexible-robotic propositions against full cost-of-care metrics. Negotiate bundled agreements that align device procurement with shared-savings on reduced length-of-stay and complication avoidance.
- Investors and strategic acquirers: Focus on firms that combine technical differentiation with a credible clinical pathway—evidence of multicenter trials, regulatory momentum, and early reimbursement discussions materially de-risks exit timing.
- Payers and policy-makers: Engage earlier with evidence-generation strategies to define coverage positions and payment levels that incentivize high-value uses without promoting inappropriate utilization.
- Component suppliers: Lock in dual-sourcing and scalable manufacturing capacity now; lead times for miniaturized, flexible components will create bottlenecks as adopters move from pilot to scale.
Priority Moves for 2026 — A Tactical Checklist
- Close clinical-evidence gaps for highest-potential indications. Target randomized or multicenter comparative studies that speak directly to payer value propositions.
- Build reimbursement playbooks around evolving CPT and CMS signals—translate codes into price-to-procedure models that hospitals can operationalize.
- Design flexible commercial models (lease, subscription, outcome-sharing) to lower upfront capital barriers and align incentives with utilization.
- Secure integrated surgeon training programs and proctorship pathways to shorten time-to-first-case and mitigate early-adopter friction.
- Validate supply-chain robustness by qualifying alternate suppliers for critical flexible-actuation components and disposables.
Risks, Uncertainties, and What to Watch in 2026
Key uncertainties remain: the pace of surgeon training and comfort, the final shape of reimbursement codes and coverage policies, and the economics of disposables versus reusable instrument strategies. Our sensitivity analyses identify three high-impact triggers that could alter the growth path materially: large-scale comparative trials showing unequivocal clinical or economic benefit; adverse reimbursement determinations; and supply-chain constraints that raise per-procedure costs beyond hospital thresholds.
Conclusion — The Strategic Value of the Report for 2026
Decision-makers need market intelligence that is both rigorous and operationally directive. PW Consulting’s Flexible Surgical Robot Market report offers precisely that: a clear forecast rooted in up-to-date clinical and regulatory signals, competitive mapping that reveals where market power is consolidating, and a tactical playbook for converting technological promise into commercial adoption. For executives preparing 2026 budgets, R&D roadmaps, or M&A strategies, the report provides the evidence-based frameworks and scenario models needed to make confident, time-sensitive choices.
For organizations ready to move from inquiry to implementation, PW Consulting’s full dataset and consultative briefings will map out the granular segmentation, unit-economics worksheets, and tailored go-to-market models necessary to operationalize a 2026 strategy. Contact PW Consulting to arrange a briefing and access the complete forecast model and proprietary scenario tools.
For detailed analysis of this topic, please visit the official page: Flexible Surgical Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 6.25% CAGR for Global ESD Grounding Mats Market Through 2032
By pmarketresearch, 2026-08-18
ESD Grounding Mats Market — Strategic Imperatives for 2026: PW Consulting Executive Brief
As manufacturers, procurement leads, and strategic planners prepare capital and product roadmaps for 2026, the ESD grounding mats market is asserting itself as a quietly dynamic segment with clear implications for operations, compliance, and margin management. PW Consulting’s latest market study — synthesizing historical performance through 2025 and forward-looking scenarios to 2032 — provides the evidence base organizations need to make prioritized, risk-aware decisions next year. This executive brief outlines the report’s strategic value, highlights the forces shaping 2026 decision windows, and offers a concise playbook for executives. (Note: this preview demonstrates analytical depth while reserving the full segment-level detail for the full report.)
Fuke Zhidai Pian Market
Market snapshot: growth trajectory and competitive structure
The ESD grounding mats market has shown steady expansion over the past half-decade, increasing from an estimated USD 235.0 Million in 2020 to USD 315.5 Million in 2025. Our base-case forecast projects continued expansion in 2026 and beyond, with the market expected to reach approximately USD 332.6 Million in 2026 and to grow to roughly USD 482.3 Million by 2032 — reflecting a compounded annual growth rate of about 6.25% across the forecast window. These numbers reflect broad-based demand drivers and moderate pricing power in a market that remains fragmented: the three-largest players account for under one-third of market share, while the top five control less than 40%, indicating room for consolidation, differentiation, and local incumbency advantages.
Luxury Cross Door Refrigerator Market
Why 2026 matters: converging drivers that create a decision inflection
-
Standards and compliance are tightening. ANSI/ESD S20.20 and IEC 61340-5-1 remain the operative frameworks driving procurement specifications. In parallel, guidance such as ANSI/ESD TR20.20 effectively mandates daily verification of footwear and mat grounding systems in many electronics assembly environments — elevating the importance of traceable verification and service-level warranties.
Flip Chip Packages Market -
End-market tailwinds are reinforcing demand. Continued investment in semiconductor and electronics manufacturing capacity, together with medical and aerospace production requirements, underpins steady mat replacement and upgrade cycles.
-
Input-cost pressure is nontrivial. Natural rubber benchmark prices and synthetic rubber indices have firmed, with spot observations showing natural rubber around the USD 2.40/kg mark in parts of Northeast Asia and elevated producer-price indices for synthetic rubber variants. This creates a test case for price recovery mechanisms and material substitution strategies.
-
Product differentiation is shifting from material composition alone to tested, certified systems. The recent rollout of serialized testing and certification kits and the publication of updated selection guides show that customers increasingly value provable, auditable performance over commodity pricing.
What the full report delivers (practical, operational content)
Pitched to support procurement directors, product managers, and corporate strategists, the full PW Consulting ESD Grounding Mats Market report is built around operational utility rather than academic segmentation alone. Key deliverables include:
-
Validated market sizing and forward scenarios (2020–2032) with stress-tested sensitivity to input-cost shocks and demand slippage.
-
Regulatory and test-protocol playbook clarifying compliance obligations (ANSI/ESD, IEC frameworks) and practical verification cadences for shop-floor implementation.
-
Buying and sourcing toolkit: supplier scorecards, total cost of ownership (TCO) models, and contract clauses to manage raw-material pass-throughs and quality warranties.
-
Commercial templates for service-led monetization: certification-as-a-service, serialized test records, and aftermarket replacement programs.
-
Acquisition and partnership screening — a prioritized list of capabilities that make for attractive tuck-ins or alliances (e.g., test-serialization, localized manufacturing, specialty compound formulations).
To preserve strategic value for decision-makers, the report reserves detailed sub-segment shares and region/application splits for subscribers — providing the directional narrative here while ensuring the full data set remains a decision-enabling asset.
Competitive landscape: what incumbent and challenger strategies tell us
The market features a mix of large diversified industrial players and specialized niche manufacturers. Leading examples demonstrate how different strategic postures shape market positioning:
-
Desco Industries Inc. (incl. SCS) — a long-standing leader offering ANSI/ESD-compliant vinyl and rubber dissipative products and a strong technical messaging play around standards adherence. Strengths: established channel relationships, recognized compliance expertise, vertical product range for worksurfaces and floors.
-
ACL Staticide Inc. — known for resilient dual-layer and homogeneous mat constructions with chemical and heat resistance. Strengths: product engineering and laboratory-oriented value propositions that appeal to high-reliability verticals.
-
Botron Company Inc. — differentiates with multi-layer rubber designs (including exclusive 3-layer constructions) and ergonomics-focused floor mat offerings. Strengths: durability claims and ergonomic product development.
-
NoTrax (Justrite Safety Group) — brings broader industrial safety portfolio leverage to ESD anti-fatigue and anti-static mat lines, enabling bundled safety+ESD offers to manufacturing customers.
-
3M — leverages its larger static-control portfolio and distribution reach to sell integrated ESD protection solutions; strength is the ability to package mats with broader ESD program services and materials.
Recent industry moves underscore a growing emphasis on certification and selection guidance: in December 2025 a vendor introduced serialized, individually-certified bench mat kits; in early 2026, a prominent mat supplier published an updated selection guide aligned with IEC 61340; and in 2025 a technical body released practical testing-frequency guidelines. These trends favor suppliers who can combine product quality with traceable verification and buyer education.
Strategic playbook for 2026 (prioritized actions)
-
For manufacturers: Move from a pure product-sale model to a product-plus-certification model. Invest in serialized testing capability, certificate management platforms, and clearly marketed verification services. This supports premiuming and lowers price elasticity.
-
For procurement: Reassess sourcing strategies to mitigate rubber-price risk: negotiate flexible index-linked pricing, introduce multi-year hedges where appropriate, and evaluate alternative compounds (SBR/EPDM blends) with full TCO analysis that includes lifecycle replacement and compliance costs.
-
For product leaders: Prioritize modular mat systems that reduce SKU complexity while allowing customization for key verticals (electronics, aerospace, healthcare). Consider anti-microbial and wipe-down-friendly laminates for healthcare and lab environments as a differentiator.
-
For investors / M&A teams: Target acquisitions that provide serialized testing capabilities, local manufacturing footprints in high-growth manufacturing clusters, or proprietary compound formulations. Given the market’s fragmentation and sub-40% top-five concentration, well-executed tuck-ins can quickly accrete market share and margin.
-
For compliance and operations teams: Formalize daily verification routines and digital record-keeping consistent with ANSI/ESD TR20.20 guidance. Building transparent audit trails not only reduces failure risk but creates aftermarket services opportunities.
Investment implications and risk management
-
Opportunities: Service-led revenue streams (certification, scheduled testing), premium differentiated materials, and consolidation-driven margin expansion.
-
Risks: Input-cost volatility (natural and synthetic rubber), regulatory non-compliance exposures, and margin compression from low-cost global entrants. The supply-chain impact of rubber-price inflation is tangible and calls for contract-level mitigants and supplier diversification.
-
Mitigants: Indexed pricing clauses, dual sourcing, localized production where logistics and lead-time sensitivity demand it, and product warranties tied to documented verification regimes.
How PW Consulting’s report supports 2026 decision cycles
Leaders must balance near-term operational resilience against medium-term strategic positioning. Our report converts market forecasting into executable decision support: scenario-tested budgets for capital procurement, prioritized product investments, and a short list of candidate targets for inorganic growth. Importantly, it provides templates you can operationalize within 60–120 days across procurement, compliance, and product teams.
For teams that require immediacy: the report’s appendices include sample contract language for raw-material pass-throughs, a compliance verification checklist aligned to ANSI/ESD and IEC standards, and a supplier scorecard tailored to evaluate both product performance and service capability (including the ability to deliver serialized certification).
Conclusion — the tactical horizon for 2026
2026 will reward organizations that convert compliance pressure and material-cost volatility into structured commercial advantage. Those that unify product quality with auditable verification, hedge input risks, and pursue selective capability acquisitions will capture outsized share and margin gains. PW Consulting’s full ESD Grounding Mats Market report is designed to be an operational companion for those moves — delivering the proprietary sub-segment data, supplier maps, and scenario toolkits that are intentionally summarized here to preserve strategic utility.
Access the full analysis to obtain the detailed regional, material, and application breakdowns, along with the proprietary models we used to stress-test 2026 scenarios. PW Consulting stands ready to support tailored strategy workshops, acquisition screening, and procurement playbook rollouts to translate insight into action.
For detailed analysis of this topic, please visit the official page: ESD Grounding Mats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Orlistat Capsules Market Poised to Reach USD 280.05 Million by 2032, Growing at a 3.85% CAGR
By pmarketresearch, 2026-08-18
Orlistat Capsules Market: Strategic Imperatives for 2026 — Executive Brief from PW Consulting
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused synthesis of our latest Orlistat Capsules Market research — the authoritative briefing designed to inform board-level strategy and commercial planning in 2026. Grounded in a base-year assessment (2025) and a validated historical series (2020–2025), the study projects the market through 2032 and quantifies a steady compound annual growth rate of 3.85% across the forecast horizon. The global market stood at USD 215.0 Million in 2025 and, under our central scenario, is projected to expand toward a market size consistent with USD 280 Million by 2032. This brief outlines the strategic value of the full report and highlights the near-term actions executives should prioritize — preserving analytical depth while withholding full segment-level tables to encourage direct access to the source report for transaction-grade data.
End-Of-Life Vehicle Recycling Equipment Market
Market Snapshot: What the headline numbers tell executives
-
Measured, resilient growth: Our baseline projection assumes a mid-single-digit structural expansion (CAGR 3.85%) driven by continued obesity-management adoption, channel shifts (notably digital pharmacy penetration), and an active generic/manufactured supply base.
Worldwide Neodecanoic Acid Market -
Two-pill economics: The market dynamics remain shaped by a dual ecosystem of prescription-strength branded legacy products and OTC lower-dose offerings — each demands a different commercial and regulatory playbook.
Photography Continuous Lighting Market -
Supply-side tailwinds: Industry sourcing trends, including a measurable decline in API production costs late in 2025, are creating an operational window for margin recovery and price-competitive market entry.
Strategic imperatives for 2026 (what boards and BU heads should act on now)
-
Prioritize portfolio clarity: Segregate assets into defense, harvest and invest buckets. Prescription-branded heritage assets require regulatory support and payer negotiation; OTC offerings need robust brand-protection and e-commerce plans.
-
Lock in raw-material advantages: The late-2025 easing of orlistat API costs changes capital allocation calculus for manufacturing expansion and contract manufacturing negotiations. Time-limited procurement contracts and hedged sourcing should be considered.
-
Design channel-specific GTM: Retail pharmacy, hospital channels and online pharmacies demand differentiated pricing, packaging and anti-counterfeit measures. Executives must quantify channel-level ROI before committing salesforce and marketing spend.
-
Strengthen IP and brand-defense posture: Historical patent expirations have opened the market to generics; active brand and distribution protection — including digital monitoring for counterfeit products — are non-negotiable for OTC marketers.
-
Embed payer and HTA engagement: Prior authorization rules and BMI-based coverage criteria require early payer evidence strategies, targeted real-world evidence generation and outcomes-based contracting pilots for prescription products.
-
Reassess M&A and partnership timing: Moderate market concentration leaves space for bolt-on manufacturing plays, licensing agreements and regional distribution partnerships. Use a playbook-driven screening to prioritize targets with WHO‑GMP credentials and proven export capability.
-
Operationalize scenario planning: Build three-to-five-year capacity and pricing scenarios to stress-test margin resilience against generics incursion, API price swings and evolving channel mix.
What the PW Consulting report delivers — practical components for execution
-
Executive Decision Deck: Board-ready takeaways, prioritized initiatives and a 90-day action plan keyed to 2026 milestones.
-
Market Sizing & Forecast Methodology: Transparent modeling, assumptions and sensitivity analyses (base, upside, downside) covering 2026–2032.
-
Commercial Playbooks: Channel-specific go-to-market templates for retail, hospital and online pharmacy channels, including launch, pricing and promotional levers.
-
Competitive Benchmarking: Deep profiles of incumbent and emerging manufacturers and distributors, including product positioning, distribution rights and recent corporate moves.
-
Regulatory & Payer Roadmap: A concise matrix of approval status, reimbursement triggers and payer requirements — with recommendations for dossier sequencing and evidence generation.
-
Supply Chain & Sourcing Playbook: Actionable guidance on API procurement, contract manufacturing partner selection, capacity planning and quality assurance measures.
-
M&A & Partnership Due Diligence Kit: Templates, valuation heuristics and integration checklists tailored to the Orlistat value chain.
-
Financial Models & Sensitivity Templates: NPV, IRR, break-even and scenario-based dashboards to support investment committees and transaction teams.
-
Implementation Toolkit: Cross-functional KPIs, a phased roll-out timeline and workshop-ready materials to operationalize strategy across commercial, regulatory and supply functions.
Competitive landscape — focused intelligence without the raw tables
-
Brands and rights holders: The market continues to be influenced by legacy branded assets and rights transfers. A notable example is the stewardship of a long-standing 120 mg branded prescription product by an established European-origin rights holder, with an affiliated U.S. distributor controlling exclusive U.S. prescription-channel commercialization.
-
OTC leadership: Consumer-facing 60 mg OTC offerings are managed by a major consumer-health player with deep retail distribution and direct-to-consumer marketing capability; protecting trust in that channel is critical after reported counterfeit incidents in digital marketplaces.
-
Manufacturing & exports: Several India-based manufacturers operate WHO‑GMP certified facilities and are active exporters; these players present low-cost supply and contract-manufacturing alternatives for market entrants seeking rapid scale.
-
Historical developer and legacy IP: The product’s originator remains a useful historical reference for clinical positioning and brand equity despite rights having changed hands over time.
-
Recent developments that matter: Regulatory label updates by U.S. distributors (early‑2026) and counterfeit alerts affecting OTC channels (mid‑2025) have immediate commercial and reputational implications for channel strategy, risk monitoring and post‑market surveillance.
Implications of regulatory and market dynamics
-
Prescription vs OTC segregation: The split in dispensing regimes requires parallel but distinct evidence, pricing and distribution strategies. Prescription products are subject to payer access constraints; OTC products face consumer-safety and counterfeiting exposures.
-
Generics environment: The historical expiration of early patents created a generics base that compresses price over time. Successful incumbents will need to compensate through value-added services, branded generics strategies or channel control.
-
Payer thresholds: Prior authorization and BMI criteria used by payers make a case for investing in real-world evidence and targeted outcome studies to preserve formulary access for prescription therapies.
Methodology & data credibility
-
Base period and forecast: The report uses 2025 as the base year, a validated historical window (2020–2025), and a forecast period through 2032. Our central projection incorporates a 3.85% CAGR for the forecast horizon and is stress-tested across alternative demand and pricing scenarios.
-
Data sources: The analysis integrates primary interviews with commercial and regulatory leaders, proprietary pricing and trade datasets, publicly filed regulatory documents, company disclosures and targeted supply-chain intelligence.
-
Quality control: All figures and models were subject to multi-stage validation, including crosswalks against national drug registries, distributor shipment data and independent API cost indices.
How to use this intelligence in 2026 — three immediate use cases
-
Procurement and capacity planning: Use the report’s supply‑side scenario outputs to renegotiate API and contract manufacturing agreements now, locking in favorable terms before demand re-acceleration windows.
-
Commercial defense play: For branded prescription holders, deploy the payer engagement and evidence-generation roadmap to mitigate prior-authorization leakage and protect unit economics.
-
OTC channel protection: For consumer-health teams, implement the anti-counterfeiting and digital marketplace monitoring recommendations included in the report to preserve brand trust and retail partner confidence.
What’s not in this brief — and why you should consult the full report
-
This executive summary intentionally omits granular regional and application-level percentage breakdowns, full competitive share tables and downloadable financial models — elements included in the full PW Consulting report that are necessary for transaction diligence, tender response preparation and M&A valuation work.
-
If you are preparing a market entry, divestiture, licensing negotiation or capital allocation decision in 2026, the full data packs, scenario models and operational checklists are indispensable and available through our client portal or by contacting PW Consulting’s commercial team.
PW Consulting’s Orlistat Capsules Market report is designed to convert market intelligence into executable decisions. For access to the complete dataset, segmented forecasts, company scorecards and the transaction-ready financial models referenced here, visit the PW Consulting report page or contact your account director to arrange a licensed copy and an implementation workshop tailored to your priorities for 2026.
For detailed analysis of this topic, please visit the official page: Orlistat Capsules Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Handheld Arthroscopic Instrument Market to Rise from USD 2,550 Million in 2025 to USD 3,885.19 Million by 2032 at a 6.2% CAGR
By pmarketresearch, 2026-08-18
Handheld Arthroscopic Instrument Market: Strategic Imperatives for 2026 — PW Consulting Report Highlights
PW Consulting’s new market intelligence brief on the Handheld Arthroscopic Instrument market provides senior leaders with the forward-looking evidence they need to set winning strategies in 2026. Drawing on a rigorous historical analysis (2020–2025) and a detailed forecast horizon (2026–2032), the report quantifies the market’s trajectory, isolates commercial inflection points, and converts clinical and regulatory dynamics into executable options for device OEMs, investors, and health system procurement teams.
Zinc-O,O-Dibutyl Phosphorodithioate Market
Why this report matters for 2026 decision-makers
- Clear growth vector: the global market, measured at USD 2,550 Million in our base year (2025), is projected to expand at a compound annual growth rate (CAGR) of 6.2% through the forecast period — reaching roughly USD 3,885 Million by 2032. This steady momentum frames near-term product, channel, and M&A choices.
- Actionable, scenario-based guidance: instead of high-level commentary, PW Consulting provides playbooks that translate market trends into prioritized initiatives for product development, commercial deployment, and partnering in 2026.
- Competitive clarity without overexposure: the market is meaningfully consolidated, with a clear top-tier of incumbent device manufacturers and a smaller, dynamic cohort of specialist innovators. Our assessment shows where scale protects margins and where agility unlocks white-space opportunities.
Executive takeaways — what senior leaders will use
- Portfolio prioritization: identify which handheld capabilities to accelerate (e.g., articulating tools, powered resection adjuncts, and minimally invasive access systems) and where to defer investment until clinical adoption curves steepen.
- Go-to-market calibration: an evidence-backed framework for allocating commercial investment between direct sales, distributor partnerships, and bundled procedure-supply models that optimize hospital procurement economics.
- Supply chain resilience: a supplier-risk matrix focused on critical inputs (medical-grade stainless steels, precision machining, and sterilization consumables) and mitigations for single-source dependencies.
- Regulatory & reimbursement alignment: mapping device design and labeling priorities to real-world sterilization expectations and common arthroscopy billing pathways, enabling smoother adoption and reimbursement capture.
Market trajectory and the strategic horizon (2026–2032)
PW Consulting’s modeling accounts for demographic tailwinds, procedural volume growth in minimally invasive orthopedics, and incremental technology-driven adoption. With a 6.2% CAGR embedded in our base-case scenario, the market presents a reliable expansion environment rather than a volatile boom-or-bust cycle. This implies that near-term strategic moves—optimization of product portfolios, selective capital deployment, and targeted M&A—will compound value over a multi-year window rather than delivering instant, high-risk returns.
Smart Motion Sensor Light Market
Competitive landscape: incumbents, challengers, and specialist innovators
The handheld arthroscopic instrument arena combines global device powerhouses with nimble specialists. Our competitive mapping categorizes participants by technical breadth, commercial reach, and innovation velocity:
Fully Automatic Thermal Analyzer Market
- Global OEMs with broad portfolios: Companies such as Arthrex, Smith+Nephew, Stryker, CONMED, KARL STORZ, Zimmer Biomet, Medtronic, and Johnson & Johnson (DePuy Synthes) maintain extensive product families and deep institutional relationships—advantages for scale-driven pricing, bundled product offerings, and penetration into major health systems.
- Specialists and disruptors: Firms like Joint Preservation Innovations (JPI) and Richard Wolf demonstrate how focused product innovation can create first-mover clinical differentiation. Notably, JPI secured FDA 510(k) clearance in December 2025 for an articulating rotary cutting instrument designed to address bone access in tight joint spaces — an example of how targeted engineering can open new clinical pathways.
- Strategic implications: incumbents will continue to defend core channels and high-volume indications while partnership or tuck-in M&A remains the most efficient route to acquire articulation, single-use solutions, or novel ergonomic designs from smaller innovators.
Technology, clinical practice, and regulatory dynamics
- Technology convergence: incremental advances — miniaturized articulation, refined powered resection tools, and improved ergonomics — are creating tangible usability improvements that shorten learning curves and reduce procedure times. These improvements translate directly to procurement conversations centered on total procedure cost and surgeon productivity.
- Sterilization and reprocessing pressures: CDC guidance and hospital infection-prevention protocols continue to shape device design choices. Reusable handheld instruments that enter sterile sites must meet sterilization or high-level disinfection expectations in many markets; this reality drives demand for corrosion-resistant materials and serviceable designs that ease reprocessing burden.
- Reimbursement context: common CPT coding practices for arthroscopic procedures influence hospital economics and provider willingness to adopt incremental-cost technologies. Aligning product value propositions to established billing pathways accelerates uptake and shortens procurement cycles.
Commercial playbooks for 2026
PW Consulting provides multiple modular playbooks designed for use in corporate planning cycles and board discussions:
- Fast-follower playbook — For mid-sized players: prioritize acquiring or licensing high-impact ergonomic improvements and focus commercial efforts on specialty centers to establish proof points and case-series outcomes.
- Scale-defend playbook — For incumbents: double down on bundled procedure offers, service contracts, and integrated training programs that lock in institutional adoption while evaluating tuck-in acquisitions to fill surgical gaps.
- Disruptor playbook — For startups and medtech VCs: target niche surgical indications where articulation or miniaturization unlocks clear clinical advantage; leverage regulatory milestones and targeted clinical publications to create acquisition visibility within 18–36 months.
Report contents — what’s inside the full PW Consulting study
The published report goes beyond market numbers to deliver practical tools and evidence that can be used immediately in strategic planning:
- Robust historical demand analysis (2020–2025) and transparent forecasting methodology for 2026–2032, including sensitivity and scenario models.
- Clinical adoption pathways and surgeon preference mapping that explain uptake differentials across device features and procedural types.
- Regulatory and reimbursement playbook — a concise guide for labeling, clinical evidence generation, and CPT-code alignment to support payer conversations.
- Vendor benchmarking and go-to-market frameworks that combine commercial KPIs with tender and contract negotiation tactics.
- M&A target-screening criteria and valuation yardsticks tailored to the market’s current consolidation dynamics.
- Supply chain risk assessment and recommended mitigations for sourcing medical-grade materials and precision manufacturing capacity.
- Confidential annexes — including operational scorecards, unit economics templates, and interview-sourced insights from hospital procurement leaders and orthopedic surgeons (available to licensed report holders).
How PW Consulting converts data into decisions
The hallmark of this study is prescriptive clarity. Each chapter concludes with a short list of recommended decisions that senior leaders can action within 90, 180, and 360 days. Examples include tactical pricing adjustments to protect margin while defending hospital tender wins, near-term product development bets that de-risk clinical adoption, and a prioritized list of capabilities suitable for bolt-on acquisition.
Methodology and credibility
Our conclusions are sourced from a triangulation of primary interviews, surgical procedure databases, hospital procurement surveys, and manufacturer disclosures, cross-validated with market-level financial modeling. The report’s base year is 2025, and our forecast covers 2026–2032 — allowing readers to align strategic initiatives with corporate planning cycles and capital budgets set in 2026.
Next steps — using the insight to act in 2026
- Leadership teams: use the report’s scenario toolkit to test how different commercial investments affect market share and margin across a 3–5 year horizon.
- Product & R&D heads: draw on the clinical insights to prioritize features that reduce OR time, improve reprocessing workflows, or enable new procedural approaches.
- Corporate development teams: leverage the M&A screening criteria to shortlist acquisition targets that deliver immediate capability expansion without disrupting core operations.
- Procurement and hospital administrators: utilize the total-cost-of-ownership frameworks to renegotiate contracts and evaluate supplier consolidation strategies.
Read the full analysis
PW Consulting’s Handheld Arthroscopic Instrument Market report is structured to support decision-making across functions and to serve as the 2026 playbook for growth, defense, and selective disruption. For executives seeking the full datasets, confidential annexes, and the step-by-step implementation roadmaps, please visit PW Consulting’s market reports page to access the complete document and licensing options.
For detailed analysis of this topic, please visit the official page: Handheld Arthroscopic Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Whetstones Market Tops USD 148.5 Million in 2025 — Poised for Continued Growth Through 2026–2032
By pmarketresearch, 2026-08-12
Whetstones Market 2026 Preview: Strategic Imperatives for Corporate Leaders
PW Consulting’s new Whetstones Market report — the Whetstones Market chapter of our Whetstones Market series — synthesizes five years of market behaviour (2020–2025) and offers a forward-looking, scenario-ready forecast through 2032. This briefing distils the clearest takeaways that will matter to procurement directors, product managers, manufacturing strategists, channel leaders and M&A teams making decisions in 2026. We show why the next 18 months are decisive, identify where margin and resilience can be won, and explain which signals you must track to keep strategy aligned to a market growing at mid-single digits.
Electrolytic capacitor paper Market
Market at a glance (what matters)
- The global whetstones market is a modest, mature hardware segment measured in USD (Million). After rising from the low triple digits into the mid‑hundreds during the 2020–2025 period, the market is forecast to grow throughout 2026–2032 at a compound annual growth rate of 4.25% under our base scenario.
- PW Consulting’s baseline model projects continued measured expansion through 2032, driven by a mix of consumer premiumization, steady professional demand, and selective industrial replacement cycles.
- This growth is sufficient to create new return-on-investment opportunities for product innovations and supply‑chain optimization — but not large enough to make undisciplined volume plays profitable without targeted differentiation.
Why this report is strategically material for 2026
- Translate macro momentum into boardroom decisions: our analysis connects headline growth to P&L-sensitive actions—product line rationalization, premiumization of core SKUs, and targeted capacity investments.
- De‑risk raw material exposure: the report maps supply risk for natural novaculite and the principal synthetic abrasives while prescribing hedging, vertical integration and sourcing contingencies.
- Inform M&A and partnership routes: we delineate acquisition targets by capability (quarry access, ceramic R&D, bonded abrasives manufacturing, DTC brands) and quantify where consolidation could meaningfully move the needle.
- Operationalize regulatory and marketing claims: guidance on Made in USA compliance and labeling prevents reputational and legal drag while unlocking premium pricing for legitimate claims.
What the full report delivers (practical, implementable content)
- Transparent methodology and forecast engine: demand drivers, elasticity assumptions, shipment-to-revenue mapping and sensitivity tables that let you stress-test scenarios specific to your cost structure.
- Go‑to‑market playbooks: SKU prioritization, premium framing, channel segmentation (retailers, online DTC, professional distributors), and conversion levers for chef/creator endorsement programs.
- Supply‑chain and raw‑material playbooks: supplier scorecards, supplier concentration risk matrices, inventory policies and near-term procurement play options to secure novaculite and key synthetic inputs such as aluminum oxide and silicon carbide.
- Competitive vendor scorecards and capability maps: qualitative and semi‑quantitative profiles of incumbent manufacturers and specialty producers, benchmarking on integration, innovation, geographic reach, and channel strength.
- M&A scenario templates and valuation pointers: tailored to smaller industrials and specialty consumer brands, including accretion/dilution models, five‑year synergy schedules and integration risk checklists.
- Commercial KPIs and data dashboard templates: recommended leading indicators (review sentiment scores, channel fill rates, professional endorsement velocity) and how to instrument them using third‑party data and internal telemetry.
Market dynamics and structural drivers
The whetstones market is simultaneously traditional and innovation‑rich. Longstanding demand from home cooks and woodworking professionals sits beside fast‑moving innovation in synthetic ceramic and bonded systems that promise speed and consistency. Several structural vectors matter to strategy:
Solid Tumors Target Proteins Market
- Material bifurcation: natural novaculite stones retain authentic value propositions — provenance, tactile heritage and a premium narrative — while synthetic options (aluminum oxide, silicon carbide, ceramic bonds) deliver predictable grit, faster cut rates and manufacturing scalability. Each pathway carries distinct cost, sourcing and marketing implications.
- Supply geography and reserves: proven quarry reserves for specific natural materials are concentrated and, in some cases, controlled by vertically integrated operators. That concentration shapes negotiating leverage and long‑term cost curves.
- Channel and influence effects: editorial testing and chef endorsements (recent product tests in mainstream food media have materially affected consumer consideration) accelerate premium product adoption and create short windows to capitalize on visibility.
- Regulatory and claims risk: rules governing “Made in USA” claims and similar provenance assertions are material to pricing and positioning; non‑compliant claims create financial and reputational risk that must be actively managed.
- Industry fragmentation: the competitive structure is not dominated by a single global integrator — several well‑positioned specialty firms, industrial brands and system providers compete across different customer segments, leaving opportunity for consolidation and capability acquisitions.
Competitive positioning — who matters and why
Our vendor analysis highlights a mix of vertically integrated heritage players, global industrial abrasives manufacturers, high‑performance Japanese specialists and systems providers focused on equipment and workflow integration. A selective summary of strategic positions:
Medical Gas Area Alarm Panel Market
- Dan’s Whetstone Company: quarry ownership and fully domestic manufacturing underpin a strong provenance story and supply control. This model supports premium positioning and margin resilience where authenticity matters.
- Norton Abrasives (Saint‑Gobain): strength in synthetic manufacturing, scale, and industrial channels; suited to customers prioritizing consistency and integration into tool‑level supply agreements.
- SHAPTON and Matsunaga (King brand): Japanese specialists that compete on high‑performance ceramic and waterstone technologies, reputation among professional knife users, and precision‑oriented product engineering.
- Work Sharp, Falcon, NORITAKE, and Gesswein: diverse plays ranging from sharpening systems and benchtop equipment to specialty stone supply for jewellery and toolmakers; they capture non‑commodity parts of the value chain.
Recent editorial and testing coverage in consumer media has elevated certain product lines, creating short windows of accelerated consumer demand. Separately, our competitive maps show that the top handful of firms collectively represent far from overwhelming market control — top players account for a minority share, leaving adjacent pockets open to nimble entrants and consolidation.
Strategic scenarios for 2026 (decision playbook)
Out of our scenario suite, three pragmatic strategies emerge for market participants depending on appetite and capability:
- Protect-and‑premium (for premium consumer brands and vertically integrated producers)
- Pursue provenance certification and storytelling, lock long‑dated supply from key quarries where possible, and invest in chef/creator partnerships to maintain premium ASPs.
- Prioritize quality control systems and customer education programs to reduce returns and increase lifetime value.
- Scale-and‑systematize (for industrial suppliers and large abrasives manufacturers)
- Standardize synthetic product lines, optimize bonded processes and pursue channel partnerships with tool OEMs to embed stones into consumable supply streams.
- Drive cost out via process automation in ceramic and resin bonding operations while selectively acquiring niche brands for channel access.
- Experiment-and‑specialize (for challengers and digital-first brands)
- Target narrow technical niches (e.g., jewelry, woodturning, professional culinary) with high‑margin SKUs, direct content marketing, and rapid iteration informed by reviewer feedback.
- Use subscription and replenishment models to capture recurring revenue from consumable surfaces and finishing products.
Tactical 90–365 day priorities
- 90 days: complete a raw‑material risk assessment and vendor qualification for the next 12–18 months; validate any provenance claims against FTC guidance; run a SKU profitability sweep to identify low-turn inventory candidates.
- 180 days: execute a chef/influencer pilot tied to a premium SKU, instrument customer review tracking, and implement a supplier buffering policy for critical grades.
- 365 days: finalize a one‑year roadmap for product and channel expansion tied to a go/no‑go M&A threshold; operationalize the dashboard KPIs recommended in our report (fill rate, review velocity, ASP by channel, raw material cost delta).
What we recommend you track in 2026
- Editorial and testing cycles in major culinary outlets and specialist trade media — these create outsized episodic demand.
- Raw material supply announcements and long‑term lease activity in known quarry regions.
- New product introductions from ceramic and bonded‑stone specialists that change expected cut/time trade‑offs.
- Regulatory guidance updates related to provenance and origin claims in key consumer markets.
Accessing full intelligence
This release is a director‑level briefing designed to establish the strategic view. The full Whetstones Market report contains the proprietary segmentation tables, regional and application forecasts, vendor scorecards and downloadable model files that are required to execute the playbooks we outline here. If you are planning capital allocation, procurement commitments or acquisition diligence in 2026, the detailed forecasts and supplier evaluations in the full report will materially accelerate and de‑risk those workflows.
PW Consulting is ready to walk your executive team through a tailored briefing that translates these findings into a company‑specific action plan with prioritized initiatives, financial impact scenarios and a monitored KPIs dashboard for 2026. Contact our industry practice to schedule a strategy session and gain access to the complete dataset and forecasting model.
For detailed analysis of this topic, please visit the official page: Whetstones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com