

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Degradable Implants Market to Expand from USD 6.85 Billion in 2025 to USD 11.93 Billion by 2032, Backed by an 8.25% CAGR

PW Consulting Releases Strategic Brief: Degradable Implants Market — A 2026 Playbook for Market Leaders and Challengers
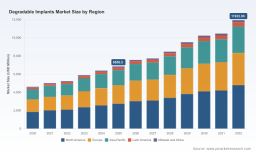
PW Consulting today publishes a strategic briefing drawn from our forthcoming Degradable Implants Market report, designed to equip executive teams with the evidence and decision frameworks they need as they allocate R&D, regulatory and commercial capital in 2026. The degradable implants market has moved from scientific promise to commercial reality: after a market value of USD 4,608.7 million in 2020, PW’s model projects continual expansion—reaching USD 6,850.5 million in 2025 and accelerating into the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 8.25%, with our 2032 projection exceeding USD 11.9 billion. For leaders preparing budgets, partnerships and regulatory dossiers for next year, this report translates high-level growth into executable options while preserving the detailed segment data behind a gated model.
Rare Earth Battery Alloys Market
Why this report matters for 2026 decision-making
- Translating growth into strategy: The macro expansion is real, but winning requires choices—material selection, clinical evidence prioritization and commercialization sequencing—that determine whether a program is accretive or dilutive to enterprise value.
- Regulatory and evidence timing: The regulatory pathway for bioresorbables is now characterized by heightened scrutiny on long-term biocompatibility and mechanical performance across degradation timelines; timing of clinical milestones materially affects market access windows and ROI.
- Supply chain and cost management: Specialized magnesium alloys and precision manufacturing materially raise component costs versus conventional implants; supply concentration in primary magnesium production adds a volatility premium that must be hedged.
- Competitive posture: The market displays a moderate concentration (CR3 ≈ 42.5%; CR5 ≈ 56.8%)—enough room for scale players to defend incumbency but also for focused innovators to create lucrative niches.
What the PW Consulting report delivers (practical outputs)
- Comprehensive market sizing and 2026–2032 forecast with bottom-up and scenario-based projections that isolate demand drivers and sensitivity to reimbursement and pricing.
- Technology and materials mapping—polymers, ceramics, magnesium alloys and emerging biological matrices—linked to manufacturing cost envelopes and scale economics.
- Regulatory and clinical roadmap: stepwise requirements (including ISO 10993 biocompatibility frameworks), recommended study designs to demonstrate mechanical equivalence through degradation, and timing templates for FDA/EMA submissions.
- Supplier and OEM intelligence: vendor scorecards, margin corridor analyses, and contract manufacturing profiles to accelerate production scale-up without compromising regulatory traceability.
- Commercial playbooks: GTM sequencing, hospital procurement strategies, value dossiers for payers and clinicians, and launch KPIs for trauma, orthopedic reconstruction and cardiovascular scaffold applications.
- Deal and investment suite: M&A heatmaps, licensing models, and joint-venture archetypes informed by CR3/CR5 concentration and technology ownership.
- Interactive financial model and data annex (gated): full segment splits, unit economics, and sensitivity levers available to subscribers and licensed users.
Competitive landscape: how incumbents and specialists are positioning
The competitive topology is bifurcating along two axes: large orthopedics/medtech incumbents leveraging commercial reach and regulatory expertise, and specialist innovators driving material-level differentiation.
Paper Coffee Filter Market
- Specialist innovators — Firms such as Bioretec Ltd and Syntellix AG have staked leadership in magnesium-based solutions and are translating clinical-first positioning into regulatory milestones. Bioretec’s RemeOs magnesium alloy portfolio earned the industry’s first FDA De Novo clearance in its class and has since accrued further regulatory momentum (including a Breakthrough Device designation for a RemeOs DrillPin and CE approvals supporting European commercialization). These regulatory achievements shorten commercial lead times for novel metallic resorbable fixation and create a reference set for competitors. Syntellix’s MAGNEZIX line similarly demonstrates how metallic degradables can scale clinically when combined with strong device-level evidence and regional certifications.
- Polymer specialists and platform owners — Companies such as Inion Oy have commercialized polymer-based, bioabsorbable plates, screws and anchors across multiple specialties and boast substantial clinical usage; their strengths lie in integrated polymer platforms and well-developed clinical adoption pathways.
- Large medtech incumbents — Major OEMs (including Medtronic, Johnson & Johnson / DePuy Synthes, Stryker, Zimmer Biomet and Smith+Nephew) are actively incubating or acquiring bioresorbable capabilities to protect franchise value and address surgeon demand for absorption-enabled workflows. These players bring scale in distribution, hospital contracting and payer engagement—critical advantages when converting clinical approvals into unit volumes.
- Cardiovascular niche players — Biotronik’s resorbable scaffold programs underscore that the cardiovascular use-case has a distinct evidence and reimbursement arc compared with orthopedics, requiring dedicated registries and HTA engagement strategies.
Regulatory, material and supply dynamics to watch in 2026
- Regulatory rigor is the new baseline: FDA and EMA expectations now routinely include long-term in vivo degradation studies and proof of mechanical equivalence across the degradation lifecycle; sponsors should budget for multi-year programs and plan staged submissions to sustain investor confidence.
- Magnesium economics and sourcing: Development of medical-grade magnesium alloys increases unit production costs—our analysis shows a meaningful premium relative to conventional materials—and primary magnesium supply is regionally concentrated. China’s dominance in upstream magnesium production drives a potential price and availability volatility that can distort margin models for manufacturers absent mitigation strategies.
- Clinical evidence and HCP adoption: Surgeon familiarity, instrumentation compatibility and real-world registries will be decisive in adoption speed, especially for pediatric and trauma applications where device removal avoidance is a clear clinical value proposition.
Strategic actions for 2026: a practical playbook
- Secure material supply and manufacturing continuity: Negotiate multi-year supply contracts with quality clauses, explore geographic diversification for critical alloys, and assess vertical integration where scale economics justify capex.
- Invest early in degradation-focused evidence: Prioritize preclinical and early clinical studies that demonstrate mechanical competence through critical healing windows—this de-risks reimbursement conversations and accelerates regulatory acceptance.
- Design commercialization pilots intelligently: Launch in clinical centers of excellence to build registry data, refine surgical technique training, and create KOL advocates before broad roll-out.
- Align pricing to differentiated value: Account for production cost differentials (notably for magnesium-based implants) and build payer dossiers that quantify savings from avoided hardware removal, reduced secondary procedures and shortened care pathways.
- Consider partnership-first approaches: For many innovators, licensing to or co-developing with a larger OEM reduces time-to-scale and leverages established sales channels while preserving upside through milestone and royalty structures.
- Model multiple scenarios: Run downside and upside scenarios tied to regulatory timelines, magnesium price shocks and hospital adoption rates; use contingent investment tranches to protect cash runway.
How PW’s intelligence accelerates your 2026 roadmap
Executives who use PW’s degradable implants intelligence gain access to a practical combination of macro forecasts, competitive scorecards and executable playbooks that reduce uncertainty at three critical decision gates: R&D prioritization, regulatory sequencing and commercialization sequencing. The report’s gated models allow clients to interrogate unit economics under custom assumptions—isolating the impact of material costs, scaling efficiencies and pricing strategies on IRR and payback.
Portable LED Light Facial Device Market
Access and next steps
This release is a strategic synopsis designed to demonstrate the report’s analytic depth while preserving the granular segment tables, regional splits and company-level scorecards that form the paywalled core. Firms planning capital allocation, M&A or partnership strategies for 2026 should engage PW Consulting for a tailored briefing and demo of the interactive forecast model.
To request a briefing, licensing terms for the interactive model, or to arrange a private strategy workshop for your leadership team, contact PW Consulting’s Life Sciences Strategy practice. Our consultants can map the outputs of this study to your product portfolio, regulatory timelines and commercial channels so you can move from insight to action in 2026 with confidence.
For detailed analysis of this topic, please visit the official page: Degradable Implants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com