

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: N95 Mask Market Hits $2B in 2025, 8.7% CAGR to $3.49B by 2032

Navigating the N95 Grade Medical Protective Masks Market: A Strategic Overview for 2026 and Beyond
The global landscape for respiratory protection has undergone a fundamental transformation over the past half-decade. What was once a commoditized procurement category has evolved into a critically regulated, clinically essential infrastructure component. As healthcare institutions, industrial operators, and supply chain strategists recalibrate their risk mitigation frameworks, the N95 Grade Medical Protective Masks Market stands at the intersection of public health preparedness, regulatory stringency, and manufacturing capability. This analysis draws from our latest comprehensive market research to outline the structural forces shaping the industry from 2026 through 2032. Readers seeking actionable intelligence, granular segmentation breakdowns, and proprietary forecasting models are directed to the full report, which serves as a foundational decision-support tool for procurement leaders, investor relations teams, and competitive strategists.
Market Trajectory and Structural Drivers
The market has demonstrated sustained expansion since the early 2020s, with historical performance indicating a consistent upward trajectory driven by heightened infection control protocols, occupational safety mandates, and institutional procurement standardization. From a baseline of approximately 1.38 billion USD in 2020, the sector has progressed through successive annual increments, reaching the 2.00 billion USD threshold by 2025. Forward-looking projections place the market value at 2.14 billion USD in 2026, with acceleration expected through the latter half of the forecast window. By 2032, estimated market revenue approaches 3.49 billion USD, reflecting a compound annual growth rate of 8.7 percent across the 2025–2032 forecasting horizon.
Several interdependent dynamics underpin this trajectory. First, healthcare administrators have institutionalized respiratory protection as a baseline operational requirement rather than an episodic procurement response. Second, regulatory frameworks governing filtration certification, fluid resistance, and single-use compliance have raised the technical bar for market entry, effectively concentrating supply among manufacturers capable of consistent quality validation. Third, supply chain resilience initiatives have prompted end-users to diversify sourcing strategies, favoring vendors with documented certification continuity and transparent material sourcing. Together, these forces have transitioned the market from volume-driven surplus cycles to value-driven, compliance-aligned purchasing behavior.
Regulatory Frameworks and Technical Benchmarks
The commercial viability of N95-grade respiratory protection is inextricably linked to certification rigor and regulatory compliance. All FDA-cleared N95 respirators are designated as single-use disposable devices. Reprocessing or reuse pathways require explicit FDA enforcement discretion or emergency use authorization, a constraint that shapes inventory planning, waste management protocols, and lifecycle costing across healthcare networks. Concurrently, NIOSH-certified filtering facepiece respirators must display a TC-84-A approval number and demonstrate a minimum 95 percent filtration efficiency against 0.3-micron particles, a technical threshold that serves as the de facto baseline for procurement qualification in clinical environments.
For surgical N95 respirators deployed in medical protective applications, the technical requirements extend further. These devices must additionally satisfy ASTM F2100 Level 2 or Level 3 fluid resistance and particulate filtration standards. The convergence of these standards creates a bifurcated product architecture in which general particulate protection and fluid-resistant medical-grade models occupy distinct procurement categories. Electrostatic filter media technology has emerged as a critical performance differentiator within this architecture, reducing breathing resistance by up to 50 percent while preserving medical-grade fluid resistance at 160 mm Hg. This engineering balance directly influences clinician adoption rates, wearer compliance, and extended-shift usability, factors that procurement committees increasingly weigh during vendor evaluations.
Reimbursement and administrative dynamics further complicate purchasing decisions. CPT codes for N95 respirator utilization in hospital settings are anchored to infection control procedures that require documented medical necessity for airborne pathogen protection. This coding dependency ties product selection to clinical documentation workflows, meaning that procurement choices must align not only with technical specifications but also with hospital coding compliance and cost-recovery pathways. The intersection of regulatory labeling, certification numbering, material performance, and reimbursement justification forms a complex decision matrix that many organizations are only beginning to navigate systematically.
Competitive Landscape and Strategic Positioning
The market exhibits moderate concentration, with the top three manufacturers accounting for 47.8 percent of total revenue and the top five collectively capturing 58.2 percent. This concentration reflects the barriers to entry posed by certification pipelines, compliance documentation, and established institutional relationships. Several organizations have differentiated their positioning through product-line specialization, supply chain agility, and regulatory continuity.
3M Company, headquartered in Saint Paul, Minnesota, remains a defining reference point in the healthcare respirator segment. The company manufactures NIOSH-approved N95 and surgical N95 filtering facepiece respirators, including fluid-resistant medical-grade models engineered for clinical deployment. Louis M. Gerson Company, Inc., operating from Middleboro, Massachusetts, produces FDA-cleared and NIOSH-approved N95 particulate respirators that emphasize low breathing resistance and fluid resistance tailored to medical applications. Makrite Industries, Inc., with headquarters in Taiwan and global operations that include United States supply channels, supplies NIOSH-approved and FDA-cleared surgical N95 respirators for healthcare settings, offering private-label medical-grade options that appeal to institutional branding and procurement flexibility.
DemeTECH Corporation, based in the United States, manufactures NIOSH-approved N95 and surgical N95 respirators for medical use, including FDA-cleared fluid-resistant models. Moldex-Metric, Inc. offers NIOSH-approved N95 filtering facepiece respirators specifically oriented toward healthcare and medical protective applications. Shawmut Corporation provides NIOSH-approved N95 respirators under its Protex series, explicitly designed for medical and healthcare protective needs. Medtecs Corporation, also United States-based, develops and supplies N95 masks certified for medical protective use within healthcare environments. These organizations collectively represent a competitive field shaped by differing manufacturing footprints, certification pathways, and product-line emphases.
Strategic differentiation among these players rarely hinges on price alone. Instead, it revolves around certification continuity, production capacity stability, material sourcing transparency, private-label capability, and responsiveness to institutional compliance requirements. The recent CDC-NIOSH update in May 2026, which refreshed the Certified Equipment List as of June 1, 2026, confirmed ongoing active production and certification for medical-grade respirators, reinforcing the regulatory permanence of the category. For procurement teams and competitive analysts, tracking certification list updates, approval number visibility, and documented fluid-resistance compliance has become a routine but essential element of supplier qualification.
Segmentation Logic and Demand Architecture
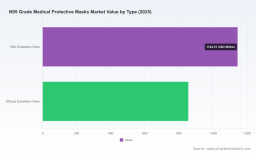
The market is structured around three primary segmentation dimensions: geography, product type, and application context. Each dimension shapes procurement behavior, inventory strategy, and risk allocation. Regional demand patterns reflect varying institutional procurement maturity, regulatory adoption speeds, and healthcare infrastructure density. Product type segmentation distinguishes respirators equipped with exhalation valves from those without, a distinction that carries clinical, operational, and infection-control implications. Application segmentation separates demand originating from hospital and clinic environments, industrial settings, and individual end-users, each with different purchasing cycles, compliance drivers, and volume characteristics.
Hospital and clinic procurement typically operates through structured vendor qualification processes, bulk contracting, and compliance documentation requirements. Industrial demand is influenced by occupational safety programs, particulate exposure assessments, and worker protection mandates. Individual market segments often respond to public health messaging, retail availability, and consumer-grade certification awareness. The interplay among these segments creates a multi-channel demand environment in which pricing, certification emphasis, and distribution strategy must be calibrated separately rather than treated as a uniform market proposition.
Material cost dynamics further complicate segmentation strategy. The adoption of electrostatic filter media has enabled manufacturers to improve wearer comfort without sacrificing fluid resistance, but this engineering advantage also introduces sensitivity to raw material availability, media formulation consistency, and production yield. Organizations evaluating long-term supply partnerships must therefore consider not only unit pricing but also media quality control, tolerance consistency, and the ability to maintain filtration performance across production batches. In a market where clinical usability directly influences adoption and compliance, material performance is a strategic variable rather than a purely technical footnote.
Operational Implications for 2026 Decision-Makers
For executives, procurement leaders, and strategy teams operating in 2026, the N95 Grade Medical Protective Masks Market presents several actionable considerations. The first is compliance alignment. As regulatory expectations around certification labeling, single-use classification, and fluid-resistance standards remain firmly entrenched, organizations must embed verification checkpoints into supplier onboarding and periodic re-qualification. The presence of a valid TC-84-A approval number, documented NIOSH approval status, and FDA clearance where applicable should form the minimum baseline for any contract inclusion.
The second consideration is inventory architecture. Given the single-use disposable classification and the reimbursement implications tied to documented medical necessity, organizations benefit from treating respirator inventory as a regulated clinical supply rather than a general safety stock item. Forecasting should incorporate infection control calendars, seasonal respiratory illness patterns, institutional staffing cycles, and potential surge scenarios. Over-reliance on reactive purchasing increases exposure to price volatility and compliance gaps; proactive multi-quarter planning reduces both.
The third consideration is supplier diversification with qualification rigor. Market concentration indicates that a limited number of manufacturers command a substantial share of revenue, but institutional buyers still benefit from maintaining qualified alternatives across different manufacturing footprints and product configurations. Diversification should not dilute compliance standards. Instead, it should expand the pool of pre-qualified vendors capable of meeting certification, fluid-resistance, and documentation requirements. Private-label options, where available, can provide additional flexibility for institutions seeking branded supply continuity without compromising regulatory alignment.
A fourth consideration involves reimbursement and coding awareness. Since CPT code utilization for N95 respirators in hospital settings depends on documented medical necessity for airborne pathogen protection, procurement decisions should be coordinated with clinical documentation teams and revenue cycle stakeholders. Alignment across supply chain, infection control, and administrative coding functions helps ensure that purchased products support both clinical protection and institutional cost-recovery structures.
Medical Protective Masks Market
Finally, organizations should monitor certification list updates, material performance trends, and regulatory guidance revisions as ongoing intelligence inputs. The May 2026 CDC-NIOSH equipment list refresh underscores that certification status is dynamic and must be tracked continuously. Companies that institutionalize this monitoring process are better positioned to anticipate supply continuity, validate replacement products, and maintain uninterrupted compliance across procurement cycles.
Conclusion and Next Steps for Strategic Intelligence
The N95 Grade Medical Protective Masks Market is no longer defined by episodic demand shocks alone. It is now shaped by enduring regulatory expectations, engineering-driven product differentiation, concentration-oriented competitive dynamics, and procurement workflows that fuse clinical protection with administrative compliance. The 8.7 percent compound annual growth trajectory projected through 2032, alongside the estimated expansion from approximately 2.14 billion USD in 2026 to 3.49 billion USD by the close of the forecast period, signals a market that will continue to reward organizations capable of aligning technical qualification, supply resilience, and compliance discipline.
N95 Grade Medical Protective Masks Market
This overview has outlined the structural contours, regulatory benchmarks, competitive positioning, and operational considerations that define the market environment for 2026 decision-makers. Full segmentation data, regional demand distribution, application-level revenue splits, product-type breakdowns, detailed company profiles, competitive benchmarking matrices, and proprietary scenario modeling are available in the complete market research publication. Readers seeking comprehensive datasets and actionable strategic frameworks are encouraged to access the full report to support procurement planning, competitive positioning, investment evaluation, and long-range supply strategy development.
For detailed analysis of this topic, please visit the official page: N95 Grade Medical Protective Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com