

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Healthy Lifestyle
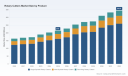
Rotary Cutters Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic briefing intended to frame the rotary cutters market for executive decisions in 2026. This teaser synthesizes the most consequential macro trends and competitive inflection points derived from our full market study (base year 2025; historical window 2020–2025; forecast 2026–2032). The global market has demonstrated resilient expansion through the last half-decade and—guided by a 6.8% compound annual growth rate in our forecast—continues on a trajectory that creates distinct windows for investment, product innovation, and channel repositioning. The objective here is to establish the strategic line-of-sight you need; proprietary segment tables and granular breakdowns are intentionally withheld and available in the full report at pwconsulting.com to support transaction-level and go-to-market execution.
Rotary Cutters Market
Why this market matters in 2026
-
Structural durability: Rotary cutters remain foundational to agricultural, roadside, and land-management operations. Even as mechanization evolves, the category benefits from steady replacement cycles, aftermarket services, and product upgrades that support healthy margin pools for OEMs and dealers.
Rotary Cutters Market -
Accelerating commercial opportunities: With the market base expanding from recent years into 2026, OEMs that combine product robustness with optimized service networks can capture disproportionate value—particularly through aftermarket parts, service contracts, and retrofit kits.
Rotary Cutters Market -
Capital-light growth vectors: Partnerships, contract manufacturing transitions, and targeted local production are emerging as faster and lower-capital routes to market share gains compared with greenfield facilities—important for balancing 2026 capital allocation decisions.
Condensed market snapshot (strategic highlights)
-
Market momentum: The global rotary cutters market reached a meaningful baseline in our 2025 assessment and enters a multi-year expansion phase. Our forecast assumes a 6.8% CAGR through 2032, reflecting both underlying demand growth and incremental value capture from higher-spec models and service monetization.
-
Concentration and competitive dynamics: The market exhibits moderate concentration among a small group of established OEMs. The top-tier firms collectively command a material share of the market, leaving room for niche players to scale through product specialization, distribution depth, or service excellence.
-
Service and maintenance as a lever: Recent operational improvements—such as reduced regrinding lead times in North America—underscore that aftermarket responsiveness is an increasingly important differentiator for both OEMs and distributors.
What the full PW Consulting study gives you (practical, decision-ready content)
Our full report is structured to move leaders from insight to action. Highlights include:
-
Robust market sizing and forward-looking scenarios: Proprietary top-line demand models, sensitivity analyses (price, fuel and steel cost, dealer inventory turns), and three demand scenarios to stress-test capital plans and product roadmaps.
-
Go-to-market playbooks: Channel economics for dealer networks, OEM-direct vs. distributor strategies, parts-and-service monetization models, and customer segmentation frameworks that prioritize returns on sales and service investments.
-
Product and engineering implications: Benchmarks for durability design, lessons from gearbox and deck redesigns, and a prioritized matrix of feature investments that yield the best combination of customer value and manufacturing cost efficiency.
-
Supply chain and operations toolkit: Cost-to-serve maps, supplier risk heatmaps (including steel and gearbox components), and operational playbooks to reduce lead times and increase first-time-fix rates in field service.
-
M&A and portfolio optimization support: Screening criteria for bolt-on acquisitions, value-creation levers post-close, and modeled returns under multiple integration choices.
-
Commercial pilots and KPIs: Ready-to-run pilot designs for new service offerings, pricing experiments, and dealer incentive schemes—each with target KPIs and expected payback timelines.
Competitive landscape — what to watch in 2026
The competitive fabric of the rotary cutters market blends long-standing OEM brands with regional specialists and emerging partnerships. Below are the firms central to our landscape analysis and the strategic implications executives should factor into 2026 plans.
-
Bush Hog (Selma, Alabama) : A North American stalwart with broad product coverage and an extensive dealer network. Their recent product iterations emphasize reinforced structures—an engineering response to customer demand for higher durability. Strategically, Bush Hog’s depth in distribution and brand recognition makes it both a formidable incumbent and an attractive partner for supply consolidation or aftermarket growth initiatives.
-
Alamo Industrial : Known for roadside and off-road cutting heads, Alamo’s engineering focus on specialty applications gives it a differentiated position—especially where regulatory or roadside-standards complexity elevates switching costs. Watch for selective partnerships or production transitions that reallocate capacity across brands.
-
Schulte Industries (Canada) : A player in large-capacity rotary cutter designs. Schulte’s product scale advantage is a defensive moat for customers requiring higher throughput equipment, and it positions the company as a supplier of choice where field productivity is paramount.
-
Land Pride (Salina, Kansas) : Strong in farm and roadside segments with a diverse model family. Their emphasis on modularity and OEM channel relations makes them strategically relevant for OEMs seeking partnerships to expand model breadth quickly.
-
Woods Equipment (Oregon) : With a mix of specialty and mainstream models, Woods’ portfolio emphasizes brush-control and heavy-duty mowing—areas where aftermarket service depth and field-proven ruggedness drive purchase decisions.
-
RhinoAg : Offers flexibility through flex-wing and boom-mounted systems. RhinoAg’s product design orientation makes it a potential scaling candidate through distribution partnerships or targeted OEM integrations.
Recent industry moves underscore the strategic churn: a 2025 production transition saw capacity realigned between manufacturing sites, and a 2026 strategic partnership brought domestic production and brand leverage into sharper focus. These events illustrate two prevailing themes for 2026—continuing consolidation of manufacturing footprints, and the use of brand alliances to accelerate market access.
Operational and product trends shaping 2026 choices
-
Design for serviceability: Gearbox updates with sight glasses and serviceable fill plugs, and deck redesigns that enhance debris management, are reducing downtime and total lifecycle cost—critical to buyers focused on utilization.
-
Aftermarket as a revenue engine: Shorter service turnarounds and improved parts availability elevate aftermarket margins and lock in customer lifetime value. Firms that invest in rapid regrinding, parts logistics, and field diagnostic tools will capture outsized margins.
-
Localized production to manage trade and logistics risk: Strategic partnerships that localize production under respected brands are reshaping sourcing and channel economics—especially in jurisdictions where onshore manufacturing yields procurement or regulatory advantages.
Five strategic recommendations for 2026
-
Prioritize aftermarket and service uplift. Make targeted investments in turnaround time reduction, field diagnostics, and parts logistics to convert operational improvements into recurring revenue.
-
Evaluate partnerships before greenfield expansions. Consider co-manufacturing or licensing arrangements to accelerate product launches with lower capital risk and quicker dealer acceptance.
-
Use product engineering as a competitive moat. Focus R&D on serviceability, modularity, and materials that lower total cost of ownership; these attributes are increasingly decisive in procurement decisions.
-
Stress-test M&A targets against dealer network fit and aftermarket synergies. Real value often resides in network reach and spare-parts coverage rather than in headline product lines alone.
-
Invest in data-driven field support. Deploy telematics and remote diagnostics pilots to reduce mean time to repair and to create data streams that inform next-generation product specs.
Next steps
This briefing outlines the strategic terrain for rotary cutters in 2026—highlighting the macro scale, competitive inflection points, and operational levers most likely to determine winners. For deal teams, product leaders, and channel executives, the full PW Consulting report provides the actionable detail required to convert these insights into investment decisions and commercialization plans. Key proprietary elements—detailed segment economics, dealer-level network maps, and modeled scenario outputs—are intentionally excluded from this summary and are available in the comprehensive study on our website.
Contact PW Consulting’s advisory team to obtain the full Rotary Cutters Market report and a tailored briefing that maps our findings to your organization’s strategic priorities.
For detailed analysis of this topic, please visit the official page: Rotary Cutters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Veterinary Drug Market to Reach USD 46.57B by 2032 at 6.2% CAGR
By pmarketresearch, 2026-07-13
Veterinary Drug Market 2026: Strategic Imperatives for Executive Decisions
As Pw Consulting’s lead industry analysis for the Veterinary Drug Market, this briefing frames the strategic value of our full 2026 market study and highlights the evidence-based actions executives must consider during the next planning cycle. The market has moved decisively from a mid‑teens billion base earlier this decade to a robust multi‑decade growth trajectory: total global veterinary drug revenues rose materially between 2020 and 2025, and our baseline forecasts (2026–2032) project a compound annual growth rate (CAGR) of approximately 6.2%, with the market expanding substantially through 2032. These macro dynamics create both expansion opportunities and execution risks for incumbent manufacturers, specialty entrants, contract manufacturers, and investors.
Veterinary Drug Market
Why this research matters for 2026 decisions
-
Investment prioritization: the report quantifies where growth is concentrated and which therapeutic classes and modalities are accelerating fastest, enabling disciplined capital allocation across R&D, M&A, and commercial rollouts.
Veterinary Drug Market -
Portfolio strategy: it maps product lifecycles against market demand and regulatory windows so you can decide where to double down on next‑generation biologics versus where to pursue lower‑margin generic plays.
Veterinary Drug Market -
Commercial design: the study provides go‑to‑market segmentation frameworks and pricing sensitivity analyses tailored to companion animal and livestock channels to optimize launch sequencing and channel economics.
-
Regulatory and supply‑chain resilience: with recent shifts in conditional approvals, EUA decisions, and biologics licensing requirements, the study gives scenario playbooks for regulatory engagement and contingency planning for production constraints.
-
M&A and partnership screening: a prioritized target list and valuation sensitivity model help deal teams size potential bolt‑on acquisitions and strategic alliances in a market where the top players remain concentrated but new entrants are rapidly introducing differentiated assets.
Market context and growth drivers
The market’s recent expansion reflects a convergence of secular trends. Rising pet ownership, the premiumization of companion animal healthcare, and increasing willingness among pet owners to fund advanced diagnostics and therapies are powerful demand multipliers for pharmaceuticals and biologics. At the same time, intensifying focus on herd health, productivity, and antimicrobial stewardship on the livestock side is supporting higher uptake of targeted therapeutics and growth‑promoting interventions where permitted by regulation.
Technological shifts—particularly the adoption of biologics, long‑acting formulations, and novel delivery systems—are reshaping product economics and channel structures. Parallel pressures on the cost base—driven by elevated pharmaceutical input prices and supply chain constraints reported by industry associations—are forcing companies to rethink sourcing, contract manufacturing, and inventory strategies.
Regulatory and policy dynamics
-
Conditional and accelerated approvals: regulators are increasingly using conditional approvals to speed innovative veterinary drugs to market while still managing safety data requirements—creating both upside for early movers and complexity for post‑market evidence commitments.
-
Biologics licensing and manufacturing standards: veterinary biologics remain subject to robust licensure pathways and manufacturing controls. Licensed production sites and compliance with national acts governing biologics are non‑negotiable for market access and product integrity.
-
Emergency authorizations and single‑use interventions: regulators have demonstrated flexibility in crises, issuing emergency use authorizations for targeted animal health threats. These measures change the risk/reward calculus for companies with contingency products or adaptable manufacturing capacity.
Competitive landscape — concentration and strategic positioning
The veterinary drug industry exhibits moderate to high concentration at the top: the leading three companies account for a meaningful majority of market share, and the top five constitute an even larger portion of revenue—a structure that rewards scale, distribution reach, and R&D depth. Against this backdrop, there is room for specialists and generics providers to pursue niche scale or cost leadership strategies.
-
Zoetis Inc. — With deep expertise across pharmaceuticals, vaccines, and diagnostics, Zoetis continues to leverage scale and a broad portfolio. Recent approvals extending growth implants and other production‑animal products reinforce its capacity to combine regulatory experience with commercial force. For competitors, Zoetis’ playbook highlights the value of integrated product and service offerings that lock in veterinarian and producer loyalty.
-
Boehringer Ingelheim Animal Health — Known for innovation across vaccines and pharmaceuticals, the company’s strategy centers on integrated smart solutions and farm‑level digital links. Their model underscores the competitive advantage of tying therapeutics to preventive and monitoring services.
-
Elanco, Merck, Ceva, and other global players — These firms balance broad therapeutic coverage with targeted investments in biologics and parasiticides. Their global networks and manufacturing footprints act as barriers to rapid scale‑up by regional players, but they also reveal acquisition and divestiture opportunities for nimble challengers.
-
Specialists and generics (e.g., Phibro, Dechra, Vetoquinol, Bimeda, Huvepharma) — These players compete on cost, speed to market for generics, and focused therapeutic expertise. Their success often depends on regulatory agility and relationships with distributors and veterinarians.
Recent regulatory approvals in early 2026—covering pain management products, extended‑release implants for beef cattle, and novel medicated feed formulas—illustrate how product introductions continue to shift competitive dynamics in both companion and production animal segments. These approvals also heighten the tactical importance of launch sequencing, post‑approval evidence plans, and supply chain readiness.
What’s in the full Pw Consulting Veterinary Drug Market report
-
Executive summary with scenario‑based market sizing and a concise implications matrix for C‑suite decision making.
-
Methodology appendix describing our base year (2025) calibration, historical series (2020–2025), and the assumptions underlying the 2026–2032 forecast path.
-
Therapeutic and modality analysis that ranks classes by growth rate, margin profile, regulatory complexity, and commercial barriers—presented as decision tools rather than raw tables.
-
Competitive benchmarking dossier profiling product portfolios, pipeline assets, manufacturing capacity, and go‑to‑market strengths for the leading firms.
-
Regulatory roadmap and compliance checklist for biologics and small‑molecule approvals, including conditional approval pathways and EUA contingency playbooks.
-
Commercial playbooks with channel economics, pricing models, veterinarian segmentation, and digital engagement strategies for companion and livestock channels.
-
Supply‑chain stress tests, supplier concentration assessments, and manufacturing expansion decision frameworks.
-
M&A screening templates, valuation sensitivity models, and a prioritized shortlist of target archetypes (technology, geographic extension, generics/commercial or manufacturing scale).
-
Appendices with slide‑ready charts, a downloadable financial model, and an evidence library of regulatory notices, approvals, and data sources used to build the forecast.
How executives should use the findings in 2026
-
Adopt a two‑track R&D funding approach: protect core revenue through life‑cycle management while allocating a defined portion of incremental R&D to high‑growth biologics and differentiated delivery systems.
-
Prioritize manufacturing investments where margin uplift and regulatory complexity overlap—especially for biologics—while outsourcing commoditized production to cost‑competitive CMOs with veterinary expertise.
-
Prepare regulatory evidence plans concurrently with development programs to shorten time‑to‑value in conditional approval regimes and to manage post‑market obligations.
-
Use the competitive concentration data to shape M&A strategy: acquire capabilities that close strategic gaps (e.g., digital services, biologics, or specific species expertise) rather than pursuing broad scale alone.
-
Institute a commercial segmentation playbook that differentiates tactics for high‑value companion animal owners versus volume‑driven livestock customers—optimizing margin capture and distribution costs.
Closing perspective and next steps
The veterinary drug market in 2026 is simultaneously stable and dynamic: steady macro growth underpinned by demographic and behavioral demand drivers, combined with episodic regulatory and supply shocks that favor adaptive organizations. The CR3/CR5 concentration profile means scale and distribution still matter, but regulatory agility, biologics capability, and targeted commercial models are decisive differentiators for the next five years.
Our full Pw Consulting report delivers the granular segmentation, competitive scorecards, and ready‑to‑use financial models that senior teams need to convert insight into action. To access the complete dataset, therapeutic splits, and downloadable scenario models that underpin the forecast and strategic playbooks, view the full study at the source page. The summary here is intentionally directional—designed to establish priorities and present the strategic logic—and the complete report contains the detailed segment numbers and annexes required for transactional diligence and operational planning.
For immediate inquiries on bespoke strategic workshops, M&A screening, or a tailored 90‑day implementation plan aligned with the report’s findings, our industry team at Pw Consulting is prepared to engage directly with executive sponsors.
For detailed analysis of this topic, please visit the official page: Veterinary Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Forensic Accounting Market to Hit USD 1,221 Million by 2032
By pmarketresearch, 2026-07-13
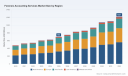
Forensic Accounting Services Market — Strategic Outlook for 2026 Decision‑Makers
As organizations recalibrate risk appetites and compliance frameworks for a new regulatory and technological era, forensic accounting has moved from a specialist discipline to a board‑level capability. PW Consulting’s upcoming Forensic Accounting Services Market study (base year 2025) offers a practical, decision‑grade compass for executives, in‑house counsel, risk officers, and advisory firms preparing strategic moves in 2026 and beyond. The market reached approximately USD 700 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 8.2% across the 2026–2032 forecast window — a trajectory that frames both near‑term investment priorities and medium‑term capability gaps for enterprises and service providers alike.
Forensic Accounting Services Market
Why this study matters for 2026
-
Convergence of risk vectors. Cyber breaches, complex financial crime, cross‑border litigation, and heightened regulatory scrutiny are converging into multi‑disciplinary investigations that demand integrated forensic accounting, digital forensics, and legal coordination. The market dynamics embedded in this study quantify that convergence and translate it into practical options for allocating spend, talent, and technology in 2026.
Forensic Accounting Services Market -
Capital allocation and M&A timing. With forensic accounting services growing at a mid‑single‑digit premium to adjacent professional services, the study provides the revenue and growth context that informs acquisition bench‑building, bolt‑on strategies, and greenfield investments — particularly where specialized boutiques or regional practices can fill capability gaps quickly.
Forensic Accounting Services Market -
Talent and cost management. Premiums for Certified Fraud Examiners (CFE) and experienced forensic accountants are measurable and persistent; the report translates labor cost inflation and certification premia into workforce planning scenarios, bill‑rate models, and retention playbooks suitable for 2026 budgeting cycles.
Core drivers shaping the market
-
Regulatory and standards pressure. Enforceable professional standards and sector guidance (including contemporary updates to the AICPA’s forensic services guidance) have raised baseline expectations for methodology, documentation, and expert testimony. Our analysis identifies which parts of the forensic workflow will be subject to the most immediate scrutiny and which controls companies should prioritize in 2026 to reduce legal and reputational exposure.
-
Technology and analytics. Forensic analytics tools — from anomaly detection engines to provenance tracing — are entering widespread commercial use. Large advisory firms and niche tool vendors are investing in integrated stacks. The net effect: faster evidence discovery cycles but higher vendor diligence requirements. The study maps the vendor taxonomy, capability tiers, and the practical tradeoffs between build, buy, and partner strategies.
-
Cyber‑forensics coupling. Recent strategic partnerships between major professional services firms and cybersecurity specialists underscore a structural shift: forensic accounting engagements increasingly require deep data security and incident response capabilities. We evaluate how firms can operationalize this coupling without creating duplication or compliance gaps.
-
Litigation intensity and alternative dispute mechanisms. Corporate restructurings, bankruptcy proceedings, and global arbitration trends have sustained demand for litigation support and expert testimony. The report models demand drivers for dispute‑related engagements and the commercial levers firms can use to capture that work.
What the report delivers — practical content for implementers
-
Comprehensive market sizing and growth scenarios. We present a base‑case market sizing for 2025 and model growth through 2032 under multiple adoption and regulatory scenarios to support capital planning.
-
Service and delivery playbooks. Usable templates for structuring fraud investigation, litigation support, risk assessment, and bankruptcy engagements — including team composition, evidence flows, and quality checkpoints.
-
Vendor and capability heatmaps. Benchmarks of global and regional providers across technical skills, digital forensics, expert witness track record, and pricing models — designed for rapid shortlist development and RFP issuance.
-
Financial models and pricing toolkits. Cost‑to‑serve frameworks, utilization levers, and value‑based pricing approaches that reflect the labor premium for certified practitioners and the capital costs of analytics tooling.
-
M&A and partnership playbooks. Due diligence checklists, integration risk matrices, and a prioritized list of capability gaps that are most accretive when addressed by acquisition or alliance in 2026.
-
Regulatory impact matrix. A translator that connects current and emerging enforcement patterns (standards and sector guidance) to operational controls and documentation practices that counsel should mandate prior to or during investigations.
-
Executive briefings and board materials. Ready‑to‑use slide packages that translate forensic risks into financial exposure, disclosure considerations, and remediation timelines suitable for C‑suite and board audiences.
Competitive landscape — what the major players are doing
The market combines global, multi‑disciplinary advisory houses with specialized regional and boutique forensic firms. Leading global firms are leveraging scale and cross‑service integration to deliver end‑to‑end investigative capabilities, while smaller firms compete on domain specialization, rapid responsiveness, and localized expert witness strength. Key players profiled in the study include a mix of large advisory brands and specialised forensic practices; each occupies a distinct strategic position in the value chain.
-
Crawford & Company: A global provider with broad service lines including litigation support and expert financial analysis. Their scale and loss‑adjusting heritage make them a go‑to for insurer‑led investigations and complex claims work.
-
Fiske & Company: A focused litigation‑support and forensic accounting practice that competes through deep technical expertise in fraud investigations and economic damages — a model that is highly attractive to law firms and claimants seeking specialized testimony.
-
Dean Dorton Allen Ford: Known for integrated fraud and risk assessment services, including whistleblower programs and SEC compliance consulting — a profile that aligns with corporate governance and regulatory remediation work.
-
Miller & Company LLP and Pribramsky & Co: Regional firms with strong local testimony pedigrees and practical strengths in dispute resolution and internal audit augmentation — they often win mandates where local legal knowledge and court acceptance are decisive.
-
Cg Team and Forensic Risk Alliance: Providers that blend litigation support with loss recovery and forensic accounting. Their agility makes them competitive for short‑cycle engagements.
-
Orrick, Herrington & Sutcliffe LLP and Alvarez & Marsal: Firms that combine forensic accounting with legal teams and restructuring capabilities, respectively. These integrated models are well suited to multi‑jurisdictional disputes and complex insolvency situations.
Recent market moves illustrate the strategic levers at play: major professional services firms are forming cybersecurity partnerships, launching advanced forensic analytics products, and acquiring boutique specialists to shore up niche capabilities. These developments accelerate consolidation in some parts of the market while raising the technical bar for boutique competitors.
Regulatory, labor, and standards context
-
Standards: The AICPA’s Statement on Standards for Forensic Services (SSFS) remains a central reference point for enforceable engagement standards. Compliance with these standards is increasingly a threshold requirement for admissibility and reputational resilience.
-
Compensation and labor market: CFEs and experienced forensic accountants command a measurable income premium versus general accounting peers; employers should expect higher base costs and plan retention incentives accordingly in 2026 hiring cycles.
-
Professional community and knowledge transfer: Industry forums and professional interest groups (including AICPA specialty areas and annual research conferences) are actively prioritizing AI integration, data privacy, and compliance program design — signaling the next wave of methodological updates that firms must adopt within advisory workflows.
Strategic imperatives for 2026
-
Invest in integrated analytics and secure data handling. Forensic engagements will increasingly hinge on the ability to process large, heterogeneous datasets while preserving evidentiary integrity and privacy — invest in secure analytics stacks and rigorous chain‑of‑custody protocols.
-
Design hybrid sourcing models. Combine in‑house capability for governance and rapid response with vetted external partners for specialty technical work and expert testimony. Our vendor heatmaps make this tactical sourcing executable.
-
Prioritize certification and career pathways. To contain labor cost escalation and talent churn, firms must create certification‑linked advancement tracks and billable pathways that capitalize on the market premium for specialized credentials.
-
Embed regulatory foresight into product design. Design services and engagement terms that anticipate admissibility standards and cross‑border evidence rules — this reduces rework and litigation risk.
-
Use M&A selectively to fill capability gaps. Where speed to market matters (e.g., cyber‑forensics, advanced analytics), targeted acquisitions or alliances will outperform organic build over the medium term.
How to use this report
Think of the study as a practical field guide and negotiation kit. It equips decision‑makers with market context to set 2026 budgets, shortlist partners, structure RFPs, and run post‑transaction integration for forensic capabilities. The study surfaces high‑confidence strategic options while intentionally withholding granular subsegment datapoints in this public summary — a design choice to protect the value of the full analysis and to steer practitioners toward the complete models, raw interview transcripts, and proprietary vendor scores contained in the report.
For executives preparing capital plans, counselers drafting engagement terms, or advisory firms sizing their next acquisition, the full PW Consulting Forensic Accounting Services Market study contains the granular inputs, scenario models, and implementation materials necessary to act decisively in 2026. Access to the full dataset and executable playbooks is available on our research portal.
For detailed analysis of this topic, please visit the official page: Forensic Accounting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vitamin Market at USD 129.6B in 2025, set to reach USD 214.7B by 2032 (7.5% CAGR)
By pmarketresearch, 2026-07-13
Vitamin Market 2026 — Strategic Preview for Enterprise Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise strategic preview of our comprehensive Vitamin Market report (base year 2025). This briefing synthesizes the macro trajectory, competitive dynamics, and near-term regulatory inflections that will shape commercially meaningful choices in 2026. Think of this as the trailer: it demonstrates the depth and decision-focus of the full study while reserving the detailed subsegment tables, proprietary models, and granular regional splits for the full report.
Vitamin Market
Market trajectory at a glance
The global vitamin market has moved from roughly USD 94.6 Billion in 2020 to an estimated USD 129.6 Billion in 2025, reflecting sustained demand across both legacy supplement channels and emerging formats. Our forecasting framework projects continued momentum through the 2026–2032 forecast window, with the market expanding at a compound annual growth rate (CAGR) of 7.5%, reaching roughly USD 214.7 Billion by 2032. These top-line dynamics are driven by a blend of structural consumption shifts, premiumization, and regulatory-driven transparency that is reshaping buyer trust.
Vitamin Market
Why this matters for 2026 decisions
- Investment prioritization: The mid-single-digit to high-single-digit CAGR profile supports continued investment in capacity and advantaged ingredients, but it also demands disciplined capital allocation. Companies must prioritize initiatives that protect margin while expanding addressable consumers—R&D into differentiated formulations, routes-to-market that improve margins, and partnerships for certification and athlete endorsements.
- Channel and format strategy: Rapid innovation in formats (e.g., gummies, stabilized liquids, and micro-dosed formats) and the strength of private label at scale require manufacturers and brand owners to define distinct value propositions. Tactical trade-offs—scale via private label versus margin capture through branded innovation—are central to 2026 product roadmaps.
- Supply resilience and ingredient sourcing: Ingredient traceability and supplier qualification now contribute directly to commercial outcomes. The landscape rewards firms that secure diversified supply networks, validated supplier programs, and transparent provenance for clinically positioned ingredients.
- Regulatory and certification risk as opportunity: Increasing regulatory oversight and expanded certification pathways are elevating compliance costs but also creating premiumization levers for certified products. Early movers that integrate certification into product development gain differentiation and shelf-preference.
Report utility — what the full study delivers
Our full Vitamin Market report is engineered for tactical use by strategy, commercial, and M&A teams. Highlights include:
Vitamin Market
- Proprietary demand model covering 2020–2032 with scenario outputs (bull / base / conservative) and sensitivity to price, channel mix, and certification premiums.
- Supply chain and cost-to-serve mapper that identifies bottlenecks, alternative sourcing routes, and potential cost savings across manufacturing, packaging, and logistics.
- Commercial playbook: actionable pricing and launch strategies for premium, mainstream, and value-tier offerings—aligned to distribution partner economics.
- Regulatory and certification tracker that quantifies potential timeline and cost impacts for new compliance requirements and major certification programs.
- Competitive benchmarking and M&A playbook with diligence checklists, synergy levers, and integration risks specific to vitamin manufacturers and ingredient suppliers.
- Go-to-market case studies and retailer scorecards that reflect real-world negotiation levers and assortment strategies across key retail partners.
Note: The full report contains the granular segmentation and proprietary forecasts that underpin the recommendations here; those datasets are intentionally omitted from this preview to preserve the study’s commercial value.
Competitive landscape — who matters and what they signal
The vitamin market exhibits meaningful concentration at the top: the three largest players account for a dominant portion of total revenues (CR3 ~58.5%), and the top five together approach a significantly higher share (CR5 ~72.3%). This degree of concentration creates a bifurcated competitive environment where scale, private-label strength, and brand trust matter simultaneously.
- Pharmavite LLC (Nature Made) — A large branded incumbent with strong retailer partnerships and private-label production capabilities that underscore the importance of both brand equity and manufacturing scale ( https://www.pharmavite.com/).
- RB Manufacturing LLC (Schiff) — A quality-focused producer with established certification programs, demonstrating how quality credentials can be a material commercial differentiator ( https://www.rb.com/).
- Kirkland Signature (Costco Wholesale) — A private-label powerhouse where scale and member trust create margin and volume advantages; their strategy illustrates the competitive pressure on branded players in mass channels ( https://www.costco.com/).
- Haleon / Centrum (ex-GSK) — A global branded leader that signals the continued relevance of broad, science-led multivitamin portfolios in developed markets ( https://www.haleon.com/).
- Pfizer and Bayer AG — Legacy consumer-health players with durable distribution and R&D capabilities; their presence highlights the intersection of pharmaceutical rigor and consumer marketing ( https://www.pfizer.com/, https://www.bayer.com/).
- Nestlé Health Science — A player emphasizing format innovation (e.g., gummy formats) and consumer-centric product design ( https://www.nestlehealthscience.com/).
- Ingredient suppliers and contract manufacturers (e.g., International Vitamin Corporation, Valensa) — These firms are critical to margin, compliance, and speed-to-market; their role in USP/third-party verification programs is increasingly strategic ( https://www.ivcinc.com/, https://valensa.com/).
Strategic takeaway: Leaders combine scale with credible, verifiable quality programs. Mid-market firms can compete by specializing—either through superior formulation and branding, or by offering differentiated manufacturing and certification capabilities to retail partners.
Regulatory and certification inflection points — 2026 and near-term
- Dietary Supplement Listing Act of 2026: The reintroduction of this Act, and the industry associations’ response, signals a material shift toward mandatory product listing and traceability. Expect increased transparency requirements that will elevate record-keeping, product registration timelines, and potential entry costs for small-scale entrants.
- Certification scope expansions: NSF International’s REG 31 designation and its rapid operationalization in 2026 close prior testing gaps and raise the bar for market access claims—particularly for athlete-targeted products. Partnerships like iNADO’s cooperation with NSF demonstrate that certification now intersects directly with sports and performance claims.
- Industry advocacy and adaptation: Trade bodies and major manufacturers are publicly supportive of clearer registries and certification pathways, recognizing that transparency can shrink counterfeit risk and reinforce trusted brands.
Implication: Firms that proactively invest in registration compliance, certification-ready quality systems, and rapid traceability will convert regulatory change from a cost into a competitive moat.
Recommended 90‑day to 18‑month actions for 2026
- 90-day priorities: audit product portfolios for compliance gaps against the emerging listing requirements; map ingredient provenance for all SKUs; and initiate dialogue with primary certification bodies to fast-track certifications that matter to your core channels.
- 6–12 month initiatives: selectively pilot certified SKUs in channels where verification delivers price premium; renegotiate supplier contracts to include traceability clauses; and recalibrate promotional investments to emphasize verified claims.
- 12–18 month moves: evaluate strategic partnerships or M&A targets that provide either ingredient security or certification throughput; deploy a segmented route-to-market playbook that balances private label volume with branded margin capture; and lock in multi-year supply agreements for critical actives.
Risks to monitor and mitigations
- Regulatory timing risk: rapid changes in listing or testing mandates can compress product development timelines. Mitigation: maintain a rolling regulatory impact dashboard and a prioritized SKU remediation queue.
- Margin pressure from private label: continued private-label expansion in big-box and online marketplaces will compress ASPs. Mitigation: invest in premiumization and evidence-backed claims that command higher price points.
- Ingredient concentration and supply shocks: concentrated ingredient sourcing can expose supply chains. Mitigation: pursue supplier diversification and backward-integration options where economically sensible.
Closing — why the full report is strategic value in 2026
Our full Vitamin Market report is designed to be a decision engine for 2026: a combination of proprietary forecasting, competitive diagnostics, and playbooks that convert insight into measurable actions. The market’s projected growth—driven by both scale and segments willing to pay for certified, differentiated products—creates attractive opportunities. At the same time, rising regulatory and certification demands convert product integrity into a strategic asset rather than a compliance cost.
To execute confidently in 2026, leaders need three things simultaneously: (1) a forward-looking demand model, (2) an executable route-to-market and pricing playbook, and (3) a compliance and supplier strategy that protects shelf access. The complete PW Consulting Vitamin Market report provides all three, plus the detailed datasets and scenario matrices that allow you to stress-test strategic choices before you commit capital.
For access to the full dataset, the granular segment breakdowns, company profiles with contact-mapped due diligence checklists, and our interactive scenario model, please consult the full PW Consulting report available via our research portal.
For detailed analysis of this topic, please visit the official page: Vitamin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gelatin Capsule Market Poised for USD 5.43B by 2032 at 4.8% CAGR
By pmarketresearch, 2026-07-13
Gelatin Capsule Market 2026: Strategic Imperatives for Resilient Growth
As PW Consulting’s Chief Industry Analyst, I present a high-level strategic briefing that frames our full Gelatin Capsule Market study and its practical value for decision-makers planning for 2026 and beyond. The gelatin capsule market is on a steady expansion path—the global market, measured at a base year of 2025, is projected to grow from roughly USD 3.87 Billion in 2025 to an estimated USD 5.43 Billion by 2032, reflecting a compound annual growth rate (CAGR) of approximately 4.8% over the 2026–2032 forecast window. This macro trajectory conceals important structural inflections and supplier-level dynamics that will determine winners and losers in the coming 18–36 months.
Gelatin Capsule Market
Why this study matters for 2026 decision cycles
-
Actionability: Boards and corporate strategy teams need more than market size—they need executable choices. Our study translates growth and risk signals into prioritized strategic options: capacity investment timing, supplier qualification sequencing, product-mix optimization, and regulatory readiness roadmaps specific to gelatin-based shells.
Gelatin Capsule Market -
Timing: With steady mid-single-digit CAGR, marginal gains in supply-chain resilience, regulatory positioning, or product differentiation can produce outsized returns. 2026 is a pivot year for capital projects initiated in 2024–2025 to come on-line, and for regulatory verifications that will influence commercial sourcing decisions.
Gelatin Capsule Market -
Concentration and contestability: The market exhibits moderate concentration among the top players (our analysis places the three-largest suppliers in a near-majority position and the top five with substantive market power). That structure creates opportunities for smart challengers to outmaneuver incumbents via niche specialization, vertical integration, or regional capacity plays.
Key market dynamics shaping strategy
-
Demand stability with selective acceleration. The base market is expanding predictably, but growth is uneven across customer segments (pharmaceuticals remain foundational). Companies that map demand drivers at the molecule and SKU level will avoid overcapacity and capture premium margins.
-
Regulatory friction and supplier certification. Recent regulatory activity—ranging from trade verifications to supplier-change reporting requirements—has made supplier traceability and documentation mandatory elements of commercial diligence. Firms must embed USP/NF conformity and BSE/TSE traceability into supplier contracts and change-control playbooks to prevent market disruptions.
-
Raw-material dependency. Gelatin remains largely animal-collagen derived, introducing supply volatility tied to agrifood cycles, animal health policies, and species-specific sourcing constraints. Companies that evaluate upstream exposure and build alternative sourcing or substitution pathways reduce execution risk.
-
Transition to alternatives. Demand for non-animal (e.g., HPMC) shells is growing as end-market customers seek vegetarian/vegan claims and to mitigate animal-sourcing risk. Strategic investment in alternative-technology capabilities is increasingly a defensive requirement for market incumbents and a competitive differentiator for new entrants.
Competitive landscape—what the leading players signal
Our competitive review focuses on active global suppliers that shape capacity, technology, and standards. Each profile is a lens into strategic intent rather than a ranking; the full report contains operative supplier scorecards and decision-ready supplier-risk matrices.
-
Lonza (Basel, Switzerland) : As a leading integrated supplier, Lonza combines capsule manufacturing with complementary health-ingredient capabilities. Recent capacity investments in Asia illustrate a dual-pronged approach: serve high-growth consumer-health demand while de-risking supply chains for global pharmaceutical customers. For pharma firms, Lonza represents a partner capable of global supply continuity and technical co-development.
-
ACG Worldwide (Mumbai, India) : ACG’s aggressive footprint expansion—both in Asia and planned operations in the United States—signals a play for global scale and cost-competitive supply. Their moves are a direct challenge to incumbents in price-sensitive segments and to companies seeking redundancy outside traditional western hubs.
-
Capsugel (Morristown, NJ, USA) : Known for technology and product design in both hard and soft shells, Capsugel’s positioning blends manufacturing with formulation support—making it a preferred supplier for companies that demand design-for-manufacturability and speed-to-market for new dosage forms.
-
Qualicaps (Nara, Japan) : Embedded within a broader ingredients group, Qualicaps couples capsule manufacturing with strong regulatory and technical credentials—especially valuable in markets with stringent pharmacopeial expectations. Their European investments reflect a strategy of proximity to regulated market customers and rapid regulatory response capability.
-
Lyfe Group (formerly CapsCanada) & Capsuline (Dania Beach, Florida) : These North American players focus on high-quality empty capsules and flexible supply. They are strategically positioned to serve regional nutraceutical and pharma manufacturers seeking shorter lead times and high-touch service models. Their portfolios emphasize product quality and customer responsiveness.
Together, these firms define a competitive set where scale, regulatory credibility, geographic footprint, and portfolio breadth determine strategic options. Our full report contains transaction histories, capacity timelines, and scenario-modeled impacts of new-plant commissioning on regional supply-demand balances.
Recent industry developments to watch (strategic implications)
-
Facility openings and capacity upgrades have accelerated—firms are placing capital to shorten lead times and to be closer to high-growth customers. Decision-makers should reassess contract tenors and volume commitments in light of new regional capacity coming online.
-
Large-scale investment programs point to an industry preparing for sustained demand, but also to potential short-term oversupply in specific geographies. Companies evaluating M&A or greenfield projects must stress-test their projections against a range of commissioning scenarios.
-
Regulatory verifications and trade reviews have raised the bar for documentation. Firms with weak change-control processes will face long supplier-qualification lead times—an operational risk that translates directly into lost sales or line-down events for drug manufacturers.
What the PW Consulting report delivers (practical, decision-ready components)
-
30–60/90-day supplier risk-and-readiness playbook: a prioritized checklist for supplier qualification, audit triggers, and contingency sourcing.
-
Capital-allocation scenarios: interactive CAPEX test cases that link commissioning timelines with regional demand trajectories and price elasticity assumptions.
-
Regulatory compliance toolkit: a stepwise protocol for meeting and documenting USP/NF and other major jurisdiction requirements for supplier changes and shell conformity.
-
Commercial contracting templates and negotiation levers focused on lead-time guarantees, quality indemnities, and raw-material pass-through clauses.
-
M&A and partnership playbook: a rapid-screen framework for target selection, valuation sensitivities, and post-acquisition integration risks specific to capsule manufacturing.
-
Market-sensing dashboard: rolling indicators that flag demand shifts at SKU and molecule levels, plus alerts tied to regulatory events and major supplier capacity changes.
How to convert insight into 2026 actions
-
For procurement leaders: shorten qualification cycles, implement multi-sourcing for critical SKUs, and renegotiate flexible contracts to include change-control milestones tied to regulatory approvals.
-
For corporate strategy and M&A teams: prioritize targets that fill strategic gaps—either geographic presence or alternative-technology capabilities—while using scenario modeling to avoid bidding into overcapacity risk.
-
For R&D and regulatory affairs: embed supplier-certification milestones into product development timelines. Early alignment removes downstream launch risk in regulated markets.
-
For operational leaders: stress-test logistics strategies against plant commissioning schedules and regional trade uncertainty; identify buffer locations that minimize lead-time exposure without sacrificing cost discipline.
Closing perspective
The gelatin capsule market presents a classic strategic landscape in which moderate topline growth masks critical choices about where to build resilience, when to invest, and how to partner. With a predictable CAGR and a moderate level of market concentration among top producers, the strategic margin will accrue to companies that pair disciplined capital deployment with rigorous supplier governance and regulatory foresight.
PW Consulting’s full report provides the confidential, segment-level data, supplier scorecards, and executable playbooks that make these high-level choices implementable. The piece you are reading is a strategic “trailer”: it demonstrates the depth of our diagnostics while preserving the detailed subsegment data and supplier-level intelligence that clients rely on to execute decisive moves. For organizations preparing budgets and strategic plans in 2026, our study is designed to be both the decision support system and the implementation roadmap.
Access to the complete dataset, model files, and implementation templates is available through our research portal for licensed subscribers and consulting clients. Engage with PW Consulting to convert market signals into measurable outcomes—minimize risk, accelerate capture, and build the capabilities that will define market leadership.
For detailed analysis of this topic, please visit the official page: Gelatin Capsule Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oral Fluid Drug Test Market to reach USD 549M by 2032 (7.64% CAGR)
By pmarketresearch, 2026-07-13
Oral Fluid Drug Test System Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused industry briefing designed to orient executive teams and investment committees ahead of critical 2026 decisions. This short-form analysis distills the directional forces shaping the Oral Fluid Drug Test System market, explains why 2026 is a pivotal year for commercial and regulatory strategy, and highlights the specific ways our full market study delivers executable intelligence. Where appropriate we integrate high-level market metrics to frame opportunity size and growth trajectory, while intentionally withholding granular segment tables to encourage direct engagement with the full report for transaction- and execution-grade data.
Oral Fluid Drug Test System Market
Market trajectory: growth profile and what it means
The oral fluid drug test system market has moved from a nascent, fragmented niche into a clearly growing market. The global market expanded from roughly USD 230 million in 2020 to about USD 328 million by the 2025 base year, and is projected to continue expanding through our forecast window to reach approximately USD 549 million by 2032. This trajectory reflects a compound annual growth rate of 7.64% across the forecast period (2026–2032).
Oral Fluid Drug Test System Market
Why this matters for 2026 planning:
Oral Fluid Drug Test System Market
- Growth at this pace signals a market that is transitioning from early-adopter use cases toward broader institutional adoption — notably across transportation, workplace compliance, and clinical screening programs.
- Scale is sufficient to support selective investment in product line expansion, regulated-lab partnerships, and integrated digital services (result management, chain-of-custody, and remote supervision).
- However, the market is not yet mature: adoption remains policy-driven and sensitive to regulatory clarity, lab capacity, and demonstrable performance versus established urine-based workflows.
Regulatory inflection points shaping 2026 tactics
2024–2026 has been a period of rapidly evolving regulatory posture that will define near-term commercial windows:
- DOT’s authorization of oral fluid as an alternative to urine (finalized in late 2024) establishes a formal avenue for fleet and transportation-related demand. Operational guidelines published subsequently (early 2025) place emphasis on device standards and collection protocols that suppliers and testing laboratories must meet.
- In early 2026, the regulatory dialogue accelerated: an FDA proposal (May 2026) contemplates removing 510(k) premarket clearance requirements for oral fluid drug testing systems to facilitate HHS laboratory participation in DOT-regulated programs. If finalized, this would materially lower one regulatory barrier and change market entry economics for device innovators.
- Despite these advances, the operational roll-out has encountered friction: as of mid-2026 HHS has not yet certified a critical mass of laboratories for oral fluid testing, delaying full DOT-program deployment and creating a near-term mismatch between policy authorization and field capacity.
Strategic implication: regulatory shifts create a time-limited window where early movers that align product specifications, laboratory partnerships, and DOT/HHS compliance frameworks can secure preferred positions with large procurement buyers. Conversely, regulatory uncertainty increases the value of flexible commercial models and contingency plans.
Competitive landscape — players, positions, and playbook consequences
The competitive map comprises a mix of established diagnostics firms, analyzers and on-site device manufacturers, rapid-test specialists, and regional kit producers. Key global names include:
- OraSure Technologies, Inc. (Bethlehem, PA) — a lab-focused provider that integrates collection devices and laboratory assays; strengths include established laboratory workflows and institutional relationships.
- Abbott Laboratories (Abbott Park, IL) — supplies oral-fluid screening systems and confirmation panels; brings scale in regulatory strategy and distribution to workplace and clinical channels.
- Drägerwerk AG & Co. KGaA (Lübeck, Germany) — known for portable analyzers and on-site screening solutions oriented to law enforcement and roadside use.
- Securetec Detektions-Systeme AG (Markt Schwaben, Germany) — focuses on workplace and roadside analyzers with a European footprint and reseller networks.
- Premier Biotech, Oranoxis, UCP Biosciences, SCREEN ITALIA, MEDACX, AccuBioTech, Guangzhou Wondfo — a set of rapid-test and kit manufacturers that compete on unit cost, time-to-result, multi-analyte panels, and regional channel strength.
Notable 2026 developments that change competitive calculus:
- March 2026: Healgen obtained multi-analyte 510(k) clearance for an oral fluid device — a signal that regulatory acceptance for specific device classes is advancing and that FDA pathways remain meaningful for firms seeking formal market differentiation.
- May 2026: FDA’s proposal to remove 510(k) clearance could lower entry barriers and accelerate product proliferation — raising the importance of brand trust, field validation studies, and lab confirmation partnerships as differentiators.
- DOT’s December 2024 rule and subsequent specimen collection guidance reinforce the need for device makers to certify collection integrity and support observed collection workflows; vendors that can demonstrate robust chain-of-custody and device reliability will capture premium procurement channels.
Competitive implications: incumbents with integrated lab-to-device offerings and robust distribution retain advantages, but the regulatory loosenings open room for agile device makers and low-cost kit suppliers to enter key segments. The result will likely be intensified competition around assay sensitivity, ease-of-use, and procurement pricing over the next 18–36 months.
Recommended 2026 actions — pragmatic moves that preserve optionality
Executives must align near-term operational moves with medium-term market structural change. Priority actions we recommend for 2026:
- Regulatory & compliance: Invest in a dual-path regulatory strategy — prepare for both continued 510(k)-style clearances where advantageous and a rapid compliance kit for alternative pathways if the 510(k) requirement is removed.
- Lab-network development: Secure anchor lab partnerships now (including capacity commitments and rapid-confirmation SLAs) to avoid opening-day bottlenecks when DOT/HHS programs expand operationally.
- Product roadmap: Prioritize modular product features that matter to institutional buyers — verified chain-of-custody, tamper-evident collectors, and integration-ready data outputs for LIMS and fleet management systems.
- Go-to-market: Build targeted commercial plays for transportation fleets and large employers, including pilot frameworks that convert to long-term procurement contracts linked to compliance KPIs.
- Partnerships & M&A: Consider bolt-on acquisitions for assay breadth or lab-network footprint rather than large-scale diversification; small vertical integrations (consumables, collection devices, confirmation labs) can accelerate time-to-revenue.
- Clinical evidence and KOL engagement: Fund pragmatic validation studies in real-world operational settings (roadside, observed workplace collection) to generate differentiated evidence for buyers and regulators.
- Supply chain resilience: Lock in multi-sourced consumable supply and consider regional manufacturing partnerships to reduce lead times for nationwide deployments.
- Commercial models: Offer outcome-linked pricing (e.g., pilot-to-contract, per-confirmation pricing, or bundled device + confirmation) to de-risk adoption for large institutional customers.
What PW Consulting’s full study delivers — operational tools for 2026 decisions
Our full Oral Fluid Drug Test System Market report (base year 2025; forecast period 2026–2032) was designed as an execution-grade toolkit for corporate strategy, BD, regulatory affairs, and PE/VC deal teams. Key components include:
- Dynamic market model (Excel) with top-line, scenario planning (best/likely/worst), and sensitivity to regulatory and lab-capacity assumptions; the model incorporates our 7.64% CAGR baseline and allows you to toggle adoption curves across buyer segments.
- Regulatory tracker and impact matrix that sequences DOT, FDA, and HHS milestones, maps compliance requirements, and estimates time-to-market windows under alternate policy outcomes.
- Competitor playbooks and capability heat maps with product, geographies, channel strategies, and likely entry moves; we profile leading firms and identify partners and M&A targets by strategic fit.
- Commercial launch playbooks — buyer personas, procurement triggers, pilot templates, contract guardrails, and a recommended pricing architecture for 2026 procurements.
- Operational checklists for lab partnerships, device validation, and field rollout logistics, including recommended SLA language for confirmation turnaround and chain-of-custody audits.
- Investor-facing synthesis slides and an executive one-pager that summarize valuation drivers and near-term triggers for market acceleration.
Note: this note is intentionally high-level. The full report includes the granular segmentation, regional breakdowns, and unit- and revenue-level data required for transaction diligence and contract negotiation — data we withhold here to preserve the value of the full deliverable.
Closing — why act in 2026
2026 is not merely another year on the calendar for participants in the oral fluid drug testing ecosystem. It is a pivot point where regulatory permissiveness, operational capacity, and buyer demand converge to create both a rapid opportunity and a strategic trap. Firms that align lab capacity, product reliability, regulatory positioning, and commercial contracting now will capture first-mover economics and preferred buyer relationships. Those that delay risk ceding share to low-cost entrants or to entrenched incumbents that lock distribution channels.
PW Consulting’s study provides the empirical foundation and tactical playbooks to make those decisions with clarity. For teams preparing bids, evaluating M&A, or designing product roadmaps in 2026, the combination of our market model, regulatory sequencing, and competitive intelligence reduces execution risk and sharpens negotiation leverage.
To access the complete dataset, segmented forecasts, and bespoke advisory support, please consult the full report on our site or contact PW Consulting for a confidential briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Oral Fluid Drug Test System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Physical Examination Market to Hit USD 618.57M by 2032 at 7.0% CAGR
By pmarketresearch, 2026-07-13
Physical Examination Market 2026: Strategic Preview for Executives
As healthcare systems rethink how routine and diagnostic care are delivered, the physical examination market is moving from a place of steady clinical utility to one of strategic commercial importance. PW Consulting’s latest market research—anchored to a 2025 base year and projecting through 2032—identifies this market as a mid-sized, fast-evolving sector with a clear growth trajectory (CAGR 7.0% across the 2026–2032 forecast window). The market expanded materially during 2020–2025 as technology adoption and changing reimbursement created new use cases; by 2025 the global market reached just under USD 400 million (USD Million basis). Our study synthesizes that momentum into a practical, decision-grade playbook for 2026.
Physical Examination Market
Why this study matters for 2026 decision-makers
- Timing — 2026 is a pivot year. Recent regulatory approvals and evolving payer rules have materially changed the commercial calculus for remote-enabled and device-centric examination solutions.
- Clarity — The market is growing at a mid-single-digit compounded pace (7.0% CAGR forecast), but distribution is uneven across modalities, channels and vendors; strategic clarity on where to position investments is now value-creating.
- Actionability — Our research is designed to convert insight into initiative: from go-to-market choices and reimbursement strategies to M&A screening and product roadmaps.
What the full report delivers (practical, non-academic outputs)
- Executive synthesis of market dynamics, including regulatory inflection points, reimbursement levers and provider adoption barriers.
- Proprietary forecast model (2026–2032) calibrated to policy scenarios, technology adoption curves and capacity constraints—deliverable as a live spreadsheet to run bespoke scenarios.
- Commercial playbooks for eight strategic routes-to-market (e.g., direct to hospital systems, OEM-integrated diagnostic walls, remote subscription models, channel partnerships with diagnostics centers).
- Regulatory and reimbursement roadmaps that translate recent rulings and claims policy into timing and probability estimates for reimbursement acceptance across major payers.
- Practical ROI and unit-economics templates for pilots and scale initiatives, including sensitivity to labor-cost, device amortization and payor mix.
- Vendor benchmarking and partnership matrices focused on capability gaps (device hardware, AI-enabled interpretation, integration with EHR, after-sales service) rather than headline market share alone.
- M&A screening criteria and a short-list methodology for prioritizing assets that accelerate market entry or close technology gaps.
Market context and dynamics: the forces shaping 2026 decisions
The physical examination market entered 2026 with clear momentum. Over the 2020–2025 period the market expanded significantly as telemedicine acceptance rose and providers experimented with hybrid care models; by our base year the market neared the USD 400 million mark. Looking forward, a 7.0% compound annual growth rate through 2032 implies steady expansion, but the underlying drivers deserve careful unpacking:
Physical Examination Market
- Regulatory inflection points — Recent device clearances and new regulatory pathways (example: De Novo classification for novel AI-assisted ENT image analysis) lower barriers for advanced diagnostic modules to enter routine workflows. This changes product development timelines and alters risk profiles for clinical validation investments.
- Reimbursement evolution — Initial preventive and annual wellness services are already recognized within certain Medicare Advantage structures and commercial payer policies—creating a foundation for reimbursing exam-enabled services. However, reimbursement remains heterogeneous; the commercial winners will be those who build payer value cases that translate clinical efficiency into billable pathways.
- Workforce economics — Provider shortages and rising labor costs increase the appeal of solutions that offload low-complexity tasks to remote or patient-assisted workflows, but employers and health systems will demand hard ROI evidence tied to throughput, diagnostic yield and escalation reductions.
- Patient safety and scope-of-practice — Variation in state-level rules about who may complete history and physical examinations influences deployment choices. Successful commercial strategies will embed compliance and training as non-negotiable service components.
- Technology convergence — The combination of portable hardware, AI-assisted interpretation, and EHR integrations creates new product archetypes. These are no longer "nice-to-have" features: they are determinants of procurement decisions by health systems and large clinics.
Competitive landscape: who’s shaping the industry and how
The market remains fragmented—concentration is modest—which presents both risks and opportunities. Large legacy device manufacturers maintain trusted clinical relationships and distribution channels, while digitally-native entrants focus on software-enabled, consumer-friendly experiences.
Physical Examination Market
- Digitally-native innovators — Companies that offer integrated home and clinician-guided exam platforms are redefining patient access models. A notable recent development is an AI-enabled ENT suite receiving a novel regulatory classification in 2026, which signals that advanced image-analysis tools are moving to mainstream use and reimbursement conversations.
- Established device incumbents — Household names in clinical diagnostics continue to leverage brand trust, existing supply chains, and deep clinical workflows to defend install bases. Their challenge is to deliver digital capabilities and services at the speed of software-first competitors.
- Commercial implication — With top-tier players controlling a relatively small share of the total market, alliances and vertical integration can rapidly shift competitive positions. Strategic buyers and partners should expect consolidation opportunities—especially for assets that close capability gaps in AI interpretation, telehealth integration, or rapid regulatory compliance.
Strategic moves for 2026: recommended options by corporate agenda
- For incumbents: Accelerate digitization, selectively acquire differentiators
Prioritize partnerships or tuck-ins that add AI interpretation, remote monitoring, or consumer-friendly interfaces. Protect core clinical relationships by packaging service-level agreements and training programs that embed new devices into clinician workflows.
- For digital challengers: Prove value in focused clinical pathways
Target narrow, high-frequency use cases where remote or device-enabled exams reduce downstream costs (avoidable ER visits, specialist referrals). Use payer pilots to convert utilization improvements into reimbursement or bundled payment adoption.
- For payers and large employers: Design benefits to incentivize high-value use
Create defined coverage lanes for validated device-enabled exams in preventive and chronic-care pathways. Use value-based contracts to share savings with providers who adopt validated remote-exam technologies.
- For investors: Look for margin expansion and defensibility
Prioritize businesses demonstrating repeatable commercialization across multiple provider settings, strong data assets (annotated clinical images and sounds), and regulatory readiness that reduces time-to-revenue.
What success looks like in 2026
Organizations that move beyond product-led narratives and build integrated offerings—device, software, clinician workflows, reimbursement strategy, and analytics that demonstrate outcomes—will capture disproportionate share of growth. KPIs to monitor include trial-to-contract conversion rates, reimbursement acceptance time, per-encounter contribution margins after device amortization, and reduction in downstream utilization tied to early detection.
Why the granular data in the full report matters
The headline market trajectory (mid-single-digit CAGR to 2032, a near-400M USD market in 2025, and a material ramp to 2032) frames the opportunity, but high-confidence investment and operational choices require the granular, segmented intelligence that our full report provides. The public preview intentionally omits detailed regional and application-level splits, vendor revenue breakdowns and downloadable financial models—these are included in the complete study.
- Access to regional and channel segmentation tables to align go-to-market footprints with payer and regulatory realities.
- Vendor scorecards and benchmarking that quantify feature gaps, integration effort, and commercial traction.
- Scenario-ready financial models to stress-test pricing, reimbursement timing and pilot economics under alternative adoption curves.
How to use this preview
Use this article as a decision trigger. If your organization is considering investment, partnership, pilot deployment, or acquisition in the physical examination space in 2026, prioritize the following next steps:
- Request the full forecast model and run a three-case scenario (conservative, base, aggressive) tied to your payer mix and clinical settings.
- Conduct a 90-day market test focusing on a single clinical pathway with quantifiable outcomes (e.g., remote ENT screening, hypertension triage, annual wellness triage).
- Engage regulatory and compliance counsel early to map state-level practice limitations into deployment timelines and training requirements.
- Build a reimbursement dossier that translates clinical impact into billable codes and payer acceptance criteria; use pilot data to accelerate payer conversations.
PW Consulting’s full Physical Examination Market study delivers the segment-level detail, vendor profiles, downloadable financial models and playbooks required to operationalize these recommendations. For executives who need to make binding resource-allocation decisions in 2026, this is not a market to watch from the sidelines—it's a market to structure a tested, risk-managed entry into, with a clearly measurable path to scale.
For detailed analysis of this topic, please visit the official page: Physical Examination Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Stainless Steel Flanges Market to Reach USD 8.42B by 2032 at 5.4% CAGR
By pmarketresearch, 2026-07-13
Stainless Steel Flanges Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market study on stainless steel flanges provides a forward-looking, decision-oriented briefing designed to equip executives, procurement leaders, and investors for the strategic choices they must make in 2026. This preview highlights the study’s core strategic value, synthesizes the macro trajectory, flags the immediate regulatory and commodity shocks that will shape margins and flows this year, and outlines the tactical playbook our full report delivers. The goal here is to demonstrate analytical depth while reserving the full, granular datasets and segment tables to the source report.
Stainless Steel Flanges Market
Market trajectory and what it means for 2026 planning
The stainless steel flanges market has shown steady expansion through the 2020–2025 period, and our modeling positions 2025 as the analytical base year. The market was approximately USD 5.83 billion in 2025 and is projected to continue expanding through the forecast window. Our scenario suite, calibrated to observable drivers and recent policy shocks, yields a 2026–2032 compound annual growth rate (CAGR) of 5.4%, taking the market from an estimated USD 6.0 billion in 2026 to roughly USD 8.42 billion by 2032.
Stainless Steel Flanges Market
That trajectory matters for 2026 because it is not merely a volume story: growth is occurring against a backdrop of supply-chain repricing, regulatory compliance costs, and trade-policy friction. The consequence is that unit economics and supplier reliability will eclipse simple demand forecasts as the primary determinants of competitive advantage.
Stainless Steel Flanges Market
Immediate dynamics reshaping supplier and buyer strategies
-
Regulatory regime shifts. From January 1, 2026, carbon-border adjustment mechanisms (CBAM) began applying to imported steel products, requiring transparent carbon-footprint reporting and exposing non-compliant imports to penalties. Simultaneously, several major exporting countries implemented tighter export controls and documentary requirements for steel products effective at the start of 2026.
-
Trade protection and market access. Recent antidumping and trade measures affecting stainless steel flanges have changed sourcing calculus in key markets. Buyers that relied on low-cost global sources may confront sudden tariff or compliance costs that erode previously assumed advantages.
-
Raw material price volatility. Nickel — a primary cost driver for many stainless alloys — has shown renewed volatility. Prices recorded in mid‑2026 demonstrate both the magnitude and pace of potential margin impact; our sensitivity models quantify how swings in nickel translate into margin compression across common fabrication and distribution business models.
-
Moderate industry concentration. Market concentration is meaningful but not dominant: the top three competitors account for a significant share of demand but do not create a closed oligopoly. That structure enables strategic consolidation, targeted partnerships, and differentiated product positioning.
How PW Consulting’s analysis turns these dynamics into actionable strategy
Our full report does more than forecast — it operationalizes strategy. Key deliverables include:
- Transparent market-sizing and reproducible methodology (historical 2020–2025 and forecast 2026–2032), plus scenario-based sensitivities tied to commodity and regulatory shocks.
- Supply-chain maps that identify single-source risks, near‑term bottlenecks (processing, testing, certification), and realistic mitigation options by buyer profile.
- Price and margin models that translate nickel and alloy inputs into finished-goods costs under common manufacturing footprints (forging, machining, fabrication), enabling rapid “what-if” assessments for procurement teams.
- Regulatory impact matrix (CBAM, export licensing, antidumping) that ranks market exposure by trade lane and recommends compliance clauses and audit-ready documentation templates.
- Go-to-market and channel playbooks for manufacturers and distributors, covering premiumization, service differentiation, and cost-leadership pathways.
- Investment and M&A screening frameworks — from bolt-on acquisition targets to greenfield processing — prioritized by strategic fit, integration risk, and value-creation horizon.
- Practical contract and sourcing templates (carbon clauses, price‑adjustment triggers, quality and certification SLAs) calibrated to emerging regulatory norms.
Competitive landscape — how incumbents and challengers are positioned
The sector’s participant mix contains a spectrum of business models: premium grade producers, localized fabricators, high-volume manufacturers, and specialized distributors. Below is a concise strategic read on selected firms covered in our competitive analysis:
- Outokumpu Oyj (Helsinki, Finland) — A premium, corrosion-resistant stainless producer with engineering-led product development. Outokumpu’s strengths lie in grade differentiation and servicing industrial end‑users that prioritize lifecycle cost and corrosion performance.
- Texas Flange (Houston, U.S.) — A supply-focused, standards-compliant supplier with strong market access in petrochemical and waterworks markets. Their value proposition centers on code-compliance and fast-turn ANSI/ASME deliveries to U.S. projects.
- Shaw Stainless & Alloy (Marietta, U.S.) — Distributor–fabricator hybrid offering localized custom fabrication and assembly, appealing to pharmaceutical and wastewater clients that need tight tolerances and prompt lead times.
- Longan Flange, Kaysuns, Jiette Pipe, Zhejiang Zhiju (China) — A cluster of manufacturers combining large-diameter capabilities, standards-compliant production, and cost competitiveness for volume projects. Their agility in meeting large DN requirements is a differentiator for infrastructure programmes.
- API International, ASC Engineered Solutions, Kitz Corporation — Suppliers and fabricators focused on machined, forged, or cast solutions meeting industrial standards. They compete on certified quality and engineering services for oil & gas and power generation clients.
Collectively, the top firms show that the market is sufficiently concentrated to reward scale and certification-backed quality, while leaving room for regional specialists and service-oriented players to capture margin-rich niches. Our report’s competitor dashboards include capability matrices, certification ownership, quality-test turnaround times, and a proprietary supplier-risk score — details available in the full dossier.
Risk scenarios you must model in 2026
-
Commodity shock: Rapid nickel appreciation can erode margins on fixed long-term contracts. Our sensitivity analysis models multiple nickel price paths and recommends hedge ratios by business model (distributor vs. manufacturer vs. EPC contractor).
-
Regulatory shock: Enforcement of CBAM-like measures and export license controls increases documentation overhead and can render certain sourcing lanes uneconomic. We provide a compliance-cost ladder and a prioritized mitigation roadmap for 2026.
-
Trade barriers: Antidumping rulings create immediate dislocations in sourcing. Scenario playbooks include rapid qualification of alternative suppliers, short-term inventory strategies, and contract renegotiation language to preserve margins.
Recommended 2026 playbook — prioritized actions
- 0–6 months : Execute supplier carbon audits and insert CBAM-compliance clauses into new purchase orders; introduce price-adjustment triggers tied to nickel indices; build 90–180 day safety stock for critical diameters where lead times are volatile.
- 6–18 months : Shift a portion of strategic volumes to suppliers with certified low-carbon footprints or localized processing; evaluate co‑investment in finishing assets to control certification and lead times.
- 18–36 months : Pursue targeted M&A or JV opportunities to secure capacity in key regions and integrate upstream alloy procurement to capture margin and control carbon-intensity reporting.
What the full PW Consulting report contains (and why it matters)
For executives who must make procurement, caps‑ex, or M&A decisions in 2026, the full study offers the quantitative backbone and operational templates needed to act with speed and conviction. The comprehensive package includes:
- Downloadable time series market-size files and reproducible forecasting models.
- Segment and regional demand tables (note: these granular tables are intentionally withheld from this preview and are accessible in the full report).
- Supplier scorecards, regulatory-impact checklists, and contract templates for immediate deployment.
- Executive briefings and board-ready slides summarizing scenario conclusions and recommended capital allocation pathways.
Closing — why 2026 is a strategic inflection
2026 is the year in which regulatory transparency (carbon reporting), commodity volatility (notably nickel), and trade policy re‑alignment converge to reshape value capture in the stainless steel flanges market. The macro trajectory — steady growth through 2032 at a mid-single-digit CAGR — masks a highly differentiated competitive landscape where compliance, proximity to demand, and control of alloy costs will determine winners. PW Consulting’s full study provides the granular datasets, supplier analytics, and executable playbooks that senior leaders need to translate that macro outlook into defensible, revenue‑protecting, and margin-enhancing decisions.
To access the complete datasets, granular segmentation and supplier-level analytics referenced here, download the full Stainless Steel Flanges Market report from PW Consulting or contact our advisory team for a tailored briefing and the proprietary models that will support your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Stainless Steel Flanges Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Biopesticide Market to Hit USD 15.65B by 2032 at 11.15% CAGR
By pmarketresearch, 2026-07-13
Biopesticides 2026: Strategic Briefing for Decision-Makers
Executive teaser
The biopesticide sector is no longer a niche sideline of crop protection — it is a rapidly maturing market that will materially reshape portfolio strategies, supply chains and regulatory playbooks in 2026 and beyond. Our PW Consulting market study (base year 2025, forecast to 2032) shows a sustained double‑digit expansion at a compounded annual growth rate of c.11.15%. The global market more than doubles across the forecast window, underscoring both commercial opportunity and the need for disciplined, evidence‑based strategic choices. This briefing highlights why the study is indispensable to boards, business unit leaders and investors preparing for near‑term rollouts, capex calls, alliances and M&A decisions — while reserving the granular segmentation matrices and price curves for the full report to protect the competitive lift that subscribers obtain.
Biopesticide Market
Market trajectory and what it means for 2026 decisions
-
Macro trajectory: From a base of roughly USD 7.5 billion in 2025, the market is projected to exceed USD 15.6 billion by 2032 under the central scenario. That scale shift is driven by regulatory momentum, improved manufacturing economics and accelerating farmer adoption across commercial and specialty crops.
Biopesticide Market -
Strategic inflection: For companies contemplating investment in fermentation capacity, acquisitions of microbial platforms, or global registration campaigns, 2026 is a critical ‘go/no‑go’ window. Early movers who secure registration breadth and scalable supply will lock in advantaged distribution economics as adoptive curves steepen.
Biopesticide Market -
Required discipline: Rapid growth masks heterogeneous unit economics across product types and channels. Winning in 2026 requires integrating regulatory strategy, techno‑economic manufacturing analysis and a go‑to‑market model that aligns product claims with farmer ROI and agronomic advisors’ workflows.
Why this study is a practical decision tool
PW Consulting’s Biopesticide Market study was designed as a working toolkit for commercial leaders and investors. It synthesizes market sizing and a seven‑year forecast with operationally focused deliverables: regulatory pathway maps by target jurisdiction, trial and label acceleration playbooks, COGS and fermentation scale models, channel taxation and margin templates, product launch readiness checklists and a prioritized list of country dossiers for registration. The report couples market analytics with tactical instruments so teams can convert market opportunity into executable project plans within 90–180 days.
Competitive landscape — what incumbents and challengers are doing
The competitive field combines major crop protection groups moving biologicals into core portfolios and specialist biocontrol firms innovating at product and service layers. Market concentration is moderate and growing: the top three firms account for a meaningful share of sales while the top five increase that footprint further, indicating both consolidation pressure and room for disruptive entrants.
-
BASF SE: Leveraging industrial biotechnology capabilities and recent investment in BioHub fermentation capacity, BASF is pursuing scalable supply and an expanded microbial portfolio to serve large‑acre arable segments.
-
Bayer AG: Bayer’s biologicals arm continues to blend acquisition and licensing strategies to accelerate label extension across arable and specialty crops; exclusivity agreements are a core tactic to secure pipeline advantage.
-
Syngenta Group: Positioned to bundle microbial and biochemical solutions with digital agronomy offerings, Syngenta is focusing on integrated soil‑health and pest management platforms.
-
Corteva Agriscience and FMC: Both are integrating AI and high‑throughput screening to shorten discovery cycles and optimize field performance, while selectively partnering with microbial innovators to enhance speed to market.
-
Specialists (Valent BioSciences, Marrone, Koppert, Andermatt, Lallemand, Certis, BioWorks, Novonesis, Nufarm, Bioceres): These firms are doubling down on differentiation — botanical actives, entomopathogenic viruses, beneficial microbes and biologically derived formulations — and winning share in high‑value horticulture, organic and greenhouse channels.
For commercial leaders, the key takeaway is clear: strategic responses must be hybrid. Scale players should invest in flexible fermentation and regulatory capacity; specialists should defend high-margin channels and pursue partnerships that broaden market access without diluting technical IP.
Regulatory and supply dynamics shaping 2026
-
Regulatory acceleration: Early 2026 saw multiple proposed registrations in the US and an uptick in formal guidance from regionally important agencies. Guidance documents and trial standards published by industry bodies are reducing time to acceptance — but evolving data requirements in major markets (notably the EU) will continue to set the pace for dossiers and labeling strategies.
-
Manufacturing & raw‑material implications: Advances in fermentation technology and new BioHub facilities materially reduce unit costs for fungal and bacterial actives, moving several product classes from boutique to industrial scale. That shift favors players who can operationalize quality‑by‑design at scale and secure feedstock reliability.
-
Field adoption governance: Publication of commercial trial and grower assessment guidelines is improving comparability of efficacy data. Buyers and regulators will increasingly demand standardized trial outcomes as part of registration and procurement decisions.
Commercial playbook highlights for 2026
-
Prioritize registration sequencing: Adopt a portfolio approach that balances quick wins in receptive markets with targeted investment to unlock larger markets that require more extensive data. Use staged launches to monetize incremental registrations.
-
De‑risk manufacturing through hybrid strategies: Combine in‑house fermentation for core actives with CMOs for scale peaks. Stress‑test supplier options in 12–18 month simulations under scenarios of raw material volatility and regulatory hold‑ups.
-
Align channel economics to farmer ROI: Design product bundles (biological + biological/chemical rotation plans), trial evidence packages and pay‑for‑performance pilots so advisors and distributors can justify premium pricing to growers.
-
Use alliances to accelerate adoption: Licensing deals and targeted co‑development agreements are now faster routes to scale than greenfield commercialization for many mid‑sized players.
Investment, M&A and partnership implications
Private equity and strategic buyers will find compelling assets across the value chain: microbial discovery platforms with validated modes of action, niche players with strong channel positions in high‑value crops, and fermentation/bioprocessing assets that can be integrated into existing chemical manufacturing footprints. Our report provides valuation comparables, sensitivity analyses and a prioritized M&A wishlist that maps to three strategic archetypes: Capability Buyer (manufacturing/scale), Portfolio Buyer (label breadth) and Channel Buyer (distribution and specialty crops).
Risk matrix — what to watch in 2026
-
Regulatory divergence: Changes in microbial data demands across jurisdictions can materially delay launch timelines and inflate approval costs.
-
Supply bottlenecks: Even with fermentation advancements, capacity allocation and quality control remain critical — failures here can erode trust with growers and distributors.
-
Performance variability: Biologicals are inherently more sensitive to field conditions — robust IPM integration and local trial evidence will be a competitive moat for market leaders.
-
Consolidation pressure: The moderate concentration of the market means smaller players face acquisition pressure or margin compression unless they carve defensible niches.
What the full PW Consulting report delivers (practically)
-
Validated market sizing and a granular forecast model (2026–2032) with scenario toggles for regulatory, adoption and price sensitivity.
-
Regulatory pathway maps and country‑level dossier checklists prioritized by commercial impact.
-
Manufacturing techno‑economic models for fermentation, formulation and packaging across scale points.
-
Commercial trial templates, label claim evidence packages and grower adoption playbooks for rapid field validation.
-
Competitive benchmarking, CRx concentration analysis and executable M&A/partnership frameworks.
-
Investor briefings, board‑ready slide decks and a 90‑day launch action plan tailored to your company archetype.
Note: To preserve the strategic value of the analysis, detailed regional and application splits, price curves and sub‑segment financials are intentionally withheld from this summary. Subscribers to the full report receive the complete dataset and editable models.
How PW Consulting recommends you act in 2026
-
Immediate (0–3 months): Run a gap analysis versus the report’s registration and manufacturing templates; secure pilot agreements with 1–2 CMOs; prioritize dossiers for immediate filing.
-
Near term (3–9 months): Launch controlled commercial trials using standardized protocols; finalize at least one strategic licensing or co‑development agreement if you lack discovery breadth.
-
Medium term (9–18 months): Execute scale‑up on fermentation assets or integrate acquired capabilities; lock distribution partnerships in priority geographies; align pricing models to verified farmer ROI.
Closing — why this matters now
Biopesticides are transitioning from experimental adjuncts to core tools in modern crop protection. The combination of regulatory momentum, improved manufacturing economics and clearer field adoption pathways creates a narrow but decisive window for leaders to secure durable advantage. Our full PW Consulting study arms executives with the forensic market evidence, operational playbooks and deal roadmaps required to turn growth into profitable, defensible scale. For teams planning capex, M&A or global launches in 2026, the choice is simple: move with a validated plan or risk being reactive in a market that rewards preparedness.
Access to the full dataset, segmentation matrices and executable templates is available through the PW Consulting report portal for subscribers and select clients.
For detailed analysis of this topic, please visit the official page: Biopesticide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Carpet tiles market to reach USD 20.53M by 2032 at 6.4% CAGR
By pmarketresearch, 2026-07-13
Carpet Tiles Market 2026: Strategic Preview for Decision-Makers
As the global built environment navigates economic recalibration, sustainability mandates and evolving specification preferences, carpet tiles have re-emerged as a strategic material choice for owners, designers and manufacturers alike. PW Consulting’s new Carpet Tiles Market study (base year 2025, forecast 2026–2032) synthesizes five years of market movement and a seven-year outlook to give executives the actionable intelligence they need for decisive 2026 planning.
Carpet Tiles Market
Market snapshot — pacing and scale
The carpet tiles market has demonstrated steady expansion through the early 2020s, growing from approximately USD 9.8 million in 2020 to USD 13.3 million in 2025. Our forecast, built on demand drivers, cost trajectories and adoption curves, anticipates growth at a compound annual growth rate of roughly 6.4% across 2026–2032, reaching an estimated USD 20.5 million by 2032. Market concentration is meaningful: the three largest players control a majority share (CR3 ~55%), and the top five account for roughly 70% of global value — a structure that shapes competitive dynamics, margin pools and channel negotiation power.
Carpet Tiles Market
Why this matters for 2026 strategic decisions
For corporate leaders planning capital allocation, product roadmaps, or go-to-market moves in 2026, three truths emerge from our analysis:
Carpet Tiles Market
- Sustainability is table stakes, but execution divides winners from laggards. Clients and procurement policies increasingly specify environmental performance as a primary criterion. Companies that translate sustainability commitments into verifiable product attributes, lifecycle transparency and circular service models gain price resilience and specification leadership.
- Modularity and installation economics drive commercial demand. The advantages of modular carpet tiles for flexibility, repairability and phased fit-outs mean that product design and service propositions (replacements, take-back, refurbishment) can become primary differentiators.
- Consolidation and channel control create strategic openings for niche innovators. With a concentrated supplier base, selective M&A and focused partnerships — especially in sustainability-certified, design-forward niches — offer routes to rapid scale or to defensible premium positioning.
From insight to action: where to focus in 2026
- Product strategy — design, materials, and service bundles. Prioritize carpet tile collections that balance design differentiation with modularity and reparability. Invest in validated recycled content and low-emission systems, and design commercial-grade warranty/service bundles that monetize long-term maintenance and refurbishment.
- Supply chain — localization and duty engineering. Reassess sourcing strategies in light of tariff shifts and trade agreements. The CUSMA/USMCA rules of origin create a cost advantage for qualifying North American manufactured tiles intended for intra-regional trade; consider nearshoring or regional platform strategies to secure margin and delivery velocity.
- Pricing and commercial policy. With manufacturers passing through input costs and tariffs selectively, 2026 will be a year where smart price architecture (value-based pricing for sustainability and lifecycle services) beats uniform cost-plus approaches.
- M&A and partnerships. Pursue tuck-ins that add circular capabilities (recycling, take-back), or creative brands with strong design credentials to access new specification channels without undermining incumbent relationships.
- Specification & channel influence. Strengthen relationships with specifiers, national contractors and workplace consultants. A small number of decisions (large commercial projects, hospitality roll-outs) can move volumes disproportionately given the market’s concentration profile.
Competitive landscape — what the leaders are doing (and why it matters)
The competitive map is populated by established global flooring groups and focused specialists. What binds the leaders is a dual emphasis on product breadth and sustainability credibility; distinctions appear in route-to-market, R&D depth, and service-oriented business models.
- Interface, Inc. (Atlanta) continues to position itself at the intersection of design and sustainability. Recent launches underscore a strategy of marrying design narratives with low-carbon credentials — a play that supports premium positioning in commercial interiors and corporate procurement lists. Interface’s long-standing PFAS-free policy and carbon-focused commitments give them specification traction with sustainability-driven buyers.
- Mohawk Industries, Inc. (Dalton) leverages scale and a multi-brand approach to serve diverse channels. Mohawk’s engagement in design showcases signals efforts to drive emotional and tactile differentiation — an effective route to defend commercial projects where aesthetics and occupant experience influence supplier selection.
- Shaw Industries Group (Dalton) deploys product refresh cycles and sustainability messaging to remain competitive. Their portfolio refresh and event-led product launches indicate continued investment in design-led specification activity.
- Milliken & Company (LaGrange) focuses on performance and design-led modular solutions for institutional and commercial segments. Their recent collection launches reflect a strategy of targeted creativity to capture projects where brand-driven selection matters.
- Tarkett, Forbo, and European specialists (e.g., Fletco, BLOQ). These companies increasingly compete on regenerative materials and production transparency. Fletco’s 100% CO2-neutral production and use of regenerated yarns exemplify an industrial model that appeals to project teams targeting ambitious sustainability targets.
- Regional manufacturers and integrated players (e.g., Al Abdullatif). Fully integrated platforms in certain regions combine price control with tailored local go-to-market reach — a powerful combination where specification preferences include local content and rapid delivery.
Recent product activity — from Interface’s design-led launches to Milliken and Shaw’s refreshed lines and Fletco’s regenerated-yarn collections — reveals an industry where innovation is incremental but decisive. Expect successful products to combine tactile appeal, installation efficiencies and verifiable sustainability metrics.
Regulatory and cost tailwinds — practical implications
- Chemical and product regulation: The industry-wide removal of PFAS from U.S. carpet production since 2019 is now a baseline expectation for many specifiers. Suppliers without credible product chemistry transparency risk exclusion from public and corporate bids.
- Tariffs and trade policy: Tariff adjustments on imported hard-surface and decorative products have introduced price inflation in certain channels; some manufacturers implemented price increases in 2025. Product sourcing strategies must therefore be stress-tested against further tariff volatility.
- Trade advantages: Duty rules under CUSMA/USMCA can be a competitive lever for North American manufacturers exporting regionally — a structural edge for those who can certify origin and manage compliance efficiently.
- Energy and production footprint: Claims of CO2-neutral production, as demonstrated by some European manufacturers, are increasingly material in public and large corporate procurement. Investing in verifiable renewable-energy sourcing or procurement partnerships can unlock specification wins and allow premium pricing.
Risk matrix for 2026 decision-makers
- Execution risk: Failure to operationalize sustainability claims (traceability, take-back, recycled content verification) will erode credibility rapidly.
- Channel concentration: Heavy dependence on a small number of commercial specification channels increases exposure to project cyclicality and competitive displacement.
- Commodity & labor cost volatility: Raw material swings and regional labor cost inflation can compress margins unless offset by price discipline or local manufacturing adjustments.
- Regulatory surprises: Unanticipated chemical or trade policy changes could accelerate product reformulation costs or reconfigure supply chains.
What PW Consulting’s Carpet Tiles report delivers (practical, usable outputs)
We designed this study to be directly operational for 2026 planning cycles. Highlights include:
- Market-sizing and forward scenarios (base year 2025; forecast 2026–2032) with sensitivity runs for demand, price and tariff permutations.
- Competitive playbooks that translate public moves (product launches, sustainability claims, showroom strategies) into tactical responses for manufacturers and distributors.
- Supply-chain heatmap and sourcing decision framework that integrates duty engineering, freight/delivery risk and regional labor considerations.
- Sustainability commercialization toolkit: how to validate claims, design circular services, and structure warranty and take-back economics.
- Go-to-market architectures for incumbents and entrants: segmentation of channels by specification influence, procurement behavior and lifecycle expectations (note: detailed subsegment market shares and unit economics are reserved for subscribers).
- Deal and partnership checklist for M&A, joint ventures and licensing arrangements that accelerate capability acquisition while preserving margin discipline.
How to use this research in 90 days
- Week 1–3: Align executive priorities using our scenario outputs — set price guardrails, sustainability targets and channel investment limits.
- Week 4–8: Stress-test your supply chain and sourcing plan against tariff and origin scenarios using our supply-chain heatmap.
- Week 9–12: Deploy the sustainability commercialization toolkit to validate product claims and design an initial take-back pilot for a single product line or market.
Closing perspective
Carpet tiles sit at an intersection of design, operational flexibility and environmental ambition. The coming 12–18 months will reward organizations that convert sustainability commitments into verifiable product systems, that retool supply chains to neutralize tariff and freight exposure, and that lean into modular service economics that project owners now prize. PW Consulting’s Carpet Tiles Market study gives leaders a pragmatic roadmap — from scenario planning to market-winning product and channel plays — to make 2026 a year of strategic clarity rather than tactical reaction.
For companies preparing capital budgets, product roadmaps or acquisition strategies in 2026, the study provides the quantified scenarios and executable tools required to prioritize investment and to defend or expand specification share. For full subsegment detail, supplier-by-supplier share analysis, and the proprietary worksheets that underlie our scenario modelling, please refer to the full PW Consulting report.
For detailed analysis of this topic, please visit the official page: Carpet Tiles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com