

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Physical Examination Market to Hit USD 618.57M by 2032 at 7.0% CAGR

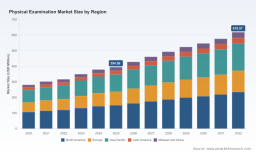
Physical Examination Market 2026: Strategic Preview for Executives
As healthcare systems rethink how routine and diagnostic care are delivered, the physical examination market is moving from a place of steady clinical utility to one of strategic commercial importance. PW Consulting’s latest market research—anchored to a 2025 base year and projecting through 2032—identifies this market as a mid-sized, fast-evolving sector with a clear growth trajectory (CAGR 7.0% across the 2026–2032 forecast window). The market expanded materially during 2020–2025 as technology adoption and changing reimbursement created new use cases; by 2025 the global market reached just under USD 400 million (USD Million basis). Our study synthesizes that momentum into a practical, decision-grade playbook for 2026.
Physical Examination Market
Why this study matters for 2026 decision-makers
- Timing — 2026 is a pivot year. Recent regulatory approvals and evolving payer rules have materially changed the commercial calculus for remote-enabled and device-centric examination solutions.
- Clarity — The market is growing at a mid-single-digit compounded pace (7.0% CAGR forecast), but distribution is uneven across modalities, channels and vendors; strategic clarity on where to position investments is now value-creating.
- Actionability — Our research is designed to convert insight into initiative: from go-to-market choices and reimbursement strategies to M&A screening and product roadmaps.
What the full report delivers (practical, non-academic outputs)
- Executive synthesis of market dynamics, including regulatory inflection points, reimbursement levers and provider adoption barriers.
- Proprietary forecast model (2026–2032) calibrated to policy scenarios, technology adoption curves and capacity constraints—deliverable as a live spreadsheet to run bespoke scenarios.
- Commercial playbooks for eight strategic routes-to-market (e.g., direct to hospital systems, OEM-integrated diagnostic walls, remote subscription models, channel partnerships with diagnostics centers).
- Regulatory and reimbursement roadmaps that translate recent rulings and claims policy into timing and probability estimates for reimbursement acceptance across major payers.
- Practical ROI and unit-economics templates for pilots and scale initiatives, including sensitivity to labor-cost, device amortization and payor mix.
- Vendor benchmarking and partnership matrices focused on capability gaps (device hardware, AI-enabled interpretation, integration with EHR, after-sales service) rather than headline market share alone.
- M&A screening criteria and a short-list methodology for prioritizing assets that accelerate market entry or close technology gaps.
Market context and dynamics: the forces shaping 2026 decisions
The physical examination market entered 2026 with clear momentum. Over the 2020–2025 period the market expanded significantly as telemedicine acceptance rose and providers experimented with hybrid care models; by our base year the market neared the USD 400 million mark. Looking forward, a 7.0% compound annual growth rate through 2032 implies steady expansion, but the underlying drivers deserve careful unpacking:
Physical Examination Market
- Regulatory inflection points — Recent device clearances and new regulatory pathways (example: De Novo classification for novel AI-assisted ENT image analysis) lower barriers for advanced diagnostic modules to enter routine workflows. This changes product development timelines and alters risk profiles for clinical validation investments.
- Reimbursement evolution — Initial preventive and annual wellness services are already recognized within certain Medicare Advantage structures and commercial payer policies—creating a foundation for reimbursing exam-enabled services. However, reimbursement remains heterogeneous; the commercial winners will be those who build payer value cases that translate clinical efficiency into billable pathways.
- Workforce economics — Provider shortages and rising labor costs increase the appeal of solutions that offload low-complexity tasks to remote or patient-assisted workflows, but employers and health systems will demand hard ROI evidence tied to throughput, diagnostic yield and escalation reductions.
- Patient safety and scope-of-practice — Variation in state-level rules about who may complete history and physical examinations influences deployment choices. Successful commercial strategies will embed compliance and training as non-negotiable service components.
- Technology convergence — The combination of portable hardware, AI-assisted interpretation, and EHR integrations creates new product archetypes. These are no longer "nice-to-have" features: they are determinants of procurement decisions by health systems and large clinics.
Competitive landscape: who’s shaping the industry and how
The market remains fragmented—concentration is modest—which presents both risks and opportunities. Large legacy device manufacturers maintain trusted clinical relationships and distribution channels, while digitally-native entrants focus on software-enabled, consumer-friendly experiences.
Physical Examination Market
- Digitally-native innovators — Companies that offer integrated home and clinician-guided exam platforms are redefining patient access models. A notable recent development is an AI-enabled ENT suite receiving a novel regulatory classification in 2026, which signals that advanced image-analysis tools are moving to mainstream use and reimbursement conversations.
- Established device incumbents — Household names in clinical diagnostics continue to leverage brand trust, existing supply chains, and deep clinical workflows to defend install bases. Their challenge is to deliver digital capabilities and services at the speed of software-first competitors.
- Commercial implication — With top-tier players controlling a relatively small share of the total market, alliances and vertical integration can rapidly shift competitive positions. Strategic buyers and partners should expect consolidation opportunities—especially for assets that close capability gaps in AI interpretation, telehealth integration, or rapid regulatory compliance.
Strategic moves for 2026: recommended options by corporate agenda
- For incumbents: Accelerate digitization, selectively acquire differentiators
Prioritize partnerships or tuck-ins that add AI interpretation, remote monitoring, or consumer-friendly interfaces. Protect core clinical relationships by packaging service-level agreements and training programs that embed new devices into clinician workflows.
- For digital challengers: Prove value in focused clinical pathways
Target narrow, high-frequency use cases where remote or device-enabled exams reduce downstream costs (avoidable ER visits, specialist referrals). Use payer pilots to convert utilization improvements into reimbursement or bundled payment adoption.
- For payers and large employers: Design benefits to incentivize high-value use
Create defined coverage lanes for validated device-enabled exams in preventive and chronic-care pathways. Use value-based contracts to share savings with providers who adopt validated remote-exam technologies.
- For investors: Look for margin expansion and defensibility
Prioritize businesses demonstrating repeatable commercialization across multiple provider settings, strong data assets (annotated clinical images and sounds), and regulatory readiness that reduces time-to-revenue.
What success looks like in 2026
Organizations that move beyond product-led narratives and build integrated offerings—device, software, clinician workflows, reimbursement strategy, and analytics that demonstrate outcomes—will capture disproportionate share of growth. KPIs to monitor include trial-to-contract conversion rates, reimbursement acceptance time, per-encounter contribution margins after device amortization, and reduction in downstream utilization tied to early detection.
Why the granular data in the full report matters
The headline market trajectory (mid-single-digit CAGR to 2032, a near-400M USD market in 2025, and a material ramp to 2032) frames the opportunity, but high-confidence investment and operational choices require the granular, segmented intelligence that our full report provides. The public preview intentionally omits detailed regional and application-level splits, vendor revenue breakdowns and downloadable financial models—these are included in the complete study.
- Access to regional and channel segmentation tables to align go-to-market footprints with payer and regulatory realities.
- Vendor scorecards and benchmarking that quantify feature gaps, integration effort, and commercial traction.
- Scenario-ready financial models to stress-test pricing, reimbursement timing and pilot economics under alternative adoption curves.
How to use this preview
Use this article as a decision trigger. If your organization is considering investment, partnership, pilot deployment, or acquisition in the physical examination space in 2026, prioritize the following next steps:
- Request the full forecast model and run a three-case scenario (conservative, base, aggressive) tied to your payer mix and clinical settings.
- Conduct a 90-day market test focusing on a single clinical pathway with quantifiable outcomes (e.g., remote ENT screening, hypertension triage, annual wellness triage).
- Engage regulatory and compliance counsel early to map state-level practice limitations into deployment timelines and training requirements.
- Build a reimbursement dossier that translates clinical impact into billable codes and payer acceptance criteria; use pilot data to accelerate payer conversations.
PW Consulting’s full Physical Examination Market study delivers the segment-level detail, vendor profiles, downloadable financial models and playbooks required to operationalize these recommendations. For executives who need to make binding resource-allocation decisions in 2026, this is not a market to watch from the sidelines—it's a market to structure a tested, risk-managed entry into, with a clearly measurable path to scale.
For detailed analysis of this topic, please visit the official page: Physical Examination Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com