

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rotary Cutters Market to Reach USD 344.8M by 2032

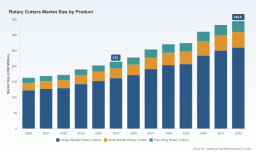
Rotary Cutters Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic briefing intended to frame the rotary cutters market for executive decisions in 2026. This teaser synthesizes the most consequential macro trends and competitive inflection points derived from our full market study (base year 2025; historical window 2020–2025; forecast 2026–2032). The global market has demonstrated resilient expansion through the last half-decade and—guided by a 6.8% compound annual growth rate in our forecast—continues on a trajectory that creates distinct windows for investment, product innovation, and channel repositioning. The objective here is to establish the strategic line-of-sight you need; proprietary segment tables and granular breakdowns are intentionally withheld and available in the full report at pwconsulting.com to support transaction-level and go-to-market execution.
Rotary Cutters Market
Why this market matters in 2026
-
Structural durability: Rotary cutters remain foundational to agricultural, roadside, and land-management operations. Even as mechanization evolves, the category benefits from steady replacement cycles, aftermarket services, and product upgrades that support healthy margin pools for OEMs and dealers.
Rotary Cutters Market -
Accelerating commercial opportunities: With the market base expanding from recent years into 2026, OEMs that combine product robustness with optimized service networks can capture disproportionate value—particularly through aftermarket parts, service contracts, and retrofit kits.
Rotary Cutters Market -
Capital-light growth vectors: Partnerships, contract manufacturing transitions, and targeted local production are emerging as faster and lower-capital routes to market share gains compared with greenfield facilities—important for balancing 2026 capital allocation decisions.
Condensed market snapshot (strategic highlights)
-
Market momentum: The global rotary cutters market reached a meaningful baseline in our 2025 assessment and enters a multi-year expansion phase. Our forecast assumes a 6.8% CAGR through 2032, reflecting both underlying demand growth and incremental value capture from higher-spec models and service monetization.
-
Concentration and competitive dynamics: The market exhibits moderate concentration among a small group of established OEMs. The top-tier firms collectively command a material share of the market, leaving room for niche players to scale through product specialization, distribution depth, or service excellence.
-
Service and maintenance as a lever: Recent operational improvements—such as reduced regrinding lead times in North America—underscore that aftermarket responsiveness is an increasingly important differentiator for both OEMs and distributors.
What the full PW Consulting study gives you (practical, decision-ready content)
Our full report is structured to move leaders from insight to action. Highlights include:
-
Robust market sizing and forward-looking scenarios: Proprietary top-line demand models, sensitivity analyses (price, fuel and steel cost, dealer inventory turns), and three demand scenarios to stress-test capital plans and product roadmaps.
-
Go-to-market playbooks: Channel economics for dealer networks, OEM-direct vs. distributor strategies, parts-and-service monetization models, and customer segmentation frameworks that prioritize returns on sales and service investments.
-
Product and engineering implications: Benchmarks for durability design, lessons from gearbox and deck redesigns, and a prioritized matrix of feature investments that yield the best combination of customer value and manufacturing cost efficiency.
-
Supply chain and operations toolkit: Cost-to-serve maps, supplier risk heatmaps (including steel and gearbox components), and operational playbooks to reduce lead times and increase first-time-fix rates in field service.
-
M&A and portfolio optimization support: Screening criteria for bolt-on acquisitions, value-creation levers post-close, and modeled returns under multiple integration choices.
-
Commercial pilots and KPIs: Ready-to-run pilot designs for new service offerings, pricing experiments, and dealer incentive schemes—each with target KPIs and expected payback timelines.
Competitive landscape — what to watch in 2026
The competitive fabric of the rotary cutters market blends long-standing OEM brands with regional specialists and emerging partnerships. Below are the firms central to our landscape analysis and the strategic implications executives should factor into 2026 plans.
-
Bush Hog (Selma, Alabama) : A North American stalwart with broad product coverage and an extensive dealer network. Their recent product iterations emphasize reinforced structures—an engineering response to customer demand for higher durability. Strategically, Bush Hog’s depth in distribution and brand recognition makes it both a formidable incumbent and an attractive partner for supply consolidation or aftermarket growth initiatives.
-
Alamo Industrial : Known for roadside and off-road cutting heads, Alamo’s engineering focus on specialty applications gives it a differentiated position—especially where regulatory or roadside-standards complexity elevates switching costs. Watch for selective partnerships or production transitions that reallocate capacity across brands.
-
Schulte Industries (Canada) : A player in large-capacity rotary cutter designs. Schulte’s product scale advantage is a defensive moat for customers requiring higher throughput equipment, and it positions the company as a supplier of choice where field productivity is paramount.
-
Land Pride (Salina, Kansas) : Strong in farm and roadside segments with a diverse model family. Their emphasis on modularity and OEM channel relations makes them strategically relevant for OEMs seeking partnerships to expand model breadth quickly.
-
Woods Equipment (Oregon) : With a mix of specialty and mainstream models, Woods’ portfolio emphasizes brush-control and heavy-duty mowing—areas where aftermarket service depth and field-proven ruggedness drive purchase decisions.
-
RhinoAg : Offers flexibility through flex-wing and boom-mounted systems. RhinoAg’s product design orientation makes it a potential scaling candidate through distribution partnerships or targeted OEM integrations.
Recent industry moves underscore the strategic churn: a 2025 production transition saw capacity realigned between manufacturing sites, and a 2026 strategic partnership brought domestic production and brand leverage into sharper focus. These events illustrate two prevailing themes for 2026—continuing consolidation of manufacturing footprints, and the use of brand alliances to accelerate market access.
Operational and product trends shaping 2026 choices
-
Design for serviceability: Gearbox updates with sight glasses and serviceable fill plugs, and deck redesigns that enhance debris management, are reducing downtime and total lifecycle cost—critical to buyers focused on utilization.
-
Aftermarket as a revenue engine: Shorter service turnarounds and improved parts availability elevate aftermarket margins and lock in customer lifetime value. Firms that invest in rapid regrinding, parts logistics, and field diagnostic tools will capture outsized margins.
-
Localized production to manage trade and logistics risk: Strategic partnerships that localize production under respected brands are reshaping sourcing and channel economics—especially in jurisdictions where onshore manufacturing yields procurement or regulatory advantages.
Five strategic recommendations for 2026
-
Prioritize aftermarket and service uplift. Make targeted investments in turnaround time reduction, field diagnostics, and parts logistics to convert operational improvements into recurring revenue.
-
Evaluate partnerships before greenfield expansions. Consider co-manufacturing or licensing arrangements to accelerate product launches with lower capital risk and quicker dealer acceptance.
-
Use product engineering as a competitive moat. Focus R&D on serviceability, modularity, and materials that lower total cost of ownership; these attributes are increasingly decisive in procurement decisions.
-
Stress-test M&A targets against dealer network fit and aftermarket synergies. Real value often resides in network reach and spare-parts coverage rather than in headline product lines alone.
-
Invest in data-driven field support. Deploy telematics and remote diagnostics pilots to reduce mean time to repair and to create data streams that inform next-generation product specs.
Next steps
This briefing outlines the strategic terrain for rotary cutters in 2026—highlighting the macro scale, competitive inflection points, and operational levers most likely to determine winners. For deal teams, product leaders, and channel executives, the full PW Consulting report provides the actionable detail required to convert these insights into investment decisions and commercialization plans. Key proprietary elements—detailed segment economics, dealer-level network maps, and modeled scenario outputs—are intentionally excluded from this summary and are available in the comprehensive study on our website.
Contact PW Consulting’s advisory team to obtain the full Rotary Cutters Market report and a tailored briefing that maps our findings to your organization’s strategic priorities.
For detailed analysis of this topic, please visit the official page: Rotary Cutters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com