

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Stainless Steel Flanges Market to Reach USD 8.42B by 2032 at 5.4% CAGR

Stainless Steel Flanges Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market study on stainless steel flanges provides a forward-looking, decision-oriented briefing designed to equip executives, procurement leaders, and investors for the strategic choices they must make in 2026. This preview highlights the study’s core strategic value, synthesizes the macro trajectory, flags the immediate regulatory and commodity shocks that will shape margins and flows this year, and outlines the tactical playbook our full report delivers. The goal here is to demonstrate analytical depth while reserving the full, granular datasets and segment tables to the source report.
Stainless Steel Flanges Market
Market trajectory and what it means for 2026 planning
The stainless steel flanges market has shown steady expansion through the 2020–2025 period, and our modeling positions 2025 as the analytical base year. The market was approximately USD 5.83 billion in 2025 and is projected to continue expanding through the forecast window. Our scenario suite, calibrated to observable drivers and recent policy shocks, yields a 2026–2032 compound annual growth rate (CAGR) of 5.4%, taking the market from an estimated USD 6.0 billion in 2026 to roughly USD 8.42 billion by 2032.
Stainless Steel Flanges Market
That trajectory matters for 2026 because it is not merely a volume story: growth is occurring against a backdrop of supply-chain repricing, regulatory compliance costs, and trade-policy friction. The consequence is that unit economics and supplier reliability will eclipse simple demand forecasts as the primary determinants of competitive advantage.
Stainless Steel Flanges Market
Immediate dynamics reshaping supplier and buyer strategies
-
Regulatory regime shifts. From January 1, 2026, carbon-border adjustment mechanisms (CBAM) began applying to imported steel products, requiring transparent carbon-footprint reporting and exposing non-compliant imports to penalties. Simultaneously, several major exporting countries implemented tighter export controls and documentary requirements for steel products effective at the start of 2026.
-
Trade protection and market access. Recent antidumping and trade measures affecting stainless steel flanges have changed sourcing calculus in key markets. Buyers that relied on low-cost global sources may confront sudden tariff or compliance costs that erode previously assumed advantages.
-
Raw material price volatility. Nickel — a primary cost driver for many stainless alloys — has shown renewed volatility. Prices recorded in mid‑2026 demonstrate both the magnitude and pace of potential margin impact; our sensitivity models quantify how swings in nickel translate into margin compression across common fabrication and distribution business models.
-
Moderate industry concentration. Market concentration is meaningful but not dominant: the top three competitors account for a significant share of demand but do not create a closed oligopoly. That structure enables strategic consolidation, targeted partnerships, and differentiated product positioning.
How PW Consulting’s analysis turns these dynamics into actionable strategy
Our full report does more than forecast — it operationalizes strategy. Key deliverables include:
- Transparent market-sizing and reproducible methodology (historical 2020–2025 and forecast 2026–2032), plus scenario-based sensitivities tied to commodity and regulatory shocks.
- Supply-chain maps that identify single-source risks, near‑term bottlenecks (processing, testing, certification), and realistic mitigation options by buyer profile.
- Price and margin models that translate nickel and alloy inputs into finished-goods costs under common manufacturing footprints (forging, machining, fabrication), enabling rapid “what-if” assessments for procurement teams.
- Regulatory impact matrix (CBAM, export licensing, antidumping) that ranks market exposure by trade lane and recommends compliance clauses and audit-ready documentation templates.
- Go-to-market and channel playbooks for manufacturers and distributors, covering premiumization, service differentiation, and cost-leadership pathways.
- Investment and M&A screening frameworks — from bolt-on acquisition targets to greenfield processing — prioritized by strategic fit, integration risk, and value-creation horizon.
- Practical contract and sourcing templates (carbon clauses, price‑adjustment triggers, quality and certification SLAs) calibrated to emerging regulatory norms.
Competitive landscape — how incumbents and challengers are positioned
The sector’s participant mix contains a spectrum of business models: premium grade producers, localized fabricators, high-volume manufacturers, and specialized distributors. Below is a concise strategic read on selected firms covered in our competitive analysis:
- Outokumpu Oyj (Helsinki, Finland) — A premium, corrosion-resistant stainless producer with engineering-led product development. Outokumpu’s strengths lie in grade differentiation and servicing industrial end‑users that prioritize lifecycle cost and corrosion performance.
- Texas Flange (Houston, U.S.) — A supply-focused, standards-compliant supplier with strong market access in petrochemical and waterworks markets. Their value proposition centers on code-compliance and fast-turn ANSI/ASME deliveries to U.S. projects.
- Shaw Stainless & Alloy (Marietta, U.S.) — Distributor–fabricator hybrid offering localized custom fabrication and assembly, appealing to pharmaceutical and wastewater clients that need tight tolerances and prompt lead times.
- Longan Flange, Kaysuns, Jiette Pipe, Zhejiang Zhiju (China) — A cluster of manufacturers combining large-diameter capabilities, standards-compliant production, and cost competitiveness for volume projects. Their agility in meeting large DN requirements is a differentiator for infrastructure programmes.
- API International, ASC Engineered Solutions, Kitz Corporation — Suppliers and fabricators focused on machined, forged, or cast solutions meeting industrial standards. They compete on certified quality and engineering services for oil & gas and power generation clients.
Collectively, the top firms show that the market is sufficiently concentrated to reward scale and certification-backed quality, while leaving room for regional specialists and service-oriented players to capture margin-rich niches. Our report’s competitor dashboards include capability matrices, certification ownership, quality-test turnaround times, and a proprietary supplier-risk score — details available in the full dossier.
Risk scenarios you must model in 2026
-
Commodity shock: Rapid nickel appreciation can erode margins on fixed long-term contracts. Our sensitivity analysis models multiple nickel price paths and recommends hedge ratios by business model (distributor vs. manufacturer vs. EPC contractor).
-
Regulatory shock: Enforcement of CBAM-like measures and export license controls increases documentation overhead and can render certain sourcing lanes uneconomic. We provide a compliance-cost ladder and a prioritized mitigation roadmap for 2026.
-
Trade barriers: Antidumping rulings create immediate dislocations in sourcing. Scenario playbooks include rapid qualification of alternative suppliers, short-term inventory strategies, and contract renegotiation language to preserve margins.
Recommended 2026 playbook — prioritized actions
- 0–6 months : Execute supplier carbon audits and insert CBAM-compliance clauses into new purchase orders; introduce price-adjustment triggers tied to nickel indices; build 90–180 day safety stock for critical diameters where lead times are volatile.
- 6–18 months : Shift a portion of strategic volumes to suppliers with certified low-carbon footprints or localized processing; evaluate co‑investment in finishing assets to control certification and lead times.
- 18–36 months : Pursue targeted M&A or JV opportunities to secure capacity in key regions and integrate upstream alloy procurement to capture margin and control carbon-intensity reporting.
What the full PW Consulting report contains (and why it matters)
For executives who must make procurement, caps‑ex, or M&A decisions in 2026, the full study offers the quantitative backbone and operational templates needed to act with speed and conviction. The comprehensive package includes:
- Downloadable time series market-size files and reproducible forecasting models.
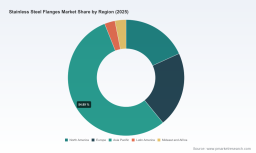
- Segment and regional demand tables (note: these granular tables are intentionally withheld from this preview and are accessible in the full report).
- Supplier scorecards, regulatory-impact checklists, and contract templates for immediate deployment.
- Executive briefings and board-ready slides summarizing scenario conclusions and recommended capital allocation pathways.
Closing — why 2026 is a strategic inflection
2026 is the year in which regulatory transparency (carbon reporting), commodity volatility (notably nickel), and trade policy re‑alignment converge to reshape value capture in the stainless steel flanges market. The macro trajectory — steady growth through 2032 at a mid-single-digit CAGR — masks a highly differentiated competitive landscape where compliance, proximity to demand, and control of alloy costs will determine winners. PW Consulting’s full study provides the granular datasets, supplier analytics, and executable playbooks that senior leaders need to translate that macro outlook into defensible, revenue‑protecting, and margin-enhancing decisions.
To access the complete datasets, granular segmentation and supplier-level analytics referenced here, download the full Stainless Steel Flanges Market report from PW Consulting or contact our advisory team for a tailored briefing and the proprietary models that will support your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Stainless Steel Flanges Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com