

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Carpet tiles market to reach USD 20.53M by 2032 at 6.4% CAGR

Carpet Tiles Market 2026: Strategic Preview for Decision-Makers
As the global built environment navigates economic recalibration, sustainability mandates and evolving specification preferences, carpet tiles have re-emerged as a strategic material choice for owners, designers and manufacturers alike. PW Consulting’s new Carpet Tiles Market study (base year 2025, forecast 2026–2032) synthesizes five years of market movement and a seven-year outlook to give executives the actionable intelligence they need for decisive 2026 planning.
Carpet Tiles Market
Market snapshot — pacing and scale
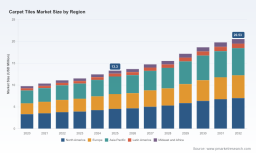
The carpet tiles market has demonstrated steady expansion through the early 2020s, growing from approximately USD 9.8 million in 2020 to USD 13.3 million in 2025. Our forecast, built on demand drivers, cost trajectories and adoption curves, anticipates growth at a compound annual growth rate of roughly 6.4% across 2026–2032, reaching an estimated USD 20.5 million by 2032. Market concentration is meaningful: the three largest players control a majority share (CR3 ~55%), and the top five account for roughly 70% of global value — a structure that shapes competitive dynamics, margin pools and channel negotiation power.
Carpet Tiles Market
Why this matters for 2026 strategic decisions
For corporate leaders planning capital allocation, product roadmaps, or go-to-market moves in 2026, three truths emerge from our analysis:
Carpet Tiles Market
- Sustainability is table stakes, but execution divides winners from laggards. Clients and procurement policies increasingly specify environmental performance as a primary criterion. Companies that translate sustainability commitments into verifiable product attributes, lifecycle transparency and circular service models gain price resilience and specification leadership.
- Modularity and installation economics drive commercial demand. The advantages of modular carpet tiles for flexibility, repairability and phased fit-outs mean that product design and service propositions (replacements, take-back, refurbishment) can become primary differentiators.
- Consolidation and channel control create strategic openings for niche innovators. With a concentrated supplier base, selective M&A and focused partnerships — especially in sustainability-certified, design-forward niches — offer routes to rapid scale or to defensible premium positioning.
From insight to action: where to focus in 2026
- Product strategy — design, materials, and service bundles. Prioritize carpet tile collections that balance design differentiation with modularity and reparability. Invest in validated recycled content and low-emission systems, and design commercial-grade warranty/service bundles that monetize long-term maintenance and refurbishment.
- Supply chain — localization and duty engineering. Reassess sourcing strategies in light of tariff shifts and trade agreements. The CUSMA/USMCA rules of origin create a cost advantage for qualifying North American manufactured tiles intended for intra-regional trade; consider nearshoring or regional platform strategies to secure margin and delivery velocity.
- Pricing and commercial policy. With manufacturers passing through input costs and tariffs selectively, 2026 will be a year where smart price architecture (value-based pricing for sustainability and lifecycle services) beats uniform cost-plus approaches.
- M&A and partnerships. Pursue tuck-ins that add circular capabilities (recycling, take-back), or creative brands with strong design credentials to access new specification channels without undermining incumbent relationships.
- Specification & channel influence. Strengthen relationships with specifiers, national contractors and workplace consultants. A small number of decisions (large commercial projects, hospitality roll-outs) can move volumes disproportionately given the market’s concentration profile.
Competitive landscape — what the leaders are doing (and why it matters)
The competitive map is populated by established global flooring groups and focused specialists. What binds the leaders is a dual emphasis on product breadth and sustainability credibility; distinctions appear in route-to-market, R&D depth, and service-oriented business models.
- Interface, Inc. (Atlanta) continues to position itself at the intersection of design and sustainability. Recent launches underscore a strategy of marrying design narratives with low-carbon credentials — a play that supports premium positioning in commercial interiors and corporate procurement lists. Interface’s long-standing PFAS-free policy and carbon-focused commitments give them specification traction with sustainability-driven buyers.
- Mohawk Industries, Inc. (Dalton) leverages scale and a multi-brand approach to serve diverse channels. Mohawk’s engagement in design showcases signals efforts to drive emotional and tactile differentiation — an effective route to defend commercial projects where aesthetics and occupant experience influence supplier selection.
- Shaw Industries Group (Dalton) deploys product refresh cycles and sustainability messaging to remain competitive. Their portfolio refresh and event-led product launches indicate continued investment in design-led specification activity.
- Milliken & Company (LaGrange) focuses on performance and design-led modular solutions for institutional and commercial segments. Their recent collection launches reflect a strategy of targeted creativity to capture projects where brand-driven selection matters.
- Tarkett, Forbo, and European specialists (e.g., Fletco, BLOQ). These companies increasingly compete on regenerative materials and production transparency. Fletco’s 100% CO2-neutral production and use of regenerated yarns exemplify an industrial model that appeals to project teams targeting ambitious sustainability targets.
- Regional manufacturers and integrated players (e.g., Al Abdullatif). Fully integrated platforms in certain regions combine price control with tailored local go-to-market reach — a powerful combination where specification preferences include local content and rapid delivery.
Recent product activity — from Interface’s design-led launches to Milliken and Shaw’s refreshed lines and Fletco’s regenerated-yarn collections — reveals an industry where innovation is incremental but decisive. Expect successful products to combine tactile appeal, installation efficiencies and verifiable sustainability metrics.
Regulatory and cost tailwinds — practical implications
- Chemical and product regulation: The industry-wide removal of PFAS from U.S. carpet production since 2019 is now a baseline expectation for many specifiers. Suppliers without credible product chemistry transparency risk exclusion from public and corporate bids.
- Tariffs and trade policy: Tariff adjustments on imported hard-surface and decorative products have introduced price inflation in certain channels; some manufacturers implemented price increases in 2025. Product sourcing strategies must therefore be stress-tested against further tariff volatility.
- Trade advantages: Duty rules under CUSMA/USMCA can be a competitive lever for North American manufacturers exporting regionally — a structural edge for those who can certify origin and manage compliance efficiently.
- Energy and production footprint: Claims of CO2-neutral production, as demonstrated by some European manufacturers, are increasingly material in public and large corporate procurement. Investing in verifiable renewable-energy sourcing or procurement partnerships can unlock specification wins and allow premium pricing.
Risk matrix for 2026 decision-makers
- Execution risk: Failure to operationalize sustainability claims (traceability, take-back, recycled content verification) will erode credibility rapidly.
- Channel concentration: Heavy dependence on a small number of commercial specification channels increases exposure to project cyclicality and competitive displacement.
- Commodity & labor cost volatility: Raw material swings and regional labor cost inflation can compress margins unless offset by price discipline or local manufacturing adjustments.
- Regulatory surprises: Unanticipated chemical or trade policy changes could accelerate product reformulation costs or reconfigure supply chains.
What PW Consulting’s Carpet Tiles report delivers (practical, usable outputs)
We designed this study to be directly operational for 2026 planning cycles. Highlights include:
- Market-sizing and forward scenarios (base year 2025; forecast 2026–2032) with sensitivity runs for demand, price and tariff permutations.
- Competitive playbooks that translate public moves (product launches, sustainability claims, showroom strategies) into tactical responses for manufacturers and distributors.
- Supply-chain heatmap and sourcing decision framework that integrates duty engineering, freight/delivery risk and regional labor considerations.
- Sustainability commercialization toolkit: how to validate claims, design circular services, and structure warranty and take-back economics.
- Go-to-market architectures for incumbents and entrants: segmentation of channels by specification influence, procurement behavior and lifecycle expectations (note: detailed subsegment market shares and unit economics are reserved for subscribers).
- Deal and partnership checklist for M&A, joint ventures and licensing arrangements that accelerate capability acquisition while preserving margin discipline.
How to use this research in 90 days
- Week 1–3: Align executive priorities using our scenario outputs — set price guardrails, sustainability targets and channel investment limits.
- Week 4–8: Stress-test your supply chain and sourcing plan against tariff and origin scenarios using our supply-chain heatmap.
- Week 9–12: Deploy the sustainability commercialization toolkit to validate product claims and design an initial take-back pilot for a single product line or market.
Closing perspective
Carpet tiles sit at an intersection of design, operational flexibility and environmental ambition. The coming 12–18 months will reward organizations that convert sustainability commitments into verifiable product systems, that retool supply chains to neutralize tariff and freight exposure, and that lean into modular service economics that project owners now prize. PW Consulting’s Carpet Tiles Market study gives leaders a pragmatic roadmap — from scenario planning to market-winning product and channel plays — to make 2026 a year of strategic clarity rather than tactical reaction.
For companies preparing capital budgets, product roadmaps or acquisition strategies in 2026, the study provides the quantified scenarios and executable tools required to prioritize investment and to defend or expand specification share. For full subsegment detail, supplier-by-supplier share analysis, and the proprietary worksheets that underlie our scenario modelling, please refer to the full PW Consulting report.
For detailed analysis of this topic, please visit the official page: Carpet Tiles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com