

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vitamin Market at USD 129.6B in 2025, set to reach USD 214.7B by 2032 (7.5% CAGR)

Vitamin Market 2026 — Strategic Preview for Enterprise Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise strategic preview of our comprehensive Vitamin Market report (base year 2025). This briefing synthesizes the macro trajectory, competitive dynamics, and near-term regulatory inflections that will shape commercially meaningful choices in 2026. Think of this as the trailer: it demonstrates the depth and decision-focus of the full study while reserving the detailed subsegment tables, proprietary models, and granular regional splits for the full report.
Vitamin Market
Market trajectory at a glance
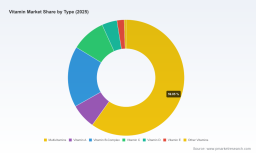
The global vitamin market has moved from roughly USD 94.6 Billion in 2020 to an estimated USD 129.6 Billion in 2025, reflecting sustained demand across both legacy supplement channels and emerging formats. Our forecasting framework projects continued momentum through the 2026–2032 forecast window, with the market expanding at a compound annual growth rate (CAGR) of 7.5%, reaching roughly USD 214.7 Billion by 2032. These top-line dynamics are driven by a blend of structural consumption shifts, premiumization, and regulatory-driven transparency that is reshaping buyer trust.
Vitamin Market
Why this matters for 2026 decisions
- Investment prioritization: The mid-single-digit to high-single-digit CAGR profile supports continued investment in capacity and advantaged ingredients, but it also demands disciplined capital allocation. Companies must prioritize initiatives that protect margin while expanding addressable consumers—R&D into differentiated formulations, routes-to-market that improve margins, and partnerships for certification and athlete endorsements.
- Channel and format strategy: Rapid innovation in formats (e.g., gummies, stabilized liquids, and micro-dosed formats) and the strength of private label at scale require manufacturers and brand owners to define distinct value propositions. Tactical trade-offs—scale via private label versus margin capture through branded innovation—are central to 2026 product roadmaps.
- Supply resilience and ingredient sourcing: Ingredient traceability and supplier qualification now contribute directly to commercial outcomes. The landscape rewards firms that secure diversified supply networks, validated supplier programs, and transparent provenance for clinically positioned ingredients.
- Regulatory and certification risk as opportunity: Increasing regulatory oversight and expanded certification pathways are elevating compliance costs but also creating premiumization levers for certified products. Early movers that integrate certification into product development gain differentiation and shelf-preference.
Report utility — what the full study delivers
Our full Vitamin Market report is engineered for tactical use by strategy, commercial, and M&A teams. Highlights include:
Vitamin Market
- Proprietary demand model covering 2020–2032 with scenario outputs (bull / base / conservative) and sensitivity to price, channel mix, and certification premiums.
- Supply chain and cost-to-serve mapper that identifies bottlenecks, alternative sourcing routes, and potential cost savings across manufacturing, packaging, and logistics.
- Commercial playbook: actionable pricing and launch strategies for premium, mainstream, and value-tier offerings—aligned to distribution partner economics.
- Regulatory and certification tracker that quantifies potential timeline and cost impacts for new compliance requirements and major certification programs.
- Competitive benchmarking and M&A playbook with diligence checklists, synergy levers, and integration risks specific to vitamin manufacturers and ingredient suppliers.
- Go-to-market case studies and retailer scorecards that reflect real-world negotiation levers and assortment strategies across key retail partners.
Note: The full report contains the granular segmentation and proprietary forecasts that underpin the recommendations here; those datasets are intentionally omitted from this preview to preserve the study’s commercial value.
Competitive landscape — who matters and what they signal
The vitamin market exhibits meaningful concentration at the top: the three largest players account for a dominant portion of total revenues (CR3 ~58.5%), and the top five together approach a significantly higher share (CR5 ~72.3%). This degree of concentration creates a bifurcated competitive environment where scale, private-label strength, and brand trust matter simultaneously.
- Pharmavite LLC (Nature Made) — A large branded incumbent with strong retailer partnerships and private-label production capabilities that underscore the importance of both brand equity and manufacturing scale ( https://www.pharmavite.com/).
- RB Manufacturing LLC (Schiff) — A quality-focused producer with established certification programs, demonstrating how quality credentials can be a material commercial differentiator ( https://www.rb.com/).
- Kirkland Signature (Costco Wholesale) — A private-label powerhouse where scale and member trust create margin and volume advantages; their strategy illustrates the competitive pressure on branded players in mass channels ( https://www.costco.com/).
- Haleon / Centrum (ex-GSK) — A global branded leader that signals the continued relevance of broad, science-led multivitamin portfolios in developed markets ( https://www.haleon.com/).
- Pfizer and Bayer AG — Legacy consumer-health players with durable distribution and R&D capabilities; their presence highlights the intersection of pharmaceutical rigor and consumer marketing ( https://www.pfizer.com/, https://www.bayer.com/).
- Nestlé Health Science — A player emphasizing format innovation (e.g., gummy formats) and consumer-centric product design ( https://www.nestlehealthscience.com/).
- Ingredient suppliers and contract manufacturers (e.g., International Vitamin Corporation, Valensa) — These firms are critical to margin, compliance, and speed-to-market; their role in USP/third-party verification programs is increasingly strategic ( https://www.ivcinc.com/, https://valensa.com/).
Strategic takeaway: Leaders combine scale with credible, verifiable quality programs. Mid-market firms can compete by specializing—either through superior formulation and branding, or by offering differentiated manufacturing and certification capabilities to retail partners.
Regulatory and certification inflection points — 2026 and near-term
- Dietary Supplement Listing Act of 2026: The reintroduction of this Act, and the industry associations’ response, signals a material shift toward mandatory product listing and traceability. Expect increased transparency requirements that will elevate record-keeping, product registration timelines, and potential entry costs for small-scale entrants.
- Certification scope expansions: NSF International’s REG 31 designation and its rapid operationalization in 2026 close prior testing gaps and raise the bar for market access claims—particularly for athlete-targeted products. Partnerships like iNADO’s cooperation with NSF demonstrate that certification now intersects directly with sports and performance claims.
- Industry advocacy and adaptation: Trade bodies and major manufacturers are publicly supportive of clearer registries and certification pathways, recognizing that transparency can shrink counterfeit risk and reinforce trusted brands.
Implication: Firms that proactively invest in registration compliance, certification-ready quality systems, and rapid traceability will convert regulatory change from a cost into a competitive moat.
Recommended 90‑day to 18‑month actions for 2026
- 90-day priorities: audit product portfolios for compliance gaps against the emerging listing requirements; map ingredient provenance for all SKUs; and initiate dialogue with primary certification bodies to fast-track certifications that matter to your core channels.
- 6–12 month initiatives: selectively pilot certified SKUs in channels where verification delivers price premium; renegotiate supplier contracts to include traceability clauses; and recalibrate promotional investments to emphasize verified claims.
- 12–18 month moves: evaluate strategic partnerships or M&A targets that provide either ingredient security or certification throughput; deploy a segmented route-to-market playbook that balances private label volume with branded margin capture; and lock in multi-year supply agreements for critical actives.
Risks to monitor and mitigations
- Regulatory timing risk: rapid changes in listing or testing mandates can compress product development timelines. Mitigation: maintain a rolling regulatory impact dashboard and a prioritized SKU remediation queue.
- Margin pressure from private label: continued private-label expansion in big-box and online marketplaces will compress ASPs. Mitigation: invest in premiumization and evidence-backed claims that command higher price points.
- Ingredient concentration and supply shocks: concentrated ingredient sourcing can expose supply chains. Mitigation: pursue supplier diversification and backward-integration options where economically sensible.
Closing — why the full report is strategic value in 2026
Our full Vitamin Market report is designed to be a decision engine for 2026: a combination of proprietary forecasting, competitive diagnostics, and playbooks that convert insight into measurable actions. The market’s projected growth—driven by both scale and segments willing to pay for certified, differentiated products—creates attractive opportunities. At the same time, rising regulatory and certification demands convert product integrity into a strategic asset rather than a compliance cost.
To execute confidently in 2026, leaders need three things simultaneously: (1) a forward-looking demand model, (2) an executable route-to-market and pricing playbook, and (3) a compliance and supplier strategy that protects shelf access. The complete PW Consulting Vitamin Market report provides all three, plus the detailed datasets and scenario matrices that allow you to stress-test strategic choices before you commit capital.
For access to the full dataset, the granular segment breakdowns, company profiles with contact-mapped due diligence checklists, and our interactive scenario model, please consult the full PW Consulting report available via our research portal.
For detailed analysis of this topic, please visit the official page: Vitamin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com