

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Biopesticide Market to Hit USD 15.65B by 2032 at 11.15% CAGR

Biopesticides 2026: Strategic Briefing for Decision-Makers
Executive teaser
The biopesticide sector is no longer a niche sideline of crop protection — it is a rapidly maturing market that will materially reshape portfolio strategies, supply chains and regulatory playbooks in 2026 and beyond. Our PW Consulting market study (base year 2025, forecast to 2032) shows a sustained double‑digit expansion at a compounded annual growth rate of c.11.15%. The global market more than doubles across the forecast window, underscoring both commercial opportunity and the need for disciplined, evidence‑based strategic choices. This briefing highlights why the study is indispensable to boards, business unit leaders and investors preparing for near‑term rollouts, capex calls, alliances and M&A decisions — while reserving the granular segmentation matrices and price curves for the full report to protect the competitive lift that subscribers obtain.
Biopesticide Market
Market trajectory and what it means for 2026 decisions
-
Macro trajectory: From a base of roughly USD 7.5 billion in 2025, the market is projected to exceed USD 15.6 billion by 2032 under the central scenario. That scale shift is driven by regulatory momentum, improved manufacturing economics and accelerating farmer adoption across commercial and specialty crops.
Biopesticide Market -
Strategic inflection: For companies contemplating investment in fermentation capacity, acquisitions of microbial platforms, or global registration campaigns, 2026 is a critical ‘go/no‑go’ window. Early movers who secure registration breadth and scalable supply will lock in advantaged distribution economics as adoptive curves steepen.
Biopesticide Market -
Required discipline: Rapid growth masks heterogeneous unit economics across product types and channels. Winning in 2026 requires integrating regulatory strategy, techno‑economic manufacturing analysis and a go‑to‑market model that aligns product claims with farmer ROI and agronomic advisors’ workflows.
Why this study is a practical decision tool
PW Consulting’s Biopesticide Market study was designed as a working toolkit for commercial leaders and investors. It synthesizes market sizing and a seven‑year forecast with operationally focused deliverables: regulatory pathway maps by target jurisdiction, trial and label acceleration playbooks, COGS and fermentation scale models, channel taxation and margin templates, product launch readiness checklists and a prioritized list of country dossiers for registration. The report couples market analytics with tactical instruments so teams can convert market opportunity into executable project plans within 90–180 days.
Competitive landscape — what incumbents and challengers are doing
The competitive field combines major crop protection groups moving biologicals into core portfolios and specialist biocontrol firms innovating at product and service layers. Market concentration is moderate and growing: the top three firms account for a meaningful share of sales while the top five increase that footprint further, indicating both consolidation pressure and room for disruptive entrants.
-
BASF SE: Leveraging industrial biotechnology capabilities and recent investment in BioHub fermentation capacity, BASF is pursuing scalable supply and an expanded microbial portfolio to serve large‑acre arable segments.
-
Bayer AG: Bayer’s biologicals arm continues to blend acquisition and licensing strategies to accelerate label extension across arable and specialty crops; exclusivity agreements are a core tactic to secure pipeline advantage.
-
Syngenta Group: Positioned to bundle microbial and biochemical solutions with digital agronomy offerings, Syngenta is focusing on integrated soil‑health and pest management platforms.
-
Corteva Agriscience and FMC: Both are integrating AI and high‑throughput screening to shorten discovery cycles and optimize field performance, while selectively partnering with microbial innovators to enhance speed to market.
-
Specialists (Valent BioSciences, Marrone, Koppert, Andermatt, Lallemand, Certis, BioWorks, Novonesis, Nufarm, Bioceres): These firms are doubling down on differentiation — botanical actives, entomopathogenic viruses, beneficial microbes and biologically derived formulations — and winning share in high‑value horticulture, organic and greenhouse channels.
For commercial leaders, the key takeaway is clear: strategic responses must be hybrid. Scale players should invest in flexible fermentation and regulatory capacity; specialists should defend high-margin channels and pursue partnerships that broaden market access without diluting technical IP.
Regulatory and supply dynamics shaping 2026
-
Regulatory acceleration: Early 2026 saw multiple proposed registrations in the US and an uptick in formal guidance from regionally important agencies. Guidance documents and trial standards published by industry bodies are reducing time to acceptance — but evolving data requirements in major markets (notably the EU) will continue to set the pace for dossiers and labeling strategies.
-
Manufacturing & raw‑material implications: Advances in fermentation technology and new BioHub facilities materially reduce unit costs for fungal and bacterial actives, moving several product classes from boutique to industrial scale. That shift favors players who can operationalize quality‑by‑design at scale and secure feedstock reliability.
-
Field adoption governance: Publication of commercial trial and grower assessment guidelines is improving comparability of efficacy data. Buyers and regulators will increasingly demand standardized trial outcomes as part of registration and procurement decisions.
Commercial playbook highlights for 2026
-
Prioritize registration sequencing: Adopt a portfolio approach that balances quick wins in receptive markets with targeted investment to unlock larger markets that require more extensive data. Use staged launches to monetize incremental registrations.
-
De‑risk manufacturing through hybrid strategies: Combine in‑house fermentation for core actives with CMOs for scale peaks. Stress‑test supplier options in 12–18 month simulations under scenarios of raw material volatility and regulatory hold‑ups.
-
Align channel economics to farmer ROI: Design product bundles (biological + biological/chemical rotation plans), trial evidence packages and pay‑for‑performance pilots so advisors and distributors can justify premium pricing to growers.
-
Use alliances to accelerate adoption: Licensing deals and targeted co‑development agreements are now faster routes to scale than greenfield commercialization for many mid‑sized players.
Investment, M&A and partnership implications
Private equity and strategic buyers will find compelling assets across the value chain: microbial discovery platforms with validated modes of action, niche players with strong channel positions in high‑value crops, and fermentation/bioprocessing assets that can be integrated into existing chemical manufacturing footprints. Our report provides valuation comparables, sensitivity analyses and a prioritized M&A wishlist that maps to three strategic archetypes: Capability Buyer (manufacturing/scale), Portfolio Buyer (label breadth) and Channel Buyer (distribution and specialty crops).
Risk matrix — what to watch in 2026
-
Regulatory divergence: Changes in microbial data demands across jurisdictions can materially delay launch timelines and inflate approval costs.
-
Supply bottlenecks: Even with fermentation advancements, capacity allocation and quality control remain critical — failures here can erode trust with growers and distributors.
-
Performance variability: Biologicals are inherently more sensitive to field conditions — robust IPM integration and local trial evidence will be a competitive moat for market leaders.
-
Consolidation pressure: The moderate concentration of the market means smaller players face acquisition pressure or margin compression unless they carve defensible niches.
What the full PW Consulting report delivers (practically)
-
Validated market sizing and a granular forecast model (2026–2032) with scenario toggles for regulatory, adoption and price sensitivity.
-
Regulatory pathway maps and country‑level dossier checklists prioritized by commercial impact.
-
Manufacturing techno‑economic models for fermentation, formulation and packaging across scale points.
-
Commercial trial templates, label claim evidence packages and grower adoption playbooks for rapid field validation.
-
Competitive benchmarking, CRx concentration analysis and executable M&A/partnership frameworks.
-
Investor briefings, board‑ready slide decks and a 90‑day launch action plan tailored to your company archetype.
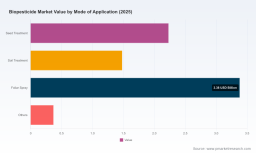
Note: To preserve the strategic value of the analysis, detailed regional and application splits, price curves and sub‑segment financials are intentionally withheld from this summary. Subscribers to the full report receive the complete dataset and editable models.
How PW Consulting recommends you act in 2026
-
Immediate (0–3 months): Run a gap analysis versus the report’s registration and manufacturing templates; secure pilot agreements with 1–2 CMOs; prioritize dossiers for immediate filing.
-
Near term (3–9 months): Launch controlled commercial trials using standardized protocols; finalize at least one strategic licensing or co‑development agreement if you lack discovery breadth.
-
Medium term (9–18 months): Execute scale‑up on fermentation assets or integrate acquired capabilities; lock distribution partnerships in priority geographies; align pricing models to verified farmer ROI.
Closing — why this matters now
Biopesticides are transitioning from experimental adjuncts to core tools in modern crop protection. The combination of regulatory momentum, improved manufacturing economics and clearer field adoption pathways creates a narrow but decisive window for leaders to secure durable advantage. Our full PW Consulting study arms executives with the forensic market evidence, operational playbooks and deal roadmaps required to turn growth into profitable, defensible scale. For teams planning capex, M&A or global launches in 2026, the choice is simple: move with a validated plan or risk being reactive in a market that rewards preparedness.
Access to the full dataset, segmentation matrices and executable templates is available through the PW Consulting report portal for subscribers and select clients.
For detailed analysis of this topic, please visit the official page: Biopesticide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com