

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Healthy Lifestyle
PW Consulting: European bread market valued at $55B in 2025, forecast to reach $65.4B by 2032 on a 2.5% CAGR
By pmarketresearch, 2026-07-13
European Bread Market 2026 Preview: Strategic Imperatives for Producers, Retailers, and Investors
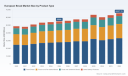
PW Consulting's latest European Bread Market report (base year 2025) delivers a practical, decision-focused roadmap for executives preparing budgets, supply strategies, and M&A activity for 2026 and beyond. The European bread market registered steady recovery through 2020–2025 and stood at approximately USD 55,000 million in 2025. Our modelling projects continued expansion across 2026–2032 at a compound annual growth rate of 2.5%, reaching an estimated USD 65,378 million by 2032. This briefing outlines the strategic value of the report for boardrooms and business units while deliberately reserving detailed segment-level tables and region-specific figures for subscribers to the full report.
European Bread Market
Why this report matters for 2026 decisions
-
Actionable foresight for 2026 planning cycles: The forecast cadence and scenario modelling included in the report align with typical capex and commercial planning timelines, translating macro projections into quarterly, channel‑level implications for 2026 budgeting and 2027–2028 operational plans.
European Bread Market -
Risk-first supply decisions: With raw material volatility intensifying, procurement teams need granular stress tests and hedging playbooks to justify supplier contracts, working capital and storage investments. Our report maps likely P&L sensitivity to commodity moves under multiple scenarios.
European Bread Market -
M&A and partnership prioritisation: The study filters potential targets by strategic fit, integration risk and near-term synergies—equipping corporate development teams with a ranked shortlist and valuation heuristics geared to current market multiples.
-
Regulatory-readiness: New and upcoming rules will reshape packaging, labelling and fortification obligations across key jurisdictions. The report translates regulatory timelines into compliance checklists, cost impact estimates and reformulation roadmaps.
Market trajectory and structural characteristics
After a mid‑cycle dip and subsequent rebound in the early 2020s, the European bread market demonstrated resilience through shifting consumer habits and cost pressures. Our base-year sizing (2025) and point forecasts through 2032 show moderate, steady growth—reflecting a maturing market where volume growth is increasingly supported by product premiumisation, convenience formats and bake-off / frozen channels rather than broad-based expansion in staple volumes.
Concentration metrics indicate a market that is not dominated by a single player: the three‑firm concentration and five‑firm concentration ratios point to a competitive landscape where national and regional champions coexist with pan‑European groups and local independents. This structure creates both acquisition opportunities for scale players and white‑space for nimble specialists focused on niche channels.
Key dynamics shaping 2026 outcomes
-
Commodity volatility: Wheat futures have moved materially—our monitoring layer observed prices around USD 666 per bushel as of May 20, 2026, up more than 20% year‑over‑year. That step‑change in raw material cost feeds directly into short‑term margin erosion for producers and can trigger rapid price‑pass through or demand shifts for lower‑cost formats. The report contains sensitivity tables linking wheat price bands to EBITDA impacts at multiple scale points.
-
Packaging and waste regulation: The EU Packaging and Packaging Waste Regulation (PPWR), in force from August 2026, imposes recyclability, recycled content and waste reduction targets. For bread producers and private‑label manufacturers, this creates immediate design and sourcing requirements for primary and secondary pack formats—impacting both cost and shelf logistics. Our compliance roadmap prioritises packaging interventions with the highest ROI and provides supplier assessment criteria for recycled content sourcing.
-
Labelling and fortification obligations: Existing EU consumer information rules continue to enforce nutrition and allergen transparency for prepacked bread products; alongside this, some national regimes (notably the UK) have phased in mandatory flour fortification measures by late 2026. These developments have product formulation and labelling implications that the report quantifies in terms of reformulation cost, labelling change management and audit readiness.
-
Channel evolution: Retail consolidation, the maturation of online speciality retail and the rapid professionalisation of foodservice bakery offer divergent growth vectors. Our channel scenarios examine trade‑off choices—e.g., margin erosion in mainstream grocery versus unit economics in QSR supply agreements and the capital efficiency of bake‑off models for quick service and in‑store fresh offers.
Competitive landscape: what incumbents and challengers are doing
The competitive field is marked by differentiated strategies: global scale players pursue geographic roll‑outs and integration into QSR supply chains; convenience‑focused specialists expand frozen and par‑baked capacity; national champions defend branded premium positions while independents capture artisan and local freshness premiums. The report contains detailed company profiles and strategic play analyses for major operators, including but not limited to Grupo Bimbo, ARYZTA, Lantmännen Unibake, Barilla, Associated British Foods (Allied Bakeries/AB Mauri), and the European Bakery Group.
-
Grupo Bimbo: Operates a pan‑European model that blends sliced and artisan formats, using acquisitive growth to consolidate shelf space and foodservice contracts. Their European footprint demonstrates how global logistics and procurement can be deployed to defend margin against commodity swings.
-
ARYZTA: A clear example of strategic capacity investment—its announced investment in a bun plant near Lisbon in early 2026 signals a targeted play into QSR and Iberian consolidation. The report includes an analysis of how such investments affect route‑to‑market and service-level economics in high‑volume contract channels.
-
Lantmännen Unibake: Expansion via acquisition into the bake‑off and frozen segments illustrates a hedge against in‑store labour scarcity and a move to scale products that fit retail convenience trends. We examine integration risks and synergies when global groups acquire regional artisan producers.
-
Barilla and Associated British Foods: These groups maintain broad retail portfolios and ingredient supply capabilities; their strategies show the value of vertical integration—both in price stability and in faster product innovation cycles.
-
European Bakery Group and other regional players: Smaller groups retain competitive advantage through local freshness, channel intimacy and tailored SKUs that large players find hard to replicate at margin. Our go‑to‑market playbooks show when to partner, acquire or compete with these specialists.
Strategic implications and recommended actions for 2026
-
Prioritise procurement resilience: Establish multi‑tier sourcing, increase indexed procurement contracts and model working capital impacts under 3–5 commodity scenarios. The report provides procurement templates and KPI dashboards that tie contract terms to margin outcomes.
-
Accelerate packaging redesign with compliance gateways: Treat PPWR readiness as a cross‑functional programme—product development, procurement and packaging engineering must align on materials choices, lead times and supplier qualification. We include a phased implementation schedule that minimises SKU disruption.
-
Reassess channel economics: Use our channel‑specific margin models to reallocate commercial investment—promotions, co‑op funds, and listing spend—to formats with durable margins in 2026 and 2027. The report quantifies break‑even points for bake‑off investments and frozen network roll‑outs.
-
Targeted M&A and partnerships: Seek tuck‑ins that bring capacity in high‑growth convenience segments or that close logistical gaps in key corridors. Our M&A screening matrix ranks targets by strategic fit, scale synergies and integration complexity.
-
Embed compliance and labelling as product differentiators: Turn regulatory changes into consumer‑facing advantages (e.g., transparent fortification messaging, clear allergen communication), rather than merely a cost of compliance. The report offers sample communication frameworks and costed labelling templates.
What’s inside the full PW Consulting report (practical modules)
-
Market sizing and forecast models (2020–2032) with downloadable model files and scenario toggles.
-
Channel and format playbooks—commercial and operational KPIs to run pilots, scale successful formats and shift trade investments.
-
Supply chain stress tests linking wheat price bands, freight and energy to margin scenarios and liquidity needs.
-
Regulatory impact matrix (PPWR, UK fortification, EU labelling) and an implementation checklist with cost ranges and timelines.
-
Competitive heatmaps and company profiles with M&A target screening and value capture cases.
-
Pricing and promotion optimization toolkit together with private‑label benchmarking and recommended tender structures for 2026 supply agreements.
-
Operational annexes—plant capex sizing, labour optimisation templates, and packaging sourcing playbooks (including recycled‑content supplier directory).
Methodology and data transparency
Our base‑year market sizing combines company reported revenues, trade statistics and primary interviews across retailers, manufacturers and distributors. Forecasts are produced using a bottom‑up SKU modelling approach cross‑checked with top‑down macro drivers and validated through scenario analysis. To preserve competitive sensitivity while enabling executive action, we provide the full dataset and replication models to subscribers; the public summary intentionally omits granular segment and regional tabulations to ensure integrity of commercial intelligence.
Next steps
For boards, executive teams and investors preparing 2026 plans, the full PW Consulting European Bread Market report is engineered to convert macro trends into executable initiatives. The public briefing above highlights the principal strategic takeaways—subscribe to access the complete datasets, downloadable forecasting models, and the tactical annexes described. PW Consulting stands ready to support bespoke scenario modelling, carve‑out due diligence or integration planning workshops to accelerate your 2026 decisions.
For detailed analysis of this topic, please visit the official page: European Bread Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Winter Loungewear Market at USD 18.5B in 2025, Set to Rise to USD 28.28B by 2032 on a 6.25% CAGR
By pmarketresearch, 2026-07-13
Winter Loungewear Market: 2026 Strategic Outlook — PW Consulting Winter Loungewear Market Report (Preview)
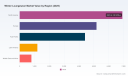
PW Consulting’s Winter Loungewear Market report (base year 2025) delivers a compact, decision-grade preview for executives shaping product, channel and investment strategies in 2026. The market matured from approximately USD 13.9 billion in 2020 to USD 18.5 billion in 2025, and our modeling projects steady expansion at a 6.25% CAGR through the 2026–2032 forecast window, with the market crossing the USD 28 billion mark by 2032. This briefing outlines the report’s strategic value, core industry dynamics, competitor implications and the tangible playbooks we provide — while intentionally withholding the granular split tables and proprietary segment matrices that are available in full on our client portal.
Winter Loungewear Market
Why this report matters for 2026 corporate decision-making
-
Macro clarity underpins tactical choices: The market’s persistent mid-single-digit CAGR signals an environment where disciplined product differentiation, channel optimization and cost control drive share gains more than broad category expansion. Companies that treat growth as run-rate expansion plus selective disruption will outperform peers.
Winter Loungewear Market -
Fragmented supplier landscape: With a low market concentration (our CR3 and CR5 metrics confirm a fragmented field), scale benefits are bounded and nimble, well-capitalized challengers can win by owning consumer experience, supply chain agility and sustainability credentials rather than by pure volume.
Winter Loungewear Market -
Timing matters: 2026 is a pivotal year for converting pandemic-driven loungewear adoption into sustainable margins. The next 12–18 months will define which brands convert trial into loyalty through assortment engineering, premiumization, and hybrid channel plays.
What the PW Consulting report delivers (practical, action-ready content)
-
Proprietary market sizing and forecast model — built on historical 2020–2025 performance, seasonality adjustments and bottom-up SKU and pricing analytics — enabling bespoke scenario runs for management teams and investors.
-
Go-to-market playbooks — channel-specific initiatives and KPI scorecards for e-commerce/DTC, department store partnerships, and specialty retail. Each playbook contains launch calendars, margin impact simulations, and recommended promotional ladders tailored to winter cycles.
-
Product roadmap templates — prioritization frameworks for fabric mixes, thermal performance vs. comfort trade-offs, and layering strategies to align product development with 2026 consumer segments.
-
Supply chain and sourcing playbook — raw material risk heatmaps, cost-to-serve models, and a phased plan for integrating recycled and sustainable polyester blends while protecting gross margin performance.
-
Retailer and channel negotiation toolkit — win-win merchandising frameworks and promotional timing that preserve ASPs and lifetime value while maintaining share in peak winter windows.
-
M&A and partnership scouting lists — thematic targets across adjacent categories (performance-loungewear, premium sleepwear, fabric technology start-ups) and quick-bid valuation ranges to accelerate due diligence.
-
Risk scenarios and contingency playbooks — six downside and upside scenarios (raw material shocks, demand softness, fast-fashion countermoves) with operational triggers and response matrices for 2026 executives.
Key industry dynamics shaping strategy
-
Material science and circularity: Polyester continues to dominate global fiber output and remains central to fleece and synthetic blends used in winter loungewear. At the same time, recycled fleece and sustainable polyester blends are moving from niche to mainstream as brands respond to consumer demand and regulatory pressure. Expect sourcing complexity as firms balance cost, traceability and circularity.
-
Raw material supply landscape: Global cotton supply trends and polyester production dynamics introduce a multi-year cost backdrop that affects margin management, particularly for mid-market players. Hedging strategies and long-term supplier agreements will be differentiators in 2026.
-
Consumer behaviour: Comfort-first design remains foundational, but premiumization (softness, fit, and performance hybridization) and occasion diversification (home, travel, casual out-of-home) are expanding average order values. Loyalty drivers are moving from price to fabric experience and sustainable credentials.
-
Channel evolution: Digital-first and DTC models continue to capture share, but omnichannel integration — especially flexible returns, try-at-home, and localized fulfillment — will be decisive in improving unit economics and conversion rates.
Competitive landscape — what leading players are signaling
-
Hanesbrands Inc.: A scale-focused incumbent, Hanes leverages affordable comfort staples and deep distribution. Their emphasis on everyday warmth and thermal basics makes them resilient in value-conscious segments. Strategic priority: retain penetration in core channels while testing premium fleece innovations.
-
Gap Inc. & Old Navy (including Athleta): Gap’s multi-brand approach spans value through performance. Old Navy’s Bounce Fleece launches and Athleta’s Forever Fleece hybrids show a two-pronged strategy — keep wide-market reach while monetizing performance and lifestyle upgrades. Strategic priority: cross-brand migration and portfolio margin management.
-
SKIMS: Premium, brand-driven moves (including recent holiday and Team USA Winter Olympics capsule launches) emphasize limited-edition, storytelling-led strategies that drive higher ASPs and social buzz. Strategic priority: scale exclusivity without diluting brand cachet.
-
H&M: Fast-fashion play with broad winter loungewear offerings — competitive on price, quick on trend adoption. Strategic priority: speed-to-shelf and cost management through large-scale sourcing.
-
Eberjey and Aritzia: Boutique-to-premium brands focusing on fabric hand-feel and curated fits. These players demonstrate that targeted premiumization can command margin premiums even in a crowded market. Strategic priority: deepen direct consumer relationships and limited distribution partnerships.
-
PVH (Calvin Klein, etc.): Leveraging brand equity to capture premium sleep-loungewear opportunities with strong margin potential. Strategic priority: licensing and selective retail partnerships to broaden reach while protecting brand positioning.
Recent product moves — such as SKIMS’ Team USA Winter Olympics collection (Jan 2026) and Old Navy’s Bounce Fleece launches (Dec 2025) — underscore two concurrent trends: (1) seasonal limited collections that drive urgency and high-margin lift, and (2) continuous core innovation (fleece hybrids, wide-leg joggers) aimed at sustaining repeat purchases. PW Consulting’s report analyzes these initiatives to show how to replicate gains without sacrificing lifetime value.
Strategic implications and recommended plays for 2026
-
Prioritize “fabric-first” SKU rationalization: Shift assortments toward fewer, higher-performing fabric families that deliver clear consumer benefits and simplify inventory turns. Use our SKU decision matrix to identify top 10 SKUs to double down on for winter 2026.
-
Accelerate circular product pilots: Implement a two-step program — lightweight recycled blend integration to test consumer acceptance, followed by scaled take-back programs with key retail partners. This preserves margin while meeting evolving expectations.
-
Optimize channel economics: Implement differentiated pricing and promotional cadence across DTC and wholesale, supported by dynamic fulfillment strategies to protect margins. Use our channel scorecard to reallocate marketing spend toward the highest IRR customer cohorts.
-
Leverage limited-edition drop strategies: Combine seasonal capsule launches with influencer partnerships to drive short-term ASP uplift and long-term brand heat — an approach validated by recent brand activity across premium and mass-market players.
-
Prepare for concentrated M&A and partnerships: Seek targets that provide either proprietary fabric technologies, direct-to-consumer audience access, or sustainable sourcing capability. Our M&A playbook provides valuation heuristics and fast due-diligence checklists.
How to use this report — from boardroom to product floor
-
Executive briefing pack — one-page CFO and CEO decision summaries that translate market moves into P&L and cash-flow implications.
-
Operational toolkits — SKU rationalization templates, promotional calendars, and supplier negotiation scripts ready for immediate deployment.
-
Data access and modeling — clients receive the underlying forecast model (editable) to run bespoke scenarios, plus a dashboard that links market forecasts to SKU and channel-level KPIs.
Final note — what’s intentionally absent here
This release follows the “trailer” principle: it demonstrates the depth and utility of our analysis and the practical levers available to executives, while intentionally omitting the full granular segmentation tables, regional breakdowns, and the proprietary SKU-level matrices that represent the core intelligence deliverable. Those detailed datasets and interactive models are available through our report subscription and client service portal — where buyers can access complete regional, material and distribution channel splits, plus customizable scenario outputs tailored to 2026 planning cycles.
Next steps
-
For immediate strategic use: request the “Executive Brief + Channel Playbooks” package to receive the editable forecast model and retailer negotiation toolkits.
-
For investment teams: commissioning a tailored deep-dive (M&A screening, due diligence data room) accelerates transaction readiness for late-2026 windows.
-
For product and sourcing teams: schedule a two-day workshop with PW Consulting to convert the report’s roadmaps into a timed, KPI-driven implementation plan for the 2026 winter season.
PW Consulting’s Winter Loungewear Market report equips leaders to transform market momentum into durable competitive advantage. For access to the complete report, proprietary segment tables and the interactive forecast model, visit our official report page or contact your PW Consulting engagement lead.
For detailed analysis of this topic, please visit the official page: Winter Loungewear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sleep Apnea Masks Market Set to Expand at an 8.15% CAGR Through 2032
By pmarketresearch, 2026-07-13
Sleep Apnea Masks Market — Strategic Outlook and Decision Framework for 2026
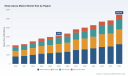
As demand for obstructive sleep apnea therapies grows, the global sleep apnea masks market stands at a pivotal inflection point. Our baseline assessment places total market revenue at roughly USD 3.15 billion in 2025, with a modeled expansion to approximately USD 5.45 billion by 2032, representing a 2026–2032 compound annual growth rate (CAGR) of 8.15%. Those headline numbers mask important structural shifts — convergence of clinical, reimbursement, regulatory and channel dynamics — that will determine winners and losers in 2026 and beyond.
Sleep Apnea Masks Market
Why this report matters to 2026 decision-makers
Executives making capital allocation, product roadmap, commercial partnership, or M&A decisions in 2026 cannot rely on historical playbooks alone. Accelerating product innovation (AI-assisted personalization, minimalist interfaces), changing reimbursement practices, and new entrants expanding distribution channels are altering the basis of competition. Our study synthesizes market sizing and a forward-looking scenario suite with practical modules — regulatory pathways, reimbursement maps, customer segmentation and supplier scorecards — designed to convert insight into executable choices.
Sleep Apnea Masks Market
-
Clarity on market scale and trajectory: our top-line model establishes the macro opportunity and quantifies upside across plausible adoption scenarios through 2032.
Sleep Apnea Masks Market -
Decision-grade drilldowns: we translate epidemiology, device adoption curves and payer mechanics into specific revenue implications for product classes and routes-to-market — without exposing confidential segmented tables in this summary.
-
Actionable playbook: we map 12-month and 36-month actions by company archetype — incumbent OEM, new entrant, component supplier, and distributor — so management teams can prioritize investments and partnerships immediately.
Market architecture and dynamics (executive summary)
The market is concentrated: the top three players account for the majority of revenue and the top five approach near-total concentration, reflecting high switching costs for established channel relationships and value attributed to clinical evidence and device compatibility. Competitive advantage is increasingly derived from ecosystem control — device-to-mask interoperability, software-linked comfort personalization, and broad payer coverage — rather than narrow hardware differentiation alone.
Key structural drivers include:
-
Clinical acceptance and adherence improvements supported by comfort innovations and remote monitoring.
-
Payer rules and replacement cycles that shape unit demand and aftermarket revenue.
-
Regulatory requirements (CPAP masks are regulated as Class II devices requiring 510(k) clearance in the U.S.) that impose time and cost on market entrants but also raise barriers to low-quality imports.
-
Supply-chain dependencies — notably medical-grade silicone for cushions — that influence margin and time-to-market across manufacturers.
Competitive landscape — who to watch and why
The current competitive set blends entrenched global OEMs, specialist mask manufacturers and new disruptors seeking market footholds. Our report provides comparative strategic profiles, OEM playbooks and scenario analyses for each of the leading players. Highlights below summarize strategic implications rather than exhaustive firm-level data.
-
ResMed — With recent regulatory clearances for AI-enabled comfort personalization, ResMed is shifting the value equation from purely mechanical fit to software-assisted adherence improvement. For competitors, this raises the bar on data-enabled features and creates opportunities for partnerships where device ecosystems are open.
-
Fisher & Paykel Healthcare — Known for cushion and headgear innovations, Fisher & Paykel continues to defend premium segments through incremental design and clinician-focused evidence. Their approach underscores the continued importance of clinician buy-in in hospitals and sleep labs.
-
Philips Respironics — With a broad portfolio across full face and nasal interfaces, Philips remains a distribution powerhouse. Their scale amplifies marketing reach and supports competitive pricing strategies.
-
Inogen — A recent entrant with a new CPAP mask line backed by patient-use evidence, Inogen demonstrates how adjacent respiratory players can disrupt incumbents by leveraging existing distribution and brand trust.
-
REMSleep Holdings — A small but strategically important player whose expanded regulatory clearance for nasal pillow systems broadens addressable institutional customers; that clearance signals opportunities for suppliers who can adapt clinical evidence for broader use cases.
-
Other notable participants — Several regional and specialist manufacturers (including legacy DME suppliers and low-cost OEMs) remain competitive on price and niche design innovation, particularly where distribution and reimbursement barriers are lower.
Strategic inference: incumbents must defend ecosystem lock-in (device-to-mask compatibility, software advantages), while challengers can win by focusing on a limited number of high-impact clinical or commercial differentiators and by forming targeted channel partnerships.
Regulatory, reimbursement and supply-side realities
Regulatory and payer mechanics materially influence commercial viability. In the U.S., CPAP masks are regulated as Class II devices and typically require 510(k) clearance to be marketed. Medicare and other payers reimburse masks under specific HCPCS codes and replacement schedules — these coverage and frequency rules continue to shape unit demand and aftermarket sales. On the supply side, reliance on medical-grade silicone for cushions remains a critical input; quality, certification and sourcing resilience can be decisive in product launches and returns to service models.
What the report contains — practical modules for execution
Our full market study is organized to support immediate strategy execution and board-level decision-making. Key modules include:
-
Validated market sizing and forecast model (2020–2032) with scenario toggles for clinical adoption and reimbursement changes.
-
Product and channel profitability matrix to prioritize SKU rationalization and new product investments.
-
Regulatory playbook and time-to-market comparator for U.S., EU and select APAC markets — including a 510(k) checklist and mitigation pathways.
-
Reimbursement and claims analysis mapping codes, replacement timelines, and payer sensitivities relevant to unit economics.
-
Competitive scorecards and M&A landscape with playbook options for bolt-ons, licensing and OEM partnerships.
-
Supply-chain risk assessment focused on cushion materials, contract manufacturing options and inventory resiliency strategies.
-
Customer segmentation and go-to-market blueprints for direct-to-consumer, DME channel, and institutional sales.
-
Investment case templates and valuation sensitivities for private equity and corporate development teams evaluating entry or expansion.
Recommended strategic agenda for 2026
Our synthesis yields a concise set of prioritized moves that market participants should consider implementing in 2026:
-
Prioritize interoperability: secure device-to-mask compatibility or provide clear conversion incentives for clinician networks.
-
Invest selectively in software-enabled comfort features and adherence analytics — not as an add-on, but as a core differentiator tied to reimbursement-friendly clinical outcomes.
-
Strengthen supplier diversification for medical-grade silicone and critical components; consider dual-sourcing and inventory hedges.
-
Map and monetize aftermarket revenue: focus on replacement cycles, consumables and subscription models for mask refresh and hygiene compliance.
-
Leverage regulatory wins: use 510(k) clearances and clinical evidence as commercial levers to unlock institutional channels and payer contracting.
-
For new entrants: pursue focused, evidence-backed product launches with tight channel partnerships rather than broad-market rollouts.
-
For investors: prioritize targets with defensible distribution or proprietary adherence data, and stress-test acquisition models against reimbursement changes.
How PW Consulting’s analysis reduces execution risk
Our methodology integrates primary interviews with clinicians and payers, device-level usage telemetry where available, claims data modeling, and component-level costing. The report’s scenario engine allows leaders to stress-test strategic bets — for example, the commercial impact of a regulatory clearance that expands institutional use or the entry of a low-priced competitor into key channels. The output is not a set of static tables but an executable roadmap and a prioritized action list tailored to company archetypes.
Next steps — where to get the full intelligence
This briefing is a strategic preview: it reveals the market trajectory, competitive inflection points and tactical imperatives while intentionally omitting the granular segment-level tables and downloadable model that underpin the full analysis. For teams preparing 2026 budgets, product roadmaps, or M&A pipelines, the report’s complete datasets and scenario models are an essential complement to internal planning. Visit our report page to access the full study, interactive forecast model and deep-dive annexes — including company scorecards, contract manufacturer maps, and reimbursement worksheets that support rapid decision-making.
In a market defined by clinical nuance, payer complexity and accelerating product innovation, actionable intelligence wins. Our Sleep Apnea Masks Market report is designed to convert insight into impact — helping leaders choose the right investments, partners and product bets for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Sleep Apnea Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Inorganic Feed Mycotoxin Binders Market to Grow at 5.15% CAGR (2026–2032) from USD 920.5M Base (2025) to USD 1,308.2M by 2032 — Asia‑Pacific, Bentonite (USD 514.3M) and Poultry Feed (USD 388.5M) Lead in Fragmented Market (CR3 28.5%)
By pmarketresearch, 2026-07-13
Inorganic Feed Mycotoxins Binders and Modifiers Market: Strategic Imperatives for 2026 — PW Consulting Insight
Executive snapshot
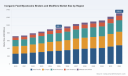
The inorganic feed mycotoxins binders and modifiers market has moved from a niche risk-management tool to a core component of commercial feed strategies. Our PW Consulting benchmark study (base year 2025, historical 2020–2025, forecast period 2026–2032) quantifies this maturation: the global market rose steadily through the early 2020s to reach approximately USD 920.5 Million in 2025 and, under our base-case projections at a compound annual growth rate (CAGR) of 5.15%, is expected to approach USD 1.31 Billion by 2032. These headline figures matter for boardroom decisions in 2026 because they reflect a combination of sustained demand, structural supply factors, and regulatory pressures that will shape capital allocation, product development and route-to-market strategies over the next planning cycle.
Inorganic Feed Mycotoxins Binders And Modifiers Market
Why 2026 is a strategic inflection point
Several converging dynamics elevate 2026 as a decision-making inflection point for feed manufacturers, ingredient suppliers, and investors:
Inorganic Feed Mycotoxins Binders And Modifiers Market
- End-market professionalization. Animal-protein producers are formalizing mycotoxin mitigation into procurement specifications rather than ad hoc risk responses — increasing demand for validated, consistent binder solutions.
- Regulatory tightening and claims scrutiny. Evolving regional frameworks (notably in the EU) already recognize specific inorganic clays for aflatoxin mitigation while imposing efficacy and safety requirements. This raises the bar for product substantiation and places a premium on providers that can demonstrate efficacy without compromising nutrient bioavailability.
- Raw material and supply-chain realities. Inorganic binders are mined minerals (bentonite, montmorillonite, sepiolite, zeolites, etc.); variations in ore quality, processing, and logistics create cost and availability variability — a commercial lever and a source of risk.
- Product differentiation and commercialization maturity. Leading players are moving from generic clay supply to formulated, branded solutions with demonstrable spectrum coverage against polar and non-polar mycotoxins and integrated service propositions (application guidance, dosing protocols, performance monitoring).
What the numbers imply for strategy
Headline market growth at ~5.15% CAGR masks important heterogeneity in demand drivers and supplier economics. From a strategic standpoint, the expansion trajectory signals continued, predictable revenue for suppliers that can solve three problems simultaneously: efficacy across mycotoxin classes, regulatory-compliant claims, and minimal nutrient interaction. For buyers and processors, predictable market growth reduces supply-side volatility risk but increases the need for robust vendor selection criteria.
Inorganic Feed Mycotoxins Binders And Modifiers Market
Competitive landscape — positioning and dynamics
The market exhibits moderate concentration: the top-three suppliers account for a meaningful slice of sales while the top-five extend that reach further. This creates a dual dynamic — established players exert scale advantages in R&D, distribution and regulatory dossiers, yet material indigenous and regional suppliers sustain local competition and innovation. Against this backdrop, a handful of global players set the tone for product claims and channel expansion:
- Amlan International (Oil-Dri Corporation of America) — Strengths lie in proprietary mineral processing and branded binder lines designed for rapid aflatoxin uptake and broader biotoxin coverage. Recent commercial moves (product launches and partnerships in South Asia, and high-visibility showcases at regional feed shows) illustrate an aggressive go-to-market cadence designed to convert technical differentiation into market share gains.
- Kemin Industries — Leverages longstanding feed additive expertise and a portfolio approach combining inorganic adsorbents with complementary chemistries. Kemin’s playbook emphasizes validated performance and integration into feed producer quality systems, which supports premium positioning in risk-averse markets.
- Tolsa — European clay specialist with multi-component formulations that combine bentonite, sepiolite and activated carbons. Tolsa’s strength lies in raw-material mastery and a product development pathway focused on balanced sequestration across toxin profiles.
- Bentoli Inc. — Representative of agile, product-centered suppliers that compete on formulation flexibility and close commercial service to livestock and poultry customers, especially in regional markets where local ore access and quick field support matter.
These players exemplify different routes to commercial success: proprietary processing and branded science, integrated feed-additive portfolios, raw-material specialization with formulation expertise, and regional service-led competition. For strategic buyers, the choice between scale, scope and local intimacy will depend on target geographies, product claims required, and procurement sophistication.
Regulatory and scientific guardrails — what you must prove
Regulatory frameworks are a gating factor for premium positioning. The European example — where certain bentonites are authorised for aflatoxin B1 reduction subject to clear dosing limits and demonstration of safety — illustrates the twin requirements of efficacy and nutrient-safety. Regulatory authorities increasingly require evidence that binders do not impair the bioavailability of key nutrients while delivering measurable mycotoxin reduction. From a strategic perspective, this raises several imperatives:
- Invest in robust, GLP-aligned efficacy and safety studies; third-party validations materially affect acceptance by feed mill customers and integrators.
- Align product labels and claims with jurisdictional norms; overclaiming invites regulatory pushback and commercial rejection.
- Embed nutrient-interaction testing into the product development cycle to avoid costly reformulations after market entry.
Practical content in the PW Consulting report — what decision-makers will find
Our report is designed as an operational playbook for 2026 decisions rather than an academic treatise. Among the deliverables we highlight:
- Top-line market sizing (historic and forecast) and scenario modelling under alternative price-and-supply assumptions, with transparent methodology and sensitivity tables.
- Segment-level demand drivers across product types, applications and regions — with trade-offs and risk matrices. (Note: we intentionally withhold granular proprietary splits in this press preview.)
- Supplier scorecards and capability maps assessing R&D, regulatory dossiers, distribution reach and service models — an actionable shortlist for procurement and M&A screening.
- Commercial due-diligence templates and unit-economics calculators that buyers and private-equity teams can apply to prospective targets.
- Raw-material sourcing playbooks, including mine-to-mill quality controls, logistics optimization and hedging approaches for feed-ingredient buyers.
- Case studies of field trials and application protocols that demonstrate how to convert laboratory efficacy into farm-level performance.
Actionable recommendations for executives in 2026
For leadership teams looking to convert market insight into competitive advantage, our analysis points to a focused set of steps:
- Prioritize regulatory-grade evidence. Allocate budget early in 2026 for GLP studies that simultaneously measure toxin sequestration and nutrient bioavailability.
- Lock in ore quality and logistics. Establish multi-source feedstock contracts and invest in upstream processing controls to stabilise product quality and margin.
- Pursue selective partnerships in high-growth geographies. Local distribution or manufacturing partnerships accelerate market access and lower commercial friction in regions with rising feed safety standards.
- Differentiate through service. Offer dosing calculators, field-monitoring programs, and co-branded farm-level trials to move beyond commodity pricing.
- Use targeted M&A to consolidate mid-tier players and capture regional scale — but only after stress-testing nutrient-interaction and regulatory dossiers.
- Prepare for claim scrutiny. Harmonise marketing claims with regulatory expectations and ensure traceability across the supply chain.
M&A and investor perspective
The sector’s moderate concentration profile creates both buy-and-build and roll-up opportunities. Strategic acquirers can achieve scale benefits in R&D and regulatory costs, while financial sponsors can extract multiple expansion through operational improvement (procurement, formulation standardisation, and route-to-market optimisation). However, premium valuations must be justified by validated pipeline efficacy, stable raw-material access, and defensible customer contracts. Our proprietary valuation frameworks in the report model these contingencies explicitly.
Conclusion — how PW Consulting helps you act in 2026
The inorganic binders and modifiers market is a mature growth market that rewards technical credibility, supply-chain control and regulatory discipline. For companies and investors planning capital and commercial decisions in 2026, the critical question is not whether demand exists, but how to capture it at attractive margins while meeting rising evidence and regulatory standards.
PW Consulting’s full report provides the granular segmentation, supplier scorecards, scenario forecasts and execution roadmaps required to convert the high-level insights in this preview into operational plans. If your 2026 strategy depends on securing product differentiation, market access or M&A confidence in the inorganic mycotoxin binders space, our detailed models and templates are designed to accelerate decision-making and de-risk execution.
For detailed analysis of this topic, please visit the official page: Inorganic Feed Mycotoxins Binders And Modifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luciferase Assay Market Poised to Rise from USD 620.0 Million in 2025 to USD 992.33 Million by 2032 at a 6.95% CAGR
By pmarketresearch, 2026-07-13
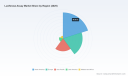
Luciferase Assay Market 2026: Strategic Briefing — Where to Play and How to Win
PW Consulting’s latest Luciferase Assay Market report delivers a pragmatic, decision-grade blueprint for executives preparing strategic moves in 2026. Drawing on a validated historical dataset (2020–2025) and a detailed forecast to 2032, the research synthesizes commercial dynamics, technology inflection points, competitive positioning, and executional playbooks. The market’s macro trajectory — rising from a mid‑2020s base to a near‑billion dollar opportunity by the end of the decade, and expanding at a compound annual growth rate of approximately 6.95% through the forecast horizon — creates actionable windows for suppliers, service providers, and strategic investors. This briefing outlines the report’s strategic value, the high‑level market picture, competitive implications, and the practical tools included for 2026 corporate decision‑making.
Luciferase Assay Market
Why this report matters for 2026 decisions
-
Timing precision: 2026 is a hinge year. The market has moved beyond early‑adopter product cycles and now rewards scale, multiplexing capability, and integration with high‑throughput workflows. Our analysis isolates the operational changes that convert R&D traction into commercial traction within the next 12–24 months.
Luciferase Assay Market -
Risk‑calibrated opportunity assessment: With clear macro growth (CAGR ~6.95%) and measurable concentration among the market leaders (top‑three and top‑five firms representing meaningful shares of market revenue), the landscape favors focused investments in platform differentiation and channel depth rather than scattershot expansion.
Luciferase Assay Market -
Decision frameworks, not just data: The report translates market movement into executable choices — where to deploy R&D spend, when to pursue pricing premium vs. volume play, what partnerships accelerate access to end‑users, and how to structure M&A screening to capture synergistic capability.
Market trajectory — the high‑level picture
Our consolidated dataset shows the luciferase assay market expanding steadily from a base of roughly USD 450 million in 2020 to approximately USD 620 million in 2025, with further acceleration expected through the 2026–2032 forecast period. By 2032 the market is projected to approach a nine‑figure territory nearing USD 1.0 billion. This growth is driven by three structural forces: continued demand from drug discovery and basic research; adoption of higher‑sensitivity luciferase technologies enabling new assay formats; and the scaling of high‑throughput screening operations in biopharma and CROs.
Importantly, market concentration metrics indicate moderate consolidation: the combined share of the three largest vendors and the five largest vendors points to a market where established players retain structural advantages, but where specialist entrants with differentiated assay chemistries or integrated services can capture meaningful niche share. These dynamics shape realistic thresholds for profitable entry and scale.
Strategic implications for corporate leaders in 2026
-
Product strategy — prioritize sensitivity, multiplexing, and workflow integration. Customers increasingly value assays that reduce hands‑on time, enable multiplexed readouts, and integrate with automated liquid handlers and LIMS. Products that demonstrate compatibility with multi‑mode detection and two‑color bioluminescence techniques are positioned to command premium pricing.
-
Commercial model — hybridize sales motions. Purely transactional distribution is being outcompeted by bundled architectures that combine reagent kits, validated protocols, and consumable subscriptions. Firms that layer technical services (assay validation, protocol transfer, automation integration) onto reagent sales report higher retention and margin stability.
-
M&A and partnership focus — target capability gaps rather than scale alone. Bolt‑on acquisitions that add proprietary luciferase variants, substrate chemistries, or software‑enabled analytics accelerate market penetration more effectively than generalist consolidation. Similarly, collaborations with instrument OEMs and contract research organizations expand addressable demand through co‑validated workflows.
-
Geographic and channel entry — be selective. While global demand grows, the most attractive near‑term opportunities favor jurisdictions with dense biopharma clusters and mature translational research ecologies. Channel strategies should optimize for laboratory preference and regulatory nuance rather than broad distribution rollouts.
-
Regulatory posture — standardize RUO clarity and clinical limitations. Luciferase assay kits remain predominantly designated for Research Use Only (RUO) and are not intended as diagnostic or therapeutic devices in clinical settings. Firms must standardize labeling, customer communications, and quality systems to avoid regulatory ambiguity while supporting translational research needs.
Report contents — what you get
Our report was designed as a strategic toolset for executives, commercialization leads, and investors. It synthesizes primary interviews, supplier and buyer surveys, and secondary literature into a compact set of actionable deliverables:
-
Market sizing and validated 2020–2025 history, with robust scenario forecasts through 2032 built from bottom‑up and top‑down reconciliations.
-
Segment playbooks that prioritize addressable segments (by product type, application area, and channel motion) and map the most defensible routes to share gains — presented as go‑to‑market blueprints rather than raw sub‑segment tables.
-
Technology and innovation radar summarizing emergent luciferase chemistries, imaging modalities, and multiplexing strategies — including an assessment of where incremental R&D produces step‑changes vs. incremental improvements.
-
Commercial execution toolkit: pricing elasticity models, distributor vs. direct sales decision frameworks, and templates for subscription/consumable economics with margin sensitivity analysis.
-
Supply chain and operational risk matrix covering reagent sourcing, Cold‑chain implications, and supplier diversification strategies to maintain production continuity and cost control.
-
Vendor scorecards and M&A screening: qualitative assessments of capability, scale, and strategic fit for the sector’s active corporate players (profiles included), and a prioritized list of candidate M&A targets by value creation theme.
-
Case studies and protocol playbooks illustrating successful product launches, academic partnerships, and CRO collaboration models that lifted commercial adoption.
Competitive landscape — what the leader moves tell us
The market is anchored by a handful of well‑resourced firms that combine reagent platforms, catalog breadth, and channel reach with ongoing product innovation. Their competitive actions — from platform upgrades to conference‑led product signals — set technical and commercial reference points for the broader market.
-
Promega Corporation: Continues to drive innovation in small, high‑intensity luciferase systems. Recent demonstrations of red‑shifted luciferase chemistry and paired two‑color analyses (presented at an industry conference in 2026) underscore a roadmap toward multiplexed, high‑sensitivity assays that reduce cross‑talk and increase dynamic range. For challengers, the strategic response is focused R&D on assay orthogonality and sample compatibility.
-
Thermo Fisher Scientific: Leverages global commercial scale and a wide instrument/reagent portfolio to embed luciferase assays in end‑to‑end workflows. Their strength lies in cross‑selling and validated protocols. Competitors should assess partnership or integrator models to access the same customer touchpoints.
-
Revvity Inc. (formerly PerkinElmer): Positions its luciferase offerings for high‑throughput screening in large pharma environments. Their history of automation compatibility signals that assay performance at scale — reproducibility, stability of reagents, and instrument interfacing — is a differentiator.
-
Biotium and Abcam: These players offer value‑focused kits with strong application notes and community adoption. Their agility in reagent development and niche customer engagement is a reminder that targeted innovation plus strong technical support remains a viable commercial model.
-
Merck KGaA (MilliporeSigma): Maintains a broad reagent portfolio that creates stickiness within research labs. Their advantage is breadth and global logistics; newer entrants can compete by offering superior protocol transfer and co‑validation services.
Operational and regulatory caveats
-
RUO designation: Ensure product claims and sales channels align with the RUO classification; stepping toward clinical claims introduces a separate, resource‑intensive regulatory pathway.
-
Quality and reproducibility: As assays move into high‑throughput and translational contexts, buyers are less tolerant of lot‑to‑lot variability. Investment in QC, lot verification, and transparent performance datasheets is non‑negotiable.
-
Intellectual property and freedom‑to‑operate: Differentiated luciferase chemistries and substrate formulations can be protected, but patent landscapes vary by jurisdiction. Licensing risk assessment should be part of any new product launch checklist.
How to use this report in 2026 — recommended playbook
-
For product leaders: Use the technology radar and validation playbooks to prioritize a one‑to‑two year development sprint that targets multiplexing and automation compatibility.
-
For commercial leaders: Implement the pricing and channel sensitivity models to pilot a hybrid sales motion (direct + strategic distribution) in two priority geographies before scaling.
-
For corporate development: Apply the vendor scorecards and M&A screens to shortlist targets that close capability gaps (e.g., unique substrates, imaging IP, or automation‑validated assays) rather than merely adding catalogue breadth.
-
For investors and PE: Leverage the scenario forecasts and concentration metrics to model exit multiples under consolidation and to size bolt‑on investments that accelerate margin improvement through cross‑sell and manufacturing optimization.
Next steps
PW Consulting’s full Luciferase Assay Market report delivers the underlying datasets, the segment playbooks, and the executable templates referenced in this briefing. The document deliberately emphasizes strategic synthesis over raw sub‑segment disclosures to preserve client advisory value while providing the precise tools needed to make high‑confidence go/no‑go decisions in 2026. For access to the full dataset, vendor scorecards, and the downloadable execution templates, please request the comprehensive report from PW Consulting.
For detailed analysis of this topic, please visit the official page: Luciferase Assay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Suppository Base Market to Climb from USD 650 Million in 2025 to USD 945.54 Million by 2032 at a 5.5% CAGR
By pmarketresearch, 2026-07-13
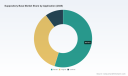
Suppository Base Market — 2026 Strategic Briefing
PW Consulting’s latest Suppository Base Market report is designed as an operationally focused intelligence product for executives making strategic sourcing, R&D, and M&A decisions in 2026. The global market for suppository bases has entered a steady, mid-single-digit growth phase: after expanding from roughly USD 498 million in 2020 to USD 650 million in our 2025 base year, our demand model shows a continuation of that momentum through the 2026–2032 forecast window — translating to a 5.5% compound annual growth rate and a projected market approaching USD 946 million by 2032. This briefing highlights the report’s strategic value, the competitive dynamics shaping supplier choice, and the practical implications for corporate decision-makers. (For full regional, type, and application breakdowns, the complete dataset and downloadable models are hosted with the full report.)
Suppository Base Market
Why this matters for 2026 decision cycles
-
Procurement: Suppository bases remain a specialty excipient category where supplier GMP status, product traceability, and grade consistency materially affect formulation stability and regulatory approvals. With a clear growth trajectory, 2026 is the inflection point for many organizations to move from tactical spot-buying to strategic supplier partnerships and long-term contracts.
Suppository Base Market -
R&D & Formulation Strategy: Choice of base (fatty/oleaginous hard fats, water-soluble PEG blends, or advanced synthetic systems) affects API release, mucosal tolerance, and patient acceptability. The report synthesizes lab-to-commercial transition risks so R&D teams can prioritize platform investments that accelerate time-to-market.
Suppository Base Market -
M&A & Corporate Development: The industry exhibits moderate concentration among established specialty suppliers — our concentration metrics indicate that the top three players account for approximately one-third of market revenue, and the top five approach just over 40% — a profile that favors roll-up plays and targeted vertical integration for mid-sized pharmaceutical and specialty chemical firms.
What the PW Consulting report delivers (practical, transaction‑grade content)
-
Granular market model (2020–2032): revenue history, base-case and alternative scenarios, and sensitivity analysis to raw material shocks and regulatory events — delivered in an editable spreadsheet to support valuation and procurement simulations.
-
Supplier scorecards: quality (GMP/cGMP history), capacity, geographic footprint, and business continuity risk matrices covering primary manufacturers and compounding distributors.
-
Formulation playbook: decision matrix for base selection by therapeutic objective, stability challenges, and patient administration route, including trade-offs between oleaginous hard fats and PEG-based systems.
-
Regulatory & compliance matrix: mapping Ph. Eur., USP, and common national requirements; inspection histories and practical guidance for dossier preparation and excipient change control.
-
Commercial go-to-market templates: sample long-form supply agreements, key performance indicators for CMO partnerships, RFP templates, and pricing frameworks that reflect raw material pass-throughs and quality premiums.
-
M&A diligence kit: target screening criteria, expected multiples range by business model (manufacturer vs. compounding distributor), and an integration checklist focused on quality systems and regulatory harmonization.
Market dynamics and operational risks
Three dynamics are driving near-term commercial decisions: (1) steady demand growth across core therapeutic segments, (2) raw material and sustainability pressures associated with vegetable-sourced hard fats, and (3) regulatory expectations around excipient provenance and GMP compliance. Hard fat bases commonly derive from saturated fatty acids sourced from coconut and palm kernel oils; this creates exposure to agricultural supply cycles, traceability requirements, and ESG scrutiny. Meanwhile, standards bodies list an array of commonly used bases (cocoa-butter substitutes, hydrogenated vegetable oils, PEG mixtures), which means formulation teams must balance clinical performance with supply security.
Regulatory alignment is non-negotiable. Some leading hard-fat manufacturers operate under EU GMP and maintain histories of US FDA cGMP inspections, and many bases are referenced in pharmacopeial compendia. For manufacturers and branded generics alike, the ability to demonstrate pharmacopeial compliance and documented supply chains will determine market access in the next regulatory sweep.
Competitive landscape — who matters and why
Our competitive analysis focuses on specialty excipient manufacturers and distribution/compounding players who control formulation access to hospital and pharmacy channels. Key firms profiled in the report include:
-
IOI Oleo GmbH (Hamburg, Germany) — A global name in hard‑fat (WITEPSOL®) bases with multiple registered grades and GMP-certified production. Their strength is in scale, regulatory pedigree, and a long track record supplying rectal and vaginal bases optimized for industrial manufacturing. Recent catalogue updates underscore continued investment in grade development and technical support for formulators.
-
Medisca (Montreal, Canada) — A major supplier to compounding pharmacies with a broad portfolio that includes vegetable‑based and PEG systems. Their commercial model is distribution-led, emphasizing availability to compounding networks; their recent promotion of natural base grades signals a push to capture pharmacist and outpatient demand.
-
PCCA (Houston, Texas, USA) — Positioned around proprietary bases for compounding and practitioner networks, PCCA combines product breadth with service support aimed at customized preparations. Their proposition targets the clinical compounding space where rapid formulation support is valued.
-
SpecializedRx (USA) — Focused on compounding markets with a portfolio that includes established hard fats and blended bases; their niche is rapid supply to independent pharmacies and small hospital systems.
-
Gattefossé (France) — Adds formulation science to the supply equation, offering hard fat bases tailored for controlled dispersion, stability, and mucosal tolerance — appealing to pharma customers seeking technical co-development.
-
Croda Pharma (UK) — A broader excipient house whose capabilities in excipient innovation and regulatory support make them an attractive partner for branded product teams seeking differentiated functional excipients.
Recent vendor moves — for example IOI’s WITEPSOL® brochure refresh and Medisca’s active promotion of natural and Witepsol‑equivalent grades — indicate two concurrent strategies in the market: (1) incumbent manufacturers focusing on technical differentiation and regulatory validation, and (2) distributors/compounding suppliers emphasizing availability and service to downstream pharmacy networks.
Strategic implications and recommended actions for 2026
-
Embed excipient strategy into product development roadmaps. Formulation strategy should be a board-level input: early decisions on base families materially affect stability, packaging, and expiration dating. Run design-of-experiments (DOE) to de-risk transitions between base types before committing to commercial batches.
-
Diversify upstream exposure where material. For manufacturers reliant on vegetable‑derived fats, implement a multi-supplier policy and consider contracted volumes or hedging to mitigate agricultural volatility. Include sustainability and traceability clauses in supplier contracts to anticipate procurement disruptions driven by ESG scrutiny.
-
Prioritize GMP and pharmacopeial alignment in supplier selection. Regulatory inspections and pharmacopeial references remain decisive in hospital and export markets. Select suppliers with transparent inspection histories and documented change-control procedures.
-
Leverage compounding channels tactically. If market entry speed is a priority, partnering with compounding-focused distributors and networks can accelerate access to B2B and outpatient demand while a longer-term manufacturing strategy is developed.
-
Evaluate M&A to achieve scale or technical capability. Given the market’s moderate concentration, acquisitive moves can secure capacity, broaden grade portfolios, or add formulation expertise — especially compelling for players seeking integrated supply chains or enhanced technical services.
PW Consulting’s unique analytical edge
Our report combines market-sizing rigor with transactional insights: the model is backed by bottom-up production and consumption estimates, validated against manufacturer disclosures and compounding distribution activity. The supplier scorecards and risk matrices are built from primary interviews, inspection histories, and product disclosures, while the commercial toolset provides immediate operational utility for procurement, quality, and corporate development teams.
We intentionally limit the level of segmentation detail in this public briefing to preserve the “trailer” effect: the full report contains the regional, type, and application splits (historical and forecast), price curves by base grade, and scenario-run workbooks that clients use directly in board-level decision-making and deal diligence.
Next steps — how to use this intelligence in 2026
-
Download the full dataset and editable models to run your own scenarios on procurement contracts and acquisition targets.
-
Use our supplier scorecards in RFP shortlists and pre-acquisition due diligence to quantify regulatory and supply continuity risk.
-
Engage our consulting team for accelerated diligence or to co-develop formulation testing plans aligned to your product pipeline milestones.
PW Consulting’s Suppository Base Market report is built for the practical needs of 2026 planners: it converts a complex, technically-driven supply market into action-oriented strategy, procurement playbooks, and transaction-ready diligence. Access to the full report and underlying models is available via our client portal — contact your PW representative to obtain the full dataset, supplier annexes, and the editable forecast workbook.
For detailed analysis of this topic, please visit the official page: Suppository Base Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Booming Home Pet Deworming Market — Poised to Reach USD 4,976 Million by 2032 with a 6.75% CAGR
By pmarketresearch, 2026-07-13
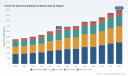
Home Pet Deworming Medicine Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting presents a forward-looking industry briefing drawn from our forthcoming Home Pet Deworming Medicine Market report (base year 2025, historical series 2020–2025, forecast 2026–2032). This briefing distills the macro trajectory, competitive posture, supply‑chain and regulatory inflection points, and the precise decision tools executives will need to convert market momentum into profitable action in 2026. The full report contains the proprietary segmentation tables, granular scenario outputs and go‑to‑market playbooks that are intentionally withheld here to preserve client value and to drive direct access to the source analysis.
Home Pet Deworming Medicine Market
Macro trajectory: robust, predictable growth
The home pet deworming medicine market has moved from a clear recovery phase into sustained expansion. Our historical analysis shows the market rising from USD 2,272.32 Million in 2020 to USD 3,150.0 Million in 2025. Under the baseline case in our forecast (2026–2032), the market continues to expand at a compound annual growth rate of 6.75%, with the market expected to surpass USD 4,975.99 Million by 2032. This profile — steady mid‑single‑digit CAGR coupled with resilient demand drivers — creates a planning horizon well suited to both near‑term tactical moves and multi‑year strategic investments.
Home Pet Deworming Medicine Market
Why 2026 is a pivotal year for corporate strategy
- Acceleration of consumer self‑care behaviors: Pet owners continue to favor at‑home remedies, boosting demand for OTC and veterinarian‑recommended over‑the‑counter formats. Companies that make 2026 the year of channel and packaging innovation can capture disproportionate share.
- Regulatory and generic pressure: The recent regulatory approvals expanding generic fenbendazole options change competitive dynamics. Firms must reassess price elasticity and lifecycle management for branded assets.
- Supply‑chain concentration risks: API production concentrations (notably in Asia Pacific) create both cost advantages and vulnerability to supply disruption — a critical factor for sourcing strategies and inventory policy.
- Portfolio rationalization opportunity: The market concentration metrics (CR3 ≈ 48.2% and CR5 ≈ 62.4%) indicate a moderately consolidated market where mid‑tier players can win by focusing on segmentation, convenience formats and channel specialization.
Actionable implications for 2026 corporate plans
Leaders who treat 2026 as the year to operationalize strategic options will benefit. Our report equips companies with applied tools; below are the high‑impact initiatives we recommend evaluating this year:
Home Pet Deworming Medicine Market
- Differentiated format plays: Invest selectively in chewables, spot‑on delivery innovations, or palatable suspensions based on channel economics and margin profiles. Prioritize formats that enable premium pricing through convenience and compliance features.
- Channel orchestration: Rebalance downstream investments across veterinary channels, retail chains and e‑commerce. Implement SKU rationalization and targeted promotions to improve inventory turns without sacrificing share in core outlets.
- Generic defense and lifecycle tactics: Launch defendable label extensions, collateralized clinical messaging, and bundled offerings to blunt margin erosion where generics are emerging.
- Supply resilience and vertical levers: Secure multi‑source API contracts, qualify alternate manufacturing sites, and model inventory buffers using the stress‑test scenarios in our annex to reduce stockout risk.
- M&A and partnership scouting: Use our screened target list and valuation templates to accelerate tuck‑ins that add channel capabilities, formulation expertise, or regulatory dossiers.
Competitive landscape — reading the field in 2026
The market’s mid‑consolidation state favors leaders that combine scale with innovation. Below are strategic profiles and implications for each core competitor we analyze in depth in the report.
- Zoetis (Parsippany, NJ, USA) — Strengths: well‑recognized companion animal portfolio and established liquid dewormer offerings. Strategic implication: defend prescription‑based channels, accelerate pet‑owner education programs to sustain premium positioning.
- Merck Animal Health (Rahway, NJ, USA) — Strengths: broad‑spectrum fenbendazole‑based products and strong vet relations. Strategic implication: leverage clinical credibility to offset generic entries and explore bundling dewormers with parasite prevention regimens.
- Elanco Animal Health (Greenfield, IN, USA) — Strengths: multi‑parasite chewable tablets and recent emergency authorizations in adjacent parasiticide categories. Strategic implication: exploit regulatory agility to fast‑track label extensions and capture episodic demand; consider rapid rollouts of novel dosing formats.
- Virbac (Fort Worth, TX, USA) — Strengths: flavored chewables and differentiated formulation expertise. Strategic implication: double down on palatability and compliance messaging to win owners prioritizing ease of administration.
- PetIQ (Eagle, ID, USA) — Strengths: OTC reach and value positioning in mass channels. Strategic implication: optimize private‑label economics and loyalty programs to sustain volume amid price competition.
- Boehringer Ingelheim (Ingelheim, Germany) — Strengths: global R&D and companion animal heritage. Strategic implication: focus on innovation pipelines that create distance from low‑cost generics through clinical differentiation.
- Ceva Santé Animale (Libourne, France) — Strengths: targeted parasiticide portfolio and regional strengths. Strategic implication: pursue selective partnerships to expand distribution in underpenetrated channels.
- Dechra Pharmaceuticals (Northwich, UK) — Strengths: niche veterinary formulations. Strategic implication: target premium veterinarian channels with specialized dosing formats and compliance tools.
- Central Garden & Pet / Farnam (Walnut Creek, CA, USA) — Strengths: consumer brand equity for home use formulations. Strategic implication: invest in retail merchandising and digital guidance to reduce misuse and increase repeat purchase.
- Durvet (Blue Springs, MO, USA) — Strengths: distribution breadth for affordable products. Strategic implication: collaborate on co‑branded value packs and geographic expansion in cost‑sensitive markets.
These competitor summaries are complemented in the full report by matrixed capability assessments (R&D, manufacturing scale, channel strength, pricing resilience) and scenario‑based market share trajectories that reveal plausible winners and losers under fast/slow generic adoption.
Regulatory and supply dynamics that will determine winners
- Generic entries and labeling compliance: The January 2026 FDA approval of the first generic fenbendazole oral suspension (Defendazole by Norbrook) for livestock underscores a shifting regulatory landscape. While the approval currently targets cattle and goats, it accelerates the development pathway for generics and heightens downward pricing pressure across fenbendazole‑containing portfolios. Additionally, over‑the‑counter pet dewormers such as pyrantel pamoate and praziquantel remain subject to strict labeling requirements; compliance will be a differentiator in retailer and veterinary procurement decisions.
- API geography and cost levers: Fenbendazole API production is concentrated in Asia Pacific (notably India and China). This concentration supports cost efficiency for manufacturers that secure long‑term contracts, but it also raises exposure to geopolitical and trade policy shifts. We provide a procurement decision tree in the report to quantify this tradeoff.
- Ad hoc emergency authorizations: The November 2025 emergency use authorization for a related parasiticide highlights how episodic regulatory decisions can create short‑term demand spikes. Companies with flexible manufacturing and rapid distribution pathways can monetize these windows.
What the PW Consulting report contains (practical, executable deliverables)
Our full market study is intentionally operational. Key deliverables include:
- Top‑line and bottom‑line forecasts (2020–2032) with Monte Carlo sensitivity bands for pricing, adoption and generic entry scenarios.
- Segmentation models by format, channel and animal cohort with interactive pivot tables (note: detailed segment tables and regional/application breakdowns are available only in the paid report).
- Competitive scorecards and 24‑month tactical playbooks for new product launches, value‑pack rollouts and private‑label strategies.
- Supply‑chain risk simulations, API sourcing roadmaps and recommended inventory buffers calibrated to service‑level targets.
- M&A screening list with valuation templates, synergies estimates and integration checklists for bolt‑on and platform acquisitions.
- Pricing elasticity studies and promotion optimization models designed for retail and veterinary channels.
How leading teams use this intelligence in 90–180 day sprints
- Commercial leaders: Use the SKU rationalization and pricing modules to lift gross margin ahead of anticipated generic pressure.
- R&D and product managers: Prioritize formulations that improve compliance and reduce dosing errors; pilot at scale using our launch playbook.
- Supply chain and procurement: Execute the API dual‑sourcing play and test contract durations that balance price and continuity risk.
- M&A teams: Shortlist targets using our acquisition filter; run the included integration stress tests before bid submission.
Next steps — where to go for the detailed intelligence
This briefing is designed to accelerate decision‑making in 2026 by highlighting the levers that matter most. For corporate teams preparing capital allocations, product roadmaps, or M&A strategies, the full PW Consulting Home Pet Deworming Medicine Market report provides the confidential segment tables, vendor scorecards and financial models required to finalize plans with confidence. Access to the complete dataset and executable templates is available via PW Consulting's report portal.
To discuss customized briefings, scenario runs tailored to your portfolio, or to obtain the full report and its proprietary appendices, contact PW Consulting’s animal health practice. Our analysts are ready to run bespoke variants of the model to reflect your price points, channel mixes and product pipeline.
For detailed analysis of this topic, please visit the official page: Home Pet Deworming Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Jewelry Beads Market Set to Grow at 5.5% CAGR Through 2032, New Report Reveals
By pmarketresearch, 2026-07-13
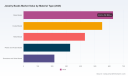
PW Consulting: Strategic Outlook — Jewelry Beads Market Report (Base Year 2025) — A 2026 Decision-Maker’s Playbook
PW Consulting today releases its authoritative market intelligence brief for the global Jewelry Beads Market, built on a five-year historical foundation (2020–2025) and forward-looking forecasts through 2032. The study sizes the market at USD 2,150 million in 2025 and models growth to approximately USD 3,128 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.5% over the 2026–2032 forecast window. Designed specifically to inform near-term corporate strategy, sourcing decisions, and commercial execution in 2026, the report blends rigorous data analysis with practical, operational playbooks for manufacturers, distributors, brands and investors.
Jewelry Beads Market
Why this report matters for 2026
-
Actionable intelligence for immediate allocation decisions: the report translates market-scale and trend signals into prioritised tactical moves for the coming 12–18 months.
Jewelry Beads Market -
Risk-informed sourcing and manufacturing guidance: detailed supply‑chain mappings and scenario plans that allow procurement teams to stress-test sourcing alternatives against tariff and energy volatility.
Jewelry Beads Market -
Revenue and margin playbooks: go-to-market templates for premium and value-tier strategies, channel mix optimization, and SKU rationalisation to protect margins as cost pressures shift.
-
M&A and partnership roadmaps: an investment lens highlighting where consolidation, vertical integration, or strategic alliances can accelerate scale or margin capture.
Market context and near-term dynamics
The Jewelry Beads Market navigated uneven performance in the early 2020s, with pandemic-era disruption, subsequent normalization, and commodity-driven cost shocks. After a period of contraction observed in 2023, the market rebounded through 2024 into 2025, culminating in the USD 2,150 million base year. Our models forecast steady expansion to just over USD 3.1 billion by 2032 under a central-case CAGR of 5.5% — a growth trajectory driven by a combination of personalized-fashion demand, expanding DIY and craft communities, premiumization in discretionary spend, and rising digital commerce penetration.
However, the outlook is not uniform across the value chain. Key structural forces to watch in 2026 include: input-cost pressure from energy and raw-material markets (notably for glass and crystal production), evolving regulatory constraints on hazardous substances in jewelry components, and shifting geopolitical trade policies that affect cross-border sourcing and landed costs. These dynamics create concentrated tactical risks — and opportunities — for firms that move early on supply diversification, cost-to-serve optimisation and product differentiation.
Competitive landscape — fragmented but strategically active
The industry remains low-to-moderately concentrated, with leading firms accounting for a limited share of the global market. This fragmentation sustains healthy competition and niche specialization. From precision crystal producers and legacy Czech glass manufacturers to large-scale wholesale platforms and regional distributors, competitive advantage today is built on one or more of the following: brand premiumisation, product precision and quality control, scale in distribution, specialist design and color trend capability, and digital channel mastery.
-
Established manufacturers with deep technical know-how — such as precision-cut crystal suppliers and traditional European glass bead makers — retain leadership in premium and craft-centric segments, leveraging centuries‑old manufacturing techniques combined with contemporary design trend pipelines.
-
Large wholesale platforms and diversified suppliers from Asia provide scale, breadth of assortments, and rapid replenishment capabilities that serve mass-market and fast-fashion channels.
-
US- and Europe-based distributors and specialist retailers combine curated assortments with educational content and community engagement, supporting the growth of the DIY consumer base and higher-frequency repeat purchases.
Notable market participants profiled in the report include leading manufacturers, premium crystal brands, major wholesale platforms and specialised distributors. Our company dossiers evaluate product portfolios, channel strategies, manufacturing footprints, regulatory compliance readiness and strategic intent — enabling readers to benchmark partners and rivals on criteria that matter for 2026 execution.
Regulatory and supply-side noise to factor into 2026 plans
-
Regulatory compliance remains a table-stakes issue: jurisdictions continue to enforce strict limits on lead, cadmium and other regulated substances in jewelry components, with active standards in major markets. Buyers and manufacturers must accelerate testing, certification and traceability to avoid market access disruptions.
-
Trade policy and tariffs: tariffs on certain glass bead imports and the possibility of tariff actions on gemstone and component imports increase landed-cost risk. Procurement teams should model tariff scenarios and evaluate near-shore alternatives.
-
Energy and input-cost inflation: energy price increases in key production centers have materially affected glass-bead manufacturing economics. Our cost models and scenario analyses help quantify the pass-through potential and identify levers for mitigation.
2026 Playbook — concrete steps recommended by PW Consulting
For executives preparing budgets and strategic initiatives for 2026, the report distills our analysis into a prioritised, time-bound playbook:
-
Sourcing diversification: implement a two-track sourcing strategy — secure low-cost scale supply while qualifying regional or near-shore partners for critical SKUs to reduce tariff and transport risk.
-
Selective premiumisation: launch capsule collections with premium crystal and precision-cut glass to capture margin expansion; use limited-edition runs and color-trend tie-ins to drive urgency and higher ASPs.
-
Channel rebalancing: accelerate direct-to-consumer digital experiences and subscription/kit offerings to increase lifetime value and reduce dependence on wholesale churn.
-
Regulatory-first product governance: institute mandatory materials testing, vendor attestations and SKU-level compliance flags to protect market access in regulated regions.
-
Operational resilience: hedge energy exposure where possible, pursue manufacturing efficiency projects, and adopt inventory segmentation to align service levels to SKU economics.
-
M&A and partnerships: target bolt-on acquisitions that fill capability gaps (e.g., precision finishing, proprietary crystal formulations, or design studios) and co-invest in shared warehousing for regional speed-to-market.
What’s inside the PW Consulting report (practical deliverables)
The report balances high-level strategic guidance with tangible, implementable assets designed for 2026 action:
-
Executive synthesis and investment thesis for 2026–2028
-
Historical market sizing (2020–2025) and forward projections (2026–2032) with sensitivity scenarios
-
Demand-driver analysis: consumer cohorts, channel economics, and product archetypes
-
Supply-chain maps and supplier scorecards (quality, lead time, regulatory posture and ESG metrics)
-
Regulatory and tariff appendix summarising active standards and duty exposures relevant to sourcing decisions
-
Practical toolkits: cost-to-serve models, SKU rationalisation templates, supplier negotiation playbooks, and a go-to-market launch checklist
-
Company profiles and competitive benchmarking across manufacturing, wholesale, and retail segments
Recent industry movements and signals to monitor in 2026
Market actors continue to use trade shows, trend leadership and product introductions as commercial catalysts. Recent activity includes trade show participation across major industry events and early releases of seasonal color trends by leading bead manufacturers — tangible signals that design-led differentiation and community engagement remain powerful growth levers. At the same time, documented increases in energy costs for glass production and continuing regulatory scrutiny reinforce the need for material traceability and cost contingency planning.
How to use this report
Procurement directors, product heads, private equity investors and board members should use this report as both a risk map and a testable operations-and-commercial playbook. It is particularly useful for companies that need to: (1) rebuild supplier scorecards after a period of supply constraint, (2) reprice assortments to protect margins, (3) identify acquisition targets that bring manufacturing differentiation, or (4) accelerate direct-to-consumer propositions tied to design and color trends.
PW Consulting’s Jewelry Beads Market Report is intentionally constructed as a “teaser + toolkit” — it demonstrates the depth of our market modelling and strategic prescriptions while reserving full segment-level allocations, granular regional breakdowns and company revenue shares for the complete report package. This approach ensures decision-makers have a concise strategic summary now, with the option to access the detailed datasets, interactive dashboards and supplier scorecards required for immediate implementation.
To access the full report, the interactive data dashboards, or to commission a custom 90‑day implementation engagement aligned to your specific supply, product, or channel needs, visit PW Consulting’s research portal or contact our Jewelry & Accessories practice lead for a briefing.
For detailed analysis of this topic, please visit the official page: Jewelry Beads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Diabetes Telemedicine Technology Market Set to Expand at a 13.5% CAGR During 2026–2032 Forecast
By pmarketresearch, 2026-07-13
Diabetes Telemedicine Technology Market: A 2026 Strategic Preview — PW Consulting
Executive summary
As healthcare systems recalibrate for post-pandemic digital care, diabetes telemedicine technology is transitioning from niche telemonitoring to an embedded element of chronic care delivery. PW Consulting’s latest market assessment finds the global Diabetes Telemedicine Technology market reached USD 5,650 Million in 2025 and is on a steep growth trajectory: our forecast projects the market to expand at a compound annual growth rate (CAGR) of 13.5% over the 2026–2032 period. By 2026 the market is expected to surpass USD 6.8 billion, with the longer-term projection pointing to material scale and new commercial structures by 2032.
Diabetes Telemedicine Technology Market
Why this matters to enterprises in 2026
-
Strategic timing: With reimbursement rules and remote monitoring codes being refreshed across major markets, 2026 is a window for vendors, payers, and provider systems to lock in commercial models and pilot scalable care pathways.
Diabetes Telemedicine Technology Market -
Competition and concentration: The market exhibits measurable concentration among leading platform and device players — a three‑firm concentration ratio that signals established incumbents but leaves room for differentiated entrants with specialized clinical propositions.
Diabetes Telemedicine Technology Market -
Economics of scale: Rapid adoption of continuous glucose monitoring (CGM), connected insulin delivery, and remote monitoring platforms is driving unit-cost reductions and opening new value-based contracting opportunities for enterprises ready to operationalize outcomes‑linked models.
Market dynamics shaping near-term decisions
Three macro drivers will shape executive choices in 2026: (1) regulatory and reimbursement shifts that materially change the revenue calculus for RPM and telehealth services; (2) product and interoperability advances among device and platform vendors that lower integration friction; and (3) provider adoption patterns that move from episodic tele-visits to integrated chronic care pathways.
-
Regulatory and reimbursement: Recent U.S. policy actions extend telehealth flexibilities and introduce new remote patient monitoring (RPM) codes that better reflect shorter monitoring intervals and management time. Together with modest increases in physician fee schedules, these changes alter reimbursement unit economics for diabetes telemedicine services through at least 2027 and create a near-term runway for scaled pilot programs.
-
Product innovation: Vendors are expanding beyond glucose telemetry into multi‑sensor approaches for complications prevention, and regulatory clearances have enabled tighter integration between CGMs and automated insulin delivery systems — enabling higher‑value closed‑loop care that can be delivered remotely.
-
Care model evolution: Payers and provider networks are increasingly embracing asynchronous and continuous care models (e.g., expanded on‑demand prevention programs), which favor platform solutions that support team‑based monitoring, coaching, and outcome tracking.
What successful players will prioritize in 2026
-
Clinical outcomes-first product design: Prioritize proof points for glycemic outcomes, hypoglycemia reduction and reduced complications as primary commercial value levers, not just device adoption metrics.
-
Interoperability and data-ops: Invest in EHR integrations, device-agnostic ingestion layers, and analytics pipelines that reduce clinician overhead and deliver actionable alerts rather than raw streams of telemetry.
-
Reimbursement and contracting playbooks: Build commercial templates that translate RPM codes and telehealth flexibilities into bundled services, demonstrating ROI at the cohort level. Prepare for shorter monitoring intervals embedded in next‑generation codes.
-
Distribution and hybrid channels: Combine direct-to-patient digital engagement with provider-led chronic care programs and value-based contracts with payers to diversify revenue and mitigate concentration risk.
-
Safety and regulatory readiness: Maintain proactive regulatory strategies for device integrations and automated delivery approvals to accelerate time-to-market for closed-loop solutions.
Competitive landscape — who’s shaping the field
The competitive map comprises established device OEMs, digital-first care platforms, and specialist RPM providers. Notable companies profiled in our analysis include platform-oriented vendors that integrate multi‑device data and care workflows, traditional medical device leaders extending telehealth capabilities, and focused innovators addressing complications prevention and reversal models.
-
Platform integrators: Companies that aggregate device telemetry, provide remote patient monitoring (RPM) workflows, and integrate with clinical systems form the backbone of scalable telemedicine delivery. These vendors typically emphasize device compatibility, care team dashboards, and analytics for population management.
-
Device leaders: Established CGM and insulin delivery manufacturers are increasingly shipping software features for data sharing and remote management, and regulatory approvals enabling tighter system integrations are accelerating closed‑loop telecare.
-
Clinical‑service specialists: A subset of companies combine RPM devices with nurse‑led virtual clinical support or specialized prevention sensors, creating differentiated value propositions around complications avoidance and behaviorally focused reversal programs.
Our report profiles leading suppliers, evaluates their strategic positioning, and maps recent developments that change competitive dynamics — for example, new product launches extending remote monitoring scope, regulatory clearances enabling device interoperability, and policy updates expanding reimbursement pathways.
Recent developments with direct operational impact
-
Product launches expanding monitoring scope — innovations that bring multi‑parameter sensing into routine remote surveillance and broaden use cases for early complications detection.
-
Regulatory clearances that enable device interoperability and automated delivery, unlocking higher‑value closed‑loop telecare.
-
Policy updates that extend telehealth flexibilities and introduce RPM codes better aligned with modern remote diabetes management — these materially affect go‑to‑market and pricing strategies for the next 24 months.
What the PW Consulting report delivers (practical contents)
Our Diabetes Telemedicine Technology Market report is designed as a decision-ready playbook for executives. It includes:
-
Executive market thesis and scenario-driven forecasts (topline market trajectory and sensitivity analyses for 2026–2032).
-
Vendor scorecards and strategic positioning maps to inform partnership, M&A, and procurement decisions.
-
Implementation playbooks — technology integration blueprints, data integration checklists, clinician workflow redesign templates, and pilot KPIs that accelerate time-to-value.
-
Reimbursement and commercial templates — use-case level contracting approaches, RPM coding implications, and payer negotiation tactics tied to clinical outcomes.
-
Regulatory and compliance trackers tailored to device‑software integrations and telehealth modalities.
-
Risk and mitigation frameworks covering cybersecurity, patient engagement, and interoperability failure modes.
To preserve competitive value, the report presents headline market sizing and growth dynamics in this announcement while withholding full sub‑segment tables and granular regional/application breakdowns — these are available in the full report for subscribers and clients.
Implications for common enterprise audiences
-
For device manufacturers: Shift resources toward software-enabled services and certified integrations; demonstrate outcomes to secure higher reimbursement and preferred placements in provider contracts.
-
For digital health platforms: Differentiate through clinical depth and workflow automation; leverage interoperability to become the data layer for value‑based diabetes care.
-
For payers and health systems: Prioritize pilots that align RPM economics to short‑term revenue codes and medium‑term risk-sharing arrangements tied to complication avoidance.
-
For investors: Seek companies with defensible data assets, validated clinical programs, and established routes to reimbursement; concentration ratios suggest acquisition opportunities for scale players seeking clinical depth.
Methodology and credibility
PW Consulting’s forecasts combine bottom‑up device shipment and subscription modeling with top‑down adoption scenarios informed by payer policy shifts, vendor product roadmaps, and clinician adoption curves. We triangulate vendor disclosures, regulatory filings, reimbursement rulings, and primary interviews with provider, payer, and vendor executives to produce actionable insights.
Call to action
PW Consulting’s Diabetes Telemedicine Technology Market report provides the operational detail executives need to convert 2026 opportunities into sustainable programs. The release above highlights the market’s scale and the strategic inflection points shaping near‑term decisions; detailed segment tables, regional and application splits, vendor scorecards, and implementation templates are reserved for the full report.
Contact PW Consulting or visit our report page to access the complete analysis, the downloadable playbooks, and a bespoke briefing to align your 2026 strategy with the market’s accelerating trajectory.
For detailed analysis of this topic, please visit the official page: Diabetes Telemedicine Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digital Ureteroscopes Market Set to Expand at a 6.5% CAGR
By pmarketresearch, 2026-07-13
Digital Ureteroscopes Market — Strategic Imperatives for 2026: A PW Consulting Preview
Executive summary
The global digital ureteroscopes market has transitioned from a niche clinical tool into a strategically important segment of urology capital and consumables planning. After expanding from roughly USD 240 million in 2020 to an estimated USD 320 million in our 2025 base year, the market is forecast to grow at a compound annual growth rate (CAGR) of approximately 6.5% through 2032, when total revenues are projected to approach the half‑billion dollar mark. This steady expansion is being driven by converging forces: rising prevalence of stone disease, procedural migration to ambulatory settings, regulatory clarity for digital devices, and rapidly maturing single‑use technologies that change total cost of ownership considerations for hospitals and ASCs.
Digital Ureteroscopes Market
Why this report matters to executives in 2026
- Make capital allocation decisions with confidence: the report translates market momentum into targeted investment priorities across product platforms, manufacturing scale, and aftermarket service capability.
- Design differentiated go‑to‑market strategies: our customer segmentation and procurement insights reveal where clinical value, pricing flexibility, and service models create defensible positioning.
- De‑risk regulatory and reimbursement pathways: the report synthesizes 510(k) precedent, biocompatibility expectations, and CPT/payment dynamics to guide submission and evidence plans.
- Identify consolidation and partnership opportunities: a focused M&A playbook highlights targets and rationales for bolt‑on acquisitions and distribution alliances.
- Prepare for clinical adoption inflection points: scenario models quantify the implications of single‑use adoption, reusable lifecycle optimization, and new imaging/pressure‑monitoring features on buying decisions.
What the PW Consulting report delivers (practical, executable content)
- Actionable market forecast model (2026–2032) with scenario sensitivity to pricing, reimbursement, and adoption rates — delivered in spreadsheet format for executive planning.
- Procurement and TCO playbook comparing single‑use and reusable economics across typical hospital and ASC purchasing profiles, including repair and reprocessing assumptions.
- Regulatory roadmap and evidence plan templates for 510(k) submissions, incorporating performance, imaging, and biocompatibility endpoints.
- Commercial due diligence modules: competitor benchmarking, pricing ladder, channel analysis, and distribution cost models.
- Clinical adoption accelerator: recommended clinical study designs and key opinion leader engagement strategies to shorten time‑to‑adoption.
- M&A and partnership matrix identifying strategic fits by capability, region, and product architecture — prioritized by our proprietary strategic fit scoring.
- Customizable slide decks and executive summaries to inform Board discussions and investor briefings.
Competitive landscape snapshot — what leading suppliers are doing and what it means
The competitive field combines legacy endoscopy OEMs with newer single‑use specialists. Market concentration is meaningful: a handful of established players shape standards, channel relationships, and clinical perceptions, while agile entrants accelerate innovation on disposability, slim‑profile engineering, imaging, and systems integration.
Digital Ureteroscopes Market
- Boston Scientific Corporation — Leveraging its LithoVue Elite single‑use platform and recent FDA actions, Boston Scientific is pushing value through integrated procedure support features such as real‑time intrarenal pressure monitoring. For incumbents and new entrants alike, the key takeaway is that procedure‑level differentiation (e.g., pressure monitoring) shortens clinical adoption cycles when coupled with reimbursement clarity.
- KARL STORZ SE & Co. KG — With high‑resolution CMOS imaging and reusable platform strength, KARL STORZ positions toward hybrid strategies that retain reusable economics while modernizing visualization. Their playbook demonstrates how durable platforms can compete by emphasizing lifetime imaging quality and accessory ecosystems.
- Olympus Corporation — Olympus continues to stress durability and image fidelity for flexible ureteroscopy. Their strength in endoscopy services and dealer networks underlines the importance of post‑sale support as a competitive moat.
- Dornier MedTech — Recent U.S. product introductions reflect a focused single‑use strategy complemented by procedure accessories (e.g., ureteral access sheaths). Dornier’s launches highlight the commercial impact of bundling disposables with complementary devices to capture procedure economics.
- Ambu A/S — Ambu’s aScope 5 Uretero and system compatibility illustrate how platform interoperability (camera‑to‑processing unit) can accelerate adoption in facilities seeking turnkey single‑use workflows.
- OTU Medical Inc. — As a nimble innovator, OTU advances slim models and differentiated deflection options, forcing incumbents to respond on miniaturization and ergonomics. Smaller firms like OTU are often attractive targets for strategic buyers seeking technology fills.
- Richard Wolf GmbH & Stryker Corporation — Both emphasize imaging advances and portfolio breadth. Their market presence reinforces that integration into broader endoscopy suites and cross‑selling into urology portfolios remain high‑value routes to scale.
Collectively, these players illustrate two parallel competitive arcs: (1) platform incumbency that leverages durable assets, service, and imaging excellence; and (2) single‑use entrants that target infection control, streamlined workflows, and predictable per‑procedure economics. Winning strategies will combine clinical evidence, channel economics, and device lifecycle engineering.
Digital Ureteroscopes Market
Regulatory, reimbursement and clinical dynamics to watch
- Regulatory: Digital flexible ureteroscopes are regulated in the U.S. under Class II device pathways with 510(k) precedent. Manufacturers must demonstrate visualization performance, accessory compatibility, and biocompatibility — and recent clearances underscore that regulators expect mature bench and clinical evidence packages.
- Reimbursement: Established CPT codes for ureteroscopic stone management support both single‑use and reusable adoption models. Reimbursement landscapes are generally stable, but procurement teams will require robust per‑procedure economics to greenlight capital changes.
- Clinical: The single‑use value proposition — elimination of reprocessing and cross‑contamination risk — is resonating, particularly in high‑volume centers and ASCs. Conversely, reusable platforms remain attractive where repair networks, exchange programs, and image longevity reduce lifetime cost.
Key strategic recommendations for 2026 decision‑makers
- For OEMs considering product investment: prioritize modular imaging and sensor features (e.g., intrarenal pressure monitoring) that can be field‑upgraded; this protects installed bases and supports premium pricing.
- For single‑use specialists: build channel partnerships with distributers that have strong ASC and community hospital reach, and structure flexible commercial pilots that address procurement risk aversion.
- For hospital and ASC procurement leaders: adopt total cost of care frameworks that compare single‑use and reusable options across direct costs, downtime risk, and infection control externalities; engage clinicians with objective, site‑specific models from pilot data.
- For investors and PE sponsors: prioritize targets with proprietary manufacturing scale or unique consumable economics; accelerate diligence on repair networks and aftermarket revenue potential where reusable models persist.
- For regulators and payors: collaborate early with innovators on clinical endpoint selection to avoid late design modifications that delay market access.
How PW Consulting’s report helps translate insight into action
Our Digital Ureteroscopes Market report is structured as a practical toolkit, not an academic exercise. It combines primary interviews with clinicians and procurement officers, supplier financial and product intelligence, and a transparent forecasting engine you can adapt to your assumptions. Deliverables include a risk‑adjusted forecast model, playbooks for commercial pilots, evidence templates for regulatory submissions, and an M&A checklist that prioritizes value levers.
In keeping with our “preview” approach, this release outlines the strategic conclusions and operational guidance that will influence 2026 planning. Detailed tables — including supply chain cost models, region‑by‑region demand breakdowns, product‑type volumes, and granular price elasticities — are intentionally reserved for the full report to provide maximum commercial value to purchasers.
Next steps
PW Consulting’s Digital Ureteroscopes Market report is designed for CEOs, corporate strategy teams, commercial leaders, and investors who must make firm choices in 2026 about product roadmaps, go‑to‑market models, and M&A activity. To unlock the full dataset, customizable forecast workbook, and tactical playbooks, contact PW Consulting to obtain the complete report and licensing options for enterprise use.
For detailed analysis of this topic, please visit the official page: Digital Ureteroscopes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com