

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sleep Apnea Masks Market Set to Expand at an 8.15% CAGR Through 2032

Sleep Apnea Masks Market — Strategic Outlook and Decision Framework for 2026
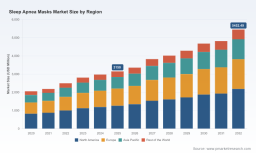
As demand for obstructive sleep apnea therapies grows, the global sleep apnea masks market stands at a pivotal inflection point. Our baseline assessment places total market revenue at roughly USD 3.15 billion in 2025, with a modeled expansion to approximately USD 5.45 billion by 2032, representing a 2026–2032 compound annual growth rate (CAGR) of 8.15%. Those headline numbers mask important structural shifts — convergence of clinical, reimbursement, regulatory and channel dynamics — that will determine winners and losers in 2026 and beyond.
Sleep Apnea Masks Market
Why this report matters to 2026 decision-makers
Executives making capital allocation, product roadmap, commercial partnership, or M&A decisions in 2026 cannot rely on historical playbooks alone. Accelerating product innovation (AI-assisted personalization, minimalist interfaces), changing reimbursement practices, and new entrants expanding distribution channels are altering the basis of competition. Our study synthesizes market sizing and a forward-looking scenario suite with practical modules — regulatory pathways, reimbursement maps, customer segmentation and supplier scorecards — designed to convert insight into executable choices.
Sleep Apnea Masks Market
-
Clarity on market scale and trajectory: our top-line model establishes the macro opportunity and quantifies upside across plausible adoption scenarios through 2032.
Sleep Apnea Masks Market -
Decision-grade drilldowns: we translate epidemiology, device adoption curves and payer mechanics into specific revenue implications for product classes and routes-to-market — without exposing confidential segmented tables in this summary.
-
Actionable playbook: we map 12-month and 36-month actions by company archetype — incumbent OEM, new entrant, component supplier, and distributor — so management teams can prioritize investments and partnerships immediately.
Market architecture and dynamics (executive summary)
The market is concentrated: the top three players account for the majority of revenue and the top five approach near-total concentration, reflecting high switching costs for established channel relationships and value attributed to clinical evidence and device compatibility. Competitive advantage is increasingly derived from ecosystem control — device-to-mask interoperability, software-linked comfort personalization, and broad payer coverage — rather than narrow hardware differentiation alone.
Key structural drivers include:
-
Clinical acceptance and adherence improvements supported by comfort innovations and remote monitoring.
-
Payer rules and replacement cycles that shape unit demand and aftermarket revenue.
-
Regulatory requirements (CPAP masks are regulated as Class II devices requiring 510(k) clearance in the U.S.) that impose time and cost on market entrants but also raise barriers to low-quality imports.
-
Supply-chain dependencies — notably medical-grade silicone for cushions — that influence margin and time-to-market across manufacturers.
Competitive landscape — who to watch and why
The current competitive set blends entrenched global OEMs, specialist mask manufacturers and new disruptors seeking market footholds. Our report provides comparative strategic profiles, OEM playbooks and scenario analyses for each of the leading players. Highlights below summarize strategic implications rather than exhaustive firm-level data.
-
ResMed — With recent regulatory clearances for AI-enabled comfort personalization, ResMed is shifting the value equation from purely mechanical fit to software-assisted adherence improvement. For competitors, this raises the bar on data-enabled features and creates opportunities for partnerships where device ecosystems are open.
-
Fisher & Paykel Healthcare — Known for cushion and headgear innovations, Fisher & Paykel continues to defend premium segments through incremental design and clinician-focused evidence. Their approach underscores the continued importance of clinician buy-in in hospitals and sleep labs.
-
Philips Respironics — With a broad portfolio across full face and nasal interfaces, Philips remains a distribution powerhouse. Their scale amplifies marketing reach and supports competitive pricing strategies.
-
Inogen — A recent entrant with a new CPAP mask line backed by patient-use evidence, Inogen demonstrates how adjacent respiratory players can disrupt incumbents by leveraging existing distribution and brand trust.
-
REMSleep Holdings — A small but strategically important player whose expanded regulatory clearance for nasal pillow systems broadens addressable institutional customers; that clearance signals opportunities for suppliers who can adapt clinical evidence for broader use cases.
-
Other notable participants — Several regional and specialist manufacturers (including legacy DME suppliers and low-cost OEMs) remain competitive on price and niche design innovation, particularly where distribution and reimbursement barriers are lower.
Strategic inference: incumbents must defend ecosystem lock-in (device-to-mask compatibility, software advantages), while challengers can win by focusing on a limited number of high-impact clinical or commercial differentiators and by forming targeted channel partnerships.
Regulatory, reimbursement and supply-side realities
Regulatory and payer mechanics materially influence commercial viability. In the U.S., CPAP masks are regulated as Class II devices and typically require 510(k) clearance to be marketed. Medicare and other payers reimburse masks under specific HCPCS codes and replacement schedules — these coverage and frequency rules continue to shape unit demand and aftermarket sales. On the supply side, reliance on medical-grade silicone for cushions remains a critical input; quality, certification and sourcing resilience can be decisive in product launches and returns to service models.
What the report contains — practical modules for execution
Our full market study is organized to support immediate strategy execution and board-level decision-making. Key modules include:
-
Validated market sizing and forecast model (2020–2032) with scenario toggles for clinical adoption and reimbursement changes.
-
Product and channel profitability matrix to prioritize SKU rationalization and new product investments.
-
Regulatory playbook and time-to-market comparator for U.S., EU and select APAC markets — including a 510(k) checklist and mitigation pathways.
-
Reimbursement and claims analysis mapping codes, replacement timelines, and payer sensitivities relevant to unit economics.
-
Competitive scorecards and M&A landscape with playbook options for bolt-ons, licensing and OEM partnerships.
-
Supply-chain risk assessment focused on cushion materials, contract manufacturing options and inventory resiliency strategies.
-
Customer segmentation and go-to-market blueprints for direct-to-consumer, DME channel, and institutional sales.
-
Investment case templates and valuation sensitivities for private equity and corporate development teams evaluating entry or expansion.
Recommended strategic agenda for 2026
Our synthesis yields a concise set of prioritized moves that market participants should consider implementing in 2026:
-
Prioritize interoperability: secure device-to-mask compatibility or provide clear conversion incentives for clinician networks.
-
Invest selectively in software-enabled comfort features and adherence analytics — not as an add-on, but as a core differentiator tied to reimbursement-friendly clinical outcomes.
-
Strengthen supplier diversification for medical-grade silicone and critical components; consider dual-sourcing and inventory hedges.
-
Map and monetize aftermarket revenue: focus on replacement cycles, consumables and subscription models for mask refresh and hygiene compliance.
-
Leverage regulatory wins: use 510(k) clearances and clinical evidence as commercial levers to unlock institutional channels and payer contracting.
-
For new entrants: pursue focused, evidence-backed product launches with tight channel partnerships rather than broad-market rollouts.
-
For investors: prioritize targets with defensible distribution or proprietary adherence data, and stress-test acquisition models against reimbursement changes.
How PW Consulting’s analysis reduces execution risk
Our methodology integrates primary interviews with clinicians and payers, device-level usage telemetry where available, claims data modeling, and component-level costing. The report’s scenario engine allows leaders to stress-test strategic bets — for example, the commercial impact of a regulatory clearance that expands institutional use or the entry of a low-priced competitor into key channels. The output is not a set of static tables but an executable roadmap and a prioritized action list tailored to company archetypes.
Next steps — where to get the full intelligence
This briefing is a strategic preview: it reveals the market trajectory, competitive inflection points and tactical imperatives while intentionally omitting the granular segment-level tables and downloadable model that underpin the full analysis. For teams preparing 2026 budgets, product roadmaps, or M&A pipelines, the report’s complete datasets and scenario models are an essential complement to internal planning. Visit our report page to access the full study, interactive forecast model and deep-dive annexes — including company scorecards, contract manufacturer maps, and reimbursement worksheets that support rapid decision-making.
In a market defined by clinical nuance, payer complexity and accelerating product innovation, actionable intelligence wins. Our Sleep Apnea Masks Market report is designed to convert insight into impact — helping leaders choose the right investments, partners and product bets for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Sleep Apnea Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com