

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Jewelry Beads Market Set to Grow at 5.5% CAGR Through 2032, New Report Reveals

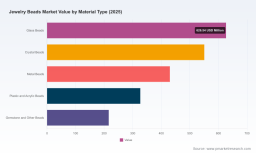
PW Consulting: Strategic Outlook — Jewelry Beads Market Report (Base Year 2025) — A 2026 Decision-Maker’s Playbook
PW Consulting today releases its authoritative market intelligence brief for the global Jewelry Beads Market, built on a five-year historical foundation (2020–2025) and forward-looking forecasts through 2032. The study sizes the market at USD 2,150 million in 2025 and models growth to approximately USD 3,128 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.5% over the 2026–2032 forecast window. Designed specifically to inform near-term corporate strategy, sourcing decisions, and commercial execution in 2026, the report blends rigorous data analysis with practical, operational playbooks for manufacturers, distributors, brands and investors.
Jewelry Beads Market
Why this report matters for 2026
-
Actionable intelligence for immediate allocation decisions: the report translates market-scale and trend signals into prioritised tactical moves for the coming 12–18 months.
Jewelry Beads Market -
Risk-informed sourcing and manufacturing guidance: detailed supply‑chain mappings and scenario plans that allow procurement teams to stress-test sourcing alternatives against tariff and energy volatility.
Jewelry Beads Market -
Revenue and margin playbooks: go-to-market templates for premium and value-tier strategies, channel mix optimization, and SKU rationalisation to protect margins as cost pressures shift.
-
M&A and partnership roadmaps: an investment lens highlighting where consolidation, vertical integration, or strategic alliances can accelerate scale or margin capture.
Market context and near-term dynamics
The Jewelry Beads Market navigated uneven performance in the early 2020s, with pandemic-era disruption, subsequent normalization, and commodity-driven cost shocks. After a period of contraction observed in 2023, the market rebounded through 2024 into 2025, culminating in the USD 2,150 million base year. Our models forecast steady expansion to just over USD 3.1 billion by 2032 under a central-case CAGR of 5.5% — a growth trajectory driven by a combination of personalized-fashion demand, expanding DIY and craft communities, premiumization in discretionary spend, and rising digital commerce penetration.
However, the outlook is not uniform across the value chain. Key structural forces to watch in 2026 include: input-cost pressure from energy and raw-material markets (notably for glass and crystal production), evolving regulatory constraints on hazardous substances in jewelry components, and shifting geopolitical trade policies that affect cross-border sourcing and landed costs. These dynamics create concentrated tactical risks — and opportunities — for firms that move early on supply diversification, cost-to-serve optimisation and product differentiation.
Competitive landscape — fragmented but strategically active
The industry remains low-to-moderately concentrated, with leading firms accounting for a limited share of the global market. This fragmentation sustains healthy competition and niche specialization. From precision crystal producers and legacy Czech glass manufacturers to large-scale wholesale platforms and regional distributors, competitive advantage today is built on one or more of the following: brand premiumisation, product precision and quality control, scale in distribution, specialist design and color trend capability, and digital channel mastery.
-
Established manufacturers with deep technical know-how — such as precision-cut crystal suppliers and traditional European glass bead makers — retain leadership in premium and craft-centric segments, leveraging centuries‑old manufacturing techniques combined with contemporary design trend pipelines.
-
Large wholesale platforms and diversified suppliers from Asia provide scale, breadth of assortments, and rapid replenishment capabilities that serve mass-market and fast-fashion channels.
-
US- and Europe-based distributors and specialist retailers combine curated assortments with educational content and community engagement, supporting the growth of the DIY consumer base and higher-frequency repeat purchases.
Notable market participants profiled in the report include leading manufacturers, premium crystal brands, major wholesale platforms and specialised distributors. Our company dossiers evaluate product portfolios, channel strategies, manufacturing footprints, regulatory compliance readiness and strategic intent — enabling readers to benchmark partners and rivals on criteria that matter for 2026 execution.
Regulatory and supply-side noise to factor into 2026 plans
-
Regulatory compliance remains a table-stakes issue: jurisdictions continue to enforce strict limits on lead, cadmium and other regulated substances in jewelry components, with active standards in major markets. Buyers and manufacturers must accelerate testing, certification and traceability to avoid market access disruptions.
-
Trade policy and tariffs: tariffs on certain glass bead imports and the possibility of tariff actions on gemstone and component imports increase landed-cost risk. Procurement teams should model tariff scenarios and evaluate near-shore alternatives.
-
Energy and input-cost inflation: energy price increases in key production centers have materially affected glass-bead manufacturing economics. Our cost models and scenario analyses help quantify the pass-through potential and identify levers for mitigation.
2026 Playbook — concrete steps recommended by PW Consulting
For executives preparing budgets and strategic initiatives for 2026, the report distills our analysis into a prioritised, time-bound playbook:
-
Sourcing diversification: implement a two-track sourcing strategy — secure low-cost scale supply while qualifying regional or near-shore partners for critical SKUs to reduce tariff and transport risk.
-
Selective premiumisation: launch capsule collections with premium crystal and precision-cut glass to capture margin expansion; use limited-edition runs and color-trend tie-ins to drive urgency and higher ASPs.
-
Channel rebalancing: accelerate direct-to-consumer digital experiences and subscription/kit offerings to increase lifetime value and reduce dependence on wholesale churn.
-
Regulatory-first product governance: institute mandatory materials testing, vendor attestations and SKU-level compliance flags to protect market access in regulated regions.
-
Operational resilience: hedge energy exposure where possible, pursue manufacturing efficiency projects, and adopt inventory segmentation to align service levels to SKU economics.
-
M&A and partnerships: target bolt-on acquisitions that fill capability gaps (e.g., precision finishing, proprietary crystal formulations, or design studios) and co-invest in shared warehousing for regional speed-to-market.
What’s inside the PW Consulting report (practical deliverables)
The report balances high-level strategic guidance with tangible, implementable assets designed for 2026 action:
-
Executive synthesis and investment thesis for 2026–2028
-
Historical market sizing (2020–2025) and forward projections (2026–2032) with sensitivity scenarios
-
Demand-driver analysis: consumer cohorts, channel economics, and product archetypes
-
Supply-chain maps and supplier scorecards (quality, lead time, regulatory posture and ESG metrics)
-
Regulatory and tariff appendix summarising active standards and duty exposures relevant to sourcing decisions
-
Practical toolkits: cost-to-serve models, SKU rationalisation templates, supplier negotiation playbooks, and a go-to-market launch checklist
-
Company profiles and competitive benchmarking across manufacturing, wholesale, and retail segments
Recent industry movements and signals to monitor in 2026
Market actors continue to use trade shows, trend leadership and product introductions as commercial catalysts. Recent activity includes trade show participation across major industry events and early releases of seasonal color trends by leading bead manufacturers — tangible signals that design-led differentiation and community engagement remain powerful growth levers. At the same time, documented increases in energy costs for glass production and continuing regulatory scrutiny reinforce the need for material traceability and cost contingency planning.
How to use this report
Procurement directors, product heads, private equity investors and board members should use this report as both a risk map and a testable operations-and-commercial playbook. It is particularly useful for companies that need to: (1) rebuild supplier scorecards after a period of supply constraint, (2) reprice assortments to protect margins, (3) identify acquisition targets that bring manufacturing differentiation, or (4) accelerate direct-to-consumer propositions tied to design and color trends.
PW Consulting’s Jewelry Beads Market Report is intentionally constructed as a “teaser + toolkit” — it demonstrates the depth of our market modelling and strategic prescriptions while reserving full segment-level allocations, granular regional breakdowns and company revenue shares for the complete report package. This approach ensures decision-makers have a concise strategic summary now, with the option to access the detailed datasets, interactive dashboards and supplier scorecards required for immediate implementation.
To access the full report, the interactive data dashboards, or to commission a custom 90‑day implementation engagement aligned to your specific supply, product, or channel needs, visit PW Consulting’s research portal or contact our Jewelry & Accessories practice lead for a briefing.
For detailed analysis of this topic, please visit the official page: Jewelry Beads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com