

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
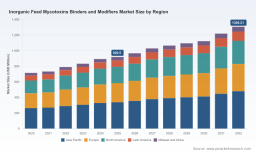
PW Consulting Forecasts Inorganic Feed Mycotoxin Binders Market to Grow at 5.15% CAGR (2026–2032) from USD 920.5M Base (2025) to USD 1,308.2M by 2032 — Asia‑Pacific, Bentonite (USD 514.3M) and Poultry Feed (USD 388.5M) Lead in Fragmented Market (CR3 28.5%)

Inorganic Feed Mycotoxins Binders and Modifiers Market: Strategic Imperatives for 2026 — PW Consulting Insight
Executive snapshot
The inorganic feed mycotoxins binders and modifiers market has moved from a niche risk-management tool to a core component of commercial feed strategies. Our PW Consulting benchmark study (base year 2025, historical 2020–2025, forecast period 2026–2032) quantifies this maturation: the global market rose steadily through the early 2020s to reach approximately USD 920.5 Million in 2025 and, under our base-case projections at a compound annual growth rate (CAGR) of 5.15%, is expected to approach USD 1.31 Billion by 2032. These headline figures matter for boardroom decisions in 2026 because they reflect a combination of sustained demand, structural supply factors, and regulatory pressures that will shape capital allocation, product development and route-to-market strategies over the next planning cycle.
Inorganic Feed Mycotoxins Binders And Modifiers Market
Why 2026 is a strategic inflection point
Several converging dynamics elevate 2026 as a decision-making inflection point for feed manufacturers, ingredient suppliers, and investors:
Inorganic Feed Mycotoxins Binders And Modifiers Market
- End-market professionalization. Animal-protein producers are formalizing mycotoxin mitigation into procurement specifications rather than ad hoc risk responses — increasing demand for validated, consistent binder solutions.
- Regulatory tightening and claims scrutiny. Evolving regional frameworks (notably in the EU) already recognize specific inorganic clays for aflatoxin mitigation while imposing efficacy and safety requirements. This raises the bar for product substantiation and places a premium on providers that can demonstrate efficacy without compromising nutrient bioavailability.
- Raw material and supply-chain realities. Inorganic binders are mined minerals (bentonite, montmorillonite, sepiolite, zeolites, etc.); variations in ore quality, processing, and logistics create cost and availability variability — a commercial lever and a source of risk.
- Product differentiation and commercialization maturity. Leading players are moving from generic clay supply to formulated, branded solutions with demonstrable spectrum coverage against polar and non-polar mycotoxins and integrated service propositions (application guidance, dosing protocols, performance monitoring).
What the numbers imply for strategy
Headline market growth at ~5.15% CAGR masks important heterogeneity in demand drivers and supplier economics. From a strategic standpoint, the expansion trajectory signals continued, predictable revenue for suppliers that can solve three problems simultaneously: efficacy across mycotoxin classes, regulatory-compliant claims, and minimal nutrient interaction. For buyers and processors, predictable market growth reduces supply-side volatility risk but increases the need for robust vendor selection criteria.
Inorganic Feed Mycotoxins Binders And Modifiers Market
Competitive landscape — positioning and dynamics
The market exhibits moderate concentration: the top-three suppliers account for a meaningful slice of sales while the top-five extend that reach further. This creates a dual dynamic — established players exert scale advantages in R&D, distribution and regulatory dossiers, yet material indigenous and regional suppliers sustain local competition and innovation. Against this backdrop, a handful of global players set the tone for product claims and channel expansion:
- Amlan International (Oil-Dri Corporation of America) — Strengths lie in proprietary mineral processing and branded binder lines designed for rapid aflatoxin uptake and broader biotoxin coverage. Recent commercial moves (product launches and partnerships in South Asia, and high-visibility showcases at regional feed shows) illustrate an aggressive go-to-market cadence designed to convert technical differentiation into market share gains.
- Kemin Industries — Leverages longstanding feed additive expertise and a portfolio approach combining inorganic adsorbents with complementary chemistries. Kemin’s playbook emphasizes validated performance and integration into feed producer quality systems, which supports premium positioning in risk-averse markets.
- Tolsa — European clay specialist with multi-component formulations that combine bentonite, sepiolite and activated carbons. Tolsa’s strength lies in raw-material mastery and a product development pathway focused on balanced sequestration across toxin profiles.
- Bentoli Inc. — Representative of agile, product-centered suppliers that compete on formulation flexibility and close commercial service to livestock and poultry customers, especially in regional markets where local ore access and quick field support matter.
These players exemplify different routes to commercial success: proprietary processing and branded science, integrated feed-additive portfolios, raw-material specialization with formulation expertise, and regional service-led competition. For strategic buyers, the choice between scale, scope and local intimacy will depend on target geographies, product claims required, and procurement sophistication.
Regulatory and scientific guardrails — what you must prove
Regulatory frameworks are a gating factor for premium positioning. The European example — where certain bentonites are authorised for aflatoxin B1 reduction subject to clear dosing limits and demonstration of safety — illustrates the twin requirements of efficacy and nutrient-safety. Regulatory authorities increasingly require evidence that binders do not impair the bioavailability of key nutrients while delivering measurable mycotoxin reduction. From a strategic perspective, this raises several imperatives:
- Invest in robust, GLP-aligned efficacy and safety studies; third-party validations materially affect acceptance by feed mill customers and integrators.
- Align product labels and claims with jurisdictional norms; overclaiming invites regulatory pushback and commercial rejection.
- Embed nutrient-interaction testing into the product development cycle to avoid costly reformulations after market entry.
Practical content in the PW Consulting report — what decision-makers will find
Our report is designed as an operational playbook for 2026 decisions rather than an academic treatise. Among the deliverables we highlight:
- Top-line market sizing (historic and forecast) and scenario modelling under alternative price-and-supply assumptions, with transparent methodology and sensitivity tables.
- Segment-level demand drivers across product types, applications and regions — with trade-offs and risk matrices. (Note: we intentionally withhold granular proprietary splits in this press preview.)
- Supplier scorecards and capability maps assessing R&D, regulatory dossiers, distribution reach and service models — an actionable shortlist for procurement and M&A screening.
- Commercial due-diligence templates and unit-economics calculators that buyers and private-equity teams can apply to prospective targets.
- Raw-material sourcing playbooks, including mine-to-mill quality controls, logistics optimization and hedging approaches for feed-ingredient buyers.
- Case studies of field trials and application protocols that demonstrate how to convert laboratory efficacy into farm-level performance.
Actionable recommendations for executives in 2026
For leadership teams looking to convert market insight into competitive advantage, our analysis points to a focused set of steps:
- Prioritize regulatory-grade evidence. Allocate budget early in 2026 for GLP studies that simultaneously measure toxin sequestration and nutrient bioavailability.
- Lock in ore quality and logistics. Establish multi-source feedstock contracts and invest in upstream processing controls to stabilise product quality and margin.
- Pursue selective partnerships in high-growth geographies. Local distribution or manufacturing partnerships accelerate market access and lower commercial friction in regions with rising feed safety standards.
- Differentiate through service. Offer dosing calculators, field-monitoring programs, and co-branded farm-level trials to move beyond commodity pricing.
- Use targeted M&A to consolidate mid-tier players and capture regional scale — but only after stress-testing nutrient-interaction and regulatory dossiers.
- Prepare for claim scrutiny. Harmonise marketing claims with regulatory expectations and ensure traceability across the supply chain.
M&A and investor perspective
The sector’s moderate concentration profile creates both buy-and-build and roll-up opportunities. Strategic acquirers can achieve scale benefits in R&D and regulatory costs, while financial sponsors can extract multiple expansion through operational improvement (procurement, formulation standardisation, and route-to-market optimisation). However, premium valuations must be justified by validated pipeline efficacy, stable raw-material access, and defensible customer contracts. Our proprietary valuation frameworks in the report model these contingencies explicitly.
Conclusion — how PW Consulting helps you act in 2026
The inorganic binders and modifiers market is a mature growth market that rewards technical credibility, supply-chain control and regulatory discipline. For companies and investors planning capital and commercial decisions in 2026, the critical question is not whether demand exists, but how to capture it at attractive margins while meeting rising evidence and regulatory standards.
PW Consulting’s full report provides the granular segmentation, supplier scorecards, scenario forecasts and execution roadmaps required to convert the high-level insights in this preview into operational plans. If your 2026 strategy depends on securing product differentiation, market access or M&A confidence in the inorganic mycotoxin binders space, our detailed models and templates are designed to accelerate decision-making and de-risk execution.
For detailed analysis of this topic, please visit the official page: Inorganic Feed Mycotoxins Binders And Modifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com