

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
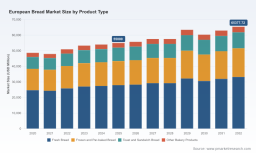
PW Consulting: European bread market valued at $55B in 2025, forecast to reach $65.4B by 2032 on a 2.5% CAGR

European Bread Market 2026 Preview: Strategic Imperatives for Producers, Retailers, and Investors
PW Consulting's latest European Bread Market report (base year 2025) delivers a practical, decision-focused roadmap for executives preparing budgets, supply strategies, and M&A activity for 2026 and beyond. The European bread market registered steady recovery through 2020–2025 and stood at approximately USD 55,000 million in 2025. Our modelling projects continued expansion across 2026–2032 at a compound annual growth rate of 2.5%, reaching an estimated USD 65,378 million by 2032. This briefing outlines the strategic value of the report for boardrooms and business units while deliberately reserving detailed segment-level tables and region-specific figures for subscribers to the full report.
European Bread Market
Why this report matters for 2026 decisions
-
Actionable foresight for 2026 planning cycles: The forecast cadence and scenario modelling included in the report align with typical capex and commercial planning timelines, translating macro projections into quarterly, channel‑level implications for 2026 budgeting and 2027–2028 operational plans.
European Bread Market -
Risk-first supply decisions: With raw material volatility intensifying, procurement teams need granular stress tests and hedging playbooks to justify supplier contracts, working capital and storage investments. Our report maps likely P&L sensitivity to commodity moves under multiple scenarios.
European Bread Market -
M&A and partnership prioritisation: The study filters potential targets by strategic fit, integration risk and near-term synergies—equipping corporate development teams with a ranked shortlist and valuation heuristics geared to current market multiples.
-
Regulatory-readiness: New and upcoming rules will reshape packaging, labelling and fortification obligations across key jurisdictions. The report translates regulatory timelines into compliance checklists, cost impact estimates and reformulation roadmaps.
Market trajectory and structural characteristics
After a mid‑cycle dip and subsequent rebound in the early 2020s, the European bread market demonstrated resilience through shifting consumer habits and cost pressures. Our base-year sizing (2025) and point forecasts through 2032 show moderate, steady growth—reflecting a maturing market where volume growth is increasingly supported by product premiumisation, convenience formats and bake-off / frozen channels rather than broad-based expansion in staple volumes.
Concentration metrics indicate a market that is not dominated by a single player: the three‑firm concentration and five‑firm concentration ratios point to a competitive landscape where national and regional champions coexist with pan‑European groups and local independents. This structure creates both acquisition opportunities for scale players and white‑space for nimble specialists focused on niche channels.
Key dynamics shaping 2026 outcomes
-
Commodity volatility: Wheat futures have moved materially—our monitoring layer observed prices around USD 666 per bushel as of May 20, 2026, up more than 20% year‑over‑year. That step‑change in raw material cost feeds directly into short‑term margin erosion for producers and can trigger rapid price‑pass through or demand shifts for lower‑cost formats. The report contains sensitivity tables linking wheat price bands to EBITDA impacts at multiple scale points.
-
Packaging and waste regulation: The EU Packaging and Packaging Waste Regulation (PPWR), in force from August 2026, imposes recyclability, recycled content and waste reduction targets. For bread producers and private‑label manufacturers, this creates immediate design and sourcing requirements for primary and secondary pack formats—impacting both cost and shelf logistics. Our compliance roadmap prioritises packaging interventions with the highest ROI and provides supplier assessment criteria for recycled content sourcing.
-
Labelling and fortification obligations: Existing EU consumer information rules continue to enforce nutrition and allergen transparency for prepacked bread products; alongside this, some national regimes (notably the UK) have phased in mandatory flour fortification measures by late 2026. These developments have product formulation and labelling implications that the report quantifies in terms of reformulation cost, labelling change management and audit readiness.
-
Channel evolution: Retail consolidation, the maturation of online speciality retail and the rapid professionalisation of foodservice bakery offer divergent growth vectors. Our channel scenarios examine trade‑off choices—e.g., margin erosion in mainstream grocery versus unit economics in QSR supply agreements and the capital efficiency of bake‑off models for quick service and in‑store fresh offers.
Competitive landscape: what incumbents and challengers are doing
The competitive field is marked by differentiated strategies: global scale players pursue geographic roll‑outs and integration into QSR supply chains; convenience‑focused specialists expand frozen and par‑baked capacity; national champions defend branded premium positions while independents capture artisan and local freshness premiums. The report contains detailed company profiles and strategic play analyses for major operators, including but not limited to Grupo Bimbo, ARYZTA, Lantmännen Unibake, Barilla, Associated British Foods (Allied Bakeries/AB Mauri), and the European Bakery Group.
-
Grupo Bimbo: Operates a pan‑European model that blends sliced and artisan formats, using acquisitive growth to consolidate shelf space and foodservice contracts. Their European footprint demonstrates how global logistics and procurement can be deployed to defend margin against commodity swings.
-
ARYZTA: A clear example of strategic capacity investment—its announced investment in a bun plant near Lisbon in early 2026 signals a targeted play into QSR and Iberian consolidation. The report includes an analysis of how such investments affect route‑to‑market and service-level economics in high‑volume contract channels.
-
Lantmännen Unibake: Expansion via acquisition into the bake‑off and frozen segments illustrates a hedge against in‑store labour scarcity and a move to scale products that fit retail convenience trends. We examine integration risks and synergies when global groups acquire regional artisan producers.
-
Barilla and Associated British Foods: These groups maintain broad retail portfolios and ingredient supply capabilities; their strategies show the value of vertical integration—both in price stability and in faster product innovation cycles.
-
European Bakery Group and other regional players: Smaller groups retain competitive advantage through local freshness, channel intimacy and tailored SKUs that large players find hard to replicate at margin. Our go‑to‑market playbooks show when to partner, acquire or compete with these specialists.
Strategic implications and recommended actions for 2026
-
Prioritise procurement resilience: Establish multi‑tier sourcing, increase indexed procurement contracts and model working capital impacts under 3–5 commodity scenarios. The report provides procurement templates and KPI dashboards that tie contract terms to margin outcomes.
-
Accelerate packaging redesign with compliance gateways: Treat PPWR readiness as a cross‑functional programme—product development, procurement and packaging engineering must align on materials choices, lead times and supplier qualification. We include a phased implementation schedule that minimises SKU disruption.
-
Reassess channel economics: Use our channel‑specific margin models to reallocate commercial investment—promotions, co‑op funds, and listing spend—to formats with durable margins in 2026 and 2027. The report quantifies break‑even points for bake‑off investments and frozen network roll‑outs.
-
Targeted M&A and partnerships: Seek tuck‑ins that bring capacity in high‑growth convenience segments or that close logistical gaps in key corridors. Our M&A screening matrix ranks targets by strategic fit, scale synergies and integration complexity.
-
Embed compliance and labelling as product differentiators: Turn regulatory changes into consumer‑facing advantages (e.g., transparent fortification messaging, clear allergen communication), rather than merely a cost of compliance. The report offers sample communication frameworks and costed labelling templates.
What’s inside the full PW Consulting report (practical modules)
-
Market sizing and forecast models (2020–2032) with downloadable model files and scenario toggles.
-
Channel and format playbooks—commercial and operational KPIs to run pilots, scale successful formats and shift trade investments.
-
Supply chain stress tests linking wheat price bands, freight and energy to margin scenarios and liquidity needs.
-
Regulatory impact matrix (PPWR, UK fortification, EU labelling) and an implementation checklist with cost ranges and timelines.
-
Competitive heatmaps and company profiles with M&A target screening and value capture cases.
-
Pricing and promotion optimization toolkit together with private‑label benchmarking and recommended tender structures for 2026 supply agreements.
-
Operational annexes—plant capex sizing, labour optimisation templates, and packaging sourcing playbooks (including recycled‑content supplier directory).
Methodology and data transparency
Our base‑year market sizing combines company reported revenues, trade statistics and primary interviews across retailers, manufacturers and distributors. Forecasts are produced using a bottom‑up SKU modelling approach cross‑checked with top‑down macro drivers and validated through scenario analysis. To preserve competitive sensitivity while enabling executive action, we provide the full dataset and replication models to subscribers; the public summary intentionally omits granular segment and regional tabulations to ensure integrity of commercial intelligence.
Next steps
For boards, executive teams and investors preparing 2026 plans, the full PW Consulting European Bread Market report is engineered to convert macro trends into executable initiatives. The public briefing above highlights the principal strategic takeaways—subscribe to access the complete datasets, downloadable forecasting models, and the tactical annexes described. PW Consulting stands ready to support bespoke scenario modelling, carve‑out due diligence or integration planning workshops to accelerate your 2026 decisions.
For detailed analysis of this topic, please visit the official page: European Bread Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com