

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Digital Ureteroscopes Market Set to Expand at a 6.5% CAGR

Digital Ureteroscopes Market — Strategic Imperatives for 2026: A PW Consulting Preview
Executive summary
The global digital ureteroscopes market has transitioned from a niche clinical tool into a strategically important segment of urology capital and consumables planning. After expanding from roughly USD 240 million in 2020 to an estimated USD 320 million in our 2025 base year, the market is forecast to grow at a compound annual growth rate (CAGR) of approximately 6.5% through 2032, when total revenues are projected to approach the half‑billion dollar mark. This steady expansion is being driven by converging forces: rising prevalence of stone disease, procedural migration to ambulatory settings, regulatory clarity for digital devices, and rapidly maturing single‑use technologies that change total cost of ownership considerations for hospitals and ASCs.
Digital Ureteroscopes Market
Why this report matters to executives in 2026
- Make capital allocation decisions with confidence: the report translates market momentum into targeted investment priorities across product platforms, manufacturing scale, and aftermarket service capability.
- Design differentiated go‑to‑market strategies: our customer segmentation and procurement insights reveal where clinical value, pricing flexibility, and service models create defensible positioning.
- De‑risk regulatory and reimbursement pathways: the report synthesizes 510(k) precedent, biocompatibility expectations, and CPT/payment dynamics to guide submission and evidence plans.
- Identify consolidation and partnership opportunities: a focused M&A playbook highlights targets and rationales for bolt‑on acquisitions and distribution alliances.
- Prepare for clinical adoption inflection points: scenario models quantify the implications of single‑use adoption, reusable lifecycle optimization, and new imaging/pressure‑monitoring features on buying decisions.
What the PW Consulting report delivers (practical, executable content)
- Actionable market forecast model (2026–2032) with scenario sensitivity to pricing, reimbursement, and adoption rates — delivered in spreadsheet format for executive planning.
- Procurement and TCO playbook comparing single‑use and reusable economics across typical hospital and ASC purchasing profiles, including repair and reprocessing assumptions.
- Regulatory roadmap and evidence plan templates for 510(k) submissions, incorporating performance, imaging, and biocompatibility endpoints.
- Commercial due diligence modules: competitor benchmarking, pricing ladder, channel analysis, and distribution cost models.
- Clinical adoption accelerator: recommended clinical study designs and key opinion leader engagement strategies to shorten time‑to‑adoption.
- M&A and partnership matrix identifying strategic fits by capability, region, and product architecture — prioritized by our proprietary strategic fit scoring.
- Customizable slide decks and executive summaries to inform Board discussions and investor briefings.
Competitive landscape snapshot — what leading suppliers are doing and what it means
The competitive field combines legacy endoscopy OEMs with newer single‑use specialists. Market concentration is meaningful: a handful of established players shape standards, channel relationships, and clinical perceptions, while agile entrants accelerate innovation on disposability, slim‑profile engineering, imaging, and systems integration.
Digital Ureteroscopes Market
- Boston Scientific Corporation — Leveraging its LithoVue Elite single‑use platform and recent FDA actions, Boston Scientific is pushing value through integrated procedure support features such as real‑time intrarenal pressure monitoring. For incumbents and new entrants alike, the key takeaway is that procedure‑level differentiation (e.g., pressure monitoring) shortens clinical adoption cycles when coupled with reimbursement clarity.
- KARL STORZ SE & Co. KG — With high‑resolution CMOS imaging and reusable platform strength, KARL STORZ positions toward hybrid strategies that retain reusable economics while modernizing visualization. Their playbook demonstrates how durable platforms can compete by emphasizing lifetime imaging quality and accessory ecosystems.
- Olympus Corporation — Olympus continues to stress durability and image fidelity for flexible ureteroscopy. Their strength in endoscopy services and dealer networks underlines the importance of post‑sale support as a competitive moat.
- Dornier MedTech — Recent U.S. product introductions reflect a focused single‑use strategy complemented by procedure accessories (e.g., ureteral access sheaths). Dornier’s launches highlight the commercial impact of bundling disposables with complementary devices to capture procedure economics.
- Ambu A/S — Ambu’s aScope 5 Uretero and system compatibility illustrate how platform interoperability (camera‑to‑processing unit) can accelerate adoption in facilities seeking turnkey single‑use workflows.
- OTU Medical Inc. — As a nimble innovator, OTU advances slim models and differentiated deflection options, forcing incumbents to respond on miniaturization and ergonomics. Smaller firms like OTU are often attractive targets for strategic buyers seeking technology fills.
- Richard Wolf GmbH & Stryker Corporation — Both emphasize imaging advances and portfolio breadth. Their market presence reinforces that integration into broader endoscopy suites and cross‑selling into urology portfolios remain high‑value routes to scale.
Collectively, these players illustrate two parallel competitive arcs: (1) platform incumbency that leverages durable assets, service, and imaging excellence; and (2) single‑use entrants that target infection control, streamlined workflows, and predictable per‑procedure economics. Winning strategies will combine clinical evidence, channel economics, and device lifecycle engineering.
Digital Ureteroscopes Market
Regulatory, reimbursement and clinical dynamics to watch
- Regulatory: Digital flexible ureteroscopes are regulated in the U.S. under Class II device pathways with 510(k) precedent. Manufacturers must demonstrate visualization performance, accessory compatibility, and biocompatibility — and recent clearances underscore that regulators expect mature bench and clinical evidence packages.
- Reimbursement: Established CPT codes for ureteroscopic stone management support both single‑use and reusable adoption models. Reimbursement landscapes are generally stable, but procurement teams will require robust per‑procedure economics to greenlight capital changes.
- Clinical: The single‑use value proposition — elimination of reprocessing and cross‑contamination risk — is resonating, particularly in high‑volume centers and ASCs. Conversely, reusable platforms remain attractive where repair networks, exchange programs, and image longevity reduce lifetime cost.
Key strategic recommendations for 2026 decision‑makers
- For OEMs considering product investment: prioritize modular imaging and sensor features (e.g., intrarenal pressure monitoring) that can be field‑upgraded; this protects installed bases and supports premium pricing.
- For single‑use specialists: build channel partnerships with distributers that have strong ASC and community hospital reach, and structure flexible commercial pilots that address procurement risk aversion.
- For hospital and ASC procurement leaders: adopt total cost of care frameworks that compare single‑use and reusable options across direct costs, downtime risk, and infection control externalities; engage clinicians with objective, site‑specific models from pilot data.
- For investors and PE sponsors: prioritize targets with proprietary manufacturing scale or unique consumable economics; accelerate diligence on repair networks and aftermarket revenue potential where reusable models persist.
- For regulators and payors: collaborate early with innovators on clinical endpoint selection to avoid late design modifications that delay market access.
How PW Consulting’s report helps translate insight into action
Our Digital Ureteroscopes Market report is structured as a practical toolkit, not an academic exercise. It combines primary interviews with clinicians and procurement officers, supplier financial and product intelligence, and a transparent forecasting engine you can adapt to your assumptions. Deliverables include a risk‑adjusted forecast model, playbooks for commercial pilots, evidence templates for regulatory submissions, and an M&A checklist that prioritizes value levers.
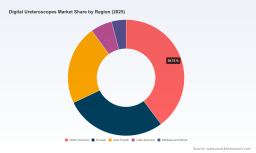
In keeping with our “preview” approach, this release outlines the strategic conclusions and operational guidance that will influence 2026 planning. Detailed tables — including supply chain cost models, region‑by‑region demand breakdowns, product‑type volumes, and granular price elasticities — are intentionally reserved for the full report to provide maximum commercial value to purchasers.
Next steps
PW Consulting’s Digital Ureteroscopes Market report is designed for CEOs, corporate strategy teams, commercial leaders, and investors who must make firm choices in 2026 about product roadmaps, go‑to‑market models, and M&A activity. To unlock the full dataset, customizable forecast workbook, and tactical playbooks, contact PW Consulting to obtain the complete report and licensing options for enterprise use.
For detailed analysis of this topic, please visit the official page: Digital Ureteroscopes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com