

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Healthy Lifestyle
PW Consulting: Nitinol Medical Device Market USD 1,850M in 2025, 8.5% CAGR to 2032
By pmarketresearch, 2026-07-30
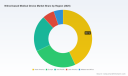
Nitinol-Based Medical Device Market — A Strategic Preview for 2026 Decision Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused preview of our new market research on Nitinol-based medical devices. This preview distills the strategic signals corporate leaders must act on in 2026 while deliberately withholding the granular segment tables and source-level splits that drive tactical execution. The full report contains those datasets and step-by-step playbooks; consider this a high-fidelity trailer designed to accelerate executive alignment and push high-priority decisions to the front of the boardroom agenda.
Nitinol-based Medical Device Market
Macro view: size, trajectory and what it implies
By our base year (2025) sizing the Nitinol-based medical device market reached approximately USD 1,850 Million. The market has expanded from approximately USD 1,250 Million in 2020 and is modeled to grow at a compound annual growth rate (CAGR) of roughly 8.5% through our forecast horizon, culminating in an implied market above USD 3.2 Billion by 2032. That trajectory is not merely arithmetic — it reflects accelerating device innovation (miniaturization, complex geometries), faster clinical adoption of minimally invasive interventions, and expanded use-cases across surgical specialties.
Nitinol-based Medical Device Market
For corporate leaders, two imperative conclusions follow. First, volume and addressable revenue are growing fast enough that first-mover investments in supply chain capacity, regulatory preparedness, and clinical evidence generation materially improve lifetime product economics. Second, rising demand exposes supply-side bottlenecks and cost inflation that will meaningfully affect margins unless addressed through deliberate sourcing and process strategies.
Nitinol-based Medical Device Market
Supply, cost and manufacturing dynamics — the levers that matter in 2026
- Raw material economics: Medical-grade Nitinol commands a substantial price premium compared with common implant alloys. Typical industry benchmarks show medical-grade Nitinol wire pricing materially higher than stainless alternatives — a delta that is a fundamental driver of device pricing and margin sensitivity. Expect procurement to be a primary battleground for margin protection.
- Capacity expansion and geographic diversification: Leading suppliers are scaling rapidly. Recent investment activity — including purpose-built Nitinol centers and equipment acquisitions — signals that suppliers are prioritizing higher throughput and tighter quality controls to serve OEMs expanding product portfolios. These developments create practical windows to re-negotiate supply agreements and lock in capacity for multi-year product ramps.
- Processing complexity and premium capabilities: Beyond raw wire, value is captured in advanced processes — ultra-fine drawing, precision tubing, shape-setting, micro-lumen creation, and post-processing surface treatments. Control over these capabilities materially shortens time-to-market and reduces technical risk on complex designs.
Regulatory and clinical risk: pressure points to prioritize
Regulatory scrutiny for nickel-containing alloys has increased. The U.S. FDA’s guidance on non-clinical assessment of devices containing Nitinol emphasizes corrosion potential and mechanical testing as core evaluation areas, raising the bar for pre-market technical packages. At the same time, there remains no universally adopted, dedicated standard for nickel ion release testing — a gap that creates uncertainty for both manufacturers and regulators and elevates the importance of defensible, internally consistent testing strategies.
From a strategic perspective, companies that proactively invest in robust, traceable corrosion and ion-release programs — and that can demonstrate mitigations (coatings, alternative surface finishes, process controls) — will differentiate in procurement, clinician adoption, and payer conversations. Firms that treat regulatory uncertainty as a fixed cost rather than a managed risk will see elevated launch timelines and capital erosion.
Competitive landscape — direction of travel, not the final score
The market exhibits measurable concentration at the top: the three largest players capture the majority of specialist supply, and the top five increase that dominance further. That level of concentration shapes bargaining dynamics between OEMs and suppliers and creates both strategic risks and consolidation opportunities for acquirers.
Key company archetypes and strategic behaviors we profile in the full research include:
- Precision melt and wire specialists expanding melt capacity and downstream quality programs — exemplified by companies investing heavily in melt throughput and supplier recognition awards that validate program maturity.
- Ultra-fine and medical-grade wire producers focusing on micron-scale capabilities to serve premium guidewire and stent designs.
- Contract manufacturers and component specialists acquiring niche capabilities (e.g., gun-drilling for microcatheters) to internalize high-risk processes and shorten supplier chains.
- Custom OEM partners that provide coil-forming, shape-setting, and device assembly services to accelerate OEM prototype-to-scale transitions.
We include company-level capability maps, investment timelines, and signal matrices in the full study. The preview purposefully omits granular market-share and segment share tables so that clients access the competitive scorecards directly from the source deliverable.
Recent strategic signals (illustrative)
- Facility expansions in lower-cost manufacturing regions that double local output capacity — a clear signal that suppliers are preparing for multi-year OEM demand ramps and that contract rates may moderate volatility if capacity is effectively absorbed.
- Targeted capability acquisitions focused on micro-manufacturing processes (precision lumen creation, advanced drilling) — indicating that contract manufacturers are moving up the value chain to lock in higher-margin work and reduce technical outsourcing risk.
- Regulatory recognition and supplier awards from leading OEMs — suggesting that supply reliability and validated process controls are increasingly decisive selection criteria.
What the full PW Consulting report delivers — practical, actionable content
Our objective is to deliver intelligence that translates directly into executable decisions. The full report contains:
- Model-backed market sizing and a 2020–2032 financial model with scenario toggles for demand, price inflation, and adoption curves.
- Segmentation taxonomies (product, application, geography) with downloadable data tables and interactive dashboards — note: this preview intentionally withholds the segment-level numbers that underpin go-to-market prioritization.
- Supplier capability and capacity maps, including plant-level assessments, lead-time sensitivity analysis, and a supplier risk heatmap tailored for OEM sourcing teams.
- Regulatory and clinical readiness playbooks: test matrices aligned to FDA expectations, sample clinical evidence pathways by indication, and defensive strategies for managing ion-release scrutiny.
- Pricing and margin sensitivity models that incorporate raw-material cost curves, processing premiums, and throughput ramps.
- M&A and partnership screening frameworks with prioritized targets, valuation approaches, and integration risk checklists for acquirers seeking to capture upstream or downstream value.
- Practical checklists, RFP templates, and contractual clauses designed to secure capacity, IP protection, and quality commitments from strategic suppliers.
How 2026 leaders should act — a short roadmap
- Lock capacity with the right contract structure: pursue hybrid contracts that combine committed volumes with volume-flex collars to protect against over- or under-utilization during product rollouts.
- Invest in disciplined regulatory evidence: begin corrosion and ion-release mitigation testing early and build it into design control so regulatory submissions are predictable and defensible.
- Prioritize capability ownership where it drives differentiation: if your IP depends on ultra-fine drawing or proprietary shape-setting, consider nearshoring or captive investments; otherwise, prefer strategic supplier partnerships with long-term capacity commitments.
- Design a pricing playbook that isolates raw material exposure: include indexed components in long-term supply agreements and periodic repricing triggers tied to observable Nitinol market indexes.
- Use M&A tactically to secure bottleneck capabilities: target suppliers with unique micro-manufacturing competencies or contract manufacturers that can move further up the value chain and provide margin capture.
Methodology and confidence — why this forecast matters
The forecast blends: (1) a bottoms-up capacity and demand build based on procedure volumes and device adoption curves; (2) primary interviews with OEM procurement, clinical leads, and supplier executives; (3) plant-level capacity and throughput modeling; and (4) a material-cost engine that simulates the interplay between alloy pricing, processing premiums, and scale economies. Scenario analyses are provided for conservative, base, and aggressive adoption pathways so executives can stress-test investment decisions against plausible market swings.
Final note — what you don’t see here (and why it’s important)
This editorial intentionally refrains from publishing the granular regional, product, and application splits that drive precise product prioritization and M&A valuation work. Those tables and the accompanying unit economics are included in the full PW Consulting deliverable because they are the tactical intelligence that competitors would exploit if freely distributed.
If you are preparing a 2026 strategic plan, supply agreement, capital allocation decision, or M&A screen in the Nitinol device space, this preview should have clarified the principal strategic levers and the critical timing for action. The complete report supplies the hard numbers, negotiation-ready models, and executable playbooks you will need to convert strategy into measurable outcomes.
Contact PW Consulting to request the full report package, walk-through briefings, and bespoke scenario modeling tailored to your portfolio and supply chain. In markets that move as fast and as technically as Nitinol-based devices, timing and information quality are the difference between value capture and value leakage.
For detailed analysis of this topic, please visit the official page: Nitinol-based Medical Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Intranasal Drug Delivery Devices Market to Hit USD 3,435.95M by 2032 — PW Consulting
By pmarketresearch, 2026-07-23
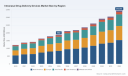
Intranasal Drug Delivery Devices Market: Strategic Imperatives for 2026
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused briefing on the intranasal drug delivery devices market — a fast-evolving subsector where device design, formulation innovation, regulatory clarity, and distribution strategy intersect to produce meaningful commercial outcomes. This preview synthesizes market momentum, regulatory context, competitive dynamics, and practical levers executives should prioritize in 2026. For clients seeking the full granular intelligence — regional splits, application-level volumes, pricing matrices, and vendor scorecards — our complete report contains the datasets and playbooks that operationalize these insights.
Intranasal Drug Delivery Devices Market
Market trajectory: a data-backed runway into 2032
Intranasal drug delivery devices have moved from niche rescue-and-symptom markets into a broader platform opportunity, driven by growth in biologics-compatible devices, nose-to-brain targeting, and renewed interest in non-invasive vaccine delivery. Our model — built on an audited historical series (2020–2025) and a scenario-driven forecast (2026–2032) with base year 2025 — shows clear acceleration. The market grew materially through the pandemic and post-pandemic years, reaching USD 1,882.0 Million in 2025. Under our central case (incorporating regulatory trends, product launches, and adoption curves), the market is projected to grow at a compound annual growth rate of approximately 8.98% over the forecast window, reaching roughly USD 3,435.95 Million by 2032.
Intranasal Drug Delivery Devices Market
Two practical takeaways for corporate planners: (1) the pace of device adoption creates a narrow window in 2026–2028 to secure preferred partnerships, intellectual property positions, and reimbursement pathways; (2) upside scenarios tied to successful nose-to-brain therapeutics and intranasal vaccines could materially re-rate capital allocation priorities, altering ROI timelines for both developers and device suppliers.
Intranasal Drug Delivery Devices Market
Why this research matters for 2026 decisions
- Capital allocation and portfolio prioritization: Investors and R&D leaders must decide whether to accelerate platform investments (e.g., dry-powder metered units, multi-dose pumps with biologic compatibility, atomizers for rapid systemic uptake) or to focus on iterative improvements to legacy pumps. Our report quantifies the trade-offs and break-even horizons under multiple adoption scenarios.
- Partnering and M&A targeting: Device-manufacturer capability (scale injection-mold tooling, sterile fill-finish integration, regulatory track record) is now a gating factor for rapid launches. The research delineates candidate profiles for licensing, OEM supply, and bolt-on acquisitions that shorten time-to-market.
- Regulatory and reimbursement preparedness: With multiple devices cleared by regulatory agencies and clear reimbursement pathways emerging for approved products in clinical settings, the tactical path to clearance and payer acceptance is operationally tractable — but requires specialized evidence-generation plans. Our analysis maps the most efficient clinical- to-commercial evidence sequences for a range of device/formulation combinations.
- Go-to-market and commercialization: Distribution strategies (hospital procurement, respiratory clinics, emergency medicine, retail pharmacy) vary by therapeutic use case. The report provides channel economics and launch playbooks that convert favorable clinical profile into durable market share.
Report deliverables — practical components
- Comprehensive market sizing and forecast model (historical 2020–2025; forecast 2026–2032) with scenario toggles.
- Technology landscape and device-architecture taxonomy (multi-dose, unit-dose, atomizers, dry powder platforms) with design constraints and formulation compatibility matrices.
- Regulatory pathway maps and a checklist for 510(k)/equivalence and device-combination product filings, plus payer-engagement templates targeted to the US and key global markets.
- Commercial playbooks: pricing frameworks, channel economics, adoption accelerators (KOL engagement, hospital formulary strategies, emergency services partnerships).
- Company dossiers and strategic assessments for tier-1 and tier-2 suppliers, including capability heatmaps and acquisition readiness analyses.
- Supply-chain risk assessment and mitigation options for critical components, secondary packaging, and sterile fill capacity.
Competitive landscape — positioning and strategic moves
This market is shaped by specialists that combine engineering precision with pharmaceutical compatibility. The competitive field ranges from global dispensing specialists to integrated CDMOs that can deliver API-to-device solutions. The following synthesis highlights the strategic posture of the most influential players and the tactical implications for potential partners and competitors.
- Aptar Pharma — A leader in comprehensive nasal spray platforms, Aptar’s portfolio spans single- and multi-dose solutions and has deep experience supporting clinical programs. Recent utilization of Aptar devices in Phase II clinical work underscores their attractiveness as an execution partner for programs seeking a proven device backbone and rapid clinical deployment. Strategic implication: pharmaceutical sponsors can de-risk clinical development timelines by favoring device partners with prior clinical track records.
- Teleflex — Known for mucosal atomization devices, Teleflex plays to the acute and emergency care segments where fast systemic uptake is required. Their products are familiar to emergency medicine procurement channels, making them a credible pathway for rescue therapies and emergency-use applications. Strategic implication: pairing atomizer technology with rescue therapeutics can accelerate acceptance in EMS and hospital formularies.
- Bespak — With a focus on combination product manufacturing and bespoke unit-dose solutions, Bespak is attractive for sponsors needing customization and regulatory partnership. Their emphasis on engineered combination products positions them well for controlled-release or specialty formulations. Strategic implication: consider Bespak for niche or differentiated dosing strategies where off-the-shelf components are insufficient.
- Silgan Dispensing — As a supplier of a broad range of nasal pumps and dispensing solutions, Silgan offers scale and packaging expertise, which supports high-volume consumer and retail-facing products. Strategic implication: large-scale launches targeting retail distribution will benefit from partners with robust packaging/assembly capability.
- Hovione — The CDMO model combined with device availability enables an integrated delivery from API through device formulation. Hovione’s recent announcement of a commercial intranasal dry powder platform signals strategic readiness to serve biologics and specialized formulations. Strategic implication: integrated CDMOs shorten development timelines and simplify regulatory dossiers for combination products.
- Kindeva Drug Delivery — With experience in nasal MDI and spray combination products, Kindeva sits at the intersection of respiratory delivery and device customization, useful for sponsors pursuing rapid systemic delivery with established inhalation know-how. Strategic implication: inhalation expertise translates into better aerosolization understanding for complex formulations.
- Nemera — Nemera’s focus on dry powder and nose-to-brain platforms, and recent partnership activity, position it as a strategic collaborator for companies pursuing CNS delivery via intranasal routes. Strategic implication: companies with CNS ambitions should assess Nemera for platform sharing or collaborative development.
- Aero Pump — Engineering-driven firm that offers precision pumps for specialized dosing needs. Their capabilities are relevant for sponsors requiring fine-grained dose control. Strategic implication: precision pump suppliers are critical when dose accuracy materially affects therapeutic index or regulatory acceptability.
Recent market signals that matter for 2026
- New clinical and commercial activity. Device suppliers are increasingly featured in clinical-stage programs and product launches — evidence that pharma sponsors prefer partners with documented device-clinical linkage.
- Platform commercialization. Several players announced platform availability for dry-powder and single-use devices in 2026, signaling rising commercial readiness for biologics and vaccines via the nasal route.
- Regulatory clarity. FDA activity has reaffirmed device classifications and approvals via 510(k) pathways for several intranasal devices. Updated labeling approvals for familiar rescue therapies (such as epinephrine and naloxone nasal configurations) are lowering the barrier for payers to accept nasal formulations in emergency care contexts.
- Reimbursement is becoming operational. In the U.S., reimbursement policies for approved intranasal products used in clinical settings are emerging, supporting the economics of adoption for hospital and emergency care pathways.
Strategic recommendations for executives — a 90‑day playbook
- Conduct a fast-track device partner audit — prioritize partners with clinical track records, regulatory dossiers, and scalable manufacturing.
- Develop a regulatory and evidence-generation roadmap that sequences device verification, biocompatibility, and targeted clinical endpoints to align with 510(k) or combination product requirements.
- Align commercial strategy to highest-probability channels in 2026 (emergency medicine, neurology clinics, respiratory care), and tailor value propositions for each channel.
- Model scenario-driven cashflows under conservative and upside adoption trajectories (our model provides ready-to-use templates).
- Prepare negotiation playbooks for OEM, licensing, or acquisition options to secure capacity and IP while minimizing dilutive risk.
Next step — get the granular intelligence
This briefing surfaces the structural drivers, competitive moves, and practical actions that matter for board-level decisions in 2026. For transaction teams, product leaders, and corporate strategists who require the underlying data and executable templates — including regional and application-level volumes, pricing sensitivities, supplier scorecards, and detailed channel economics — the full PW Consulting report delivers the confidential datasets and implementation playbooks needed to act decisively.
Contact PW Consulting to schedule a briefing where we will walk your team through the model, customize scenarios to your portfolio, and identify prioritized execution paths for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Intranasal Drug Delivery Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: E-Liquids Market to Reach USD 2.47B by 2032 at 12.58% CAGR
By pmarketresearch, 2026-07-23
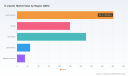
E‑Liquids Market: Strategic Brief for 2026 Decision‑Making
PW Consulting’s latest E‑Liquids Market study provides a forward‑looking intelligence package designed to convert macro momentum into executable strategy for 2026. Built on a historical series (2020–2025) and a detailed forecast window (2026–2032), the research quantifies a robust recovery and growth trajectory — driven by product innovation, channel shifts, and a rapidly evolving regulatory landscape. The market, which stood at a mid‑2020s base of approximately USD 1.125 billion (base year 2025), is projected to expand at a compound annual growth rate of 12.58% through the forecast period, effectively more than doubling by the end of the horizon. This brief explains why the report is a strategic asset for executive teams while intentionally holding back the granular segment tables that appear in the full study.
E-Liquids Market
Why this report matters for 2026
-
Timing: 2026 is a pivot year. Recent regulatory decisions and commercial investments have created a bifurcated landscape where authorized, compliant offerings can gain privileged access to the largest consumer channels — while non‑compliant players face compounding market risks.
E-Liquids Market -
Clarity on scale and trajectory: With a clear historical base and a transparent growth model, leadership teams can assess horizon planning (capacity, working capital, pricing) against a defensible market size and growth curve.
E-Liquids Market -
Practicality: The report translates macro projections into operational levers — from SKU rationalization to plant footprint decisions — giving C‑suite and business unit leaders immediate, actionable choices rather than abstract forecasts.
-
Risk quantification: Regulatory shocks and channel closures are modeled in multiple scenarios; this allows management to simulate downside impacts and construct hedges ahead of material events.
What the full study delivers (practical highlights)
-
Proprietary market model with historical reconciliation (2020–2025) and scenario‑based forecasts through 2032.
-
Regulatory impact module that overlays country‑level policy changes on demand and price models.
-
Commercial playbooks for top‑line growth: channel segmentation, pricing archetypes, promotion elasticity and D2C rollouts.
-
Supply‑chain and manufacturing toolkit: capacity vs. demand maps, quality and compliance gating, and an investment case for brownfield/greenfield expansions.
-
M&A and partnership screening: shortlist of target archetypes, valuation multipliers under different integration synergies, and post‑deal 100‑day playbook templates.
-
Brand and SKU optimization framework: margin‑weighted SKU pruning, innovation road‑maps for flavor and format, and packaging/cost trade‑offs.
-
Investor and board‑ready slide decks and financial models for scenario planning.
Macro picture: growth trajectory and market structure
The market’s trajectory from 2020 through 2025 establishes a consistent expansion pattern that accelerates into the forecast window. From a modest base in the early 2020s, the sector advances to a mid‑2020s market size near the USD 1.125 billion mark, then climbs steadily under our central scenario to reach an estimated USD 2.47 billion by 2032 — the result of ongoing product substitution, new adult user uptake in permitted channels, and premiumization across certain formats. The implied compound annual growth rate of 12.58% across the forecast period encapsulates both structural growth (category adoption and device upgrades) and cyclical drivers (regulatory approvals and trade‑channel reconfiguration).
Concentration metrics indicate a market where leading players command a dominant share footprint: the top three firms hold a majority share, while the top five collectively account for a very substantial proportion of market value. This structure creates both defensive moats for incumbents and white‑space opportunities for well‑capitalized challengers that can differentiate on regulatory compliance, brand trust, or supply reliability.
Competitive landscape: strategic implications for incumbents and challengers
The competitive field is heterogeneous and can be usefully viewed in three clusters.
-
Big tobacco and diversified incumbents (e.g., Philip Morris International, British American Tobacco, Imperial Brands, Japan Tobacco International): These companies bring scale in regulatory affairs, distribution, and capital. Their global footprint and access to regulated channels make them natural beneficiaries of favorable product authorizations. Strategic priorities should focus on portfolio rationalization (emphasize compliant SKUs), supply chain resilience, and targeted premiumization to protect margin as unit volumes scale.
-
Pod and device specialists (e.g., JUUL Labs, Logic Technology Development, NJOY): These players compete on device design, nicotine delivery characteristics, and rapid go‑to‑market of new formats. The path forward rests on achieving regulatory clearances in priority markets, proving robust youth‑access prevention measures, and forging retailer partnerships that favor tested, authorized SKUs.
-
OEM/ODM and independent e‑liquid manufacturers (e.g., Hangsen, Vape Base Ltd, Ruthless Vapor, Mister‑E‑Liquid): These suppliers are pivotal to capacity and white‑label growth. Their competitive levers are formulation agility, manufacturing quality (USP‑grade inputs), and global distribution to independent retail. For contract manufacturers, the fastest route to growth is investment in compliant production lines, traceability systems, and customer co‑development programs with leading device OEMs.
Recent commercial and regulatory developments underscore these dynamics. The U.S. Food and Drug Administration’s authorization waves (including the May 2026 authorization of several Glas ENDS products) are reshaping retail assortment rules and elevating authorized product economics. Simultaneously, the roll‑out of duties and tax regimes (e.g., the UK’s Vaping Products Duty applications opened in April 2026) and state‑level compliance regimes are changing price floors and operating compliance costs across markets. Retail‑level activity — exemplified by trade shows and bespoke category spaces for e‑liquids — suggests continued vibrancy in independent and specialty channels even as mainstream shelf access tightens for authorized SKUs only.
Regulatory and policy dynamics to prioritize
-
Authorization scarcity in the U.S.: As of mid‑2026, only a limited set of ENDS products are legally marketed. This scarcity creates a two‑tier channel system where authorized brands can command better shelf access and lower trade resistance.
-
New tax instruments and duties: Emerging excise regimes will compress margins for lower‑end SKUs and create incentives for product reformulation or premiumization.
-
State and provincial compliance: Tighter manufacturer certification rules and directory requirements at sub‑national levels increase operating overhead for smaller producers and create an advantage for firms with compliance infrastructure.
-
Retail and channel compliance: Retailers are tightening sourcing controls — preference is given to products with clear regulatory pathways and documented quality systems.
Immediate strategic imperatives for 2026
-
Prioritize regulatory gating: Map your SKU set to regulatory pathways now. Accelerate clinical, toxicology and youth‑access mitigation evidence where required to pursue authorization slots.
-
Right‑size manufacturing: Use the report’s capacity model to decide whether to expand, outsource, or form tolling partnerships. Avoid capex commitment until you reconcile authorization probabilities across priority markets.
-
Portfolio triage and premiumization: Reallocate SKU and marketing dollars toward formats and flavors that align with permitted channels while pruning low‑margin assortments.
-
Channel hedging: Grow authorized direct channels (D2C with strong age‑verification) and maintain strategic relationships with specialty retail that can support niche innovation.
-
M&A and partnerships: Seek bolt‑on targets that bring capacity, compliance expertise, or access to authorized channels. Use the study’s acquisition filters to prioritize targets by integration complexity and payback horizon.
-
Operationalize compliance: Invest in batch traceability, supplier audits, and product stewardship programs to lower regulatory and reputational risk.
How to use the full PW Consulting report
This brief outlines the strategic contours you need to act now. The full report contains the missing detail critical to execution: granular regional demand curves, flavor and format segmentation, channel‑level price bands, elasticity matrices, supplier cost curves, and a prioritized list of commercially viable M&A targets. It also includes playbooks for market entry, a regulatory probability matrix, and downloadable financial models patched to our central and alternate scenarios.
For teams designing 2026 capital plans, go‑to‑market roadmaps, or M&A pipelines, the study serves as both a diagnostic and a transaction tool. PW Consulting stands ready to deliver tailored workshops that convert the report’s insights into a 90‑day action plan aligned to your P&L and balance sheet realities.
To access the complete segmentation tables, scenario outputs and company‑level benchmarking that underpin the strategic recommendations in this brief, visit the research page linked from PW Consulting’s E‑Liquids Market offering. The full dataset is where the operational levers live — and where your execution roadmap begins.
For detailed analysis of this topic, please visit the official page: E-Liquids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Paraffin Wax Market Set to Expand at 5.6% CAGR Through 2032
By pmarketresearch, 2026-07-23
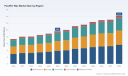
Paraffin Wax Market 2026: Strategic Primer for C-Suites and Procurement Leaders
As PW Consulting’s senior strategy team and lead industry analysts, we present an executive primer that frames why paraffin wax — a commodity often taken for granted — is now a strategic input for 2026 planning. Grounded in our latest market study (base year 2025), this overview synthesizes the macro trajectory (a market that expanded from roughly USD 7.35 billion in 2020 to USD 9.65 billion in 2025 and is projected to exceed USD 14 billion by 2032 at a 5.6% CAGR) with practical implications for sourcing, product development, regulatory compliance, and M&A. Consider this a high-resolution trailer: it surfaces the insights that matter for near-term decisions while directing practitioners to the full report for detailed segment-level intelligence and executable templates.
Paraffin Wax Market
Why Paraffin Wax Matters Strategically in 2026
-
From consumables for pathology labs and medical-device manufacturing to industrial packaging and consumer candles, paraffin wax sits at the intersection of regulated medical demand and high-volume commodity markets. That duality creates distinct strategic pressures: requirements for traceability and quality on one hand, and cost, scale and carbon footprint on the other.
Paraffin Wax Market -
Capital investments and capacity upgrades announced across the refining and chemicals sector in 2024–2026 (notably by major refiners) signal a supply-side rebalancing. These moves are rapidly changing vendor risk profiles and regional supply dynamics, making 2026 a pivot year for buyers to reassess supplier footprint and contractual terms.
Paraffin Wax Market -
Regulatory clarity (for example, occupational treatment classifications and medical-device standards) and the technical properties of medical-grade paraffin — high purity, stable melt points and controlled permeability — increasingly dictate procurement specifications and product roadmaps for manufacturers and laboratories.
Market Dynamics — What to Watch
-
Demand composition remains diversified across industrial, consumer, and medical applications. Each use case imposes different cost tolerance and specification needs; medical and histology applications place a premium on certification, traceability and contaminant control, which materially affects supplier selection and total landed cost.
-
Supply-side modernization and specialty wax product launches are creating adjacent opportunities — micronized and low-carbon waxes designed for packaging and medical-device use are already displacing legacy grades in some applications. Procurement teams should model substitution scenarios and quantify value capture from product premiumization versus volume discounts.
-
Market concentration is modest: the leading three suppliers do not dominate the landscape. This fragmentation implies both procurement upside (competitive sourcing, regional arbitrage) and strategic consolidation opportunity (scale-driven margin capture for forward-integrated players).
-
Compliance and operating practice impose recurring costs. For example, facilities using paraffin wax baths for therapeutic or pathology applications must maintain sanitization protocols, disposable liners, and scheduled wax replacement to meet clinical hygiene standards — a line-item that influences cost-per-use calculations more than unit price alone.
Competitive Landscape — Who’s Shaping the Market
The sector is populated by specialized medical-grade suppliers, laboratory consumables manufacturers, and diversified petrochemical players. Notable participants include manufacturers of professional paraffin bath systems and refill beads, suppliers of histology-grade consumables, and regional producers serving hospital and pathology lab networks. Their strategic postures break down as follows:
-
Specialist medical-device suppliers focus on productized systems and regulated consumables. Their competitive advantage lies in device-certification, bundled consumables, and relationships with clinical buyers. Expect continued emphasis on ISO quality systems and FDA-classified device pathways where applicable.
-
Histology and laboratory consumable companies compete on purity specifications, packaging formats (pellets, blocks, beads), and logistical reliability. These firms often win on consistency and technical support rather than lowest-price bids.
-
Large refiners and chemical companies are pursuing specialty wax capacity and differentiated micronized products. Their scale enables investment in low-carbon product lines, but they must stitch commercial credibility with lab-grade traceability to penetrate medical niches.
Recent commercial and operational developments crystallize these strategic themes: targeted product deliveries to pathology clients, refinery modernizations to increase specialty wax output, new micronized wax launches aimed at low-carbon packaging and devices, and catalog updates that align paraffin bath systems with ISO and FDA requirements. These events are not isolated — they reflect a coordinated shift toward higher-spec, higher-value paraffin products.
Implications for 2026 Corporate Strategy
Whether you lead procurement for a pathology lab network, a medical-device OEM, a packaging company, or an industrial candle manufacturer, 2026 choices will materially affect margin, service continuity and regulatory exposure. We recommend a six-point action agenda:
-
Supply-Base Restructuring: Reevaluate supplier scorecards to integrate quality certifications, regional capacity resilience, and demonstrable low-carbon credentials. Given market fragmentation, structured dual-sourcing or multi-tiered contracts can reduce risk without sacrificing price.
-
Contract Design & Flexibility: Shift to outcome-based SLAs that include quality/traceability KPIs and volume-adjusted pricing bands. Include clauses for capacity escalation and product substitution to mitigate feedstock volatility.
-
Product Differentiation & Premiumization: For manufacturers, invest in product lines that leverage medical-grade attributes (e.g., controlled melting behavior, permeability) and sustainability claims. These features command premium pricing in regulated channels.
-
Regulatory and Quality Investment: Prioritize ISO 13485 alignment and traceability systems if you supply medical or histology channels. The incremental compliance cost is often outweighed by access to higher-margin institutional contracts.
-
Strategic M&A and Partnerships: Consider bolt-ons that add lab-grade formulation capability, or JV arrangements with refiners improving specialty-wax output. With the market’s current concentration profile, disciplined consolidation can unlock synergies.
-
Sustainability & Total Cost of Ownership: Quantify life-cycle impacts and develop procurement metrics that capture sanitization, disposable liner usage, and wax replacement frequency — these operational costs can exceed raw-material spend in medical use-cases.
What the Full PW Consulting Report Provides (Actionable, Not Academic)
-
Transparent market sizing and top-line forecasts (2020–2032) with scenario modelling for feedstock shocks and regulatory shifts.
-
Supplier benchmarking templates and procurement scorecards that weigh quality, traceability, capacity, and sustainability attributes.
-
Commercial playbooks — RFP templates, contract clause libraries, and negotiation levers optimized for both commodity and regulated purchases.
-
Regulatory matrix and compliance checklists tailored to medical-device, pathology lab, and therapeutic bath applications.
-
Investment appraisals and M&A screeners identifying consolidation candidates and partnership archetypes across the value chain.
-
Operational dashboards for production, sanitization and inventory that translate product specifications into cost-per-use metrics for clinical environments.
To preserve the strategic advantage of our clients, the illustrative trailer above intentionally omits granular segment and regional splits. The full research package includes those datasets, interactive scenario tools, and supplier level intelligence that finance, procurement and product teams require to convert insight into action.
Closing — How to Use This Primer Today
Use this primer to: (1) stress-test your 2026 procurement and product plans against the factors highlighted here; (2) prioritize quick-win supplier and contract interventions that improve service and reduce regulatory risk; and (3) evaluate longer-horizon investments that capture premiumization and sustainability upside. The paraffin wax market is no longer a background input; it is a strategic lever. Teams that align procurement, R&D and regulatory workstreams in 2026 will turn commodity exposure into a competitive axis.
Contact PW Consulting to access the full Paraffin Wax Market study with its data appendices, supplier dossiers, and executable playbooks — the tools your leadership team needs to make confident, measurable decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Paraffin Wax Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wood Pallet Market to Reach USD 19.99B by 2032 at 4.58% CAGR
By pmarketresearch, 2026-07-23
Wood Pallet Market: Strategic Imperatives for 2026 — PW Consulting Preview
As corporate leaders plan capital allocation, supply-chain reconfiguration, and sustainability commitments for 2026, the wood pallet market deserves renewed strategic attention. PW Consulting’s forthcoming in-depth study — summarized here as a strategic preview — translates observed market forces into decision-grade insights. The global wood pallet market has expanded consistently from an estimated USD 11.7 billion in 2020 to roughly USD 14.6 billion in 2025, and our base-case forecast points to nearly USD 20.0 billion by 2032, representing a compound annual growth rate of 4.58% over the forecast horizon. That steady expansion, combined with evolving regulatory, material and customer dynamics, makes 2026 a pivotal year for commercial and operational choices across manufacturing, logistics, retail and packaging ecosystems.
Wood Pallet Market
Why this market matters for 2026 decision-makers
-
Operational leverage in logistics: Pallets are a recurring consumable and operational linchpin. Even modest improvements in pallet selection, repair strategy, or circularity can yield material reductions in freight damage, handling time and total landed cost across high-volume distribution networks.
Wood Pallet Market -
Regulatory and market visibility: New regulatory frameworks and export phytosanitary standards are raising due-diligence and traceability requirements. These shifts will change procurement specifications and supplier evaluation criteria for many corporate buyers in 2026.
Wood Pallet Market -
Consolidation and supplier power: Market concentration metrics indicate a moderately consolidated landscape (CR3 ~42%, CR5 ~55%), creating both risks and opportunities for buyers and potential entrants. Strategic partnerships, selective vertical integration and bolt-on M&A merit close consideration.
-
Sustainability and brand exposure: As retailers and manufacturers make public commitments to deforestation-free supply chains and circular packaging, pallet sourcing choices are increasingly visible and auditable — influencing both procurement and sustainability reporting.
Trajectory and structural drivers — a concise synthesis
The market’s 2020–2025 growth profile reflects a combination of steady replacement demand, expanding e-commerce logistics, increasing reuse/remanufacture activity, and periodic capacity adjustments in lumber supply chains. Looking forward from the 2025 base year, our model projects mid-single-digit annual growth under the base case, with upside tied to faster e-commerce penetration and broader adoption of engineered wood products, and downside linked to sustained timber price shocks or large-scale modal shifts to reusable plastic pallets in specific verticals.
Three structural drivers deserve particular attention in 2026:
-
Regulatory tightening on origin and phytosanitary compliance: The introduction of due-diligence requirements for wood products in key trading blocs and the continuing enforcement of ISPM-15 for exports will require buyers to enhance documentation, supplier audits and logistics processes to avoid shipment delays and non-compliance penalties.
-
Raw material and circularity economics: Softwood remains the dominant raw material input across many markets; efficient lumber sourcing, remanufacture programs, and repair networks materially affect unit economics. Firms capable of integrating circular supply loops — collection, repair, and redeployment — will extract margin and resilience benefits.
-
Service and value-add differentiation: Beyond commoditized new pallet supply, market-leading players are capturing value through engineered designs, ISPM-15 certified export solutions, custom crating and logistics services. Buyers should evaluate suppliers on breadth of capabilities and the ability to meet multi-modal and export requirements.
Competitive landscape — who moves markets in 2026
The sector blends regional incumbents with national-scale manufacturers and specialized recyclers. Several firms emerge as anchor players through scale, distribution networks and service scope:
-
PalletOne Inc. (UFP Industries’ flagship pallet arm) — A large-scale new-pallet manufacturer with integrated offerings across new pallets, recycled solutions, crate fabrication and repair services. Recent bolt-on acquisitions have expanded its geographic reach and enhanced national account capabilities.
-
Millwood Inc. — A high-volume processor with an established national footprint that emphasizes recycled pallet flows and engineered manufacturing processes to serve large supply-chain buyers.
-
Falkenhahn AG and PGS Group — European players offering EPAL-compliant and custom wooden pallet solutions, with product lines oriented toward industrial specifications and cross-border commercial flows.
-
Passionate regional specialists — Challenger Pallet, Wooden Pallets LTD, Troymill Wood Products and others — that compete on specialization, export compliance (e.g., ISPM-15 heat-treated pallets), local service responsiveness and sustainability credentials.
-
Emerging sustainability leaders — Certain manufacturers are differentiating by integrating reforestation partnerships, zero-waste manufacturing certifications and ISO-style traceability frameworks that appeal to high-visibility retail and food & beverage customers.
These profiles are intentionally high level. The full report includes detailed supplier scorecards, capacity maps and a quantified M&A opportunity matrix for buyers and investors.
Regulatory and operational shocks to watch in 2026
-
Due-diligence obligations: New deforestation-related regulations in key markets will increase documentation burdens for wood-based packaging. Companies should validate supplier chains, institute audit-ready traceability and prepare for staggered compliance timelines across large and small companies.
-
Phytosanitary export compliance: ISPM-15 requirements remain non-negotiable for global shipments. Exporters must ensure heat-treatment certification and stamping operations are integrated in procurement and outbound logistics to avoid costly detentions.
-
Raw material concentration and price volatility: Timber markets can exhibit short-run shocks. Firms with flexible procurement, lumber hedging strategies or vertical linkages into sawmilling/processing will be more insulated against cost pass-through pressures.
What the PW Consulting report delivers — practical, decision-ready tools
Our full market study is structured to move executives from context to action. Key deliverables include:
-
A calibrated demand-supply model (2020–2032) with scenario toggles for e-commerce growth, reuse rates and material substitution — enabling P&L and working-capital stress tests.
-
Competitive scorecards and a capacity map that identify strategic suppliers by capability (new, recycled, ISPM-15, engineered solutions) and assess counterparty risk across procurement tiers.
-
Regulatory impact playbook that translates EPR-type initiatives and deforestation due-diligence into procurement clauses, audit templates and internal operating procedures.
-
M&A and partnership pipeline — a prioritized list of targets and collaboration archetypes for firms seeking scale, geographic expansion or circularity capabilities, with transaction hypersensitivities and integration flags.
-
Unit-cost curves, repair-versus-replace calculators and life-cycle carbon estimates to support make-or-buy and sustainability investment choices.
-
Commercial go-to-market playbooks for selling into retail, manufacturing and 3PL segments — including sample RFP language and total-cost-of-ownership (TCO) templates.
-
Operational checklists for export-ready pallet flows and ISPM-15 compliance, and an executive dashboard for quarterly monitoring of lead indicators.
These tools are designed so procurement, supply-chain and sustainability teams can operationalize strategic shifts within a 90–180 day execution window.
Actionable implications for 2026 planning cycles
-
Prioritize traceability investments now. Firms that embed audit-ready provenance controls into their sourcing will avoid last-minute compliance friction as regulations proliferate and enforcement increases.
-
Build flexible supply networks. Adopt a multi-supplier strategy that balances scale (for cost) and regional specialist partners (for export and compliance needs). Consider term-buy commitments to secure lumber flows in tight markets.
-
Accelerate circular programs where economics support them. Investment in collection, repair and remanufacturing can shorten lead times and lower variable cost per trip for high-turn distribution centers.
-
Re-evaluate product portfolios. Identify where engineered or heat-treated pallet solutions can unlock export revenue or reduce damage rates, and where lightweight or modular designs bring logistic savings.
-
Scan the consolidation landscape. Given mid-level concentration, 2026 is a window for strategic bolt-ons — acquiring local repair networks or niche export-capable producers can rapidly expand capabilities and margin profile.
Where this preview leaves the reader
This preview highlights the macro trajectory, critical forces and the practical levers executives should consider for 2026. To preserve competitive integrity for clients and to align with our “trailer” approach, we have selectively withheld the granular segment-level splits and proprietary scenario outputs from this summary. The full PW Consulting Wood Pallet Market report provides the detailed regional, type and application breakdowns, the complete financial model with scenario toggles, supplier-level economics and transaction-ready annexes that procurement teams can use directly in negotiations.
Next steps — how to use our findings
-
Procurement leaders: request the supplier scorecard annex and the TCO calculators to run your 2026 budgets and master-service agreements.
-
Operations chiefs: adopt the export compliance checklist and repair-vs-replace calculator to optimize depot operations and outbound compliance flows.
-
Corporate strategy and M&A teams: review the prioritized M&A pipeline and integration flags to identify near-term targets that accelerate capability-building.
For access to the full dataset, detailed segment reporting and bespoke advisory engagements, please consult the full PW Consulting Wood Pallet Market study. The complete report contains the quantitative detail and execution playbooks required to transform the strategic imperatives above into 2026 action plans.
For detailed analysis of this topic, please visit the official page: Wood Pallet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luxury Sunglasses Market to Hit $19.78B by 2032 at 4.59% CAGR
By pmarketresearch, 2026-07-23
Luxury Sunglasses Market — Strategic Outlook for 2026 Decision-Making
As companies prepare budgets, M&A roadmaps, product pipelines, and go-to-market plays for 2026, the luxury sunglasses market presents a balanced mix of steady growth, strategic consolidation, and disruptive technological and regulatory pressures. This briefing—drawn from PW Consulting’s comprehensive market study, base year 2025, historical window 2020–2025 and forecast horizon 2026–2032—highlights the high-level implications executives must weigh now. The full report contains the granular charts, segment tables, and scenario spreadsheets that underpin the conclusions summarized below.
Luxury Sunglasses Market
Market trajectory and what it means for 2026 plans
Across the five-year historical period through 2025 the global luxury sunglasses market expanded consistently, reaching a market size of USD 14.45 Billion in the base year. Our forecast window (2026–2032) projects continuation of that growth at a compound annual growth rate (CAGR) of 4.59%, bringing the market to roughly USD 19.78 Billion by 2032 under the baseline scenario.
Luxury Sunglasses Market
For corporate planners, the takeaway is twofold. First, the market is large and predictable enough to justify multi-year investments in brand-building, premium product lines, and supply-chain optimization. Second, growth is not explosive; it rewards disciplined capital allocation and strategies that extract margin through product differentiation, channel control, and cost containment rather than betting on blue‑sky volume expansion alone.
Luxury Sunglasses Market
Competitive structure and strategic consequences
The competitive landscape shows meaningful concentration among leading players, with the top three and top five firms controlling significant shares of the market (CR3 and CR5 at 48.5% and 65.2% respectively). That structure creates both constraints and opportunities for new entrants and incumbents:
- Incumbents benefit from scale in licensing, global distribution, and brand equity—advantages that translate into negotiating power with retailers, preferred access to premium materials, and higher tolerance for short-term price volatility.
- Mid-sized and niche firms can still win by specializing (material craftsmanship, regional cultural resonance, limited-edition drops) and by owning superior DTC experiences and creative collaborations.
Key firms to watch include EssilorLuxottica, the group whose brand and licensing portfolio covers household names and designer collaborations; Italian manufacturers such as Marcolin, De Rigo and Safilo, which combine manufacturing heritage with global license partnerships; and artisanal or boutique players like Garrett Leight and Oliver Peoples that trade on craft, provenance, and selective distribution. Each archetype implies different strategic moves for competitors and partners: from defensive licensing and scale investments to targeted partnerships, white-label production agreements, or acquisitions to gain heritage credentials.
Notable corporate moves and regulatory noise shaping 2026
Recent developments through mid‑2026 emphasize three themes that should be central to corporate strategy next year: premiumization via designer partnerships, technology integration, and tariff-driven cost pressure.
- Design & licensing: Major players continue to lock in long-term licensing deals and capsule collections with luxury houses, reinforcing premium positioning and customer lifetime value. Such partnerships remain high-return plays for companies that can manage production quality and channel control.
- Technology & product innovation: The incorporation of smart/AI-enabled features into eyewear is transitioning from novelty to a product line consideration for mainstream luxury brands. Early waves of hybrid offerings (optical prescription frames with digital features) create adjacent revenue pools and new after-sale service models.
- Tariffs & trade policy: Elevated import duties on optical products—together with episodic policy pauses and unpredictable reciprocal measures—have materially affected landed costs and pricing strategies. Some legacy producers have already moved to mitigate exposure through price increases and supplier diversification.
These dynamics are exemplified by public actions in the market: multi-year licensing renewals, high-profile capsule collections, expansions of AI/glasses portfolios targeted at prescription wearers, and price adjustments implemented to offset tariff impacts. Executives must plan for continued regulatory volatility while exploiting design and tech as sources of differentiation.
What the PW Consulting report offers (practical content)
Our full study was designed as a decision-making toolkit for 2026. It blends rigorous quantitative forecasts with practical, executable guidance:
- Market sizing and validated forecast models across multiple scenarios (baseline, downside, upside) calibrated to tariff, channel, and macroeconomic permutations;
- Channel economics and margin waterfall analyses for wholesale, retail, and direct-to-consumer (DTC) models, identifying where margin can be recovered or enhanced;
- Supply-chain stress tests and sourcing playbooks—evaluating nearshoring, dual-sourcing, and inventory strategies to manage high-duty exposure;
- Consumer segmentation and purchase-motive matrices that translate psychographics into product and price strategies (note: the report contains the segment-level shares and elasticity estimates omitted from this preview to preserve commercial value);
- Product roadmap guidance, including how to integrate smart features without cannibalizing classic premium lines, and material-sourcing recommendations for sustainable, high-margin offerings;
- M&A and partnership screeners—financial thresholds and cultural fit heuristics for deals that accelerate scale, augment brand portfolios, or secure manufacturing competence;
- Operational playbooks for retail footprint optimization and omnichannel orchestration, with KPIs, pilot templates, and a 12–24 month rollout calendar;
- Primary interview summaries and supplier scorecards that validate costs, lead times, and quality differentials used in our forecast models.
We deliberately present the high-level recommendations here while retaining the full tables and sensitivities behind the paywall so decision-makers can test moves against their unique P&L assumptions.
Strategic priorities for 2026
Based on the intersection of steady CAGR, market concentration, product innovation, and tariff risk, we advise leaders to prioritize six actions in 2026:
- Institute a tariff-response program: model landed-cost scenarios, negotiate contractual protections with suppliers, and implement staged price actions tied to clear cost triggers;
- Double down on premiumization where your brand equity supports it—limited editions, luxury licenses, and craft-backed product stories enhance margins and reduce price elasticity;
- Accelerate selective tech integration: pilot AI/smart eyewear in core markets with controlled production runs and service bundles to evaluate willingness-to-pay and brand fit;
- Optimize omnichannel economics by reallocating capex to high-ROI DTC experiences and using wholesale selectively as a distribution amplifier rather than a margin sink;
- Pursue bolt-on M&A or licensing that fills capability gaps—manufacturing, optical tech, or prestige labels—while maintaining strict integration criteria and return hurdles; and
- Embed sustainability and traceability into premium narratives: consumers of luxury are increasingly sensitive to provenance, which can justify price premiums and reduce reputational risk.
Risks, sensitivities, and scenario levers
Although growth is steady, the luxury sunglasses market is sensitive to a limited set of high-impact variables:
- Trade policy volatility—sudden tariff adjustments or retaliatory measures can compress margins quickly; companies should hold contingency pricing and supply plans ready;
- Consumer discretionary cycles—premium eyewear sits in discretionary spend pockets and will bend with broader luxury consumption trends;
- Platform & distribution disruption—shifts in social commerce, resale channels, and vertical DTC brands can alter competitive placement rapidly;
- Technological missteps—over-investing in tech-enabled eyewear before clear consumer acceptance may dilute core brand equity and tie up capital.
Our scenario analysis—available in the full report—quantifies the P&L implications of these levers and prescribes triggering conditions for defensive vs. offensive moves.
How to use this intelligence in boardroom decisions
Executives should use the study to inform four board-level decisions in 2026: capital allocation (where to invest vs. conserve), pricing strategy (dynamic vs. fixed), channel mix (which channels to double down on), and inorganic growth (targets and timing). The report’s models allow custom inputs so leadership teams can run their own sensitivity analyses and produce credible, data-backed plans for investors and lenders.
Next steps
This preview demonstrates the depth and orientation of PW Consulting’s Luxury Sunglasses Market study: rigorous modeling, actionable playbooks, and scenario-tested strategic recommendations. To access the full dataset, segmentation tables, and our proprietary forecast workbook—including the detailed sensitivities on tariffs, channels, and consumer segments—please consult the report landing page or contact your PW Consulting representative. The full intelligence package is designed to be plug-and-play for 2026 planning cycles and to support rapid decision-making under uncertainty.
In markets where growth is steady but risks are concentrated, strategic clarity wins. The decisions companies take in 2026 about sourcing, partnerships, and product architecture will determine who captures the next wave of premium margin expansion in the luxury sunglasses category.
For detailed analysis of this topic, please visit the official page: Luxury Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Motorcycle Gear Market to Expand at 5.6% CAGR Through 2032
By pmarketresearch, 2026-07-23
Motorcycle Gear Market 2026: Strategic Imperatives from PW Consulting
As companies plan their strategic moves for 2026, the motorcycle gear market presents a study in contrasts: a clear recovery curve after a multi-year contraction, accelerating technological and sustainability-driven product cycles, and a regulatory environment that has grown both more prescriptive and more consequential. This introduction summarizes why PW Consulting’s new Motorcycle Gear Market research report is indispensable for executives who must convert market signals into defensible commercial action in 2026.
Motorcycle Gear Market
Why this timing matters
The market’s macro story is straightforward but actionable. After peaking in the early 2020s, total industry revenues contracted through 2025 — with the PW Consulting base year set at 2025 — creating compressed margins and clearance-driven inventories across multiple product categories. Our market sizing shows the overall market moving from a pre-contraction level in 2020 to a lower trough in 2025, before an inflection beginning in 2026 and a steady climb across our forecast window to 2032. The forecasted compound annual growth rate for the 2026–2032 period is 5.6% (USD, Million), and the market is projected to return to and exceed its earlier scale by the end of the forecast period.
Motorcycle Gear Market
For leadership teams, these dynamics mean 2026 is the year to shift from defensive tactics (inventory reduction, promotional discounting) to growth positioning—if you can mobilize clean capital, upgrade compliance processes, and accelerate product differentiation without re-creating legacy cost structures.
Motorcycle Gear Market
What PW Consulting’s study delivers (practical components)
- Granular market sizing and a rigorously validated forecast framework (historical 2020–2025; forecast 2026–2032) expressed in USD Million, with a clear explanation of assumptions and sensitivity cases.
- Competitive landscaping that goes beyond logos — we analyze capability maps, product roadmaps, channel footprints, and relative strength in key go-to-market motions.
- Regulatory and product-safety risk matrices, including recall case studies and compliance gap analysis specifically tailored for North American FMVSS and EU homologation variants.
- Supplier and cost-stack benchmarking covering raw materials (including emerging recycled membranes and biobased textiles), manufacturing labor, and logistics — with levers for near-term margin recovery.
- Commercial playbooks: launch sequencing for premium versus value tiers, omnichannel distribution optimization, pricing elasticity models, and merchandising strategies for core SKUs.
- M&A and partnership scoping: target profiles, accretion/dilution scenarios, and integration checklists for bolt-on capabilities (e.g., protective tech, sustainable textiles, digital services).
- Scenario planning templates for demand shocks, regulatory escalations, and rapid cost inflation — ready to be adapted into a 2026 board pack.
Market dynamics: what’s driving the next phase
- Safety regulation and enforcement : Recent high-profile recalls have re-centered safety as a non-negotiable commercial and reputational risk. Regulatory activity in early 2026 underlines the need for robust product testing, traceability, and post-market surveillance in supplier contracts.
- Product innovation & materials : Technical advances — from integrated armor packages to weather-proofing systems and recycled technical membranes — are accelerating product life cycles. Consumers increasingly pay a premium for demonstrable performance and sustainability credentials.
- Channel maturation : Omnichannel retailing is now table stakes. Brands that blend experiential retail, direct-to-consumer digital engagement, and strategically layered wholesale partnerships are gaining disproportionate share of wallet.
- Concentration and competitive intensity : The market shows moderate concentration at the top: the largest three players control a meaningful plurality of sales, and the top five extend that influence further. This concentration shapes distribution access, supplier bargaining, and brand citation in tiered channel relationships.
- Regional recovery and premiumization : After the contraction into 2025, recovery is heterogeneous by region and use-case, but premium technical and protection-led products consistently outperformed undifferentiated commodity items during early signs of demand renewal.
Competitive landscape — what to watch from leading players
The competitive field blends legacy European performance brands, North American technical specialists, and rising regional players. Our report profiles each major participant with emphasis on their product architecture, manufacturing levers, channel behavior, and strategic intent. A few illustrative insights:
- Alpinestars — Longstanding strength in racing-grade performance products and a clear playbook for translating motorsport credibility into consumer premiumization. Watch their product modularity and licensing moves.
- Dainese — Deeply associated with protective technology and rider safety; their October 2025 launch of eco-friendly lines signals an aggressive dual-pronged approach: safety as baseline, sustainability as premium differentiator.
- REV'IT! — A European technical touring and urban specialist that competes on fit, weatherproofing, and integrated feature sets; they are important to benchmark for functional design and mid-premium channel partnerships.
- Fox Racing — Dominant MX/off-road position and a youth-oriented branding engine; their distribution networks and licensing deals create durable access to the next generation of riders.
- Klim — Notable for adventure/touring systems and material innovation; their EICMA 2025 showcase of integrated armor and updated GORE‑TEX lines points to an engineering-first strategy.
- Leatt — A differentiated safety-tech specialist focused on neck and spinal protection, valuable as a potential technology partner or acquisition target for brands seeking instant protective credibility.
- Aerostich and Rukka — Premium touring and weatherproofing stalwarts whose emphasis on durability and lifetime utility appeals to high-value customer cohorts.
- Regional and value players (e.g., Rynox Gears) — Rapidly expanding in local markets, combining cost advantage with improved design, and representing both competitive pressure and potential channel partners for global brands.
Each company profile in the full report includes HQ, distribution footprint, SKU focus, key recent product launches, and an assessment of strategic vulnerability and opportunity. That contextual granularity informs playbooks on whether to compete, collaborate, or acquire.
Recent events that change the risk calculus
- Trade show intelligence (EICMA 2025) : Several participants used EICMA to debut refreshed protection systems and sustainable product lines — a clear signal that trade-show ROI is shifting toward functional prototype exposure and pre-order funnels rather than pure brand theatre.
- Regulatory actions (Jan–Feb 2026) : Government recalls focused on helmet impact-protection compliance have immediate implications for product testing regimes, supplier audits, and warranty provisioning. Firms must reassess acceptance criteria for inbound helmets and document chain-of-custody.
- Sustainability and materials cost pressure : Demand for recycled membranes and biobased textiles is growing, yet these materials introduce both cost and supply-chain complexity; our cost-stack models quantify break-even points for premium pass-through versus margin compression.
How to use this report in 2026 decision cycles
Executives will find three immediate use cases:
- Investment prioritization — Use our sensitivity-tested revenue and margin scenarios to allocate R&D, inventory, and marketing spend with defensible ROI thresholds over a 24–36 month horizon.
- Regulatory & product safety remediation — Adopt the report’s compliance playbook, which maps testing protocols, audit checklists, and customer-communications templates proven to reduce time-to-market disruption.
- M&A and partnership screening — Apply the acquisition scorecards and synergy calculators to shortlist targets that accelerate tech competencies (e.g., armor systems, sustainable textiles) without undermining channel relationships.
Recommendations — the strategic checklist for 2026
- Re-center product development on verifiable safety metrics and modular protective systems; factor certification timelines into each SKU roadmap.
- Segregate capital for sustainability initiatives that can be monetized through premium pricing or loyalty-driven repeat purchase economics.
- Rebalance inventory strategies from blanket discounting to targeted campaigns that preserve full-price sell-through for newly differentiated SKUs.
- Execute supplier audits and develop a two-tier sourcing strategy to insulate critical components from single-source disruption.
- Invest in digital direct-to-consumer capabilities that both capture higher margin and provide first-party data for ongoing product optimization.
- Use M&A selectively to acquire capability gaps (protective technology, certification labs, or unique material supply) rather than merely scale volume.
Next step — why read the full PW Consulting report
This introduction outlines the strategic context and the high-level levers available to executives in 2026. The full Motorcycle Gear Market report provides the underlying quantitative architecture — including our verified historical time series, scenario-based forecasts across 2026–2032, company-level capability matrices, and actionable templates for compliance, sourcing, and commercialization. Crucially, the detailed segmentation, regional channel breakdowns, and company financial proxies are intentionally reserved for the full report to ensure you have the depth required to act with conviction.
Contact PW Consulting to access the full study and the Excel-based toolkit that will enable your leadership team to convert the 5.6% CAGR opportunity and the post-2025 market recovery into measurable business outcomes.
For detailed analysis of this topic, please visit the official page: Motorcycle Gear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Body Composition Analyzers Market to Reach USD 847.35M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-23
Body Composition Analyzers Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a concise, high‑signal briefing on the Body Composition Analyzers market that frames the strategic decisions organizations must take in 2026. This preview synthesizes our latest research — built on a 2025 base year, five years of historical tracking, and a forward forecast through 2032 — to clarify where value is forming, what risk vectors to mitigate, and which capabilities will differentiate winners. Think of this as a trailer: it demonstrates our analytical depth and the practical frameworks you need, while intentionally reserving the granular splits and proprietary scorecards for the full report.
Body Composition Analyzers Market
Market snapshot: the macro trajectory
The market for body composition analyzers has moved beyond niche clinical instrumentation to a multi‑channel industry serving hospitals, diagnostics labs, sports medicine, fitness/wellness centers, research institutions, and home users. Our base year assessment (2025) places the global market at approximately USD 536 million. From a recovery and growth phase that began in the early 2020s, the market is projected to expand at a compound annual growth rate (CAGR) of roughly 6.98% during the 2026–2032 forecast window, reaching an estimated market scale in the high‑800 million USD range by 2032.
Body Composition Analyzers Market
Two observations arise from these macro numbers: first, the sector presents steady, mid‑single‑digit expansion that favors long‑term capability investments (clinical validation, connectivity, service footprint). Second, growth is uneven by channel and technology — a dynamic that creates both pockets of rapid monetization and areas where incumbents are vulnerable to disruption.
Body Composition Analyzers Market
Why this research matters for 2026 strategic choices
-
Investment prioritization: With constrained capital budgets across healthcare and wellness organizations, leaders need a clear line of sight on which product types and go‑to‑market approaches produce durable returns. Our study translates macro growth into actionable priority areas for R&D, M&A, and sales deployment.
-
Procurement clarity for providers: Hospitals and clinics increasingly demand device reproducibility, regulatory provenance, interoperability with electronic records, and lifecycle service guarantees. Our frameworks enable procurement teams to evaluate devices not just on up‑front cost but on total cost of ownership and clinical utility.
-
Channel & business model design for vendors: As adoption shifts across clinical, fitness, research, and home settings, vendors must refine pricing, subscription, and partnership models to capture adjacent revenue streams (software analytics, managed services, consumables).
-
Regulatory and reimbursement positioning: Device approval status and code‑based reimbursement remain leading determinants of commercial traction. We map regulatory events and reimbursement levers against commercialization timelines so executives can sequence trials and market entries for maximal impact.
What the full report delivers (practical, operational content)
-
Robust market sizing and validated forecasts (2020–2032) with scenario analysis that isolates base‑case, upside, and downside outcomes — each accompanied by sensitivity drivers and break‑even timelines for new product introductions.
-
Granular segmentation by region, product type (e.g., bioimpedance analyzers, DXA systems, skinfold calipers, and others), and application channel (clinical/diagnostic, fitness/wellness, research/academic, home). The public preview omits the granular numeric splits; the report contains those tables and underlying model files for licensed users.
-
Competitive benchmarking with vendor scorecards — assessing product portfolio breadth, regulatory clearances, clinical evidence base, service network density, software ecosystems, and channel partnerships.
-
Go‑to‑market playbooks for manufacturers and distributors that include pricing band analysis, channel margin models, and 12‑ to 36‑month roll‑out calendars aligned to regulatory gates and reimbursement timing.
-
A regulatory and reimbursement playbook mapping device classifications, notable approvals, and payer coding opportunities with step‑by‑step recommendations for obtaining clinical acceptance and reimbursement coverage.
-
Acquisition and partnership target lists with rationale, valuation heuristics, and integration risks — oriented to both strategic acquirers and financial investors.
Competitive landscape: the players you must evaluate
The market exhibits moderate concentration, with the top three vendors representing a meaningful share and the top five increasing that concentration further. This structure produces a dual dynamic: dominant players can leverage scale to invest in clinical trials and global service, while midsize specialists can outmaneuver incumbents through niche clinical positioning and rapid product iteration.
-
Tanita Corporation (Itabashi‑ku, Tokyo) — A recognized name for FDA‑cleared, professional multi‑frequency BIA segmental analyzers targeted at clinical and fitness users. Tanita’s strength is regulatory equity combined with broad clinician recognition.
-
InBody Co., Ltd. (Seoul) — Noted for a range of professional BIA analyzers with strong reproducibility and a deep presence in hospitals and sports organizations. InBody’s repeatability and clinical adoption are key purchase drivers.
-
Hologic, Inc. (Marlborough, Massachusetts) — A leader in DXA‑based whole‑body composition and bone density systems, Hologic’s Horizon DXA is a standard in many clinical settings where high precision is required.
-
OMRON Corporation (Kyoto) — Focused on Bluetooth‑enabled body composition monitors that bridge consumer wellness and clinical applications; OMRON’s distribution footprint in retail and home markets is a competitive advantage.
-
Seca GmbH & Co. KG (Hamburg) — Known for its medical BIA mBCA series, Seca combines precision hardware with integrated anthropometry tools targeted to hospitals and clinics.
-
Bodystat Ltd. (Isle of Man) — A specialist in portable BIS/BIA analyzers, Bodystat competes on device portability and speed of measurement for both medical and fitness use cases.
-
RJL Systems, Inc. (Clinton Township, Michigan) — Offers clinically validated BIA instrumentation, with a focus on whole‑body and segmental analysis and a legacy in clinical research settings.
Our full profiles identify each vendor’s technical differentiators, regulatory pathway status, service footprint, and commercial strengths — enabling competitive response and partnership evaluation. The report also contains a vendor matrix linking feature‑sets to application scenarios and procurement checklists.
Regulatory & reimbursement developments shaping 2026 actions
-
Regulatory density: Our analysts track hundreds of registered devices and active clearances in the U.S. alone. As of our latest review, over 400 body composition devices are registered with the U.S. FDA — a signal of both market maturity and ongoing regulatory activity.
-
Reimbursement levers: CPT code availability for whole‑body bioelectrical impedance assessment remains a material commercial enabler for clinical adoption; organizations that align clinical studies and coding submissions can accelerate hospital uptake.
-
Recent approvals: Clinical trust is reinforced by new clearances and conformity markings. Examples include notified clearances and CE approvals for leading systems — each of which shortens sales cycles in regulated markets and influences procurement decisions.
Strategic recommendations for 2026 (executive checklist)
-
For manufacturers: Prioritize clinical validation and regulatory sequencing in target geographies. Invest in interoperable software and cloud analytics to convert device sales into recurring revenue streams. Consider selective partnerships with electronic health record vendors to embed body composition outputs into care pathways.
-
For healthcare providers: Evaluate devices on reproducibility and integration, not just sticker price. Adopt a lifecycle procurement approach that includes warranty, calibration, and training. Leverage reimbursement codes with evidence‑based protocols to offset acquisition costs.
-
For investors and M&A teams: Target companies with proprietary clinical datasets, regulatory approvals in place, and differentiated software platforms. Expect consolidation among device manufacturers as scale becomes critical for global service and clinical trial support.
-
For fitness and consumer wellness operators: Focus on continuity of care — devices that feed longitudinal analytics and enable coaching monetization outperform stand‑alone hardware in retention and ARPU metrics.
How to use this preview
This preview demonstrates the strategic lenses we apply: rigorous market sizing, vendor benchmarking, regulatory mapping, and executable go‑to‑market playbooks. If your team needs to underwrite a product launch, prioritize an acquisition, or restructure sales and service territories for 2026, the full PW Consulting Body Composition Analyzers report provides the models, vendor scorecards, and step‑by‑step implementation tools required to convert insight into measurable outcomes.
To preserve the value of the work for our clients, we have intentionally withheld the granular regional and application numeric splits, the full vendor share table, and the downloadable financial model from this public preview. These deliverables are included in the licensed report and are designed to plug directly into corporate planning workflows.
Next steps
-
Request the full report to obtain the detailed segmentation tables, interactive forecast model, and vendor scorecards.
-
Book a briefing with our advisory team to align the report findings to your 2026 planning cycle and to receive a tailored action plan for product, market, or investment initiatives.
PW Consulting’s Body Composition Analyzers research equips executives with the analytical clarity and operational tools necessary to make confident, high‑impact decisions in 2026. For organizations seeking to move from observation to execution, the full report is where the roadmap and the implementation templates live.
For detailed analysis of this topic, please visit the official page: Body Composition Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Party Supplies Market to Reach USD 25,300M by 2032; 8.5% CAGR
By pmarketresearch, 2026-07-23
Party Supplies Market 2026: Strategic Imperatives and Actionable Insights for Decision Makers
As companies prepare strategies for 2026, the party supplies sector presents a compelling mix of growth opportunity and operational complexity. Our latest PW Consulting study positions the global market at approximately USD 14.5 billion in the 2025 base year and projects an 8.5% compound annual growth rate (CAGR) into the 2026–2032 forecast window, culminating in a market north of USD 25 billion by 2032. These headline metrics underscore a resilient recovery from pandemic-related distortions and a clear structural expansion driven by changing consumer behaviours, retail channel evolution, and product innovation.
Party Supplies Market
Why this study matters to 2026 corporate decision-making
-
Timing investments with precision: An 8.5% CAGR is not uniform across value chains. For executives evaluating capital deployment—whether in manufacturing capacity, private-label launches, or e-commerce tech—our analysis offers scenario-calibrated demand curves that help prioritize near‑term spend without sacrificing optionality for 2027–2032 upside.
Party Supplies Market -
Translating macro momentum into defensible margins: Growth alone is insufficient where input-cost volatility and tariff shocks compress profitability. The report integrates margin-sensitivity modelling tied to raw material and freight fluctuations so pricing, hedging, and supplier contracting can be stress‑tested against realistic downside cases.
Party Supplies Market -
Shaping M&A and portfolio plays: Industry concentration metrics indicate meaningful scale advantages for top players while leaving white space for targeted consolidation. For corporate development teams, the study provides acquisition prioritization frameworks and accretion/dilution modelling tailored to party‑goods economics.
-
Operational resilience and supply‑chain playbooks: With documented quarterly volatility in raw material costs and fresh tariff regimes altering sourcing economics, operations leaders need concrete routing, nearshoring, and supplier diversification options. Our work maps practical levers—lead-time buffers, dual-sourcing triggers, and inventory segmentation rules—directly into procurement KPIs.
What the report delivers (practical, executable content)
-
Demand scenarios and forecasting engine: A calibrated forecast suite for 2026–2032 that supports bottom‑up SKU and channel planning; includes probability‑weighted scenarios (baseline, upside, downside) and an interactive toolset to run “what‑if” sensitivity to price, promotion, and macro shocks.
-
SKU profitability and assortment optimization playbook: Step‑by‑step frameworks to rationalize SKUs across retail and e-commerce channels, with templates for contribution-margin analysis, inventory-turn thresholds, and SKU lifecycle governance.
-
Supply‑chain stress tests and sourcing blueprints: Practical templates for supplier scorecards, total landed-cost calculators, and contingency sourcing maps that incorporate tariff scenarios and freight-rate oscillations.
-
Go‑to‑market and channel strategies: Tactical guidance for balancing big‑box, specialty retail, and direct‑to‑consumer channels; includes playbooks for private‑label acceleration, licensing partnerships, and promotional calendar planning aligned with consumer occasion data.
-
Regulatory and product safety checklist: A compliance toolkit for lead/cadmium restrictions, children’s product testing regimes, and labeling best practices—designed to minimize recall risk and preserve retail access.
-
M&A diligence templates and valuation comparables: A ready‑to‑use diligence checklist for acquisition targets, along with stylized valuation drivers and integration roadmaps that recognize the sector’s inventory and seasonality dynamics.
-
Sustainability and packaging pathways: Practical steps for decarbonizing product footprints, moving toward recyclable and compostable disposables, and quantifying trade‑offs between cost and brand value.
Competitive landscape: what leaders need to know
The sector today mixes heritage brands, diversified leisure-and-gifting groups, specialized manufacturers, and high-volume e-commerce players. Recent corporate events have already begun reshaping competitive dynamics: the restructuring and subsequent asset sale of a major nationwide retailer and legacy manufacturer has created an immediate re‑ranking of scale players and opened pockets of supply and brand inventory that agile firms can leverage.
Key incumbent strategies vary from integrated design‑to‑distribution models to licensed-character plays and high‑volume commodity manufacturing. Several patterns are consequential for 2026 strategy:
-
Consolidation windows are open: Market concentration statistics point to a mid‑tier aggregation opportunity. Thoughtfully executed acquisitions can deliver margin uplift through SKU rationalization, shared procurement, and channel cross‑selling.
-
Brand and IP remain valuable: Licensing relationships and proprietary designs continue to command pricing power in occasion-driven segments. Firms that can combine strong creative pipelines with efficient fulfillment will outperform.
-
Mass-market manufacturers must defend on cost and sustainability: Commodity producers face margin pressure from raw material volatility and tariff headwinds. Investments in process efficiency, nearshore sourcing, and greener materials are becoming table stakes.
-
Digital-first merchants will define convenience: E‑commerce growth and the expansion of omnichannel retail mean that convenience, assortment depth, and digital merchandising will be decisive for market share gains.
Headline market signals and tactical implications
-
Input-cost shocks are real and measurable. Supply‑chain volatility has driven material-price moves that can swing costs materially within a quarter; procurement teams must adopt dynamic repricing clauses and build hedging playbooks for critical inputs.
-
Tariff policy is altering sourcing math. New trade measures introduced in 2025 have already prompted sellers to shift sourcing strategies; companies should model sourcing networks under alternate tariff paths and pursue supplier diversification to preserve competitive pricing.
-
Regulatory compliance affects product design: State‑level prohibitions on heavy metals create test-and-certify requirements for children’s and seasonal products. R&D and quality teams should embed compliance gates early in product development to avoid costly rework or market exclusions.
-
Channel mix is evolving fast. E‑commerce penetration into the party‑goods category is accelerating, creating margin opportunities through direct selling but also elevating the importance of logistics economics and return-management capabilities.
-
Event and celebration spending remains a durable demand anchor. Consumer willingness to spend on experiences and occasions supports continued expansion, but spending patterns are becoming more occasion‑specific and premiumized in certain subsegments.
Strategic playbook for 2026
-
Prioritize supply‑chain optionality: Implement a tiered sourcing strategy that balances cost competitiveness with the ability to rapidly shift volume. Include geographic diversification, contractual penalties, and dual-sourcing triggers tied to price thresholds.
-
Move from assortment breadth to margin depth: Use SKU profitability frameworks to prune low-return items and reinvest in curated assortments that support higher margins and faster turns.
-
Embed compliance into product DNA: Adopt a “regulation‑by‑design” approach that aligns R&D, procurement, and testing to reduce launch friction and protect distribution channels.
-
Invest in differentiated omnichannel experiences: Combine digital merchandising, trade promotions, and experiential retail to capture the premium occasion shopper while defending base volumes in mass channels.
-
Evaluate targeted M&A for scale and capability: Seek bolt‑on assets that close capability gaps—fulfillment density, licensing portfolios, or sustainable materials expertise—over broad diversification.
What we leave for the full study
This introductory briefing highlights structural drivers, tactical levers, and competitive dynamics that should inform 2026 decisions. The full PW Consulting Party Supplies Market report contains the granular intelligence executives need to act: detailed segment-level forecasts, region-and-application breakouts, SKU-level margin matrices, competitor revenue benchmarks, and downloadable modelling templates. Pricing elasticities, channel-by-channel conversion curves, and supplier risk heat maps are available through the report’s interactive dashboards—essential inputs for transaction diligence and operational planning.
If your leadership team is preparing a budget, supply‑chain overhaul, or M&A pipeline for 2026, the comprehensive datasets and operational playbooks in our full report will convert insight into executable plans with measurable KPIs. Visit the source page to access the full dataset, scenario tools, and bespoke advisory options from PW Consulting’s party‑goods practice.
For detailed analysis of this topic, please visit the official page: Party Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Super Absorbent Pet Pad Market: Strategic Outlook for 2026 — A PW Consulting Preview
Introduction
As PW Consulting’s senior strategy team, we prepared this executive preview to orient senior leaders, investors, and product-line owners to the strategic levers that will matter in 2026 for the Super Absorbent Pet Pad market. This narrative synthesizes our diagnostic work across market sizing, supplier economics, regulatory shifts, and competitive positioning. It intentionally surfaces the evidence-based judgments and decision frameworks that clients will need to act quickly — while preserving the proprietary, granular segmentation and scenario outputs that form the core of our paid analysis.
Super Absorbent Pet Pad Market
Market Snapshot: What the Macro Picture Shows
Using 2025 as the base year and a historical series beginning in 2020, PW Consulting’s topline model shows a steady expansion of the global Super Absorbent Pet Pad market through our forecast horizon to 2032. From a mid‑single‑hundred million USD industry base in 2020, the market rose materially by 2025 and is projected to continue expanding under our central scenario. Our forecast period spans 2026–2032 and embeds a compound annual growth rate (CAGR) of 3.6% from the base year through the forecast window.
Super Absorbent Pet Pad Market
To translate that into perspective: the market has matured beyond its early rapid‑growth phase and is now characterized by moderate, resilient growth driven by premiumization, channel shifts to e‑commerce, and product differentiation (odor control, leak protection, and sustainability claims). That growth profile creates a different strategic playbook than a high‑growth market: efficiency, margin protection, and selective innovation become the priority levers for 2026.
Super Absorbent Pet Pad Market
What the Full Report Delivers (Practical, Transaction-Grade Outputs)
- Dynamic market sizing and a reconciled forecast model (2020–2032) with downloadable scenario inputs so financial teams can re-run sensitivities under alternate SAP price and demand-shock assumptions.
- Actionable segmentation framework across product types, applications, and channels — with proprietary elasticities and unit‑price ladders for prioritizing SKUs.
- Supplier and input-cost benchmarking, including a componentized bill‑of‑materials that isolates the share and volatility of super absorbent polymer (SAP) in unit economics.
- Competitive heat maps and capability diagnostics for OEM/ODM players and private labels, including go‑to‑market scorecards and recommended partnership archetypes.
- Regulatory and standards playbook: implementation timelines and retailer compliance triggers tied to ASTM standardization efforts and voluntary certification pathways.
- Investment and M&A decision support: valuation multiples observed across recent transactions, integration risks, and potential synergies for horizontal consolidation or backward integration into SAP supply.
- Operational playbooks for production scale-up, QC, and logistics optimization under raw-material stress scenarios.
Key Market Dynamics and Strategic Implications for 2026
Below we summarize the dynamics that will materially influence near‑term decisions and the strategic options companies should prioritize in 2026.
- Input-cost concentration around SAP: Our industry engagement and cost modeling show that SAP is the single largest raw material contributor in pad manufacturing. That concentration means SAP price moves have outsized impacts on margins and retail pricing. Firms that can lock favorable long‑term supply, qualify alternative chemistries, or vertically integrate will gain a durable advantage in pricing flexibility.
- Sustainability as a double-edged sword: Degradable SAP alternatives are materially more expensive on a unit basis (industry participants reference 2–5x higher unit cost in developer conversations). While these materials open routes to premium positioning and retail shelf eligibility in sustainability programs, adoption will be constrained where price elasticity is acute. A staged product-release strategy and targeted premium channels work better than across‑the‑board reformulation in 2026.
- Standards and retailer pressure: The establishment of an ASTM subcommittee focused on pet products is accelerating voluntary standardization. Major retailers are already signaling they will favor suppliers who can demonstrate compliance. For 2026, compliance readiness will be a non‑negotiable for supply to tier‑one retail and institutional customers; proactive certification is a market access cost, not an optional marketing exercise.
- Channel bifurcation and private label dynamics: E‑commerce and private‑label programs continue to exert price pressure while creating volume opportunities. National retailers and platforms are increasingly optimizing assortments toward products that balance absorption performance with predictable cost structures. Brands that can differentiate on performance (odor control, quick‑dry, leak barriers) and simultaneously defend margins through private‑label manufacturing partnerships will capture both volume and margin.
- Quality and third‑party testing as a trust signal: Independent lab testing is becoming a buyer expectation — not just a marketing claim. Recent third‑party testing programs highlight performance variance across products; suppliers that invest in verified performance will unlock premium positioning and retailer shelf support.
Competitive Landscape — Who Matters and Why
The market exhibits moderate concentration at the top, with a small number of large suppliers commanding meaningful share while a broad set of specialized OEM/ODM firms serve differentiated product niches. That structure creates two viable strategic archetypes for 2026: scale‑driven cost leadership and specialist premiumation.
- ElinTree (China) — A specialist OEM/ODM with a focus on configurable absorbency ranges, odor control, and eco‑friendly material options. Certifications and quality systems position ElinTree as a reliable partner for branded manufacturers seeking customization and export compliance.
- Hangzhou Haoyue Personal Care — A legacy player with deep manufacturing experience. Its long production pedigree supports complex OEM contracts and consistent unit economics for larger private‑label programs.
- Tianjin Yiyi Hygiene Products — A high‑volume manufacturer with a strong export footprint, particularly in the U.S. market. Their scale and OEM capabilities make them an attractive partner for retailers and fast‑scaling private labels.
- Amazon Basics (United States) — A private‑label incumbent emphasizing performance at value price points. Represents the channel leverage private labels have over shelf assortment and the importance of manufacturing partnerships.
- Glad for Pets (United States) — A retail brand that pairs activated carbon odor control with mass retail reach; demonstrates the value of trusted consumer brands in driving purchase preference despite a crowded SKUscape.
Recent market events — a March 2026 new product launch by a named brand at Global Pet Expo and independent lab testing conducted in January 2026 — crystallize two practical points: (1) product innovation remains a necessary signal in the market, and (2) verified performance testing increasingly separates credible claims from marketing noise.
Market Concentration and Strategic Options
Our concentration analysis shows the market is neither a pure commodity nor a closed oligopoly. With the largest three firms accounting for a significant but not dominant share and the top five increasing that footprint further, scale matters for procurement and SAP exposure mitigation. Yet meaningful opportunity remains for nimble, quality-focused players to carve premium niches — particularly where they can pair validated performance with sustainability credentials and retailer endorsements.
2026 Playbook: Prioritized Actions for Executive Teams
- Hedge and secure SAP supply: Negotiate multi‑year contracts with volume bands and optionality clauses; evaluate co‑development or equity partnerships with SAP producers.
- Segment your innovation: Reserve high-cost degradable SAP formulations for targeted premium SKUs and sustainability pilots; defend core value SKUs with incremental performance improvements that do not materially raise cost.
- Certify early for ASTM-aligned standards: Invest in testing and documentation now to avoid downstream delisting from major retailers as voluntary standards crystallize into procurement requirements.
- Optimize channel mix: Use private‑label manufacturing as a margin and volume play while protecting your branded premium positions with demonstrable, third‑party validated features.
- Scenario-test price pass-through: Update pricing models to incorporate SAP cost swings and consumer elasticity thresholds, and model breakpoints at which premium features can be introduced without jeopardizing volume.
- Pursue targeted M&A or JV activity: Look for bolt‑on capabilities in odor control technologies, sustainable SAP developers, or last‑mile logistics to shorten time to market and strengthen margin capture.
How to Use PW Consulting’s Full Study
The complete PW Consulting report provides the proprietary models, SKU‑level demand curves, and supplier scorecards referenced above. It contains interactive spreadsheets for CFOs, an operations module for plant managers to run capacity stress tests under raw‑material shocks, and a retailer readiness checklist aligned to evolving ASTM guidance. If your 2026 planning cycle involves CAPEX allocation, product roadmap prioritization, or M&A screening in this category, the report was designed to be used as the central decision support artifact.
Conclusion — Why This Matters in 2026
For 2026, the Super Absorbent Pet Pad market offers stable growth, but strategic advantage will accrue to companies that treat SAP not just as an input but as a strategic asset. An integrated approach — combining supplier hedging, staged sustainability adoption, verified performance positioning, and proactive standards compliance — will separate winners from the pack. PW Consulting’s full report equips decision makers with the quantitative, operational, and regulatory tools to execute that approach; this preview highlights the direction and the core risks so your leadership team can prioritize the right near‑term actions.
To unlock the full dataset, scenario models, and supplier scorecards, refer to PW Consulting’s Super Absorbent Pet Pad Market study — the operational playbook you will want at your desk for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Super Absorbent Pet Pad Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com