

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Nitinol Medical Device Market USD 1,850M in 2025, 8.5% CAGR to 2032

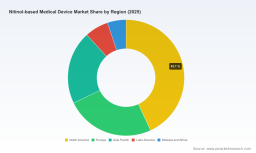
Nitinol-Based Medical Device Market — A Strategic Preview for 2026 Decision Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused preview of our new market research on Nitinol-based medical devices. This preview distills the strategic signals corporate leaders must act on in 2026 while deliberately withholding the granular segment tables and source-level splits that drive tactical execution. The full report contains those datasets and step-by-step playbooks; consider this a high-fidelity trailer designed to accelerate executive alignment and push high-priority decisions to the front of the boardroom agenda.
Nitinol-based Medical Device Market
Macro view: size, trajectory and what it implies
By our base year (2025) sizing the Nitinol-based medical device market reached approximately USD 1,850 Million. The market has expanded from approximately USD 1,250 Million in 2020 and is modeled to grow at a compound annual growth rate (CAGR) of roughly 8.5% through our forecast horizon, culminating in an implied market above USD 3.2 Billion by 2032. That trajectory is not merely arithmetic — it reflects accelerating device innovation (miniaturization, complex geometries), faster clinical adoption of minimally invasive interventions, and expanded use-cases across surgical specialties.
Nitinol-based Medical Device Market
For corporate leaders, two imperative conclusions follow. First, volume and addressable revenue are growing fast enough that first-mover investments in supply chain capacity, regulatory preparedness, and clinical evidence generation materially improve lifetime product economics. Second, rising demand exposes supply-side bottlenecks and cost inflation that will meaningfully affect margins unless addressed through deliberate sourcing and process strategies.
Nitinol-based Medical Device Market
Supply, cost and manufacturing dynamics — the levers that matter in 2026
- Raw material economics: Medical-grade Nitinol commands a substantial price premium compared with common implant alloys. Typical industry benchmarks show medical-grade Nitinol wire pricing materially higher than stainless alternatives — a delta that is a fundamental driver of device pricing and margin sensitivity. Expect procurement to be a primary battleground for margin protection.
- Capacity expansion and geographic diversification: Leading suppliers are scaling rapidly. Recent investment activity — including purpose-built Nitinol centers and equipment acquisitions — signals that suppliers are prioritizing higher throughput and tighter quality controls to serve OEMs expanding product portfolios. These developments create practical windows to re-negotiate supply agreements and lock in capacity for multi-year product ramps.
- Processing complexity and premium capabilities: Beyond raw wire, value is captured in advanced processes — ultra-fine drawing, precision tubing, shape-setting, micro-lumen creation, and post-processing surface treatments. Control over these capabilities materially shortens time-to-market and reduces technical risk on complex designs.
Regulatory and clinical risk: pressure points to prioritize
Regulatory scrutiny for nickel-containing alloys has increased. The U.S. FDA’s guidance on non-clinical assessment of devices containing Nitinol emphasizes corrosion potential and mechanical testing as core evaluation areas, raising the bar for pre-market technical packages. At the same time, there remains no universally adopted, dedicated standard for nickel ion release testing — a gap that creates uncertainty for both manufacturers and regulators and elevates the importance of defensible, internally consistent testing strategies.
From a strategic perspective, companies that proactively invest in robust, traceable corrosion and ion-release programs — and that can demonstrate mitigations (coatings, alternative surface finishes, process controls) — will differentiate in procurement, clinician adoption, and payer conversations. Firms that treat regulatory uncertainty as a fixed cost rather than a managed risk will see elevated launch timelines and capital erosion.
Competitive landscape — direction of travel, not the final score
The market exhibits measurable concentration at the top: the three largest players capture the majority of specialist supply, and the top five increase that dominance further. That level of concentration shapes bargaining dynamics between OEMs and suppliers and creates both strategic risks and consolidation opportunities for acquirers.
Key company archetypes and strategic behaviors we profile in the full research include:
- Precision melt and wire specialists expanding melt capacity and downstream quality programs — exemplified by companies investing heavily in melt throughput and supplier recognition awards that validate program maturity.
- Ultra-fine and medical-grade wire producers focusing on micron-scale capabilities to serve premium guidewire and stent designs.
- Contract manufacturers and component specialists acquiring niche capabilities (e.g., gun-drilling for microcatheters) to internalize high-risk processes and shorten supplier chains.
- Custom OEM partners that provide coil-forming, shape-setting, and device assembly services to accelerate OEM prototype-to-scale transitions.
We include company-level capability maps, investment timelines, and signal matrices in the full study. The preview purposefully omits granular market-share and segment share tables so that clients access the competitive scorecards directly from the source deliverable.
Recent strategic signals (illustrative)
- Facility expansions in lower-cost manufacturing regions that double local output capacity — a clear signal that suppliers are preparing for multi-year OEM demand ramps and that contract rates may moderate volatility if capacity is effectively absorbed.
- Targeted capability acquisitions focused on micro-manufacturing processes (precision lumen creation, advanced drilling) — indicating that contract manufacturers are moving up the value chain to lock in higher-margin work and reduce technical outsourcing risk.
- Regulatory recognition and supplier awards from leading OEMs — suggesting that supply reliability and validated process controls are increasingly decisive selection criteria.
What the full PW Consulting report delivers — practical, actionable content
Our objective is to deliver intelligence that translates directly into executable decisions. The full report contains:
- Model-backed market sizing and a 2020–2032 financial model with scenario toggles for demand, price inflation, and adoption curves.
- Segmentation taxonomies (product, application, geography) with downloadable data tables and interactive dashboards — note: this preview intentionally withholds the segment-level numbers that underpin go-to-market prioritization.
- Supplier capability and capacity maps, including plant-level assessments, lead-time sensitivity analysis, and a supplier risk heatmap tailored for OEM sourcing teams.
- Regulatory and clinical readiness playbooks: test matrices aligned to FDA expectations, sample clinical evidence pathways by indication, and defensive strategies for managing ion-release scrutiny.
- Pricing and margin sensitivity models that incorporate raw-material cost curves, processing premiums, and throughput ramps.
- M&A and partnership screening frameworks with prioritized targets, valuation approaches, and integration risk checklists for acquirers seeking to capture upstream or downstream value.
- Practical checklists, RFP templates, and contractual clauses designed to secure capacity, IP protection, and quality commitments from strategic suppliers.
How 2026 leaders should act — a short roadmap
- Lock capacity with the right contract structure: pursue hybrid contracts that combine committed volumes with volume-flex collars to protect against over- or under-utilization during product rollouts.
- Invest in disciplined regulatory evidence: begin corrosion and ion-release mitigation testing early and build it into design control so regulatory submissions are predictable and defensible.
- Prioritize capability ownership where it drives differentiation: if your IP depends on ultra-fine drawing or proprietary shape-setting, consider nearshoring or captive investments; otherwise, prefer strategic supplier partnerships with long-term capacity commitments.
- Design a pricing playbook that isolates raw material exposure: include indexed components in long-term supply agreements and periodic repricing triggers tied to observable Nitinol market indexes.
- Use M&A tactically to secure bottleneck capabilities: target suppliers with unique micro-manufacturing competencies or contract manufacturers that can move further up the value chain and provide margin capture.
Methodology and confidence — why this forecast matters
The forecast blends: (1) a bottoms-up capacity and demand build based on procedure volumes and device adoption curves; (2) primary interviews with OEM procurement, clinical leads, and supplier executives; (3) plant-level capacity and throughput modeling; and (4) a material-cost engine that simulates the interplay between alloy pricing, processing premiums, and scale economies. Scenario analyses are provided for conservative, base, and aggressive adoption pathways so executives can stress-test investment decisions against plausible market swings.
Final note — what you don’t see here (and why it’s important)
This editorial intentionally refrains from publishing the granular regional, product, and application splits that drive precise product prioritization and M&A valuation work. Those tables and the accompanying unit economics are included in the full PW Consulting deliverable because they are the tactical intelligence that competitors would exploit if freely distributed.
If you are preparing a 2026 strategic plan, supply agreement, capital allocation decision, or M&A screen in the Nitinol device space, this preview should have clarified the principal strategic levers and the critical timing for action. The complete report supplies the hard numbers, negotiation-ready models, and executable playbooks you will need to convert strategy into measurable outcomes.
Contact PW Consulting to request the full report package, walk-through briefings, and bespoke scenario modeling tailored to your portfolio and supply chain. In markets that move as fast and as technically as Nitinol-based devices, timing and information quality are the difference between value capture and value leakage.
For detailed analysis of this topic, please visit the official page: Nitinol-based Medical Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com