

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: E-Liquids Market to Reach USD 2.47B by 2032 at 12.58% CAGR

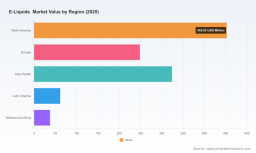
E‑Liquids Market: Strategic Brief for 2026 Decision‑Making
PW Consulting’s latest E‑Liquids Market study provides a forward‑looking intelligence package designed to convert macro momentum into executable strategy for 2026. Built on a historical series (2020–2025) and a detailed forecast window (2026–2032), the research quantifies a robust recovery and growth trajectory — driven by product innovation, channel shifts, and a rapidly evolving regulatory landscape. The market, which stood at a mid‑2020s base of approximately USD 1.125 billion (base year 2025), is projected to expand at a compound annual growth rate of 12.58% through the forecast period, effectively more than doubling by the end of the horizon. This brief explains why the report is a strategic asset for executive teams while intentionally holding back the granular segment tables that appear in the full study.
E-Liquids Market
Why this report matters for 2026
-
Timing: 2026 is a pivot year. Recent regulatory decisions and commercial investments have created a bifurcated landscape where authorized, compliant offerings can gain privileged access to the largest consumer channels — while non‑compliant players face compounding market risks.
E-Liquids Market -
Clarity on scale and trajectory: With a clear historical base and a transparent growth model, leadership teams can assess horizon planning (capacity, working capital, pricing) against a defensible market size and growth curve.
E-Liquids Market -
Practicality: The report translates macro projections into operational levers — from SKU rationalization to plant footprint decisions — giving C‑suite and business unit leaders immediate, actionable choices rather than abstract forecasts.
-
Risk quantification: Regulatory shocks and channel closures are modeled in multiple scenarios; this allows management to simulate downside impacts and construct hedges ahead of material events.
What the full study delivers (practical highlights)
-
Proprietary market model with historical reconciliation (2020–2025) and scenario‑based forecasts through 2032.
-
Regulatory impact module that overlays country‑level policy changes on demand and price models.
-
Commercial playbooks for top‑line growth: channel segmentation, pricing archetypes, promotion elasticity and D2C rollouts.
-
Supply‑chain and manufacturing toolkit: capacity vs. demand maps, quality and compliance gating, and an investment case for brownfield/greenfield expansions.
-
M&A and partnership screening: shortlist of target archetypes, valuation multipliers under different integration synergies, and post‑deal 100‑day playbook templates.
-
Brand and SKU optimization framework: margin‑weighted SKU pruning, innovation road‑maps for flavor and format, and packaging/cost trade‑offs.
-
Investor and board‑ready slide decks and financial models for scenario planning.
Macro picture: growth trajectory and market structure
The market’s trajectory from 2020 through 2025 establishes a consistent expansion pattern that accelerates into the forecast window. From a modest base in the early 2020s, the sector advances to a mid‑2020s market size near the USD 1.125 billion mark, then climbs steadily under our central scenario to reach an estimated USD 2.47 billion by 2032 — the result of ongoing product substitution, new adult user uptake in permitted channels, and premiumization across certain formats. The implied compound annual growth rate of 12.58% across the forecast period encapsulates both structural growth (category adoption and device upgrades) and cyclical drivers (regulatory approvals and trade‑channel reconfiguration).
Concentration metrics indicate a market where leading players command a dominant share footprint: the top three firms hold a majority share, while the top five collectively account for a very substantial proportion of market value. This structure creates both defensive moats for incumbents and white‑space opportunities for well‑capitalized challengers that can differentiate on regulatory compliance, brand trust, or supply reliability.
Competitive landscape: strategic implications for incumbents and challengers
The competitive field is heterogeneous and can be usefully viewed in three clusters.
-
Big tobacco and diversified incumbents (e.g., Philip Morris International, British American Tobacco, Imperial Brands, Japan Tobacco International): These companies bring scale in regulatory affairs, distribution, and capital. Their global footprint and access to regulated channels make them natural beneficiaries of favorable product authorizations. Strategic priorities should focus on portfolio rationalization (emphasize compliant SKUs), supply chain resilience, and targeted premiumization to protect margin as unit volumes scale.
-
Pod and device specialists (e.g., JUUL Labs, Logic Technology Development, NJOY): These players compete on device design, nicotine delivery characteristics, and rapid go‑to‑market of new formats. The path forward rests on achieving regulatory clearances in priority markets, proving robust youth‑access prevention measures, and forging retailer partnerships that favor tested, authorized SKUs.
-
OEM/ODM and independent e‑liquid manufacturers (e.g., Hangsen, Vape Base Ltd, Ruthless Vapor, Mister‑E‑Liquid): These suppliers are pivotal to capacity and white‑label growth. Their competitive levers are formulation agility, manufacturing quality (USP‑grade inputs), and global distribution to independent retail. For contract manufacturers, the fastest route to growth is investment in compliant production lines, traceability systems, and customer co‑development programs with leading device OEMs.
Recent commercial and regulatory developments underscore these dynamics. The U.S. Food and Drug Administration’s authorization waves (including the May 2026 authorization of several Glas ENDS products) are reshaping retail assortment rules and elevating authorized product economics. Simultaneously, the roll‑out of duties and tax regimes (e.g., the UK’s Vaping Products Duty applications opened in April 2026) and state‑level compliance regimes are changing price floors and operating compliance costs across markets. Retail‑level activity — exemplified by trade shows and bespoke category spaces for e‑liquids — suggests continued vibrancy in independent and specialty channels even as mainstream shelf access tightens for authorized SKUs only.
Regulatory and policy dynamics to prioritize
-
Authorization scarcity in the U.S.: As of mid‑2026, only a limited set of ENDS products are legally marketed. This scarcity creates a two‑tier channel system where authorized brands can command better shelf access and lower trade resistance.
-
New tax instruments and duties: Emerging excise regimes will compress margins for lower‑end SKUs and create incentives for product reformulation or premiumization.
-
State and provincial compliance: Tighter manufacturer certification rules and directory requirements at sub‑national levels increase operating overhead for smaller producers and create an advantage for firms with compliance infrastructure.
-
Retail and channel compliance: Retailers are tightening sourcing controls — preference is given to products with clear regulatory pathways and documented quality systems.
Immediate strategic imperatives for 2026
-
Prioritize regulatory gating: Map your SKU set to regulatory pathways now. Accelerate clinical, toxicology and youth‑access mitigation evidence where required to pursue authorization slots.
-
Right‑size manufacturing: Use the report’s capacity model to decide whether to expand, outsource, or form tolling partnerships. Avoid capex commitment until you reconcile authorization probabilities across priority markets.
-
Portfolio triage and premiumization: Reallocate SKU and marketing dollars toward formats and flavors that align with permitted channels while pruning low‑margin assortments.
-
Channel hedging: Grow authorized direct channels (D2C with strong age‑verification) and maintain strategic relationships with specialty retail that can support niche innovation.
-
M&A and partnerships: Seek bolt‑on targets that bring capacity, compliance expertise, or access to authorized channels. Use the study’s acquisition filters to prioritize targets by integration complexity and payback horizon.
-
Operationalize compliance: Invest in batch traceability, supplier audits, and product stewardship programs to lower regulatory and reputational risk.
How to use the full PW Consulting report
This brief outlines the strategic contours you need to act now. The full report contains the missing detail critical to execution: granular regional demand curves, flavor and format segmentation, channel‑level price bands, elasticity matrices, supplier cost curves, and a prioritized list of commercially viable M&A targets. It also includes playbooks for market entry, a regulatory probability matrix, and downloadable financial models patched to our central and alternate scenarios.
For teams designing 2026 capital plans, go‑to‑market roadmaps, or M&A pipelines, the study serves as both a diagnostic and a transaction tool. PW Consulting stands ready to deliver tailored workshops that convert the report’s insights into a 90‑day action plan aligned to your P&L and balance sheet realities.
To access the complete segmentation tables, scenario outputs and company‑level benchmarking that underpin the strategic recommendations in this brief, visit the research page linked from PW Consulting’s E‑Liquids Market offering. The full dataset is where the operational levers live — and where your execution roadmap begins.
For detailed analysis of this topic, please visit the official page: E-Liquids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com