

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Intranasal Drug Delivery Devices Market to Hit USD 3,435.95M by 2032 — PW Consulting

Intranasal Drug Delivery Devices Market: Strategic Imperatives for 2026
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused briefing on the intranasal drug delivery devices market — a fast-evolving subsector where device design, formulation innovation, regulatory clarity, and distribution strategy intersect to produce meaningful commercial outcomes. This preview synthesizes market momentum, regulatory context, competitive dynamics, and practical levers executives should prioritize in 2026. For clients seeking the full granular intelligence — regional splits, application-level volumes, pricing matrices, and vendor scorecards — our complete report contains the datasets and playbooks that operationalize these insights.
Intranasal Drug Delivery Devices Market
Market trajectory: a data-backed runway into 2032
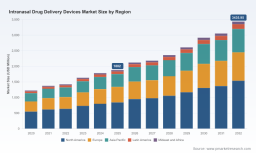
Intranasal drug delivery devices have moved from niche rescue-and-symptom markets into a broader platform opportunity, driven by growth in biologics-compatible devices, nose-to-brain targeting, and renewed interest in non-invasive vaccine delivery. Our model — built on an audited historical series (2020–2025) and a scenario-driven forecast (2026–2032) with base year 2025 — shows clear acceleration. The market grew materially through the pandemic and post-pandemic years, reaching USD 1,882.0 Million in 2025. Under our central case (incorporating regulatory trends, product launches, and adoption curves), the market is projected to grow at a compound annual growth rate of approximately 8.98% over the forecast window, reaching roughly USD 3,435.95 Million by 2032.
Intranasal Drug Delivery Devices Market
Two practical takeaways for corporate planners: (1) the pace of device adoption creates a narrow window in 2026–2028 to secure preferred partnerships, intellectual property positions, and reimbursement pathways; (2) upside scenarios tied to successful nose-to-brain therapeutics and intranasal vaccines could materially re-rate capital allocation priorities, altering ROI timelines for both developers and device suppliers.
Intranasal Drug Delivery Devices Market
Why this research matters for 2026 decisions
- Capital allocation and portfolio prioritization: Investors and R&D leaders must decide whether to accelerate platform investments (e.g., dry-powder metered units, multi-dose pumps with biologic compatibility, atomizers for rapid systemic uptake) or to focus on iterative improvements to legacy pumps. Our report quantifies the trade-offs and break-even horizons under multiple adoption scenarios.
- Partnering and M&A targeting: Device-manufacturer capability (scale injection-mold tooling, sterile fill-finish integration, regulatory track record) is now a gating factor for rapid launches. The research delineates candidate profiles for licensing, OEM supply, and bolt-on acquisitions that shorten time-to-market.
- Regulatory and reimbursement preparedness: With multiple devices cleared by regulatory agencies and clear reimbursement pathways emerging for approved products in clinical settings, the tactical path to clearance and payer acceptance is operationally tractable — but requires specialized evidence-generation plans. Our analysis maps the most efficient clinical- to-commercial evidence sequences for a range of device/formulation combinations.
- Go-to-market and commercialization: Distribution strategies (hospital procurement, respiratory clinics, emergency medicine, retail pharmacy) vary by therapeutic use case. The report provides channel economics and launch playbooks that convert favorable clinical profile into durable market share.
Report deliverables — practical components
- Comprehensive market sizing and forecast model (historical 2020–2025; forecast 2026–2032) with scenario toggles.
- Technology landscape and device-architecture taxonomy (multi-dose, unit-dose, atomizers, dry powder platforms) with design constraints and formulation compatibility matrices.
- Regulatory pathway maps and a checklist for 510(k)/equivalence and device-combination product filings, plus payer-engagement templates targeted to the US and key global markets.
- Commercial playbooks: pricing frameworks, channel economics, adoption accelerators (KOL engagement, hospital formulary strategies, emergency services partnerships).
- Company dossiers and strategic assessments for tier-1 and tier-2 suppliers, including capability heatmaps and acquisition readiness analyses.
- Supply-chain risk assessment and mitigation options for critical components, secondary packaging, and sterile fill capacity.
Competitive landscape — positioning and strategic moves
This market is shaped by specialists that combine engineering precision with pharmaceutical compatibility. The competitive field ranges from global dispensing specialists to integrated CDMOs that can deliver API-to-device solutions. The following synthesis highlights the strategic posture of the most influential players and the tactical implications for potential partners and competitors.
- Aptar Pharma — A leader in comprehensive nasal spray platforms, Aptar’s portfolio spans single- and multi-dose solutions and has deep experience supporting clinical programs. Recent utilization of Aptar devices in Phase II clinical work underscores their attractiveness as an execution partner for programs seeking a proven device backbone and rapid clinical deployment. Strategic implication: pharmaceutical sponsors can de-risk clinical development timelines by favoring device partners with prior clinical track records.
- Teleflex — Known for mucosal atomization devices, Teleflex plays to the acute and emergency care segments where fast systemic uptake is required. Their products are familiar to emergency medicine procurement channels, making them a credible pathway for rescue therapies and emergency-use applications. Strategic implication: pairing atomizer technology with rescue therapeutics can accelerate acceptance in EMS and hospital formularies.
- Bespak — With a focus on combination product manufacturing and bespoke unit-dose solutions, Bespak is attractive for sponsors needing customization and regulatory partnership. Their emphasis on engineered combination products positions them well for controlled-release or specialty formulations. Strategic implication: consider Bespak for niche or differentiated dosing strategies where off-the-shelf components are insufficient.
- Silgan Dispensing — As a supplier of a broad range of nasal pumps and dispensing solutions, Silgan offers scale and packaging expertise, which supports high-volume consumer and retail-facing products. Strategic implication: large-scale launches targeting retail distribution will benefit from partners with robust packaging/assembly capability.
- Hovione — The CDMO model combined with device availability enables an integrated delivery from API through device formulation. Hovione’s recent announcement of a commercial intranasal dry powder platform signals strategic readiness to serve biologics and specialized formulations. Strategic implication: integrated CDMOs shorten development timelines and simplify regulatory dossiers for combination products.
- Kindeva Drug Delivery — With experience in nasal MDI and spray combination products, Kindeva sits at the intersection of respiratory delivery and device customization, useful for sponsors pursuing rapid systemic delivery with established inhalation know-how. Strategic implication: inhalation expertise translates into better aerosolization understanding for complex formulations.
- Nemera — Nemera’s focus on dry powder and nose-to-brain platforms, and recent partnership activity, position it as a strategic collaborator for companies pursuing CNS delivery via intranasal routes. Strategic implication: companies with CNS ambitions should assess Nemera for platform sharing or collaborative development.
- Aero Pump — Engineering-driven firm that offers precision pumps for specialized dosing needs. Their capabilities are relevant for sponsors requiring fine-grained dose control. Strategic implication: precision pump suppliers are critical when dose accuracy materially affects therapeutic index or regulatory acceptability.
Recent market signals that matter for 2026
- New clinical and commercial activity. Device suppliers are increasingly featured in clinical-stage programs and product launches — evidence that pharma sponsors prefer partners with documented device-clinical linkage.
- Platform commercialization. Several players announced platform availability for dry-powder and single-use devices in 2026, signaling rising commercial readiness for biologics and vaccines via the nasal route.
- Regulatory clarity. FDA activity has reaffirmed device classifications and approvals via 510(k) pathways for several intranasal devices. Updated labeling approvals for familiar rescue therapies (such as epinephrine and naloxone nasal configurations) are lowering the barrier for payers to accept nasal formulations in emergency care contexts.
- Reimbursement is becoming operational. In the U.S., reimbursement policies for approved intranasal products used in clinical settings are emerging, supporting the economics of adoption for hospital and emergency care pathways.
Strategic recommendations for executives — a 90‑day playbook
- Conduct a fast-track device partner audit — prioritize partners with clinical track records, regulatory dossiers, and scalable manufacturing.
- Develop a regulatory and evidence-generation roadmap that sequences device verification, biocompatibility, and targeted clinical endpoints to align with 510(k) or combination product requirements.
- Align commercial strategy to highest-probability channels in 2026 (emergency medicine, neurology clinics, respiratory care), and tailor value propositions for each channel.
- Model scenario-driven cashflows under conservative and upside adoption trajectories (our model provides ready-to-use templates).
- Prepare negotiation playbooks for OEM, licensing, or acquisition options to secure capacity and IP while minimizing dilutive risk.
Next step — get the granular intelligence
This briefing surfaces the structural drivers, competitive moves, and practical actions that matter for board-level decisions in 2026. For transaction teams, product leaders, and corporate strategists who require the underlying data and executable templates — including regional and application-level volumes, pricing sensitivities, supplier scorecards, and detailed channel economics — the full PW Consulting report delivers the confidential datasets and implementation playbooks needed to act decisively.
Contact PW Consulting to schedule a briefing where we will walk your team through the model, customize scenarios to your portfolio, and identify prioritized execution paths for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Intranasal Drug Delivery Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com