

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Party Supplies Market to Reach USD 25,300M by 2032; 8.5% CAGR

Party Supplies Market 2026: Strategic Imperatives and Actionable Insights for Decision Makers
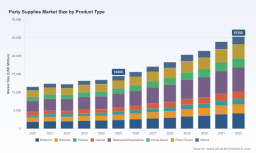
As companies prepare strategies for 2026, the party supplies sector presents a compelling mix of growth opportunity and operational complexity. Our latest PW Consulting study positions the global market at approximately USD 14.5 billion in the 2025 base year and projects an 8.5% compound annual growth rate (CAGR) into the 2026–2032 forecast window, culminating in a market north of USD 25 billion by 2032. These headline metrics underscore a resilient recovery from pandemic-related distortions and a clear structural expansion driven by changing consumer behaviours, retail channel evolution, and product innovation.
Party Supplies Market
Why this study matters to 2026 corporate decision-making
-
Timing investments with precision: An 8.5% CAGR is not uniform across value chains. For executives evaluating capital deployment—whether in manufacturing capacity, private-label launches, or e-commerce tech—our analysis offers scenario-calibrated demand curves that help prioritize near‑term spend without sacrificing optionality for 2027–2032 upside.
Party Supplies Market -
Translating macro momentum into defensible margins: Growth alone is insufficient where input-cost volatility and tariff shocks compress profitability. The report integrates margin-sensitivity modelling tied to raw material and freight fluctuations so pricing, hedging, and supplier contracting can be stress‑tested against realistic downside cases.
Party Supplies Market -
Shaping M&A and portfolio plays: Industry concentration metrics indicate meaningful scale advantages for top players while leaving white space for targeted consolidation. For corporate development teams, the study provides acquisition prioritization frameworks and accretion/dilution modelling tailored to party‑goods economics.
-
Operational resilience and supply‑chain playbooks: With documented quarterly volatility in raw material costs and fresh tariff regimes altering sourcing economics, operations leaders need concrete routing, nearshoring, and supplier diversification options. Our work maps practical levers—lead-time buffers, dual-sourcing triggers, and inventory segmentation rules—directly into procurement KPIs.
What the report delivers (practical, executable content)
-
Demand scenarios and forecasting engine: A calibrated forecast suite for 2026–2032 that supports bottom‑up SKU and channel planning; includes probability‑weighted scenarios (baseline, upside, downside) and an interactive toolset to run “what‑if” sensitivity to price, promotion, and macro shocks.
-
SKU profitability and assortment optimization playbook: Step‑by‑step frameworks to rationalize SKUs across retail and e-commerce channels, with templates for contribution-margin analysis, inventory-turn thresholds, and SKU lifecycle governance.
-
Supply‑chain stress tests and sourcing blueprints: Practical templates for supplier scorecards, total landed-cost calculators, and contingency sourcing maps that incorporate tariff scenarios and freight-rate oscillations.
-
Go‑to‑market and channel strategies: Tactical guidance for balancing big‑box, specialty retail, and direct‑to‑consumer channels; includes playbooks for private‑label acceleration, licensing partnerships, and promotional calendar planning aligned with consumer occasion data.
-
Regulatory and product safety checklist: A compliance toolkit for lead/cadmium restrictions, children’s product testing regimes, and labeling best practices—designed to minimize recall risk and preserve retail access.
-
M&A diligence templates and valuation comparables: A ready‑to‑use diligence checklist for acquisition targets, along with stylized valuation drivers and integration roadmaps that recognize the sector’s inventory and seasonality dynamics.
-
Sustainability and packaging pathways: Practical steps for decarbonizing product footprints, moving toward recyclable and compostable disposables, and quantifying trade‑offs between cost and brand value.
Competitive landscape: what leaders need to know
The sector today mixes heritage brands, diversified leisure-and-gifting groups, specialized manufacturers, and high-volume e-commerce players. Recent corporate events have already begun reshaping competitive dynamics: the restructuring and subsequent asset sale of a major nationwide retailer and legacy manufacturer has created an immediate re‑ranking of scale players and opened pockets of supply and brand inventory that agile firms can leverage.
Key incumbent strategies vary from integrated design‑to‑distribution models to licensed-character plays and high‑volume commodity manufacturing. Several patterns are consequential for 2026 strategy:
-
Consolidation windows are open: Market concentration statistics point to a mid‑tier aggregation opportunity. Thoughtfully executed acquisitions can deliver margin uplift through SKU rationalization, shared procurement, and channel cross‑selling.
-
Brand and IP remain valuable: Licensing relationships and proprietary designs continue to command pricing power in occasion-driven segments. Firms that can combine strong creative pipelines with efficient fulfillment will outperform.
-
Mass-market manufacturers must defend on cost and sustainability: Commodity producers face margin pressure from raw material volatility and tariff headwinds. Investments in process efficiency, nearshore sourcing, and greener materials are becoming table stakes.
-
Digital-first merchants will define convenience: E‑commerce growth and the expansion of omnichannel retail mean that convenience, assortment depth, and digital merchandising will be decisive for market share gains.
Headline market signals and tactical implications
-
Input-cost shocks are real and measurable. Supply‑chain volatility has driven material-price moves that can swing costs materially within a quarter; procurement teams must adopt dynamic repricing clauses and build hedging playbooks for critical inputs.
-
Tariff policy is altering sourcing math. New trade measures introduced in 2025 have already prompted sellers to shift sourcing strategies; companies should model sourcing networks under alternate tariff paths and pursue supplier diversification to preserve competitive pricing.
-
Regulatory compliance affects product design: State‑level prohibitions on heavy metals create test-and-certify requirements for children’s and seasonal products. R&D and quality teams should embed compliance gates early in product development to avoid costly rework or market exclusions.
-
Channel mix is evolving fast. E‑commerce penetration into the party‑goods category is accelerating, creating margin opportunities through direct selling but also elevating the importance of logistics economics and return-management capabilities.
-
Event and celebration spending remains a durable demand anchor. Consumer willingness to spend on experiences and occasions supports continued expansion, but spending patterns are becoming more occasion‑specific and premiumized in certain subsegments.
Strategic playbook for 2026
-
Prioritize supply‑chain optionality: Implement a tiered sourcing strategy that balances cost competitiveness with the ability to rapidly shift volume. Include geographic diversification, contractual penalties, and dual-sourcing triggers tied to price thresholds.
-
Move from assortment breadth to margin depth: Use SKU profitability frameworks to prune low-return items and reinvest in curated assortments that support higher margins and faster turns.
-
Embed compliance into product DNA: Adopt a “regulation‑by‑design” approach that aligns R&D, procurement, and testing to reduce launch friction and protect distribution channels.
-
Invest in differentiated omnichannel experiences: Combine digital merchandising, trade promotions, and experiential retail to capture the premium occasion shopper while defending base volumes in mass channels.
-
Evaluate targeted M&A for scale and capability: Seek bolt‑on assets that close capability gaps—fulfillment density, licensing portfolios, or sustainable materials expertise—over broad diversification.
What we leave for the full study
This introductory briefing highlights structural drivers, tactical levers, and competitive dynamics that should inform 2026 decisions. The full PW Consulting Party Supplies Market report contains the granular intelligence executives need to act: detailed segment-level forecasts, region-and-application breakouts, SKU-level margin matrices, competitor revenue benchmarks, and downloadable modelling templates. Pricing elasticities, channel-by-channel conversion curves, and supplier risk heat maps are available through the report’s interactive dashboards—essential inputs for transaction diligence and operational planning.
If your leadership team is preparing a budget, supply‑chain overhaul, or M&A pipeline for 2026, the comprehensive datasets and operational playbooks in our full report will convert insight into executable plans with measurable KPIs. Visit the source page to access the full dataset, scenario tools, and bespoke advisory options from PW Consulting’s party‑goods practice.
For detailed analysis of this topic, please visit the official page: Party Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com