

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Body Composition Analyzers Market to Reach USD 847.35M by 2032 at 6.98% CAGR

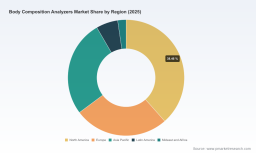
Body Composition Analyzers Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a concise, high‑signal briefing on the Body Composition Analyzers market that frames the strategic decisions organizations must take in 2026. This preview synthesizes our latest research — built on a 2025 base year, five years of historical tracking, and a forward forecast through 2032 — to clarify where value is forming, what risk vectors to mitigate, and which capabilities will differentiate winners. Think of this as a trailer: it demonstrates our analytical depth and the practical frameworks you need, while intentionally reserving the granular splits and proprietary scorecards for the full report.
Body Composition Analyzers Market
Market snapshot: the macro trajectory
The market for body composition analyzers has moved beyond niche clinical instrumentation to a multi‑channel industry serving hospitals, diagnostics labs, sports medicine, fitness/wellness centers, research institutions, and home users. Our base year assessment (2025) places the global market at approximately USD 536 million. From a recovery and growth phase that began in the early 2020s, the market is projected to expand at a compound annual growth rate (CAGR) of roughly 6.98% during the 2026–2032 forecast window, reaching an estimated market scale in the high‑800 million USD range by 2032.
Body Composition Analyzers Market
Two observations arise from these macro numbers: first, the sector presents steady, mid‑single‑digit expansion that favors long‑term capability investments (clinical validation, connectivity, service footprint). Second, growth is uneven by channel and technology — a dynamic that creates both pockets of rapid monetization and areas where incumbents are vulnerable to disruption.
Body Composition Analyzers Market
Why this research matters for 2026 strategic choices
-
Investment prioritization: With constrained capital budgets across healthcare and wellness organizations, leaders need a clear line of sight on which product types and go‑to‑market approaches produce durable returns. Our study translates macro growth into actionable priority areas for R&D, M&A, and sales deployment.
-
Procurement clarity for providers: Hospitals and clinics increasingly demand device reproducibility, regulatory provenance, interoperability with electronic records, and lifecycle service guarantees. Our frameworks enable procurement teams to evaluate devices not just on up‑front cost but on total cost of ownership and clinical utility.
-
Channel & business model design for vendors: As adoption shifts across clinical, fitness, research, and home settings, vendors must refine pricing, subscription, and partnership models to capture adjacent revenue streams (software analytics, managed services, consumables).
-
Regulatory and reimbursement positioning: Device approval status and code‑based reimbursement remain leading determinants of commercial traction. We map regulatory events and reimbursement levers against commercialization timelines so executives can sequence trials and market entries for maximal impact.
What the full report delivers (practical, operational content)
-
Robust market sizing and validated forecasts (2020–2032) with scenario analysis that isolates base‑case, upside, and downside outcomes — each accompanied by sensitivity drivers and break‑even timelines for new product introductions.
-
Granular segmentation by region, product type (e.g., bioimpedance analyzers, DXA systems, skinfold calipers, and others), and application channel (clinical/diagnostic, fitness/wellness, research/academic, home). The public preview omits the granular numeric splits; the report contains those tables and underlying model files for licensed users.
-
Competitive benchmarking with vendor scorecards — assessing product portfolio breadth, regulatory clearances, clinical evidence base, service network density, software ecosystems, and channel partnerships.
-
Go‑to‑market playbooks for manufacturers and distributors that include pricing band analysis, channel margin models, and 12‑ to 36‑month roll‑out calendars aligned to regulatory gates and reimbursement timing.
-
A regulatory and reimbursement playbook mapping device classifications, notable approvals, and payer coding opportunities with step‑by‑step recommendations for obtaining clinical acceptance and reimbursement coverage.
-
Acquisition and partnership target lists with rationale, valuation heuristics, and integration risks — oriented to both strategic acquirers and financial investors.
Competitive landscape: the players you must evaluate
The market exhibits moderate concentration, with the top three vendors representing a meaningful share and the top five increasing that concentration further. This structure produces a dual dynamic: dominant players can leverage scale to invest in clinical trials and global service, while midsize specialists can outmaneuver incumbents through niche clinical positioning and rapid product iteration.
-
Tanita Corporation (Itabashi‑ku, Tokyo) — A recognized name for FDA‑cleared, professional multi‑frequency BIA segmental analyzers targeted at clinical and fitness users. Tanita’s strength is regulatory equity combined with broad clinician recognition.
-
InBody Co., Ltd. (Seoul) — Noted for a range of professional BIA analyzers with strong reproducibility and a deep presence in hospitals and sports organizations. InBody’s repeatability and clinical adoption are key purchase drivers.
-
Hologic, Inc. (Marlborough, Massachusetts) — A leader in DXA‑based whole‑body composition and bone density systems, Hologic’s Horizon DXA is a standard in many clinical settings where high precision is required.
-
OMRON Corporation (Kyoto) — Focused on Bluetooth‑enabled body composition monitors that bridge consumer wellness and clinical applications; OMRON’s distribution footprint in retail and home markets is a competitive advantage.
-
Seca GmbH & Co. KG (Hamburg) — Known for its medical BIA mBCA series, Seca combines precision hardware with integrated anthropometry tools targeted to hospitals and clinics.
-
Bodystat Ltd. (Isle of Man) — A specialist in portable BIS/BIA analyzers, Bodystat competes on device portability and speed of measurement for both medical and fitness use cases.
-
RJL Systems, Inc. (Clinton Township, Michigan) — Offers clinically validated BIA instrumentation, with a focus on whole‑body and segmental analysis and a legacy in clinical research settings.
Our full profiles identify each vendor’s technical differentiators, regulatory pathway status, service footprint, and commercial strengths — enabling competitive response and partnership evaluation. The report also contains a vendor matrix linking feature‑sets to application scenarios and procurement checklists.
Regulatory & reimbursement developments shaping 2026 actions
-
Regulatory density: Our analysts track hundreds of registered devices and active clearances in the U.S. alone. As of our latest review, over 400 body composition devices are registered with the U.S. FDA — a signal of both market maturity and ongoing regulatory activity.
-
Reimbursement levers: CPT code availability for whole‑body bioelectrical impedance assessment remains a material commercial enabler for clinical adoption; organizations that align clinical studies and coding submissions can accelerate hospital uptake.
-
Recent approvals: Clinical trust is reinforced by new clearances and conformity markings. Examples include notified clearances and CE approvals for leading systems — each of which shortens sales cycles in regulated markets and influences procurement decisions.
Strategic recommendations for 2026 (executive checklist)
-
For manufacturers: Prioritize clinical validation and regulatory sequencing in target geographies. Invest in interoperable software and cloud analytics to convert device sales into recurring revenue streams. Consider selective partnerships with electronic health record vendors to embed body composition outputs into care pathways.
-
For healthcare providers: Evaluate devices on reproducibility and integration, not just sticker price. Adopt a lifecycle procurement approach that includes warranty, calibration, and training. Leverage reimbursement codes with evidence‑based protocols to offset acquisition costs.
-
For investors and M&A teams: Target companies with proprietary clinical datasets, regulatory approvals in place, and differentiated software platforms. Expect consolidation among device manufacturers as scale becomes critical for global service and clinical trial support.
-
For fitness and consumer wellness operators: Focus on continuity of care — devices that feed longitudinal analytics and enable coaching monetization outperform stand‑alone hardware in retention and ARPU metrics.
How to use this preview
This preview demonstrates the strategic lenses we apply: rigorous market sizing, vendor benchmarking, regulatory mapping, and executable go‑to‑market playbooks. If your team needs to underwrite a product launch, prioritize an acquisition, or restructure sales and service territories for 2026, the full PW Consulting Body Composition Analyzers report provides the models, vendor scorecards, and step‑by‑step implementation tools required to convert insight into measurable outcomes.
To preserve the value of the work for our clients, we have intentionally withheld the granular regional and application numeric splits, the full vendor share table, and the downloadable financial model from this public preview. These deliverables are included in the licensed report and are designed to plug directly into corporate planning workflows.
Next steps
-
Request the full report to obtain the detailed segmentation tables, interactive forecast model, and vendor scorecards.
-
Book a briefing with our advisory team to align the report findings to your 2026 planning cycle and to receive a tailored action plan for product, market, or investment initiatives.
PW Consulting’s Body Composition Analyzers research equips executives with the analytical clarity and operational tools necessary to make confident, high‑impact decisions in 2026. For organizations seeking to move from observation to execution, the full report is where the roadmap and the implementation templates live.
For detailed analysis of this topic, please visit the official page: Body Composition Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com