

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Luxury Sunglasses Market to Hit $19.78B by 2032 at 4.59% CAGR

Luxury Sunglasses Market — Strategic Outlook for 2026 Decision-Making
As companies prepare budgets, M&A roadmaps, product pipelines, and go-to-market plays for 2026, the luxury sunglasses market presents a balanced mix of steady growth, strategic consolidation, and disruptive technological and regulatory pressures. This briefing—drawn from PW Consulting’s comprehensive market study, base year 2025, historical window 2020–2025 and forecast horizon 2026–2032—highlights the high-level implications executives must weigh now. The full report contains the granular charts, segment tables, and scenario spreadsheets that underpin the conclusions summarized below.
Luxury Sunglasses Market
Market trajectory and what it means for 2026 plans
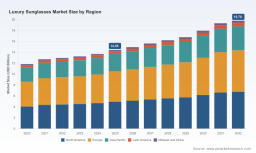
Across the five-year historical period through 2025 the global luxury sunglasses market expanded consistently, reaching a market size of USD 14.45 Billion in the base year. Our forecast window (2026–2032) projects continuation of that growth at a compound annual growth rate (CAGR) of 4.59%, bringing the market to roughly USD 19.78 Billion by 2032 under the baseline scenario.
Luxury Sunglasses Market
For corporate planners, the takeaway is twofold. First, the market is large and predictable enough to justify multi-year investments in brand-building, premium product lines, and supply-chain optimization. Second, growth is not explosive; it rewards disciplined capital allocation and strategies that extract margin through product differentiation, channel control, and cost containment rather than betting on blue‑sky volume expansion alone.
Luxury Sunglasses Market
Competitive structure and strategic consequences
The competitive landscape shows meaningful concentration among leading players, with the top three and top five firms controlling significant shares of the market (CR3 and CR5 at 48.5% and 65.2% respectively). That structure creates both constraints and opportunities for new entrants and incumbents:
- Incumbents benefit from scale in licensing, global distribution, and brand equity—advantages that translate into negotiating power with retailers, preferred access to premium materials, and higher tolerance for short-term price volatility.
- Mid-sized and niche firms can still win by specializing (material craftsmanship, regional cultural resonance, limited-edition drops) and by owning superior DTC experiences and creative collaborations.
Key firms to watch include EssilorLuxottica, the group whose brand and licensing portfolio covers household names and designer collaborations; Italian manufacturers such as Marcolin, De Rigo and Safilo, which combine manufacturing heritage with global license partnerships; and artisanal or boutique players like Garrett Leight and Oliver Peoples that trade on craft, provenance, and selective distribution. Each archetype implies different strategic moves for competitors and partners: from defensive licensing and scale investments to targeted partnerships, white-label production agreements, or acquisitions to gain heritage credentials.
Notable corporate moves and regulatory noise shaping 2026
Recent developments through mid‑2026 emphasize three themes that should be central to corporate strategy next year: premiumization via designer partnerships, technology integration, and tariff-driven cost pressure.
- Design & licensing: Major players continue to lock in long-term licensing deals and capsule collections with luxury houses, reinforcing premium positioning and customer lifetime value. Such partnerships remain high-return plays for companies that can manage production quality and channel control.
- Technology & product innovation: The incorporation of smart/AI-enabled features into eyewear is transitioning from novelty to a product line consideration for mainstream luxury brands. Early waves of hybrid offerings (optical prescription frames with digital features) create adjacent revenue pools and new after-sale service models.
- Tariffs & trade policy: Elevated import duties on optical products—together with episodic policy pauses and unpredictable reciprocal measures—have materially affected landed costs and pricing strategies. Some legacy producers have already moved to mitigate exposure through price increases and supplier diversification.
These dynamics are exemplified by public actions in the market: multi-year licensing renewals, high-profile capsule collections, expansions of AI/glasses portfolios targeted at prescription wearers, and price adjustments implemented to offset tariff impacts. Executives must plan for continued regulatory volatility while exploiting design and tech as sources of differentiation.
What the PW Consulting report offers (practical content)
Our full study was designed as a decision-making toolkit for 2026. It blends rigorous quantitative forecasts with practical, executable guidance:
- Market sizing and validated forecast models across multiple scenarios (baseline, downside, upside) calibrated to tariff, channel, and macroeconomic permutations;
- Channel economics and margin waterfall analyses for wholesale, retail, and direct-to-consumer (DTC) models, identifying where margin can be recovered or enhanced;
- Supply-chain stress tests and sourcing playbooks—evaluating nearshoring, dual-sourcing, and inventory strategies to manage high-duty exposure;
- Consumer segmentation and purchase-motive matrices that translate psychographics into product and price strategies (note: the report contains the segment-level shares and elasticity estimates omitted from this preview to preserve commercial value);
- Product roadmap guidance, including how to integrate smart features without cannibalizing classic premium lines, and material-sourcing recommendations for sustainable, high-margin offerings;
- M&A and partnership screeners—financial thresholds and cultural fit heuristics for deals that accelerate scale, augment brand portfolios, or secure manufacturing competence;
- Operational playbooks for retail footprint optimization and omnichannel orchestration, with KPIs, pilot templates, and a 12–24 month rollout calendar;
- Primary interview summaries and supplier scorecards that validate costs, lead times, and quality differentials used in our forecast models.
We deliberately present the high-level recommendations here while retaining the full tables and sensitivities behind the paywall so decision-makers can test moves against their unique P&L assumptions.
Strategic priorities for 2026
Based on the intersection of steady CAGR, market concentration, product innovation, and tariff risk, we advise leaders to prioritize six actions in 2026:
- Institute a tariff-response program: model landed-cost scenarios, negotiate contractual protections with suppliers, and implement staged price actions tied to clear cost triggers;
- Double down on premiumization where your brand equity supports it—limited editions, luxury licenses, and craft-backed product stories enhance margins and reduce price elasticity;
- Accelerate selective tech integration: pilot AI/smart eyewear in core markets with controlled production runs and service bundles to evaluate willingness-to-pay and brand fit;
- Optimize omnichannel economics by reallocating capex to high-ROI DTC experiences and using wholesale selectively as a distribution amplifier rather than a margin sink;
- Pursue bolt-on M&A or licensing that fills capability gaps—manufacturing, optical tech, or prestige labels—while maintaining strict integration criteria and return hurdles; and
- Embed sustainability and traceability into premium narratives: consumers of luxury are increasingly sensitive to provenance, which can justify price premiums and reduce reputational risk.
Risks, sensitivities, and scenario levers
Although growth is steady, the luxury sunglasses market is sensitive to a limited set of high-impact variables:
- Trade policy volatility—sudden tariff adjustments or retaliatory measures can compress margins quickly; companies should hold contingency pricing and supply plans ready;
- Consumer discretionary cycles—premium eyewear sits in discretionary spend pockets and will bend with broader luxury consumption trends;
- Platform & distribution disruption—shifts in social commerce, resale channels, and vertical DTC brands can alter competitive placement rapidly;
- Technological missteps—over-investing in tech-enabled eyewear before clear consumer acceptance may dilute core brand equity and tie up capital.
Our scenario analysis—available in the full report—quantifies the P&L implications of these levers and prescribes triggering conditions for defensive vs. offensive moves.
How to use this intelligence in boardroom decisions
Executives should use the study to inform four board-level decisions in 2026: capital allocation (where to invest vs. conserve), pricing strategy (dynamic vs. fixed), channel mix (which channels to double down on), and inorganic growth (targets and timing). The report’s models allow custom inputs so leadership teams can run their own sensitivity analyses and produce credible, data-backed plans for investors and lenders.
Next steps
This preview demonstrates the depth and orientation of PW Consulting’s Luxury Sunglasses Market study: rigorous modeling, actionable playbooks, and scenario-tested strategic recommendations. To access the full dataset, segmentation tables, and our proprietary forecast workbook—including the detailed sensitivities on tariffs, channels, and consumer segments—please consult the report landing page or contact your PW Consulting representative. The full intelligence package is designed to be plug-and-play for 2026 planning cycles and to support rapid decision-making under uncertainty.
In markets where growth is steady but risks are concentrated, strategic clarity wins. The decisions companies take in 2026 about sourcing, partnerships, and product architecture will determine who captures the next wave of premium margin expansion in the luxury sunglasses category.
For detailed analysis of this topic, please visit the official page: Luxury Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com