

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
PW Consulting: Silicon Nitride (CAS 12033-89-5) — $113M in 2025, 7.1% CAGR to 2032
By pmarketresearch, 2026-07-30
Silicon Nitride (CAS 12033-89-5) Market: Strategic Primer for 2026 Decision‑Makers
Market snapshot — what the numbers tell you (without giving your competitors everything)
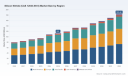
The silicon nitride (Si3N4) market is no longer a niche materials story; it is a maturing, capital‑intensive ecosystem that is moving from specialty applications toward scaled industrial adoption. Our market model (base year 2025; historical 2020–2025; forecast 2026–2032) shows steady, mid‑single‑digit to high‑single‑digit growth driven by demand resilience in bearings, advanced automotive components, medical implants, and select electronics manufacturing uses. Measured in USD Million, the market expanded materially across the 2020–2025 period and, under our base forecast, continues to compound at a 7.1% CAGR through 2032 to reach a substantially larger global revenue pool.
Silicon Nitride (CAS 12033-89-5) Market
These headline metrics matter for 2026 planning because they convert an otherwise technical materials conversation into a portfolio-level commercial opportunity: predictable topline expansion, concentrated supplier economics, and accelerating pockets of system-level adoption (notably medical devices and high-performance mobility components). We intentionally present the macro trajectory here to allow strategy teams to size the opportunity quickly while reserving the granular segmentation and proprietary unit economics for the full PW Consulting study.
Silicon Nitride (CAS 12033-89-5) Market
Why this research is strategically valuable for 2026 decisions
-
Translate materials science into business outcomes — The market’s trajectory means Si3N4 moves from a specialty raw material to a strategic lever for product differentiation (wear life, thermal stability, biocompatibility). R&D and product teams need a clear translation of material performance into commercial KPIs: cost per cycle, warranty exposure, and service interval economics.
Silicon Nitride (CAS 12033-89-5) Market -
Procurement and supply resilience — With a supplier base that includes entrenched Asian and European producers, procurement teams must plan for purity‑driven sourcing strategies, dual‑sourcing constraints, and potential premium pricing windows driven by raw material specifications.
-
Regulatory and clinical inflection points — Regulatory clearances (notably in medical devices) create first‑mover advantages and new TAMs. Understanding the timing and practical implications of approvals is essential to prioritize commercialization investments in 2026.
-
M&A, JV and vertical integration signals — Given moderate market concentration and technology differentiation, corporate development teams can identify targets for bolt‑on capability (powder synthesis, sintering, device manufacturing) that accelerate time to market.
What the PW Consulting report contains — operationally useful deliverables
-
Proprietary market model (2020–2032) with revenue forecasts by type, application and region, scenario sensitivity and breakouts by production vs. component value capture. (Note: granular splits are reserved for report subscribers.)
-
Price and margin benchmarking — supplier price bands, raw material cost drivers, and indicative manufacturing cost curves for common ceramic processing routes.
-
Technology roadmap and adoption timeline — comparative analysis of sintering routes, reaction‑bonded vs. hot‑pressed approaches, and the practical performance tradeoffs in volume production.
-
Regulatory impact and go‑to‑market playbooks — assessment of medical device pathways, certifications, and how regulatory clearances change demand profiles for FDA‑registered manufacturing capacity.
-
Supplier and capability map — verified supplier profiles, strategic strengths, capacity constraints, and an assessment of where value is captured along the powder‑to‑component chain.
-
M&A and partnership scanner — targets categorized by technology, geostrategy, and integration fit; an outcomes matrix showing time‑to‑value for 12‑ and 36‑month investment horizons.
-
Risk heatmap and mitigation playbook — supply shocks, regulatory delays, feedstock shortages, and tactical procurement/hedging options.
Competitive landscape — actionable intelligence on the key players
-
Japanese producers (UBE, Denka, KYOCERA) — These firms dominate the high‑purity powder space and are notable for tight quality control on metallic impurities and oxygen content. Their product portfolios span semiconductor‑grade to industrial grades and their pricing reflects purity tiers. Strategic implication: buyers seeking medical or semiconductor‑grade feedstock should prioritize early qualification and build supply continuity agreements with Japanese suppliers or equivalent capable alternatives.
-
European specialists (AlzChem, H.C. Starck, CeramTec, Saint‑Gobain) — These players compete on specialized chemistries and value‑added components (e.g., hot‑pressed structural ceramics). Their strengths lie in engineered grades for automotive and aerospace and in established relationships with tier‑1 industrial customers. Strategic implication: technology licensing, co‑development and component outsourcing are practical routes for OEMs looking to accelerate adoption without large capex for new ceramic lines.
-
SINTX Technologies (U.S.) — The company is unique in a regulatory sense: it operates the only FDA‑registered silicon nitride medical device manufacturing facility and has taken medical device approvals through the 510(k) pathway. That regulatory moat enables commercial entry into implant markets with a first‑mover advantage for certain orthopaedic applications. Strategic implication: medical device OEMs and investors should treat SINTX’s regulatory progress as a market architect — either as a partner or as a competitive risk to mitigate through clinical differentiation.
-
Chinese producers (e.g., Hebei Suoyi) — These vendors offer competitive pricing on standard grades and are scaling capacity for commodity applications (refractories, low‑spec bearings). Strategic implication: cost‑sensitive applications can lean on competitively priced standard grades, but quality gating and downstream warranty exposure must be managed through tightened incoming inspection and process controls.
Key recent developments and their implications
-
Regulatory milestone: SINTX’s 510(k) journey — In mid‑2025 SINTX submitted a 510(k) for silicon nitride osteotomy wedges and received clearance in October 2025 for a foot & ankle osteotomy wedge system. For 2026 planning, this converts a previously “emerging” clinical use case into a commercially addressable market segment with payment, distribution and liability dynamics that differ from non‑implant uses.
-
Supply and pricing dynamics — Japanese producers’ dominance in high‑purity powder creates a two‑tier market. High‑purity grades (metallic impurities <50 ppm, oxygen <1.5 wt%) command premium pricing; standard grades (materially higher impurity thresholds) are available at materially lower price points. The pricing spread establishes both margin pools and substitution thresholds: when engineering specs allow, buyers can materially reduce material costs by qualifying lower grades.
-
Consolidation signals — Market concentration is meaningful but not concentrated to monopoly levels: the top three vendors capture a meaningful share (CR3 ~36.5%) and the top five ~42.0% (CR5). This structure creates room for strategic alliances, selective M&A and niche incumbency rather than full oligopoly pricing power.
Strategic playbook for executives in 2026
-
Procurement: implement a tiered sourcing strategy that matches powder grade to application risk profile. Qualify at least one high‑purity supplier and one cost‑effective standard supplier to create optionality.
-
R&D: prioritize validation plans that translate Si3N4 material benefits into warranty and lifecycle KPIs. For medical and safety‑critical mobility applications, align clinical/regulatory milestones with product launch and commercial forecasting.
-
Corporate development: build M&A screening criteria that favor firms with either regulatory assets (e.g., FDA‑registered manufacturing) or unique powder synthesis IP. Expect near‑term value creation from bolt‑on capabilities that shorten qualification timelines.
-
Manufacturing: evaluate CAPEX for sintering and machining capacity only after mapping the total addressable component margin. In many cases, partnering with established component houses accelerates time to revenue more cost effectively than greenfield builds.
How to use the PW Consulting study in 90 days
-
Week 1–2: Executive readout — Use our macro snapshot and supplier matrix to align leadership on opportunity size and strategic priorities.
-
Month 1: Procurement deep‑dive — Deploy our price benchmarks and supplier capability map to issue a two‑tier RFP and begin supplier qualifications.
-
Month 2–3: Commercial decision — Combine our regulatory timeline and adoption scenarios with internal product roadmaps to set launch windows and investment approvals.
Next step — where the hidden detail lives
This primer intentionally surfaces the strategic implications, supplier archetypes, regulatory inflection points and headline economics (2020–2025 historical trends; base year 2025; forecast 2026–2032 at a 7.1% CAGR). It does not disclose the full, actionable segmentation matrices, regional breakdowns, or per‑application revenue shares that underpin our commercial recommendations — those are preserved in the full PW Consulting report and our model files to protect client value and ensure robust use of our IP.
If you are evaluating entry, procurement, or M&A in Si3N4 for 2026 planning, the complete study provides the calibrated segmentation, supplier scorecards, unit‑cost build‑ups, and policy/regulatory annexes needed to make confident, executable decisions. Contact PW Consulting for access to the full report and the model to run your custom scenarios.
For detailed analysis of this topic, please visit the official page: Silicon Nitride (CAS 12033-89-5) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
South East Asia Additive Masterbatch Market to Hit USD 241.3M by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-30
South East Asia Additive Masterbatch Market: Strategic Preview for 2026 Decision-Makers
As plastics value chains in Southeast Asia evolve under pricing pressure, regulatory change and rising demand for functional and recyclable polymers, additive masterbatches sit at the intersection of product performance, cost management and sustainability. This introduction summarizes the strategic value of PW Consulting’s South East Asia Additive Masterbatch Market study for teams making 2026 investment, sourcing and product decisions. It highlights the market trajectory, competitive topology, key dynamics and the practical, decision-ready tools included in the full report—while preserving the granular segment-level figures to encourage direct access to our datasets and models.
South East Asia Additive Masterbatch Market
Market trajectory at a glance
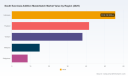
Measured on a consistent base-year (2025), the South East Asia additive masterbatch market has shown steady expansion through the historical window (2020–2025) and continues on a multi-year growth path. Our modeled market size increases from USD 120 Million in 2020 to USD 158.5 Million in 2025, with the near-term projection of USD 170.3 Million for 2026 and a continuing rise to USD 241.3 Million by 2032. This trajectory corresponds to a compound annual growth rate (CAGR) of 6.5% over the forecast period (2026–2032).
South East Asia Additive Masterbatch Market
These macro trends matter: they set the envelope for capacity planning, working capital needs, and the potential scale for new product launches or plant siting decisions. The combination of consistent mid-single-digit growth and pronounced regional heterogeneity creates both low-risk uplift and numerous differentiated playbooks for incumbents and new entrants alike.
South East Asia Additive Masterbatch Market
Why this research is strategically important for 2026
- Timing capital allocation. The report aligns demand projections and scenario variants with capex timing windows, helping executives decide whether to phase expansions, pursue bolt-on capacity or prioritize modular platforms that can be deployed quickly in response to local demand spikes.
- Cost-to-serve optimization. By modeling input-price pass-through and freight sensitivities, the study gives procurement and commercial leaders an evidence base for negotiating supply contracts, setting surcharge policies and re-balancing local vs. imported sourcing.
- Regulatory risk mitigation. With tighter restrictions on certain additive chemistries, the analysis provides options for reformulation, substitution and premium-priced compliant alternatives—vital for customers in food contact, medical and automotive segments.
- Commercial prioritization. Sales and product teams can use our scenario outputs to prioritize applications, customer segments and channel strategies that maximize margin and minimize inventory risk in 2026.
Key market dynamics shaping 2026 decisions
- Upstream resin volatility and feedstock inflation remain primary margin drivers. Industry data shows episodes of sharp masterbatch price spikes tied to polymer resin swings and periodic transport surcharges. Procurement teams should plan hedging and flexible contract mechanisms into 2026 budgets.
- Regulatory tightening across the region is constraining formulation choices and accelerating demand for compliant additive packages. This creates a premium for R&D-enabled, low-risk formulations and gives innovators first-mover advantage in key value chains.
- Logistics and trade-policy noise—short-term freight shocks, transport surcharges and tariff changes—are increasing the cost of cross-border pigment and carrier resin flows. Nearshoring and regional distribution hubs are therefore a higher-return mitigation strategy for many players.
- Labor and operating-cost pressures in select countries are compressing margins for commodity-focused operators, while vertically integrated or specialty producers retain differentiation through technical service and tailored formulations.
Market structure and concentration — strategic implications
The market exhibits a high degree of concentration at the top: the three largest producers account for roughly three quarters of market share, while the top five capture close to 85%. For decision-makers this implies:
- Price leadership and capacity moves by the largest players will materially affect regional pricing and service levels—monitoring competitor capex and plant utilization is essential.
- Smaller, nimble producers can compete on customization, speed-to-market and customer intimacy, offering partnership opportunities for downstream processors seeking differentiated formulations.
- M&A and JV activity is likely to remain an efficient route to scale or to secure specialty chemistries—particularly for firms aiming to move quickly into compliance-driven product categories.
Competitive landscape: profiles and practical takeaways
Our research examines the strategic posture and capabilities of both regional specialists and global suppliers active in Southeast Asia. Highlights include:
- US Masterbatch Joint Stock Company (Hanoi) — regional exporter and specialist in additive masterbatches, with a product set oriented to UV stabilizers, flame retardants and process aids. Strategic implication: attractive partner for regional processors seeking localized technical support and export logistics into ASEAN corridors.
- PMJ Greentech Joint Stock Company (Vietnam) — emphasis on additive and filler masterbatches with customization capability. Strategic implication: strong candidate for co-development projects where customer-specific desiccant or PPA solutions are required.
- Tosaf Compounds Ltd (Israel) — global supplier with a history of cross-regional supply; recent capacity expansion activity signals strategic diversification of production footprint. Strategic implication: watch for competitive pressures on premium packaging and industrial segments as global players broaden local supply.
- TPI Polene (Thailand) — integrated compounder with masterbatch offerings aligned to films and lamination markets. Strategic implication: vertically integrated players may offer cost and supply advantages for large converters; evaluate tradeoffs between price, technical service and lead times.
- SCG Chemicals (Thailand) — strong R&D and product breadth, with focus on color masterbatch and functional enhancements for higher-spec applications. Strategic implication: incumbents with broader polymer portfolios can cross-sell and justify premium pricing for technical solutions.
- Specialist local players (e.g., Thaipoly, Chokdee) — focus on color matching and functional additives for consumer goods. Strategic implication: attractive acquisition or distribution partners for brands prioritizing speed-to-market and close service relationships.
Recent industry moves reinforce these competitive dynamics. A notable capacity expansion by a major global supplier in 2026 and a breakthrough product enabling recyclable PET closures underline that both scale investments and circular-economy innovation will be decisive themes through 2026.
What the full report contains (practical, executable modules)
- Market model with baseline and two alternate scenarios (conservative, upside) through 2032, including sensitivity analysis to resin price, freight and regulatory shock events.
- Price matrix and cost-to-serve templates enabling direct input of company-specific purchasing terms and logistics profiles to produce tailored margin projections.
- Supplier and competitor scorecards covering product breadth, technical service, capacity, and strategic intent—designed to support partnership selection, JV diligence and M&A screening.
- Regulatory impact mapping that links additive chemistries to country-level compliance windows and reformulation lead times.
- Commercial playbooks for five archetypal go-to-market strategies: export-led scaling, regional hubbing, vertical integration, premium technical service, and sustainability-first product lines.
- Investment cases with NPV and payback calculations for brownfield expansions, greenfield plants and strategic minority investments—plus a list of shortlist targets and red-flags for deal teams.
- A downloadable Excel model and a slide-ready executive summary tailored for board-level decision-making.
How to use these insights to act in 2026
- Prioritize capex that is modular and reversible. Given freight and input-price volatility, modular capacity reduces downside and accelerates break-even in a mid-single-digit growth market.
- Hedge input exposure through blended procurement strategies: secure long-term access to carrier resins while leveraging spot markets for pigments where feasible.
- Invest in product reformulation and validation for compliance-sensitive applications now—regulatory-driven premium demand will outpace commodity segments.
- Build distribution or toll-manufacture agreements in target countries to reduce transport surcharges and tariff exposure while preserving the ability to serve national champions.
- Pursue partnerships with local specialists for rapid customer onboarding; use M&A selectively to acquire proprietary additive chemistries or to scale quickly in priority sub-markets.
- Embed circularity into the product roadmap—solutions that enable recyclability or closed-loop collection are becoming procurement filters among large brand owners.
Executive checklist for 2026
- Have you stress-tested margin performance at ±20% resin price movement and factoring in potential freight surcharges?
- Is your product pipeline compliant with the most restrictive regional additive regulations expected in the next 18–24 months?
- Do you have contingency plans for supplier disruption in pigment and carrier resin sourcing?
- What is your target share of top-tier customers vs. long-tail processors, and does your commercial model support the service expectations of each?
- Are you tracking competitor capacity moves and consolidation signals that could pressure price or create acquisition opportunities?
PW Consulting’s full South East Asia Additive Masterbatch Market report delivers the data, scenario models and tactical playbooks required to make high-confidence commercial, operational and investment decisions in 2026. For the detailed segment breakdowns, company scorecards, downloadable financial models and the complete set of decision-support tools, please consult the full report—designed specifically to move teams from insight to execution within 90 days.
For detailed analysis of this topic, please visit the official page: South East Asia Additive Masterbatch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: X-ray Radiation Protection Glass Market to hit USD 368.47M by 2032 (8% CAGR)
By pmarketresearch, 2026-07-30
Medical X-ray Radiation Protection Glass Market: Strategic Briefing for 2026 Decisions
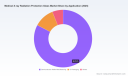
PW Consulting’s new market study on Medical X‑ray Radiation Protection Glass frames the commercial and regulatory inflection points that will shape supplier and buyer strategy in 2026. Built on a 2020–2025 historical base (base year 2025) and projecting through 2026–2032, the study models an industry expanding at an 8.0% CAGR. The global market stands at approximately USD 215.0 Million in 2025 and is projected to grow to the mid‑hundreds of millions by 2032 under the base forecast. This briefing highlights the research’s decision‑support value for capital allocation, product positioning, M&A, and procurement strategy—while preserving the granular segment tables and vendor scorecards that are available in the full report.
Medical X-ray Radiation Protection Glass Market
Why this study matters for 2026
-
Consolidated demand signal: Diagnostic and interventional imaging workloads, replacement cycles for aging radiology infrastructure, and increased regulatory scrutiny are converging to create predictable, multi-year demand for certified radiation‑protective glass and integrated shielding systems.
Medical X-ray Radiation Protection Glass Market -
Regulatory regime shift: New EU standards and updated national certification procedures implemented in 2025 materially raise compliance requirements for lead‑based and alternative shielding materials. Buyers and suppliers who can demonstrate certification readiness will capture higher‑margin tenders.
Medical X-ray Radiation Protection Glass Market -
CapEx timing and reimbursement pressure: Healthcare reimbursement and coding changes for 2026 are driving tighter capital discipline in many systems. Procurement teams will prioritize modular, low‑disruption retrofit solutions and vendors that can offer turn‑key installation and certification services.
What’s in the full report (operational deliverables)
-
Market sizing and validated forecast models (2020–2032) in USD Million with scenario sensitivity for regulatory tightening and raw‑material pricing.
-
Demand drivers mapped by procurement channel (hospitals, diagnostic centers, OEMs) and buyer persona definitions for radiology directors, hospital engineers, and procurement officers.
-
Regulatory and certification matrix covering national standards, EU 2025 changes, and recommended compliance checkpoints for procurement contracts.
-
Supply chain and cost‑to‑serve analysis: raw material exposure, fabrication bottlenecks, lead time ladders, and a contractor readiness assessment for professional installation services.
-
Competitive vendor scorecards, go‑to‑market playbooks, pricing archetypes, and an M&A playbook identifying consolidation vectors (technology, capacity, geographic footprint).
-
Excel deliverables: fully auditable financial model, unit cost simulator, and procurement negotiation templates for 3‑, 5‑, and 7‑year contracting horizons.
Note: This brief deliberately omits granular split tables (regional, type and application line items) to preserve the “trailer” effect. The full segmentation detail and drill‑downs are accessible via the PW Consulting report landing page.
Key macro takeaways and strategic implications
-
Market growth profile: With an 8.0% CAGR and clear year‑on‑year expansion from the 2025 base, suppliers should evaluate capacity investments and product roadmaps to avoid reactive price escalation. Buyers should lock multi‑year pricing or service agreements where possible to stabilize budgets.
-
Fragmentation and consolidation potential: The market concentration is low—three‑firm and five‑firm concentration ratios (CR3 ~24.6%, CR5 ~26.2%) indicate a fragmented supplier base. That fragmentation creates acquisition opportunities for vertically integrated players or regional champions seeking scale and margin control.
-
Service‑differentiation is decisive: Professional installation, certification documentation, and warranty‑backed performance are premium purchase criteria. Vendors offering bundled project management, on‑site certification testing and rapid retrofit services will command higher win rates.
-
Regulation as a barrier and an opportunity: Tighter EU and national standards implemented in 2025 raise the procurement bar. Suppliers that invest early in test laboratories, certification pipelines and compliance documentation will convert regulatory friction into commercial advantage.
-
Material and technology transition: Advances in multilayer systems and lead‑equivalent innovations are emerging. Early commercialization of alternatives with demonstrable performance and installation economies can disrupt legacy lead‑glass incumbency—especially in jurisdictions moving towards restricted lead usage.
Competitive landscape: profiles and strategic reads
The competitive set is a mix of legacy glass manufacturers, niche fabricators, and system integrators. Below are focused strategic reads on the market’s core players.
-
Corning Incorporated (Corning, New York): A legacy materials leader with the Corning Med‑X family, Corning’s high lead/barium formulations are a standard in medical X‑ray protection. Strategic advantage: deep material science, scale manufacturing, and an established reputation in hospital procurement. Consideration: incumbency brings pricing power but requires proactive regulatory-proofing and service partnerships to defend retrofit opportunities.
-
SCHOTT AG (Mainz, Germany): SCHOTT’s German‑manufactured RD 30 variants position the firm strongly in regulated environments and safety‑critical installations. Strategic advantage: European certification pedigree and diagnostic market trust. Consideration: must broaden installation and service capabilities to capture bundled tenders from hospital groups.
-
Ray‑Bar Engineering Corporation (Azusa, California): A flexible manufacturer of lead glass and custom laminated solutions with LEED compliance support. Strategic advantage: customization and sustainability credentials. Consideration: scale constraints—strategic alliances with regional installers will improve national account penetration.
-
Ward’s Premise Ltd (Thames Ditton, UK): Distributor and integrator for branded medical glasses, acting as a channel specialist in the UK and select export markets. Strategic advantage: channel reach and project management; potential acquirer candidate for manufacturers seeking direct distribution.
-
MAVIG GmbH (Germany): Offers window and panel systems integrated into X‑ray protection assemblies and mobile shields. Strategic advantage: product systems approach and focus on mobile/ERPD devices. Recent update: Apr 2026 product catalog refresh introduced new mobile shields—an immediate response to retrofit demand for emergency and hybrid suites.
-
Wolf X‑Ray Corporation (US): Specializes in mobile barriers and radiation safety glass for clinical environments. Strategic advantage: nimble manufacturing and project turnarounds for decentralized imaging sites.
-
Radiation Protection Products, Inc. (US): Offers lead‑lined and laminated safety glass with emphasis on impact resistance and optical clarity. Strategic advantage: specification fit for trauma and high‑visibility control booths.
-
Lead Glass Pro (US): Regional manufacturer and installer with recent capacity expansion. Recent development: December 2025 manufacturing expansion and broader installation footprint across 26 states—an aggressive growth move that signals consolidation at the regional level.
Recent developments and strategic implications
-
MAVIG’s April 2026 catalog update indicates a near‑term shift toward mobile shielding products—an attractive segment for hospitals seeking low‑disruption retrofits and rapid deployment.
-
Lead Glass Pro’s late‑2025 expansion demonstrates that regional players can scale quickly to meet national retrofit demand, making them attractive partners or targets for manufacturers lacking direct installation capabilities.
-
H V Skan’s multilayer glass innovation (Dec 2025) underscores the technology risk for legacy lead compositions; incumbents and private equity should prioritize R&D screening and technology scouting.
Risk matrix and recommended 90‑ to 180‑day actions for 2026
-
Regulatory shock (High impact, Medium likelihood): Map certification timelines to purchasing cycles. Action: prioritize vendors with validated EU/ISO certification and insert conditional acceptance clauses tied to certification milestones.
-
Raw material price volatility (Medium impact, Medium likelihood): Hedging and long‑term supply contracts for glass and alloy inputs reduce margin erosion. Action: negotiate supplier cost‑plus with annual cap adjustments and service credits for delayed delivery.
-
Installation capacity constraints (High impact, High likelihood for surge projects): Build or partner for certified installation teams to avoid project slippage. Action: create preferred installer programs and pre‑qualified contractor panels.
-
Technology substitution (Medium impact, Increasing likelihood): Track multilayer/lead‑free alternatives. Action: fund field evaluations and one‑site pilot installs to validate performance under real‑world clinical conditions.
How to use this study in boardroom and procurement cycles
-
Executive strategy: Use the market sizing and CR metrics to inform M&A screens and capex prioritization—target suppliers that close capability gaps (installation, certification, regional production).
-
Business development: Leverage the buyer persona and procurement playbook to design bundled offers (glass + installation + certification) that lock multi‑year service revenue.
-
Procurement teams: Adopt the provided negotiation templates and total cost of ownership model to move beyond price per square foot and into performance/certification‑backed contracting.
Next steps and access to full intelligence
PW Consulting’s full report contains the detailed segmentation tables, revenue splits, vendor scorecards with capabilities and financials, and downloadable modeling assets that operational teams need to execute on the strategies summarized here. The headline market trajectory (8.0% CAGR from a 2025 base of ~USD 215.0 Million) establishes the commercial opportunity; the granular decision levers are reserved for the full report and accompanying deliverables. For procurement teams, corporate development groups, and manufacturers looking to act in 2026, the complete dataset and playbooks will materially shorten time‑to‑decision and reduce execution risk.
Contact PW Consulting or visit the report landing page to request the full study package, a tailored executive briefing, or the Excel model for scenario planning. The window for lock‑in agreements, certification‑led product positioning, and installer network formation is now—being first to operationalize the compliance and service advantages will define winners in 2026.
For detailed analysis of this topic, please visit the official page: Medical X-ray Radiation Protection Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cocamidopropyl Betaine (CAPB) Market Outlook: Strategic Imperatives for 2026
Market snapshot — what the headline numbers tell you
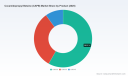
The CAPB market has moved from a niche amphoteric surfactant to a strategic ingredient in personal care and select industrial formulations. On a consolidated basis, the market expanded from a USD 100.0 Million base in 2020 to USD 150.0 Million in the report base year (2025). Our modeling shows a steady compound annual growth rate (CAGR) of 4.5% over the 2026–2032 forecast window, lifting the market toward a mid‑hundreds million dollar opportunity by 2032 under the central case. These headline figures mask important inflection points—supply stress from feedstock volatility, policy-driven reformulations in major markets, and selective capacity additions among vertically integrated suppliers—that will determine who captures the higher‑value growth pockets beyond 2026.
Cocamidopropyl Betaine (CAPB) Market
Why this research matters for 2026 corporate decision‑making
- Timing capital and contract decisions: With modest but consistent market growth and clear near‑term supply shocks, 2026 is the year to align plant uptime, feedstock contracts and off‑take agreements to lock in margin resilience.
- Reformulation windows: Regulatory pushes and retailer scoring systems are accelerating reformulation timetables for surfactants. Companies planning launches or cost pass‑throughs in 2026 must quantify CAPB’s role in product stacks and secure qualified grades in advance.
- Supplier negotiation leverage: The competitive map is concentrated around several global producers and specialty suppliers. Knowing which firms are expanding capacity or offering biomass‑balanced inputs directly affects negotiation posture and lead times.
- M&A and strategic partnerships: Mid‑sized formulators and ingredient specialists can use 2026 as a springboard for bolt‑on acquisitions or JV structures to secure feedstock, certification credentials and route‑to‑market for premium personal care segments.
What this report delivers — operationally useful intelligence
Our CAPB research is structured to be actionable for both strategic planners and commercial teams. Highlights include:
Cocamidopropyl Betaine (CAPB) Market
- Demand modeling calibrated to historical growth (2020–2025) and forecast scenarios to 2032, with sensitivity bands for raw‑material price shocks and regulatory acceleration.
- Price and margin analytics that map feedstock inputs (including DMAPA and coconut oil cost dynamics) to finished CAPB cost curves under multiple procurement strategies.
- Supplier-by-supplier dossiers that detail capacity posture, sustainability initiatives (biomass‑balanced routes, certified coconut oil sourcing), product grade portfolios, and likely commercial flex points.
- Formulation playbooks for personal care and adjacent applications that prioritize mildness, biodegradability and cost‑to‑performance tradeoffs.
- Risk matrices and scenario checklists for procurement, regulatory compliance, and go‑to‑market timing—built to be operationalized by procurement, R&D, and corporate development teams.
- A transaction support pack for M&A and partnership diligence: comparable trading multiples, integration risks, and a short list of target archetypes by capability.
To preserve competitive value for subscribers, the report deliberately refrains from publishing granular regional and application splits in this preview. Those specific matrices, unit economics and downloadable model files are included in the full report package.
Cocamidopropyl Betaine (CAPB) Market
Competitive landscape — the strategic positions you must track
The market exhibits meaningful concentration among a core group of global and specialty players. Strategic moves to watch include feedstock integration, sustainability credentialing and capacity builds targeted at consumer goods formulators.
- Galaxy Surfactants Ltd (Mumbai) : A leading surfactant specialist with integrated CAPB grades and a clear focus on biomass‑balanced innovation. Galaxy’s capability to combine sustainable inputs with established consumer care channels positions it as a preferred partner for formulators chasing green claims.
- Eastman Chemical Company (Kingsport, TN) : Eastman’s investment in DMAPA ES production in Louisiana strengthens a critical upstream link in CAPB synthesis. This capacity is strategically important for buyers seeking sustainable DMAPA options and shorter supply chains for North American manufacturing.
- Stepan Company (Northfield, IL) : With long experience in amphoterics, Stepan’s CAPB grades derived from coco‑methyl esters remain a go‑to for formulators requiring robust supply and global distribution.
- Innospec, Croda, Lonza, Kao, Solvay, Clariant, Evonik, BASF : These specialty and commodity suppliers differentiate through specific strengths—technical service, eco‑certified feedstock, formulary portfolios for sensitive skin, or geographic reach. BASF’s recent deployment of biomass‑balanced DMAPA into a key partnership underscores how upstream sustainability credentials are becoming commercial differentiators.
Recent corporate activity reinforces two themes: (1) upstream integration and sustainable feedstock availability are now strategic levers (e.g., Eastman’s Louisiana capacity and BASF’s biomass‑balanced DMAPA shipments), and (2) new product introductions tied to certified coconut sourcing or lower CO2 footprints are reshaping procurement evaluation criteria for personal care customers.
Raw material and regulatory dynamics — near‑term shocks and medium‑term steadying
Feedstock volatility is the dominant operational risk for 2026. Coconut oil—an important downstream feedstock feed for many CAPB routes—experienced acute supply tightness driven by weather and policy factors in 2024–2025, with several sourcing regions reporting significant price spikes and production declines. Shipping and CIF index movements compounded the margin pressure. While outlooks point to a modest recovery and price stabilization in the medium term, periodic spikes remain plausible if adverse weather or biodiesel mandates tighten availability again.
Regulatory drivers are complementary demand accelerants. European green chemistry policies and restrictions on certain sulphate surfactants have catalyzed reformulations toward milder, biodegradable amphoterics. Specialty certifications—whether rainforest certification, biomass‑balanced inputs, or product‑level biodegradability marks—are now part of purchase specifications for many branded customers, including emerging niches such as certified pet grooming products.
Strategic scenarios and a practical playbook for 2026
We recommend three pragmatic pathways that companies should evaluate and operationalize in 2026 depending on their position on the value chain.
- For buyers and formulators (risk minimizers): Secure multi‑tier sourcing with at least one supplier offering certified or biomass‑balanced inputs. Convert short‑term spot exposure into staggered rolling contracts with flex provisions tied to index thresholds. Prioritize qualification of alternative CAPB grades and back‑catalogue reformulations to reduce single‑ingredient dependency.
- For producers and ingredient owners (market growers): Differentiate via sustainability credentials and end‑use support. Invest selectively in capacity that is feedstock‑agile (able to accept both conventional and certified feedstocks) and in technical service capabilities that accelerate customer reformulation timelines. Consider JV or offtake agreements with DMAPA producers to stabilize upstream supply.
- For investors and corporate development teams (value creators): Target acquisitions that bring either a unique certified feedstock pathway or a strong consumer personal‑care customer base. Avoid chasing low‑margin commodity plants unless accompanied by advanced blending or specialty grade capabilities that command premium pricing.
Operational tactics for implementation include shorter internal decision cycles for raw‑material hedging, cross‑functional CAPB task forces to align procurement, R&D and marketing, and scenario‑based stress tests for product portfolios under high price volatility and strict regulatory acceleration.
How to use the full PW Consulting CAPB intelligence
This preview is designed to surface the decision levers that will matter in 2026. The complete research package contains the granular worksheets, regional and application segmentations, supplier scorecards, grade‑level economics, and downloadable scenario models you will need to quantify these levers for your own P&L. If your 2026 planning requires prioritized lists—top suppliers by strategic fit, likely margin impacts by procurement strategy, or an actionable M&A shortlist—those modules are available in the full report.
For procurement directors, R&D heads, corporate strategists and deal teams preparing 2026 roadmaps: treat CAPB not merely as an ingredient cost line, but as a leverage point to differentiate on efficacy, certifications and supply resilience. Our full report provides the granular maps and playbooks to convert these insights into executable actions.
To access the complete report and model files, visit our report page or contact the PW Consulting industrial chemicals team. The detailed segment matrices and unit‑level projections—purposefully withheld from this summary—are included in the subscriber package to preserve competitive confidentiality and to support board‑level decision making.
For detailed analysis of this topic, please visit the official page: Cocamidopropyl Betaine (CAPB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dissolving Pulp Market to Top USD 8,179.41M by 2032 at 3.05% CAGR
By pmarketresearch, 2026-07-30
Dissolving Pulp Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s new market study on Dissolving Pulp is designed as a strategic instrument for executives, investors and functional leaders making binding choices in 2026. Anchored on a base year of 2025 and covering a historical window (2020–2025) plus a forward-looking forecast (2026–2032), the research translates macro momentum into operationally relevant implications. In short: it tells you where the market is headed (and why), what that means for your cost, sourcing and go-to-market choices, and which tactical moves preserve optionality while capturing value.
Dissolving Pulp Market
Why this study matters for 2026 decisions
-
Timing: 2026 is a hinge year. The market’s medium-term trajectory is modest but persistent — our modelling produces a compound annual growth rate (CAGR) of 3.05% across the forecast window. Small differences in capacity planning, feedstock contracts or product mix executed in 2026 compound materially by 2032.
Dissolving Pulp Market -
Strategic exposure: Dissolving pulp sits at the intersection of textiles, cellulose derivatives and specialty applications (pharma/food/cosmetics). Decisions in procurement, vertical integration or commercial partnerships affect both up- and downstream economics.
Dissolving Pulp Market -
Regulatory and trade volatility: Trade investigations and changing environmental standards are introducing non-price shocks. Firms that integrate regulatory scenarios into 2026 planning reduce downside and preserve optionality.
Market trajectory at a glance (what the numbers mean)
Using USD million as the reporting unit and a 2025 base, the market has expanded from a multi-billion dollar base in 2020 through 2025 and continues to grow into the early 2030s. Our compiled series shows steady year-on-year increases across the historical period, reaching an assessed market value of approximately 6,629 USD Million in 2025. Under the central forecast (3.05% CAGR), the market rises to a low-mid single-digit growth path through 2032, culminating in an assessed market size of roughly 8,179 USD Million by 2032.
Two practical implications flow directly from those macro numbers. First, marginal capacity investments must be evaluated on a multi-year basis: modest CAGR means that brownfield optimizations and product-mix adjustments will often offer higher IRR than large greenfield expansions unless they are coupled with de-risked feedstock or captive offtake. Second, strategic buyers and sellers should price in a slow-but-steady demand uplift rather than a near-term boom — value capture will come primarily from cost discipline, differentiated product grades and route-to-market innovations.
Competitive structure — concentration and what it implies
The dissolving pulp market is meaningfully concentrated: our concentration metrics indicate the top three players account for roughly 51.2% of market throughput, while the top five together account for about 62.5%. This industry structure generates a mixed strategic landscape:
-
Pricing resilience for large integrated players — they can defend margins through scale, backward integration and access to premium woodfibre sources.
-
Opportunity windows for specialized participants — niche grades, specialty cellulose and value-added services (e.g., consistent quality for pharmaceutical or cosmetic supply chains) create pockets of higher return.
-
M&A and alliance economics — consolidation or capacity redeployment can be value accretive if executed with a clear feedstock and offtake logic, given the market’s clustering in a handful of players.
Key industry players — strategic positioning (high-level)
-
Bracell (Brazil): A global leader with an asset footprint oriented to eucalyptus-based dissolving pulp and a growing emphasis on rayon and specialty grades. Recent capacity reallocation decisions are an example of strategic response to downstream demand shifts. ( https://www.bracell.com/en/)
-
Sappi Limited (South Africa): Focused on high-purity cellulose for textile and specialty applications under established brands; strong emphasis on quality and downstream relationships. ( https://www.sappi.com/en-us/)
-
Rayonier Advanced Materials Inc. (United States): A producer with mill-level focus on high-purity dissolving pulp for cellulose derivatives and pharmaceutical applications; reputational strength in quality and sustainability. ( https://ryam.com/)
-
Lenzing AG (Austria): An integrated participant supplying dissolving pulp for regenerated fibers with an emphasis on certified sources and product traceability; an example of a vertically aligned model. ( https://www.lenzing.com/)
-
Aditya Birla Group / Grasim Industries / Birla Cellulose (India): An integrated producer whose global assets and downstream partnerships underpin supply to viscose producers and related converters. ( https://www.grasim.com/)
-
Neucel Specialty Cellulose Ltd. (Canada): Specialist in high alpha-cellulose grades (notably hemlock-derived); niche technical improvements are a competitive differentiator for pharma and film-making applications.
Recent dynamics and their 2026 implications
-
Capacity reallocation: In late 2025 a major producer announced reconfiguration of lines to prioritize dissolving pulp. Such moves tighten near-term commodity-grade pulp supply and reallocate feedstock and logistics resources. For buyers, this increases the importance of flexible offtake clauses and multi-sourcing strategies in 2026 contracts.
-
Trade investigations: A countervailing duty probe initiated in 2025 into imports from a key producing country introduces policy risk that can change landed costs and reroute trade flows within months. Scenario-based procurement and contractual protective provisions (e.g., price reopeners) are tactical necessities.
-
Feedstock pressure: Historical weather events and transport cost inflation pushed certain wood-chip prices materially higher in recent years. This cost transmission affects mill cash margins and alters the relative attractiveness of eucalyptus versus softwood feedstocks — a core input variable for 2026 planning.
Where value will be captured in 2026–2032
Based on our integrated demand-supply modelling and interviews with downstream converters, four avenues consistently deliver superior returns for incumbent and new entrants alike:
-
Grade differentiation: Premiumization into high-purity and specialty grades for pharma, cosmetics and high-performance textiles merits price premiums that outpace the baseline market CAGR.
-
Vertical or contractual integration: Securing reliable feedstock through long-term fibre agreements, tolling arrangements, or captive plantations reduces input volatility and can compress landed costs.
-
Operational excellence: Incremental improvements in yield, energy use and chemical recovery typically offer faster payback than greenfield capacity, given the market’s moderate growth pace.
-
Regulatory foresight: Proactive compliance and sustainable sourcing credentials unlock premium buyers and reduce trade disruption risks — an increasingly material commercial differentiator.
What PW Consulting’s report delivers — practical contents
The study is not an academic exercise: it is a toolbox for executives. Key components include:
-
Demand-supply balances and a forward capacity map (2026–2032), with scenario variants reflecting trade-policy shocks and feedstock stress events.
-
Price-impact analysis and margin sensitivity by grade, including a unit-economics framework you can apply to your asset base.
-
Commercial playbooks: tailored GTM options for producers, integrated converters and traders, including contracting templates and risk-sharing structures.
-
M&A and partnership scorecards: methodical screening criteria and valuation guidance for targets across the value chain.
-
Regulatory and ESG risk matrix: jurisdictional heatmaps and mitigation checklists for 2026 procurement and investment approvals.
-
Operational diagnostics: a step-by-step recovery and efficiency roadmap for mills, with prioritized capex vs. opex interventions by expected payback horizon.
How to use the study in 2026 — action-oriented recommendations
-
For producers: prioritize short-cycle yield and recovery projects that improve margin resilience; defer large greenfield commitments unless paired with secured offtake or captive fibre.
-
For traders and buyers: renegotiate contracts to include adaptive pricing or force majeure clauses that account for trade remedial actions and feedstock shocks.
-
For investors and M&A teams: use the CR and scenario outputs to stress-test targets against policy risk and feedstock volatility — value is concentrated but idiosyncratic upside exists in specialty grades.
-
For sustainability officers: accelerate traceability and third-party certification programs to reduce commercialization friction and access premium channels.
Final note — why this is a teaser, and where to get the full intelligence
This executive briefing demonstrates the depth and orientation of PW Consulting’s dissolving pulp research: it connects market-level growth, structural concentration and concrete commercial actions. Per our “trailer” approach, we have intentionally withheld granular regional and application-specific splits, detailed unit-cost schedules and the full set of scenario tables that form the operational core of the study. Those elements are essential for constructing binding 2026 budgets, ERP inputs and M&A valuations.
To obtain the complete dataset, interactive models and the full suite of playbooks and checklists (including downloadable Excel modules and scenario dashboards), please refer to the PW Consulting report landing page where you can download or license the full deliverable. The full report furnishes the segmented demand curves, regional and application breakdowns, and granular sensitivity analyses you will need to finalize 2026 capital, procurement and commercial plans.
PW Consulting — we translate market intelligence into executable strategy. Reach the report and our advisory team to schedule a deep-dive session that aligns these findings to your specific asset, portfolio or investment thesis for 2026.
For detailed analysis of this topic, please visit the official page: Dissolving Pulp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 2‑Methyl‑1,3‑Propanediol Market Poised at USD 145 Million in 2025
By pmarketresearch, 2026-07-30
2-Methyl-1,3-Propanediol Market: Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, high-impact perspective on the 2-Methyl-1,3-Propanediol (MPDiol) market geared specifically to inform executive choices in 2026. This short-form brief highlights the structural forces, commercial levers, and competitive dynamics that will determine winners and losers as the market transitions from mid-cycle consolidation to selective growth. It deliberately surfaces the analytical framework and strategic implications while reserving granular segmentation numbers for the full report—your tactical guide to executing with confidence.
2-Methyl-1, 3-Propanediol Market
Executive summary: what this study delivers for near-term strategic decisions
- Validated market trajectory and scenario-ready forecasts anchored on a comprehensive historical baseline (2020–2025), a 2026 decision point, and a forward-looking horizon to 2032.
- A clear assessment of concentration and power: a highly concentrated supplier base governs pricing, availability, and margin capture, creating both barriers and targeted opportunities for market participants.
- Actionable playbooks for commercial, procurement, and investment teams—covering contract structures, capacity strategies, and product & grade prioritization—designed for 12–24 month execution cycles starting in 2026.
- Regulatory and feedstock risk matrices, including recent regulatory developments and their near-term commercial consequences.
Market trajectory and macro view
Our analysis uses 2025 as the base year, with an empirically grounded historical series from 2020–2025 and a forecast window spanning 2026–2032. The MPDiol market has demonstrated steady, low-single-digit growth through the historical period and continues on a moderate upward trajectory into the forecast horizon. The compound annual growth rate (CAGR) applied for the forecast period is 3.0%, reflecting a mature specialty-chemical market where demand gains are driven by performance-led applications rather than commodity volume expansion.
2-Methyl-1, 3-Propanediol Market
Key macro takeaways for 2026 planning:
2-Methyl-1, 3-Propanediol Market
- The market has expanded materially since 2020, and while growth is not exponential, it is reliable—supporting disciplined capacity investments and specialty-mix optimization.
- Near-term upside is linked to engineered-resin demand, coatings performance upgrades, and selected specialty chemical applications; downside is concentrated in cyclical end-markets such as discretionary automotive and capital-intensive construction segments.
Market structure and concentration
MPDiol is supplied predominantly by a small set of global chemical producers with integrated production capabilities and advanced purification technologies. The market exhibits a high degree of concentration among the leading suppliers, a structural feature with important implications:
- Pricing dynamics are supplier-driven: incumbents with scale and integration can defend margins through flexible upstream sourcing and premium-grade product offerings.
- Commercial negotiation power rests with a few large producers, increasing the strategic value of long-term offtake agreements and backward-integration strategies for downstream players.
- High concentration improves predictability of supply in normal cycles but creates single-point risks during plant outages or feedstock disruptions—risk scenarios that demand contingency planning in 2026 procurement playbooks.
Demand dynamics and end-use themes
Demand remains anchored in polyester resin systems—both unsaturated polyester for composites and polyester variants for high-performance coatings—supported by polyurethane applications and specialty plasticizers. The performance attributes of MPDiol (elevated functionality, improved toughness, formulation flexibility) make it attractive where end-product performance commands a premium.
Critical demand-side drivers to monitor in 2026:
- Composite adoption in lightweighting and infrastructure repairs—incremental gains in wind, marine, and selected automotive niches support steady resin demand.
- Coatings and specialty paints—formulation upgrades that emphasize durability and reduced VOCs continue to favor tailored polyester chemistries incorporating MPDiol.
- Shift toward specialty grades and higher-purity streams as formulators extract margin through performance differentiation, increasing the value of purification-capable suppliers.
- Regulatory signals that expand permissible uses or change acceptance in adjacent markets—creating occasional demand spurts that favor nimble suppliers and well-prepared buyers.
Regulatory & feedstock dynamics that will matter in 2026
Two technical-regulatory factors will particularly influence strategy in the near term.
- Regulatory permissibility: Recent exemptions approved by a major regulator in mid-2024 broadened acceptable inert ingredients in certain pesticidal formulations. Such rulings can open adjacent white-space demand for specialty solvents and intermediates, contingent on formulators adapting product specifications. Executives should track approvals and time product qualification processes accordingly.
- Feedstock and process dependencies: Commercial MPDiol production relies on hydroformylation routes converting allyl alcohol (and related intermediates) using carbon monoxide and hydrogen. This creates concentrated feedstock exposure—availability, pricing, and vendor reliability for allyl alcohol and synthesis gas components will directly influence cost curves and spot availability.
Competitive landscape: who matters and why
The market is served by established specialty-chemical companies that combine global supply footprints, technology depth, and customer-facing formulation support. Key participants include long-tenured incumbents and integrated producers with differentiated capabilities:
- LyondellBasell Industries: Offers MPDiol under branded formulations and operates dedicated sites with downstream channel expertise. Its execution strength lies in integrated supply chains and branded customer engagements.
- DuPont de Nemours: Focuses on capacity investments and high-purity grades, aiming at value capture in specialty polyester and engineered applications. Strategy emphasizes quality differentiation and selective capacity growth.
- OXEA GmbH: Utilizes integrated manufacturing and purification know-how to serve quality-sensitive coatings and resin markets across Europe and beyond.
- BASF SE: Positions MPDiol within a broader performance-materials portfolio, enabling cross-selling into adhesives, coatings, and engineered resin systems backed by global application support.
- Dow Inc.: Leverages hydroformylation expertise and broad polymer chemistry capabilities to serve polyester, polyurethane, and personal-care supply chains.
- Perstorp Holding AB: Invests in bio-based process advancements, aligning with sustainability-seeking customers and specialty-coatings applications.
For 2026, the strategic advantage will accrue to players who combine flexible feedstock strategies, grade/purity differentiation, and application support services. New entrants face material technical and commercial barriers; meaningful disruption will likely come from targeted bio-based or purification-led innovations rather than broad-scale commoditization.
Risks, shocks, and scenario planning
Executives must model three interdependent risk vectors when setting 2026 strategies:
- Regulatory shocks—unexpected changes in permissible uses or product stewardship requirements can create short-term surges or sudden demand erosions in certain end-markets.
- Feedstock interruptions—supply-chain constraints for allyl alcohol or synthesis gas can propagate quickly due to limited alternative production routes, amplifying price volatility.
- Concentration-related outages—given the clustered supply base, plant outages at a major supplier can tighten spot markets rapidly; contingency capacity or diversified sourcing agreements are vital mitigants.
What the full PW Consulting report contains (practical tools for 2026)
- Detailed market model (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario toggles for macroeconomic sensitivity, feedstock shocks, and regulatory outcomes.
- Segment and regional demand maps with quantitative splits and growth levers—(note: segmented values are intentionally withheld from this preview and are available in the full report).
- Supplier benchmarking and capability heatmaps, including grade-specific purification capacity, logistics resilience, and innovation pipelines.
- Price-curve and margin simulations tied to feedstock cost inputs (allyl alcohol, CO/H2), plus procurement playbooks for lock-in and flexible-sourcing arrangements.
- M&A and partnership playbook: valuation heuristics, integration risk checklists, and a prioritized list of strategic targets by capability gap.
- Regulatory tracker and impact assessment—mapping recent rulings, such as the mid-2024 inert-ingredient exemptions, to product qualification pathways and addressable market expansion.
How executives should act in 2026
- Prioritize supply resilience: negotiate multi-year offtakes with staggered take-or-pay elements, and identify dual-source strategies for feedstock-sensitive inputs.
- Allocate investment to specialty grades: deploy modest capital to raise purification capability or co-develop high-purity streams with incumbent suppliers to capture formulation-driven margins.
- Embed regulatory intelligence into commercial planning: accelerate qualification timelines for new authorized uses and align technical dossiers to anticipated regulatory shifts.
- Hedge feedstock exposure: where feasible, pursue hedging instruments or backward integration options to stabilize input cost volatility.
- Consider partnership over greenfield: given high concentration and capital intensity, joint ventures or toll-manufacturing agreements can be lower-risk pathways to secure capacity.
In sum, the MPDiol market presents a pragmatic growth story: steady expansion, concentrated supply, and selective pockets of premiumization. For 2026, the imperative is not to chase volume blindly but to orchestrate supply-security, product differentiation, and regulatory readiness. The full PW Consulting study converts these imperatives into executable steps, models, and negotiation playbooks tailored for procurement, commercial, and corporate development teams.
Next steps
PW Consulting’s full report contains the complete datasets, segmented forecasts, and tactical annexes necessary to operationalize the above recommendations. For decision-makers preparing budgets, procurement strategies, product roadmaps, or M&A assessments in 2026, our report is designed as the single-source analytical and tactical companion.
For detailed analysis of this topic, please visit the official page: 2-Methyl-1, 3-Propanediol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: White Cement Market Poised for 4.55% CAGR Through 2032
By pmarketresearch, 2026-07-30
White Cement Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s lead industry analyst, I present a high-resolution preview of our White Cement Market study — designed to equip C-suite leaders and investment committees with the strategic signposts needed for 2026 decision cycles. The global white cement market, measured at approximately USD 9,500 million in our 2025 base year, is set on a steady growth trajectory with a 2026–2032 CAGR of 4.55%, reaching roughly USD 12,930 million by 2032. This trajectory reflects resilient demand in architecture-led construction, selective industrial applications, and a structural rebalancing of supply chains driven by raw-material geography and sustainability regulation.
White Cement Market
Why this study matters for 2026 planning
-
Timing for capacity and capital allocation: Companies planning greenfield or grinding-capex in 2026 must align multi-year payback expectations with a mid-single-digit CAGR rather than high-growth assumptions; the market is growing but remains specialized and supply-constrained in key inputs.
White Cement Market -
Margin preservation under material scarcity: Ultra-low-iron limestone scarcity and TiO2 input price volatility create asymmetric downside to margins; firms that securitize feedstock or vertically integrate will materially de-risk earnings volatility.
White Cement Market -
Sustainability compliance is now a procurement filter: Updated Environmental Product Declarations (EPDs) and green-building specifications are shifting procurement to certified products. This is not a peripheral credential — it is increasingly table-stake for institutional buyers and large developers.
-
M&A and consolidation windows: With the market’s three- and five-firm concentration metrics indicating meaningful but incomplete consolidation (CR3 ~35%, CR5 ~45%), well-positioned acquirers can pursue bolt-on deals that deliver immediate technical synergies (e.g., grinding capacity, putty integration) without having to chase scarce clinker feedstocks.
Market dynamics shaping 2026 choices
-
Supply geology and feedstock economics: White cement’s technical requirement for ultra-low-iron limestone (Fe2O3 typically well below 0.5%) means feedstock availability is uneven and concentrated. Producers face recurring sourcing decisions — secure capex to develop captive pits, long-term offtakes, or premium purchases — each with distinct balance-sheet and margin trade-offs.
-
Color and process constraints limit fuel substitution: Many decarbonization levers applied across gray cement (alternative fuels, high SCM rates) are technically constrained in white cement production because color control and high kiln temperatures restrict substitution. This elevates the strategic value of focused sustainability investments (e.g., dedicated clinker lines, carbon capture retrofit feasibility studies) and explains why some players are allocating targeted sustainability budgets to white assets.
-
Regulatory and certification tailwinds: The expansion of EPD requirements for building certifications raises the premium for validated low-footprint products. Producers that can document life-cycle performance and secure EPDs will sustain access to large institutional buyers and new specification-driven segments.
-
Downstream product integration: Value capture via downstream formulations — notably putty and architectural finishes — is a demonstrable path to higher-margin exposure and customer lock-in. Recent transactions demonstrate strategic interest in integrated white cement–putty platforms.
Competitive landscape — who is shaping the arena
The white cement market is a mix of global groups, regional specialists, and family-owned niche players. Market concentration shows room for consolidation: the top three players account for roughly one-third of the market, and the top five under half, leaving opportunity for ambitious consolidators and specialist operators alike.
-
Industrial-scale incumbents expanding strategic depth: Players such as UltraTech Cement (Aditya Birla group) have pursued inorganic growth to secure downstream positions and grinding scale. Recent acquisitions and plant integrations indicate a playbook focused on synergies between white cement production and wall-putty manufacturing to capture value along the finishes chain.
-
Regional specialists with export reach: Producers like JK Cement (notably with North India grinding and putty integration) and Federal White Cement in North America demonstrate a hybrid model — regional production expertise combined with export-driven revenue. These firms leverage logistics competence and product formulations tailored to premium architectural specifications.
-
Middle East and Mediterranean players: Producers across the GCC and Mediterranean basins (including Ras Al Khaimah White Cement Company and multiple Egyptian and Omani firms) emphasize premium product positioning and compliance with international standards to serve regional construction and export corridors.
-
Emerging-market capacity additions and certification plays: Turkish and European producers are differentiating through sustainability credentials (EPDs), while select Chinese and ASEAN manufacturers compete on price and scale for commodity-style white cement flows.
Recent corporate moves exemplify these dynamics: significant capacity additions and acquisitions announced in 2025–2026 prioritized grinding scale, putty integration, and sustainability capex (including a multi-million-euro allocation to white cement sustainability projects). These actions are leading indicators for 2026 strategies — expect further defensive tie-ups between producers seeking feedstock security and downstream integration.
What our report delivers (practical, operational, decision-ready content)
PW Consulting’s white cement study is deliberately structured to convert strategic insight into executable actions. Highlights include:
-
Market sizing and forward scenarios: Modelled base-case, upside, and stress-case demand pathways across 2026–2032, financially stressed against feedstock-price shocks and sustainability capex scenarios.
-
Investment-readiness toolkit: Step-by-step templates for capex prioritization, NPV sensitivity analyses that embed raw-material concentration risk, and a pragmatic checklist for plant-commissioning phasing when grinding vs clinker vs downstream capacity is on the table.
-
Supply-chain risk maps: GIS-informed overlays of ultra-low-iron limestone deposits, kiln locations, and export terminals — enabling rapid scenario modelling for feedstock vulnerability and logistics optimisation.
-
Commercial playbooks: Go-to-market options for premium architectural segments, specification-led selling, and bundling strategies with wall-putty and finishing systems.
-
M&A screening and valuation heuristics: A shortlist of diligencable metrics and red flags for target screens, with example transaction structures (asset vs stock, earn-outs linked to EPD certification milestones) tailored to the sector’s realities.
-
Regulatory and sustainability roadmap: Practical guidance on achieving EPD compliance, retrofitting options, and quantifying the commercial upside from certified low-carbon product premiums.
Actionable recommendations for executives in 2026
-
Prioritize feedstock security: Negotiate long-term offtakes or invest selectively in captive low-iron limestone resources. The marginal value of feedstock assurance is rising faster than the cost of selective upstream capex.
-
Target downstream integration where economically viable: Wall-putty and finish systems are not merely ancillary products; they are profitable channels to secure specification loyalty. Evaluate bolt-on acquisitions or JV structures that shorten the route to market.
-
Invest in credentialing: Allocate project funding to secure EPDs and similar certifications. For institutional projects and certified green construction, EPDs can be a gatekeeper for specification — and a source of premium pricing.
-
Differentiate via product and service: For premium architectural demand, focus on whiteness consistency, batch traceability, and logistics reliability. Service layers (e.g., specification support, installer training) compound value and protect margins.
-
Design sustainability investments around thermal and color constraints: Since traditional alternative-fuel routes are limited, prioritize energy-efficiency retrofits, selective electrification feasibility studies, and partnerships for low-carbon clinker supply.
-
Use M&A to buy capability, not just volume: Given the current concentration profile, acquisition value is often realized through capability transfer (EPD-compliant processes, downstream formulations, export infrastructure) rather than pure capacity accumulation.
-
Embed price-risk hedging into commercial contracts: Given feedstock and TiO2 volatility, contractual terms that share input-cost movements or include periodic repricing clauses will protect operating margins.
Next steps — how to use this preview
This preview synthesizes the strategic implications we believe will drive successful 2026 outcomes. The full PW Consulting white cement study contains the granular datasets, regional and application segmentation, scenario-model files, company-level dashboards, and a downloadable supply-chain atlas that informed the summaries above. We intentionally reserve the detailed segment and country-level matrices for the full report to support confidential planning and M&A diligence.
For executive teams preparing capital budgets, M&A pipelines, or procurement strategies in 2026, our report is built as an operational playbook: not only diagnosing market direction but also supplying the tools to execute. Contact PW Consulting to access the complete dataset, model workbooks, and tailored advisory sessions that translate these insights into board-ready actions.
For detailed analysis of this topic, please visit the official page: White Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LNG Bunker Fuel Market to Reach USD 646.37M by 2032 (28% CAGR)
By pmarketresearch, 2026-07-30
LNG as a Bunker Fuel: Strategic Imperatives for 2026 — PW Consulting Market Preview
Executive snapshot
As the maritime energy transition accelerates, LNG is shifting from a niche compliance strategy to a core element of short- and medium-term fuel planning. PW Consulting’s latest market study, built on a 2025 base and a seven-year forecast through 2032, identifies a market trajectory that requires immediate strategic responses: the market is modelled to expand at an annualized compound growth rate of approximately 28% across 2026–2032, rising from a 2025 baseline to a multi-fold larger market by 2032 (all values expressed in USD, revenue units in Millions). That rapid growth is not academic — it is being driven by convergent forces of regulatory pressure, port-level licensing activity, accelerating fleet adoption and supply-side innovation.
LNG as a Bunker Fuel Market
Historically the sector recorded steady build-out during 2020–2025; starting in 2026 the forecasted growth profile becomes materially steeper, reflecting recent regulatory de-risking and the commissioning of small-scale liquefaction and bunkering assets. These macro dynamics create both an opportunity window for first movers and a hazard for late entrants exposed to stranded-capital risks.
LNG as a Bunker Fuel Market
Why this report matters to decision-makers in 2026
- Clarifies the commercial runway: A 28% CAGR scenario implies compression of time-to-scale — investment and contract timelines that might previously have fit a five-year plan now compress into 18–36 months.
- Aligns capex and offtake strategy with regulatory cadence: Recent policy shifts (including removal of certain STS transfer restrictions and proactive licensing in leading bunkering hubs) change which business models will be viable at scale.
- Distinguishes infrastructure bets from service plays: The economics of shore-based liquefaction, dedicated barges and truck-to-ship models diverge significantly under differing fuel-price and utilization scenarios; the report translates those differences into decision triggers.
- Provides transaction-ready insight: Private-equity and strategic acquirers need valuations and comparable frameworks that reflect market maturation; our study supplies the necessary comparators and negotiation levers.
What PW Consulting’s market study contains — practical, operational deliverables
This is a practitioner’s report designed to be used, not merely read. Highlights include:
LNG as a Bunker Fuel Market
- Demand and supply modelling: A transparent, stress-testable demand model covering 2020–2025 historicals and a granular forecast for 2026–2032, including scenario toggles for fuel prices, carbon policy and alternative-fuel competition.
- Commercial models and contract templates: Playbooks for short- and long-term bunkering contracts, supply guarantees, swing volumes and joint-venture governance structures that reflect real-world negotiation levers.
- Infrastructure economics: Benchmarked capex/opex ranges and utilization thresholds for shore-side liquefaction, small-scale import terminals, bunker barges and truck-to-ship logistics — with sensitivity analyses for gas feedstock pricing.
- Regulatory and permitting matrix: A country- and port-level map of permitting requirements, licensing timelines and recent policy changes that materially affect time-to-market assumptions.
- Operational readiness checklists: Safety, compliance and training templates for shipowners and terminal operators preparing STS operations, bunkering SIMOPS and hybrid fueling operations.
- Competitive and M&A playbook: Profiles and positioning analysis for the leading market participants, acquisition theses, and integration checklists to accelerate value capture.
- Decision support tools: Excel-based models and board-ready slide sets that executives can use to run internal investment approvals and scenario workshops.
Competitive landscape — what incumbents and challengers are doing
The supply side is maturing along two parallel axes: hub-and-spoke terminal development led by integrated players, and nimble, vessel- and truck-based service providers that prioritize rapid coverage. The market concentration is meaningful: the top three firms hold a majority share and the top five approach three-quarters of market throughput by current measures — a structure that favors vertically integrated scale players but leaves space for specialized services and regional champions.
- Seaside LNG (Houston) — An integrated player focused on shoreside liquefaction, storage and Jones Act-compliant bunkering barges. Recent operational milestones include a SIMOPS LNG bunkering of a very large container vessel at a major US port in 2025, demonstrating capability on high-throughput calls and the operational practices required for large-vessel refuelling.
- Titan Clean Fuels (Amsterdam) — A European-origin service provider that combines LNG with biomethane supply options and operates small-scale bunker vessels. Their strategic play mixes fuel decarbonization narratives with the flexibility of smaller, distributed delivery assets.
- Harvey Gulf International Marine (New Orleans) — Operating dedicated LNG bunkering assets at a key Gulf hub, Harvey Gulf’s model emphasizes asset-backed reliability for offshore and coastal fleets, a relevant blueprint for markets prioritizing guaranteed throughput.
- JAX LNG (Jacksonville) — A regional, small-scale liquefaction and truck-to-ship operator whose model highlights speed-to-market and modularity — a template for ports seeking incremental capacity without large terminal commitments.
Across these players the strategic vectors are clear: vertical integration to control value chains, modular small-scale assets to accelerate coverage, and the inclusion of lower-carbon LNG variants (bio-LNG) to broaden the value proposition. The report analyses these vectors and translates them into partnership and investment decision trees.
Market dynamics and regulatory signals to watch
- Licensing and port policy: Some leading ports opened new supplier licensing windows in early 2026 to facilitate sea-based reloading — a strong signal that regulators are actively shaping commercial opportunity and competition.
- Permitting and STS operations: Removal of certain administrative restrictions on ship-to-ship transfers in 2025 materially reduced operational friction for STS models — a change that accelerates adoption where safety regimes are in place.
- Infrastructure density: Industry tracking shows hundreds of ports with LNG bunkering availability and a growing bunker-vessel fleet, yet practical coverage remains uneven. The interplay between port capability and shipping lane economics is central to which deployment models win.
- Fleet adoption: By end-2025 the number of LNG-fueled non-carrier vessels crossed a new threshold, with strong deliveries in 2024 and 2025; fleet mix and retrofit economics remain a cornerstone of demand modelling.
Key risks and scenario considerations
The sector’s upside is matched by concentrated execution risks. PW Consulting’s stress tests focus on:
- Fuel-price shocks and basis differentials that can erode LNG’s near-term differential advantage;
- Competing zero-carbon alternatives — ammonia, hydrogen and advanced biofuels — that may capture premium environmental positioning and policy support;
- Permitting or safety incidents that could trigger more conservative regulatory approaches; and
- Overbuild in specific corridors that produces underutilized assets and margin compression.
Each of these risks is modelled in the study with trigger thresholds and mitigation checklists to help decision-makers choose adaptive strategies.
How to use this intelligence in 2026 — recommended next steps
- Run a 90-day rapid assessment: Use the report’s benchmarking tools to map your portfolio to port readiness and identify 2–3 priority hubs for pilot projects.
- Lock short-term offtake or slot agreements: The report includes contract templates and negotiation playbooks intended to secure first-mover access without overcommitting capital.
- Prioritize modular investments: For ports and terminal operators, small-scale liquefaction and barge assets offer de-risked entry and faster path to utilization; for shipowners, phased retrofit pilots reduce technical and commercial uncertainty.
- Prepare an M&A and partnership roadmap: The consolidation profile and company-level analysis in the study identify target profiles and earn-out structures aligned with the sector’s expected maturation.
Why PW Consulting’s study is uniquely actionable
Unlike purely descriptive industry overviews, this study is an operational toolkit for 2026 decision cycles. It combines a validated growth trajectory with hands-on models, regulatory timelines and competitor playbooks so executives can move from deliberation to deployment. We present both the strategic narratives and the detailed commercial mechanics needed to execute within 6–24 months.
Next step — access the full intelligence
This preview highlights our analytical rigor and the practical value of the study. To preserve the commercial integrity of the underlying segmentation and port-level models we have deliberately withheld the proprietary, granular datasets and company-level financials that inform the report’s forecasts. Clients and subscribers who require the complete dataset — including port-by-port coverage, contractual templates, downloadable financial models and detailed company valuation comparators — can access the full report via PW Consulting’s market portal.
For an executive briefing, a tailored 90-day action plan or to license the full models and datasets, contact PW Consulting’s LNG as a Bunker Fuel practice. The 2026 decision window is narrow; equipping leadership with a robust playbook now will materially affect outcomes over the coming investment cycle.
For detailed analysis of this topic, please visit the official page: LNG as a Bunker Fuel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Calcium Gluconate Market to Reach USD 131.32B by 2032 at 5.02% CAGR
By pmarketresearch, 2026-07-30
Calcium Gluconate Market: Strategic Outlook for 2026 Decision-Makers
Executive summary
As companies position for resilient growth through 2026 and beyond, the Calcium Gluconate market demands a mix of tactical supply-side responses and strategic long-term moves. Our PW Consulting analysis—anchored on a base year of 2025 and a forecast to 2032—shows the market continuing to expand at a steady compound annual growth rate (CAGR) of 5.02%. In dollar terms the market moves from the mid‑tens of tens of billions in 2025 to an expected market size exceeding USD 130 Billion by 2032. That trajectory reflects structurally sustained demand from pharmaceutical and nutrition channels as well as incremental value capture in formulated and ready‑to‑administer products.
Calcium Gluconate Market
Why this research matters for 2026 decision cycles
-
Timing and capital allocation: 2026 is the inflection year for several strategic choices—sourcing re‑design, capacity expansion, and targeted M&A. Our report gives finance and strategy teams the scenario tools to quantify ROI across those alternatives under different supply‑shock assumptions.
Calcium Gluconate Market -
Regulatory and product strategy: With multiple regulatory filing pathways influencing market access, the right dossier and geographic strategy materially changes time‑to‑market for higher‑margin pharmaceutical applications. The study maps those pathways and prioritizes country/regulatory sequences for 2026 launches.
Calcium Gluconate Market -
Procurement and risk mitigation: The sector’s upstream link to gluconic acid fermentation and glucose feedstocks exposes manufacturers to raw material volatility and trade policy risk. Our research translates those dynamics into procurement playbooks and hedging approaches tailored for 2026 budgets.
Market trajectory and macro drivers
The Calcium Gluconate value chain spans upstream biochemical fermentation, intermediate processing, and downstream formulation into APIs and finished products. Over the 2020–2025 historical window the market showed resilience through multiple supply shocks, and the forecast to 2032 embeds a continuation of that resilience with modest acceleration in later years—driven by increased clinical demand for injectable forms, growth in nutraceuticals, and expanding use in fortified foods and personal care. The report places the 2025 market as the operational baseline and models growth pathways that are sensitive to three levers: demand growth in regulated pharmaceutical channels, supply continuity of gluconic acid feedstock, and the pace of product premiumization (e.g., high‑purity pharmaceutical grade vs. commoditized industrial grades).
Dynamics shaping near‑term supply and cost
-
Feedstock concentration: Gluconic acid—produced primarily via microbial fermentation—depends on glucose inputs that represent a significant portion of production cost. Changes in glucose availability and pricing translate directly into margin variability across producers. We model multiple glucose‑price scenarios to show how an input shock propagates to finished product economics.
-
Trade and tariff impact: Recent tariffs on glucose‑related imports from China and other trade measures have altered sourcing economics and shipping patterns. The study quantifies the impact on landed cost by origin and offers decision‑grade guidance on when regional sourcing premium is justified versus global procurement.
-
Geopolitical and logistic stress: Ongoing geopolitical disruptions and episodic logistics bottlenecks—exemplified by upstream chemical shortages and regional route closures—remain a persistent source of supply risk. Our risk matrices show which nodes in the value chain create the largest single‑point exposures, and we propose mitigation playbooks ranging from buffer inventory policies to dual‑sourced contracts with performance SLAs.
Competitive landscape: who matters and why
The market is characterized by a mix of specialized API suppliers, larger pharmaceutical manufacturers producing finished injectable products, and chemical producers serving industrial and food channels. Concentration metrics show meaningful market share clustering among the top players, indicating that the largest suppliers exert pricing and supply influence while mid‑tier firms compete on regulatory dossiers, lead times, and niche grade offerings.
-
Specialized API suppliers and certificate‑holders: Companies headquartered across the United States, Europe, India and China maintain regulatory filings (USDMF, CEP/COS, EU‑WC, JDMF and equivalents). These firms are often the first to secure contracts for pharmaceutical customers requiring documented quality systems and dossier support. Their strategic value lies in certified supply for regulated markets and rapid dossier support for customers targeting hospital and clinical segments.
-
Established pharma formulators and critical‑care suppliers: A set of multinational pharmaceutical manufacturers produces ready‑to‑administer Calcium Gluconate injections and emergency care premixes. Their strengths are regulatory scale, distribution networks into hospital systems, and the ability to bundle clinical services—advantages that matter when customers prioritize continuity of care and validated supply chains.
-
Regional commodity producers and exporters: Numerous firms, particularly in South Asia, supply large volumes for nutrition, animal feed and industrial uses. They compete on cost, export reach, and responsiveness to spot demand; their strategic considerations differ from those of dossier‑driven API suppliers.
Key company archetypes covered in the report
PW Consulting’s company profiles go beyond high‑level descriptions, detailing capabilities such as dossier types held, geographic registration footprints, manufacturing standards, and where applicable, value‑added services (e.g., sterile fill/finish, 503B compounding). Companies profiled include established API suppliers and multinational finished‑product manufacturers; each profile highlights strategic strengths, typical customer match, and a short list of tactical risks for 2026 contracting and partnership decisions.
What the report contains: practical, decision‑grade deliverables
-
Market sizing & stress‑tested forecasts: Baseline market and alternative scenarios anchored to 2025, with sensitivity to feedstock price movements and trade policy shocks.
-
Supplier risk heatmaps: Supplier‑level risk scoring across regulatory, logistics, financial stability and operational continuity dimensions—designed for use in procurement RFx processes.
-
Regulatory dossier and market entry playbooks: Step‑by‑step blueprints for gaining market access in prioritized geographies, prioritized regulatory filings, and estimated timelines and costs.
-
Commercial and pricing playbooks: Templates for dynamic pricing, contract clauses for supply assurance, and margin playbooks for premium versus commodity channels.
-
M&A and partnership shortlist: A qualitatively ranked set of potential targets and capability partners aligned to five strategic objectives (capacity, geographic diversification, dossier access, formulation capabilities, upstream integration).
-
Operational playbooks: Capacity expansion capex models, yield improvement levers in fermentation and downstream purification, and a practical checklist for sterile fill‑finish investments.
-
Procurement negotiator kit: Contract templates, SLA clauses, penalty structures for non‑performance, and an inventory optimization spreadsheet calibrated to industry lead times and cost of stock.
Strategic implications and recommended 2026 actions
-
Prioritize supplier diversification with targeted redundancy: For corporations reliant on regulated pharmaceutical supply, establish at least two certified sources across different trade blocs. The report ranks sourcing options by risk and cost to help decide whether to accept a premium for resilience.
-
Invest selectively in dossier expansion: Firms with aspirations into hospital or export markets should evaluate the economics of securing necessary filings. Our dossier ROI models show when that investment is recoverable within a 3–5 year horizon under conservative volume assumptions.
-
Consider upstream integration where strategic: For vertically oriented players, securing gluconic acid capacity (or long‑term glucose contracts) can be a defensible hedge against raw material volatility. The report includes capex break‑even timelines and alternative options such as tolling agreements.
-
Use scenario planning for contracting: Re‑negotiate supply agreements with embedded flexibility—volume bands tied to price indices, defined force majeure triggers, and clear escalation paths. We provide template clauses and negotiation playbooks tailored for 2026 contracting cycles.
-
Pursue product premiumization: Where regulatory access and branding permit, migrating customers toward higher‑purity or pre‑filled/ready‑to‑administer forms improves margin and reduces direct price competition; our commercial playbook demonstrates how to capture that value.
Why PW Consulting’s perspective is unique
Our analysis integrates granular supplier intelligence with macroeconomic scenario modeling—combining operational, regulatory and commercial lenses into a single decision‑grade deliverable. We deliberately balance depth with commercial confidentiality: the report surfaces supplier risk rankings, regulatory filing gaps, and strategic playbooks while withholding proprietary contract-level data that clients should access via our full dataset and dashboards.
Next steps and where to get the full intelligence
For procurement heads, strategy teams, and corporate development leads setting priorities for 2026, this research provides the evidence base to reconfigure supply chains, prioritize regulatory spend, and evaluate M&A targets. Because the most actionable parts of this research are in the detailed segment tables, supplier dossiers, and interactive scenario models, we invite decision‑makers to access the full report and supporting datasets on our report page. The companion datasets include supplier‑level certifications, timeline maps for filings by jurisdiction, and downloadable financial models you can adapt for internal use.
Reach out to PW Consulting to schedule a briefing and a walk‑through of the interactive dashboards that underpin the findings summarized here—so your 2026 strategies start from a position of informed clarity rather than reactive scrambling.
For detailed analysis of this topic, please visit the official page: Calcium Gluconate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sodium Hypochlorite Market at USD 320.53M in 2025; 4.9% CAGR to 2032
By pmarketresearch, 2026-07-30
Sodium Hypochlorite Market: Strategic Imperatives for 2026 — A PW Consulting Industry Brief
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, actionable orientation to our full Sodium Hypochlorite Market study. This brief surfaces the macro trends, competitive dynamics, and decision-grade implications that matter for corporate leaders planning capital allocation, commercial strategy, and supply-chain resilience in 2026. The purpose is to demonstrate the analytical depth informing our recommendations while intentionally withholding granular segment and regional breakdowns to direct you to the full report for transaction-ready intelligence.
Sodium Hypochlorite Market
Market Trajectory at a Glance
The sodium hypochlorite market has shown steady expansion over the past half-decade and is positioned for continued growth through the next planning cycle. On a consolidated basis (base year 2025), the market expanded from roughly USD 205 million in 2020 to about USD 320.5 million in 2025. Our modeled outlook projects growth to approximately USD 445.7 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.9% across the 2026–2032 forecast window.
Sodium Hypochlorite Market
Two implications follow immediately for 2026 planning: first, scale matters. The market is large enough to support differentiated investment plays (capacity expansion, product innovation, service offering layers) but remains compact enough that supply-side moves by a handful of producers materially affect pricing and availability. Second, predictability is moderate — growth is constructive but exposed to feedstock, regulatory, and trade-policy shocks that can compress margins or create short-term spikes in procurement costs.
Sodium Hypochlorite Market
What the Full Report Delivers (Practical, Transaction-Ready)
- Proprietary demand model: scenario-based forecasts with sensitivity to feedstock prices, municipal capex cycles, and hygiene-driven demand elasticity.
- Supply-side playbook: plant-level capacity analysis, utilization benchmarks, and a supplier capability matrix to prioritize counterparties by reliability, grade range, and lead-time risk.
- Pricing & margin toolkit: gross-margin drivers, break-even maps under alternative chlorine and caustic-soda price scenarios, and recommended contract structures for 2026 procurement negotiations.
- Regulatory and tariff radar: a living map of policy levers (environmental limits, import tariffs, hazardous substance rules) that influence production options and cross-border flows.
- M&A and partnership screen: criteria-based shortlist methodology for target selection, integration risk scoring, and synergistic value levers for acquisitions or joint ventures.
- Operational checklists: practical steps for ramping capacity, retrofitting assets for lower-corrosion formulations, and digitizing production controls to reduce energy and chemical waste.
Each module is designed to be actionable within a 90–180 day execution window for commercial, procurement, or corporate development teams.
Competitive Landscape — Who Moves Markets
The sodium hypochlorite industry today is characterized by a mix of large, integrated chemical producers and specialized regional manufacturers and distributors. Market concentration metrics show a moderate level of concentration among the leading producers, with the top three and top five players capturing meaningful share and influence. This creates an environment where capacity additions, planned shutdowns, or strategic repositioning by any leading firm can ripple across the market.
Key industry participants profiled in our report include established chemical majors and focused chloride-chem firms. In high-level terms:
- Large integrated chemical producers leverage chlor-alkali integration and scale logistics networks to serve municipal water-treatment and industrial customers with predictable supply and broad product portfolios.
- Regional specialists and distributors focus on last-mile service, tailored formulations, and rapid-response logistics for municipal customers and industrial accounts with specific purity or handling requirements.
- Smaller domestic manufacturers often occupy niche geographies or application verticals where proximity, technical service, and compatibility with local regulatory frameworks drive preference.
Recent industry moves emphasize these dynamics. Notable developments during 2025 highlighted in our analysis include capacity expansions by North American and European producers, product launches emphasizing reduced corrosivity and environmental impact, and strategic technology partnerships to improve digital control and process optimization. These actions underscore two strategic threads: producers are defensive on availability and offensive on product differentiation.
Key Industry Dynamics Shaping 2026 Decisions
Five structural forces will dominate executive agendas for the next 12–24 months:
- Feedstock volatility: Chlorine and caustic soda cost trajectories remain the primary cost lever for sodium hypochlorite producers. Periodic tightening of chlorine supply (driven by environmental constraints on chlor-alkali operations and regional capacity shifts) can rapidly increase input costs and raise the value of contracted supply.
- Regulatory pressure: Environmental restrictions and evolving wastewater and chemical-handling requirements are constraining some production footprints while creating incentives for lower-corrosion, lower-emissions formulations and process upgrades.
- Trade and tariff dynamics: New trade measures have added a layer of cost uncertainty on imported feedstock, altering cross-border flow economics and nudging some manufacturers to localize or re-price their sourcing strategies.
- Labor and operational constraints: Staffing shortages and labor complexity at some chlor-alkali facilities limit the ability to flex production rapidly. This creates a premium on operational agility and contingency sourcing in procurement playbooks.
- Customer demand mix: While water treatment remains a core demand driver, household cleaning, textiles, and chemical synthesis continue to shape seasonal and regional demand patterns. Buyers increasingly prize service reliability, documentation (compliance/traceability), and lower-environmental-impact chemistries.
Strategic Actions for 2026 — What Boards and Execs Should Prioritize
Our research crystallizes a short list of prioritized actions that balance growth capture with risk mitigation. These are practical choices companies can start implementing in 2026:
- Hedge and diversify feedstock exposure: Move toward multi-supplier feedstock contracts, indexed pricing features, and, where feasible, upstream integration or tolling arrangements to stabilize cost of goods sold.
- Prioritize brownfield capacity expansions and retrofits over greenfield projects: Given permitting and regulatory timelines, retrofits that increase yield or produce specialty, lower-corrosion grades deliver faster time-to-market and better IRR profiles under current forecasts.
- Differentiate on environmental credentials and service: Investing in less-corrosive formulations, clear compliance documentation, and emergency-response logistics will widen commercial moats in municipal and healthcare segments.
- Adopt digital operations: Use process-optimization partnerships and digital twins to reduce energy usage, chemical waste, and unplanned downtime—yielding direct EBIT uplift and reducing exposure to input-price shocks.
- Prepare opportunistic M&A playbooks: Look for targets with strategic geography, excess electrolyzer capacity, or value-added formulations; prioritize bolt-on acquisitions with clear synergies in distribution or technical service.
- Stress-test contracts and contingency plans: Elevate scenario-planning capabilities for sudden chlorine shortages, tariff escalations, or localized production outages; ensure commercial teams have playbooks for re-routing supply and communicating changes to key customers.
Operational KPIs to Watch in 2026
To translate strategy into measurable outcomes, PW Consulting recommends monitoring a compact KPI set monthly or quarterly:
- Feedstock cost per ton and percent of purchases under fixed-price contracts.
- Plant utilization and unplanned downtime hours attributable to regulatory or labor constraints.
- Inventory days on hand and contract coverage ratio for critical accounts.
- Sales mix by grade and application cohort (tracked privately to avoid disclosing public segment data).
- Customer satisfaction and service-level breach frequency for municipal contracts.
- Regulatory exposure index capturing number of affected plants, pending permits, and potential tariff impacts.
Why This Matters to Decision-Makers in 2026
2026 is a pivot year: macro demand is steady, but structural risks and opportunities are concentrated. Companies that lock in reliable, cost-efficient feedstock; create differentiated, lower-impact products; and fortify supply chains will convert the market’s moderate growth into sustainable margin expansion. Conversely, firms that fail to address feedstock exposure, regulatory compliance, and service reliability risk being squeezed by both cost inputs and customer churn.
Our full study equips executives with the quantitative models, supplier intelligence, regulatory mapping, and M&A screening necessary to execute these moves with confidence. It lays out not just what is likely to happen, but how to act — with a prioritized, stage-gated set of initiatives tailored for the 2026 decision calendar.
Next Steps
For teams preparing budgets, capital plans, or acquisition screens in 2026, PW Consulting’s full Sodium Hypochlorite Market report provides the granular segmentation, deal-level guidance, and plant-level analytics required to move from strategy to execution. The detailed breakdowns, substantiated by our proprietary models and field-sourced supplier intelligence, are intentionally presented in the full report to support deal negotiation and procurement contracting.
Contact PW Consulting to access the complete report and accompanying toolkits so your organization can convert market visibility into measurable competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Sodium Hypochlorite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com