

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Silicon Nitride (CAS 12033-89-5) — $113M in 2025, 7.1% CAGR to 2032

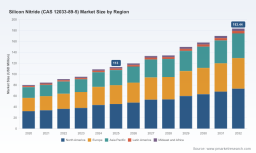
Silicon Nitride (CAS 12033-89-5) Market: Strategic Primer for 2026 Decision‑Makers
Market snapshot — what the numbers tell you (without giving your competitors everything)
The silicon nitride (Si3N4) market is no longer a niche materials story; it is a maturing, capital‑intensive ecosystem that is moving from specialty applications toward scaled industrial adoption. Our market model (base year 2025; historical 2020–2025; forecast 2026–2032) shows steady, mid‑single‑digit to high‑single‑digit growth driven by demand resilience in bearings, advanced automotive components, medical implants, and select electronics manufacturing uses. Measured in USD Million, the market expanded materially across the 2020–2025 period and, under our base forecast, continues to compound at a 7.1% CAGR through 2032 to reach a substantially larger global revenue pool.
Silicon Nitride (CAS 12033-89-5) Market
These headline metrics matter for 2026 planning because they convert an otherwise technical materials conversation into a portfolio-level commercial opportunity: predictable topline expansion, concentrated supplier economics, and accelerating pockets of system-level adoption (notably medical devices and high-performance mobility components). We intentionally present the macro trajectory here to allow strategy teams to size the opportunity quickly while reserving the granular segmentation and proprietary unit economics for the full PW Consulting study.
Silicon Nitride (CAS 12033-89-5) Market
Why this research is strategically valuable for 2026 decisions
-
Translate materials science into business outcomes — The market’s trajectory means Si3N4 moves from a specialty raw material to a strategic lever for product differentiation (wear life, thermal stability, biocompatibility). R&D and product teams need a clear translation of material performance into commercial KPIs: cost per cycle, warranty exposure, and service interval economics.
Silicon Nitride (CAS 12033-89-5) Market -
Procurement and supply resilience — With a supplier base that includes entrenched Asian and European producers, procurement teams must plan for purity‑driven sourcing strategies, dual‑sourcing constraints, and potential premium pricing windows driven by raw material specifications.
-
Regulatory and clinical inflection points — Regulatory clearances (notably in medical devices) create first‑mover advantages and new TAMs. Understanding the timing and practical implications of approvals is essential to prioritize commercialization investments in 2026.
-
M&A, JV and vertical integration signals — Given moderate market concentration and technology differentiation, corporate development teams can identify targets for bolt‑on capability (powder synthesis, sintering, device manufacturing) that accelerate time to market.
What the PW Consulting report contains — operationally useful deliverables
-
Proprietary market model (2020–2032) with revenue forecasts by type, application and region, scenario sensitivity and breakouts by production vs. component value capture. (Note: granular splits are reserved for report subscribers.)
-
Price and margin benchmarking — supplier price bands, raw material cost drivers, and indicative manufacturing cost curves for common ceramic processing routes.
-
Technology roadmap and adoption timeline — comparative analysis of sintering routes, reaction‑bonded vs. hot‑pressed approaches, and the practical performance tradeoffs in volume production.
-
Regulatory impact and go‑to‑market playbooks — assessment of medical device pathways, certifications, and how regulatory clearances change demand profiles for FDA‑registered manufacturing capacity.
-
Supplier and capability map — verified supplier profiles, strategic strengths, capacity constraints, and an assessment of where value is captured along the powder‑to‑component chain.
-
M&A and partnership scanner — targets categorized by technology, geostrategy, and integration fit; an outcomes matrix showing time‑to‑value for 12‑ and 36‑month investment horizons.
-
Risk heatmap and mitigation playbook — supply shocks, regulatory delays, feedstock shortages, and tactical procurement/hedging options.
Competitive landscape — actionable intelligence on the key players
-
Japanese producers (UBE, Denka, KYOCERA) — These firms dominate the high‑purity powder space and are notable for tight quality control on metallic impurities and oxygen content. Their product portfolios span semiconductor‑grade to industrial grades and their pricing reflects purity tiers. Strategic implication: buyers seeking medical or semiconductor‑grade feedstock should prioritize early qualification and build supply continuity agreements with Japanese suppliers or equivalent capable alternatives.
-
European specialists (AlzChem, H.C. Starck, CeramTec, Saint‑Gobain) — These players compete on specialized chemistries and value‑added components (e.g., hot‑pressed structural ceramics). Their strengths lie in engineered grades for automotive and aerospace and in established relationships with tier‑1 industrial customers. Strategic implication: technology licensing, co‑development and component outsourcing are practical routes for OEMs looking to accelerate adoption without large capex for new ceramic lines.
-
SINTX Technologies (U.S.) — The company is unique in a regulatory sense: it operates the only FDA‑registered silicon nitride medical device manufacturing facility and has taken medical device approvals through the 510(k) pathway. That regulatory moat enables commercial entry into implant markets with a first‑mover advantage for certain orthopaedic applications. Strategic implication: medical device OEMs and investors should treat SINTX’s regulatory progress as a market architect — either as a partner or as a competitive risk to mitigate through clinical differentiation.
-
Chinese producers (e.g., Hebei Suoyi) — These vendors offer competitive pricing on standard grades and are scaling capacity for commodity applications (refractories, low‑spec bearings). Strategic implication: cost‑sensitive applications can lean on competitively priced standard grades, but quality gating and downstream warranty exposure must be managed through tightened incoming inspection and process controls.
Key recent developments and their implications
-
Regulatory milestone: SINTX’s 510(k) journey — In mid‑2025 SINTX submitted a 510(k) for silicon nitride osteotomy wedges and received clearance in October 2025 for a foot & ankle osteotomy wedge system. For 2026 planning, this converts a previously “emerging” clinical use case into a commercially addressable market segment with payment, distribution and liability dynamics that differ from non‑implant uses.
-
Supply and pricing dynamics — Japanese producers’ dominance in high‑purity powder creates a two‑tier market. High‑purity grades (metallic impurities <50 ppm, oxygen <1.5 wt%) command premium pricing; standard grades (materially higher impurity thresholds) are available at materially lower price points. The pricing spread establishes both margin pools and substitution thresholds: when engineering specs allow, buyers can materially reduce material costs by qualifying lower grades.
-
Consolidation signals — Market concentration is meaningful but not concentrated to monopoly levels: the top three vendors capture a meaningful share (CR3 ~36.5%) and the top five ~42.0% (CR5). This structure creates room for strategic alliances, selective M&A and niche incumbency rather than full oligopoly pricing power.
Strategic playbook for executives in 2026
-
Procurement: implement a tiered sourcing strategy that matches powder grade to application risk profile. Qualify at least one high‑purity supplier and one cost‑effective standard supplier to create optionality.
-
R&D: prioritize validation plans that translate Si3N4 material benefits into warranty and lifecycle KPIs. For medical and safety‑critical mobility applications, align clinical/regulatory milestones with product launch and commercial forecasting.
-
Corporate development: build M&A screening criteria that favor firms with either regulatory assets (e.g., FDA‑registered manufacturing) or unique powder synthesis IP. Expect near‑term value creation from bolt‑on capabilities that shorten qualification timelines.
-
Manufacturing: evaluate CAPEX for sintering and machining capacity only after mapping the total addressable component margin. In many cases, partnering with established component houses accelerates time to revenue more cost effectively than greenfield builds.
How to use the PW Consulting study in 90 days
-
Week 1–2: Executive readout — Use our macro snapshot and supplier matrix to align leadership on opportunity size and strategic priorities.
-
Month 1: Procurement deep‑dive — Deploy our price benchmarks and supplier capability map to issue a two‑tier RFP and begin supplier qualifications.
-
Month 2–3: Commercial decision — Combine our regulatory timeline and adoption scenarios with internal product roadmaps to set launch windows and investment approvals.
Next step — where the hidden detail lives
This primer intentionally surfaces the strategic implications, supplier archetypes, regulatory inflection points and headline economics (2020–2025 historical trends; base year 2025; forecast 2026–2032 at a 7.1% CAGR). It does not disclose the full, actionable segmentation matrices, regional breakdowns, or per‑application revenue shares that underpin our commercial recommendations — those are preserved in the full PW Consulting report and our model files to protect client value and ensure robust use of our IP.
If you are evaluating entry, procurement, or M&A in Si3N4 for 2026 planning, the complete study provides the calibrated segmentation, supplier scorecards, unit‑cost build‑ups, and policy/regulatory annexes needed to make confident, executable decisions. Contact PW Consulting for access to the full report and the model to run your custom scenarios.
For detailed analysis of this topic, please visit the official page: Silicon Nitride (CAS 12033-89-5) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com