

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sodium Hypochlorite Market at USD 320.53M in 2025; 4.9% CAGR to 2032

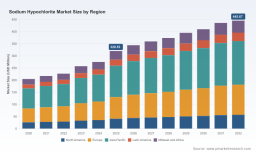
Sodium Hypochlorite Market: Strategic Imperatives for 2026 — A PW Consulting Industry Brief
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, actionable orientation to our full Sodium Hypochlorite Market study. This brief surfaces the macro trends, competitive dynamics, and decision-grade implications that matter for corporate leaders planning capital allocation, commercial strategy, and supply-chain resilience in 2026. The purpose is to demonstrate the analytical depth informing our recommendations while intentionally withholding granular segment and regional breakdowns to direct you to the full report for transaction-ready intelligence.
Sodium Hypochlorite Market
Market Trajectory at a Glance
The sodium hypochlorite market has shown steady expansion over the past half-decade and is positioned for continued growth through the next planning cycle. On a consolidated basis (base year 2025), the market expanded from roughly USD 205 million in 2020 to about USD 320.5 million in 2025. Our modeled outlook projects growth to approximately USD 445.7 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.9% across the 2026–2032 forecast window.
Sodium Hypochlorite Market
Two implications follow immediately for 2026 planning: first, scale matters. The market is large enough to support differentiated investment plays (capacity expansion, product innovation, service offering layers) but remains compact enough that supply-side moves by a handful of producers materially affect pricing and availability. Second, predictability is moderate — growth is constructive but exposed to feedstock, regulatory, and trade-policy shocks that can compress margins or create short-term spikes in procurement costs.
Sodium Hypochlorite Market
What the Full Report Delivers (Practical, Transaction-Ready)
- Proprietary demand model: scenario-based forecasts with sensitivity to feedstock prices, municipal capex cycles, and hygiene-driven demand elasticity.
- Supply-side playbook: plant-level capacity analysis, utilization benchmarks, and a supplier capability matrix to prioritize counterparties by reliability, grade range, and lead-time risk.
- Pricing & margin toolkit: gross-margin drivers, break-even maps under alternative chlorine and caustic-soda price scenarios, and recommended contract structures for 2026 procurement negotiations.
- Regulatory and tariff radar: a living map of policy levers (environmental limits, import tariffs, hazardous substance rules) that influence production options and cross-border flows.
- M&A and partnership screen: criteria-based shortlist methodology for target selection, integration risk scoring, and synergistic value levers for acquisitions or joint ventures.
- Operational checklists: practical steps for ramping capacity, retrofitting assets for lower-corrosion formulations, and digitizing production controls to reduce energy and chemical waste.
Each module is designed to be actionable within a 90–180 day execution window for commercial, procurement, or corporate development teams.
Competitive Landscape — Who Moves Markets
The sodium hypochlorite industry today is characterized by a mix of large, integrated chemical producers and specialized regional manufacturers and distributors. Market concentration metrics show a moderate level of concentration among the leading producers, with the top three and top five players capturing meaningful share and influence. This creates an environment where capacity additions, planned shutdowns, or strategic repositioning by any leading firm can ripple across the market.
Key industry participants profiled in our report include established chemical majors and focused chloride-chem firms. In high-level terms:
- Large integrated chemical producers leverage chlor-alkali integration and scale logistics networks to serve municipal water-treatment and industrial customers with predictable supply and broad product portfolios.
- Regional specialists and distributors focus on last-mile service, tailored formulations, and rapid-response logistics for municipal customers and industrial accounts with specific purity or handling requirements.
- Smaller domestic manufacturers often occupy niche geographies or application verticals where proximity, technical service, and compatibility with local regulatory frameworks drive preference.
Recent industry moves emphasize these dynamics. Notable developments during 2025 highlighted in our analysis include capacity expansions by North American and European producers, product launches emphasizing reduced corrosivity and environmental impact, and strategic technology partnerships to improve digital control and process optimization. These actions underscore two strategic threads: producers are defensive on availability and offensive on product differentiation.
Key Industry Dynamics Shaping 2026 Decisions
Five structural forces will dominate executive agendas for the next 12–24 months:
- Feedstock volatility: Chlorine and caustic soda cost trajectories remain the primary cost lever for sodium hypochlorite producers. Periodic tightening of chlorine supply (driven by environmental constraints on chlor-alkali operations and regional capacity shifts) can rapidly increase input costs and raise the value of contracted supply.
- Regulatory pressure: Environmental restrictions and evolving wastewater and chemical-handling requirements are constraining some production footprints while creating incentives for lower-corrosion, lower-emissions formulations and process upgrades.
- Trade and tariff dynamics: New trade measures have added a layer of cost uncertainty on imported feedstock, altering cross-border flow economics and nudging some manufacturers to localize or re-price their sourcing strategies.
- Labor and operational constraints: Staffing shortages and labor complexity at some chlor-alkali facilities limit the ability to flex production rapidly. This creates a premium on operational agility and contingency sourcing in procurement playbooks.
- Customer demand mix: While water treatment remains a core demand driver, household cleaning, textiles, and chemical synthesis continue to shape seasonal and regional demand patterns. Buyers increasingly prize service reliability, documentation (compliance/traceability), and lower-environmental-impact chemistries.
Strategic Actions for 2026 — What Boards and Execs Should Prioritize
Our research crystallizes a short list of prioritized actions that balance growth capture with risk mitigation. These are practical choices companies can start implementing in 2026:
- Hedge and diversify feedstock exposure: Move toward multi-supplier feedstock contracts, indexed pricing features, and, where feasible, upstream integration or tolling arrangements to stabilize cost of goods sold.
- Prioritize brownfield capacity expansions and retrofits over greenfield projects: Given permitting and regulatory timelines, retrofits that increase yield or produce specialty, lower-corrosion grades deliver faster time-to-market and better IRR profiles under current forecasts.
- Differentiate on environmental credentials and service: Investing in less-corrosive formulations, clear compliance documentation, and emergency-response logistics will widen commercial moats in municipal and healthcare segments.
- Adopt digital operations: Use process-optimization partnerships and digital twins to reduce energy usage, chemical waste, and unplanned downtime—yielding direct EBIT uplift and reducing exposure to input-price shocks.
- Prepare opportunistic M&A playbooks: Look for targets with strategic geography, excess electrolyzer capacity, or value-added formulations; prioritize bolt-on acquisitions with clear synergies in distribution or technical service.
- Stress-test contracts and contingency plans: Elevate scenario-planning capabilities for sudden chlorine shortages, tariff escalations, or localized production outages; ensure commercial teams have playbooks for re-routing supply and communicating changes to key customers.
Operational KPIs to Watch in 2026
To translate strategy into measurable outcomes, PW Consulting recommends monitoring a compact KPI set monthly or quarterly:
- Feedstock cost per ton and percent of purchases under fixed-price contracts.
- Plant utilization and unplanned downtime hours attributable to regulatory or labor constraints.
- Inventory days on hand and contract coverage ratio for critical accounts.
- Sales mix by grade and application cohort (tracked privately to avoid disclosing public segment data).
- Customer satisfaction and service-level breach frequency for municipal contracts.
- Regulatory exposure index capturing number of affected plants, pending permits, and potential tariff impacts.
Why This Matters to Decision-Makers in 2026
2026 is a pivot year: macro demand is steady, but structural risks and opportunities are concentrated. Companies that lock in reliable, cost-efficient feedstock; create differentiated, lower-impact products; and fortify supply chains will convert the market’s moderate growth into sustainable margin expansion. Conversely, firms that fail to address feedstock exposure, regulatory compliance, and service reliability risk being squeezed by both cost inputs and customer churn.
Our full study equips executives with the quantitative models, supplier intelligence, regulatory mapping, and M&A screening necessary to execute these moves with confidence. It lays out not just what is likely to happen, but how to act — with a prioritized, stage-gated set of initiatives tailored for the 2026 decision calendar.
Next Steps
For teams preparing budgets, capital plans, or acquisition screens in 2026, PW Consulting’s full Sodium Hypochlorite Market report provides the granular segmentation, deal-level guidance, and plant-level analytics required to move from strategy to execution. The detailed breakdowns, substantiated by our proprietary models and field-sourced supplier intelligence, are intentionally presented in the full report to support deal negotiation and procurement contracting.
Contact PW Consulting to access the complete report and accompanying toolkits so your organization can convert market visibility into measurable competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Sodium Hypochlorite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com