

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dissolving Pulp Market to Top USD 8,179.41M by 2032 at 3.05% CAGR

Dissolving Pulp Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s new market study on Dissolving Pulp is designed as a strategic instrument for executives, investors and functional leaders making binding choices in 2026. Anchored on a base year of 2025 and covering a historical window (2020–2025) plus a forward-looking forecast (2026–2032), the research translates macro momentum into operationally relevant implications. In short: it tells you where the market is headed (and why), what that means for your cost, sourcing and go-to-market choices, and which tactical moves preserve optionality while capturing value.
Dissolving Pulp Market
Why this study matters for 2026 decisions
-
Timing: 2026 is a hinge year. The market’s medium-term trajectory is modest but persistent — our modelling produces a compound annual growth rate (CAGR) of 3.05% across the forecast window. Small differences in capacity planning, feedstock contracts or product mix executed in 2026 compound materially by 2032.
Dissolving Pulp Market -
Strategic exposure: Dissolving pulp sits at the intersection of textiles, cellulose derivatives and specialty applications (pharma/food/cosmetics). Decisions in procurement, vertical integration or commercial partnerships affect both up- and downstream economics.
Dissolving Pulp Market -
Regulatory and trade volatility: Trade investigations and changing environmental standards are introducing non-price shocks. Firms that integrate regulatory scenarios into 2026 planning reduce downside and preserve optionality.
Market trajectory at a glance (what the numbers mean)
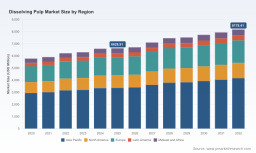
Using USD million as the reporting unit and a 2025 base, the market has expanded from a multi-billion dollar base in 2020 through 2025 and continues to grow into the early 2030s. Our compiled series shows steady year-on-year increases across the historical period, reaching an assessed market value of approximately 6,629 USD Million in 2025. Under the central forecast (3.05% CAGR), the market rises to a low-mid single-digit growth path through 2032, culminating in an assessed market size of roughly 8,179 USD Million by 2032.
Two practical implications flow directly from those macro numbers. First, marginal capacity investments must be evaluated on a multi-year basis: modest CAGR means that brownfield optimizations and product-mix adjustments will often offer higher IRR than large greenfield expansions unless they are coupled with de-risked feedstock or captive offtake. Second, strategic buyers and sellers should price in a slow-but-steady demand uplift rather than a near-term boom — value capture will come primarily from cost discipline, differentiated product grades and route-to-market innovations.
Competitive structure — concentration and what it implies
The dissolving pulp market is meaningfully concentrated: our concentration metrics indicate the top three players account for roughly 51.2% of market throughput, while the top five together account for about 62.5%. This industry structure generates a mixed strategic landscape:
-
Pricing resilience for large integrated players — they can defend margins through scale, backward integration and access to premium woodfibre sources.
-
Opportunity windows for specialized participants — niche grades, specialty cellulose and value-added services (e.g., consistent quality for pharmaceutical or cosmetic supply chains) create pockets of higher return.
-
M&A and alliance economics — consolidation or capacity redeployment can be value accretive if executed with a clear feedstock and offtake logic, given the market’s clustering in a handful of players.
Key industry players — strategic positioning (high-level)
-
Bracell (Brazil): A global leader with an asset footprint oriented to eucalyptus-based dissolving pulp and a growing emphasis on rayon and specialty grades. Recent capacity reallocation decisions are an example of strategic response to downstream demand shifts. ( https://www.bracell.com/en/)
-
Sappi Limited (South Africa): Focused on high-purity cellulose for textile and specialty applications under established brands; strong emphasis on quality and downstream relationships. ( https://www.sappi.com/en-us/)
-
Rayonier Advanced Materials Inc. (United States): A producer with mill-level focus on high-purity dissolving pulp for cellulose derivatives and pharmaceutical applications; reputational strength in quality and sustainability. ( https://ryam.com/)
-
Lenzing AG (Austria): An integrated participant supplying dissolving pulp for regenerated fibers with an emphasis on certified sources and product traceability; an example of a vertically aligned model. ( https://www.lenzing.com/)
-
Aditya Birla Group / Grasim Industries / Birla Cellulose (India): An integrated producer whose global assets and downstream partnerships underpin supply to viscose producers and related converters. ( https://www.grasim.com/)
-
Neucel Specialty Cellulose Ltd. (Canada): Specialist in high alpha-cellulose grades (notably hemlock-derived); niche technical improvements are a competitive differentiator for pharma and film-making applications.
Recent dynamics and their 2026 implications
-
Capacity reallocation: In late 2025 a major producer announced reconfiguration of lines to prioritize dissolving pulp. Such moves tighten near-term commodity-grade pulp supply and reallocate feedstock and logistics resources. For buyers, this increases the importance of flexible offtake clauses and multi-sourcing strategies in 2026 contracts.
-
Trade investigations: A countervailing duty probe initiated in 2025 into imports from a key producing country introduces policy risk that can change landed costs and reroute trade flows within months. Scenario-based procurement and contractual protective provisions (e.g., price reopeners) are tactical necessities.
-
Feedstock pressure: Historical weather events and transport cost inflation pushed certain wood-chip prices materially higher in recent years. This cost transmission affects mill cash margins and alters the relative attractiveness of eucalyptus versus softwood feedstocks — a core input variable for 2026 planning.
Where value will be captured in 2026–2032
Based on our integrated demand-supply modelling and interviews with downstream converters, four avenues consistently deliver superior returns for incumbent and new entrants alike:
-
Grade differentiation: Premiumization into high-purity and specialty grades for pharma, cosmetics and high-performance textiles merits price premiums that outpace the baseline market CAGR.
-
Vertical or contractual integration: Securing reliable feedstock through long-term fibre agreements, tolling arrangements, or captive plantations reduces input volatility and can compress landed costs.
-
Operational excellence: Incremental improvements in yield, energy use and chemical recovery typically offer faster payback than greenfield capacity, given the market’s moderate growth pace.
-
Regulatory foresight: Proactive compliance and sustainable sourcing credentials unlock premium buyers and reduce trade disruption risks — an increasingly material commercial differentiator.
What PW Consulting’s report delivers — practical contents
The study is not an academic exercise: it is a toolbox for executives. Key components include:
-
Demand-supply balances and a forward capacity map (2026–2032), with scenario variants reflecting trade-policy shocks and feedstock stress events.
-
Price-impact analysis and margin sensitivity by grade, including a unit-economics framework you can apply to your asset base.
-
Commercial playbooks: tailored GTM options for producers, integrated converters and traders, including contracting templates and risk-sharing structures.
-
M&A and partnership scorecards: methodical screening criteria and valuation guidance for targets across the value chain.
-
Regulatory and ESG risk matrix: jurisdictional heatmaps and mitigation checklists for 2026 procurement and investment approvals.
-
Operational diagnostics: a step-by-step recovery and efficiency roadmap for mills, with prioritized capex vs. opex interventions by expected payback horizon.
How to use the study in 2026 — action-oriented recommendations
-
For producers: prioritize short-cycle yield and recovery projects that improve margin resilience; defer large greenfield commitments unless paired with secured offtake or captive fibre.
-
For traders and buyers: renegotiate contracts to include adaptive pricing or force majeure clauses that account for trade remedial actions and feedstock shocks.
-
For investors and M&A teams: use the CR and scenario outputs to stress-test targets against policy risk and feedstock volatility — value is concentrated but idiosyncratic upside exists in specialty grades.
-
For sustainability officers: accelerate traceability and third-party certification programs to reduce commercialization friction and access premium channels.
Final note — why this is a teaser, and where to get the full intelligence
This executive briefing demonstrates the depth and orientation of PW Consulting’s dissolving pulp research: it connects market-level growth, structural concentration and concrete commercial actions. Per our “trailer” approach, we have intentionally withheld granular regional and application-specific splits, detailed unit-cost schedules and the full set of scenario tables that form the operational core of the study. Those elements are essential for constructing binding 2026 budgets, ERP inputs and M&A valuations.
To obtain the complete dataset, interactive models and the full suite of playbooks and checklists (including downloadable Excel modules and scenario dashboards), please refer to the PW Consulting report landing page where you can download or license the full deliverable. The full report furnishes the segmented demand curves, regional and application breakdowns, and granular sensitivity analyses you will need to finalize 2026 capital, procurement and commercial plans.
PW Consulting — we translate market intelligence into executable strategy. Reach the report and our advisory team to schedule a deep-dive session that aligns these findings to your specific asset, portfolio or investment thesis for 2026.
For detailed analysis of this topic, please visit the official page: Dissolving Pulp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com