

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: X-ray Radiation Protection Glass Market to hit USD 368.47M by 2032 (8% CAGR)

Medical X-ray Radiation Protection Glass Market: Strategic Briefing for 2026 Decisions
PW Consulting’s new market study on Medical X‑ray Radiation Protection Glass frames the commercial and regulatory inflection points that will shape supplier and buyer strategy in 2026. Built on a 2020–2025 historical base (base year 2025) and projecting through 2026–2032, the study models an industry expanding at an 8.0% CAGR. The global market stands at approximately USD 215.0 Million in 2025 and is projected to grow to the mid‑hundreds of millions by 2032 under the base forecast. This briefing highlights the research’s decision‑support value for capital allocation, product positioning, M&A, and procurement strategy—while preserving the granular segment tables and vendor scorecards that are available in the full report.
Medical X-ray Radiation Protection Glass Market
Why this study matters for 2026
-
Consolidated demand signal: Diagnostic and interventional imaging workloads, replacement cycles for aging radiology infrastructure, and increased regulatory scrutiny are converging to create predictable, multi-year demand for certified radiation‑protective glass and integrated shielding systems.
Medical X-ray Radiation Protection Glass Market -
Regulatory regime shift: New EU standards and updated national certification procedures implemented in 2025 materially raise compliance requirements for lead‑based and alternative shielding materials. Buyers and suppliers who can demonstrate certification readiness will capture higher‑margin tenders.
Medical X-ray Radiation Protection Glass Market -
CapEx timing and reimbursement pressure: Healthcare reimbursement and coding changes for 2026 are driving tighter capital discipline in many systems. Procurement teams will prioritize modular, low‑disruption retrofit solutions and vendors that can offer turn‑key installation and certification services.
What’s in the full report (operational deliverables)
-
Market sizing and validated forecast models (2020–2032) in USD Million with scenario sensitivity for regulatory tightening and raw‑material pricing.
-
Demand drivers mapped by procurement channel (hospitals, diagnostic centers, OEMs) and buyer persona definitions for radiology directors, hospital engineers, and procurement officers.
-
Regulatory and certification matrix covering national standards, EU 2025 changes, and recommended compliance checkpoints for procurement contracts.
-
Supply chain and cost‑to‑serve analysis: raw material exposure, fabrication bottlenecks, lead time ladders, and a contractor readiness assessment for professional installation services.
-
Competitive vendor scorecards, go‑to‑market playbooks, pricing archetypes, and an M&A playbook identifying consolidation vectors (technology, capacity, geographic footprint).
-
Excel deliverables: fully auditable financial model, unit cost simulator, and procurement negotiation templates for 3‑, 5‑, and 7‑year contracting horizons.
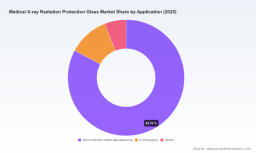
Note: This brief deliberately omits granular split tables (regional, type and application line items) to preserve the “trailer” effect. The full segmentation detail and drill‑downs are accessible via the PW Consulting report landing page.
Key macro takeaways and strategic implications
-
Market growth profile: With an 8.0% CAGR and clear year‑on‑year expansion from the 2025 base, suppliers should evaluate capacity investments and product roadmaps to avoid reactive price escalation. Buyers should lock multi‑year pricing or service agreements where possible to stabilize budgets.
-
Fragmentation and consolidation potential: The market concentration is low—three‑firm and five‑firm concentration ratios (CR3 ~24.6%, CR5 ~26.2%) indicate a fragmented supplier base. That fragmentation creates acquisition opportunities for vertically integrated players or regional champions seeking scale and margin control.
-
Service‑differentiation is decisive: Professional installation, certification documentation, and warranty‑backed performance are premium purchase criteria. Vendors offering bundled project management, on‑site certification testing and rapid retrofit services will command higher win rates.
-
Regulation as a barrier and an opportunity: Tighter EU and national standards implemented in 2025 raise the procurement bar. Suppliers that invest early in test laboratories, certification pipelines and compliance documentation will convert regulatory friction into commercial advantage.
-
Material and technology transition: Advances in multilayer systems and lead‑equivalent innovations are emerging. Early commercialization of alternatives with demonstrable performance and installation economies can disrupt legacy lead‑glass incumbency—especially in jurisdictions moving towards restricted lead usage.
Competitive landscape: profiles and strategic reads
The competitive set is a mix of legacy glass manufacturers, niche fabricators, and system integrators. Below are focused strategic reads on the market’s core players.
-
Corning Incorporated (Corning, New York): A legacy materials leader with the Corning Med‑X family, Corning’s high lead/barium formulations are a standard in medical X‑ray protection. Strategic advantage: deep material science, scale manufacturing, and an established reputation in hospital procurement. Consideration: incumbency brings pricing power but requires proactive regulatory-proofing and service partnerships to defend retrofit opportunities.
-
SCHOTT AG (Mainz, Germany): SCHOTT’s German‑manufactured RD 30 variants position the firm strongly in regulated environments and safety‑critical installations. Strategic advantage: European certification pedigree and diagnostic market trust. Consideration: must broaden installation and service capabilities to capture bundled tenders from hospital groups.
-
Ray‑Bar Engineering Corporation (Azusa, California): A flexible manufacturer of lead glass and custom laminated solutions with LEED compliance support. Strategic advantage: customization and sustainability credentials. Consideration: scale constraints—strategic alliances with regional installers will improve national account penetration.
-
Ward’s Premise Ltd (Thames Ditton, UK): Distributor and integrator for branded medical glasses, acting as a channel specialist in the UK and select export markets. Strategic advantage: channel reach and project management; potential acquirer candidate for manufacturers seeking direct distribution.
-
MAVIG GmbH (Germany): Offers window and panel systems integrated into X‑ray protection assemblies and mobile shields. Strategic advantage: product systems approach and focus on mobile/ERPD devices. Recent update: Apr 2026 product catalog refresh introduced new mobile shields—an immediate response to retrofit demand for emergency and hybrid suites.
-
Wolf X‑Ray Corporation (US): Specializes in mobile barriers and radiation safety glass for clinical environments. Strategic advantage: nimble manufacturing and project turnarounds for decentralized imaging sites.
-
Radiation Protection Products, Inc. (US): Offers lead‑lined and laminated safety glass with emphasis on impact resistance and optical clarity. Strategic advantage: specification fit for trauma and high‑visibility control booths.
-
Lead Glass Pro (US): Regional manufacturer and installer with recent capacity expansion. Recent development: December 2025 manufacturing expansion and broader installation footprint across 26 states—an aggressive growth move that signals consolidation at the regional level.
Recent developments and strategic implications
-
MAVIG’s April 2026 catalog update indicates a near‑term shift toward mobile shielding products—an attractive segment for hospitals seeking low‑disruption retrofits and rapid deployment.
-
Lead Glass Pro’s late‑2025 expansion demonstrates that regional players can scale quickly to meet national retrofit demand, making them attractive partners or targets for manufacturers lacking direct installation capabilities.
-
H V Skan’s multilayer glass innovation (Dec 2025) underscores the technology risk for legacy lead compositions; incumbents and private equity should prioritize R&D screening and technology scouting.
Risk matrix and recommended 90‑ to 180‑day actions for 2026
-
Regulatory shock (High impact, Medium likelihood): Map certification timelines to purchasing cycles. Action: prioritize vendors with validated EU/ISO certification and insert conditional acceptance clauses tied to certification milestones.
-
Raw material price volatility (Medium impact, Medium likelihood): Hedging and long‑term supply contracts for glass and alloy inputs reduce margin erosion. Action: negotiate supplier cost‑plus with annual cap adjustments and service credits for delayed delivery.
-
Installation capacity constraints (High impact, High likelihood for surge projects): Build or partner for certified installation teams to avoid project slippage. Action: create preferred installer programs and pre‑qualified contractor panels.
-
Technology substitution (Medium impact, Increasing likelihood): Track multilayer/lead‑free alternatives. Action: fund field evaluations and one‑site pilot installs to validate performance under real‑world clinical conditions.
How to use this study in boardroom and procurement cycles
-
Executive strategy: Use the market sizing and CR metrics to inform M&A screens and capex prioritization—target suppliers that close capability gaps (installation, certification, regional production).
-
Business development: Leverage the buyer persona and procurement playbook to design bundled offers (glass + installation + certification) that lock multi‑year service revenue.
-
Procurement teams: Adopt the provided negotiation templates and total cost of ownership model to move beyond price per square foot and into performance/certification‑backed contracting.
Next steps and access to full intelligence
PW Consulting’s full report contains the detailed segmentation tables, revenue splits, vendor scorecards with capabilities and financials, and downloadable modeling assets that operational teams need to execute on the strategies summarized here. The headline market trajectory (8.0% CAGR from a 2025 base of ~USD 215.0 Million) establishes the commercial opportunity; the granular decision levers are reserved for the full report and accompanying deliverables. For procurement teams, corporate development groups, and manufacturers looking to act in 2026, the complete dataset and playbooks will materially shorten time‑to‑decision and reduce execution risk.
Contact PW Consulting or visit the report landing page to request the full study package, a tailored executive briefing, or the Excel model for scenario planning. The window for lock‑in agreements, certification‑led product positioning, and installer network formation is now—being first to operationalize the compliance and service advantages will define winners in 2026.
For detailed analysis of this topic, please visit the official page: Medical X-ray Radiation Protection Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com