

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
South East Asia Additive Masterbatch Market to Hit USD 241.3M by 2032 at 6.5% CAGR

South East Asia Additive Masterbatch Market: Strategic Preview for 2026 Decision-Makers
As plastics value chains in Southeast Asia evolve under pricing pressure, regulatory change and rising demand for functional and recyclable polymers, additive masterbatches sit at the intersection of product performance, cost management and sustainability. This introduction summarizes the strategic value of PW Consulting’s South East Asia Additive Masterbatch Market study for teams making 2026 investment, sourcing and product decisions. It highlights the market trajectory, competitive topology, key dynamics and the practical, decision-ready tools included in the full report—while preserving the granular segment-level figures to encourage direct access to our datasets and models.
South East Asia Additive Masterbatch Market
Market trajectory at a glance
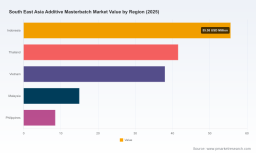
Measured on a consistent base-year (2025), the South East Asia additive masterbatch market has shown steady expansion through the historical window (2020–2025) and continues on a multi-year growth path. Our modeled market size increases from USD 120 Million in 2020 to USD 158.5 Million in 2025, with the near-term projection of USD 170.3 Million for 2026 and a continuing rise to USD 241.3 Million by 2032. This trajectory corresponds to a compound annual growth rate (CAGR) of 6.5% over the forecast period (2026–2032).
South East Asia Additive Masterbatch Market
These macro trends matter: they set the envelope for capacity planning, working capital needs, and the potential scale for new product launches or plant siting decisions. The combination of consistent mid-single-digit growth and pronounced regional heterogeneity creates both low-risk uplift and numerous differentiated playbooks for incumbents and new entrants alike.
South East Asia Additive Masterbatch Market
Why this research is strategically important for 2026
- Timing capital allocation. The report aligns demand projections and scenario variants with capex timing windows, helping executives decide whether to phase expansions, pursue bolt-on capacity or prioritize modular platforms that can be deployed quickly in response to local demand spikes.
- Cost-to-serve optimization. By modeling input-price pass-through and freight sensitivities, the study gives procurement and commercial leaders an evidence base for negotiating supply contracts, setting surcharge policies and re-balancing local vs. imported sourcing.
- Regulatory risk mitigation. With tighter restrictions on certain additive chemistries, the analysis provides options for reformulation, substitution and premium-priced compliant alternatives—vital for customers in food contact, medical and automotive segments.
- Commercial prioritization. Sales and product teams can use our scenario outputs to prioritize applications, customer segments and channel strategies that maximize margin and minimize inventory risk in 2026.
Key market dynamics shaping 2026 decisions
- Upstream resin volatility and feedstock inflation remain primary margin drivers. Industry data shows episodes of sharp masterbatch price spikes tied to polymer resin swings and periodic transport surcharges. Procurement teams should plan hedging and flexible contract mechanisms into 2026 budgets.
- Regulatory tightening across the region is constraining formulation choices and accelerating demand for compliant additive packages. This creates a premium for R&D-enabled, low-risk formulations and gives innovators first-mover advantage in key value chains.
- Logistics and trade-policy noise—short-term freight shocks, transport surcharges and tariff changes—are increasing the cost of cross-border pigment and carrier resin flows. Nearshoring and regional distribution hubs are therefore a higher-return mitigation strategy for many players.
- Labor and operating-cost pressures in select countries are compressing margins for commodity-focused operators, while vertically integrated or specialty producers retain differentiation through technical service and tailored formulations.
Market structure and concentration — strategic implications
The market exhibits a high degree of concentration at the top: the three largest producers account for roughly three quarters of market share, while the top five capture close to 85%. For decision-makers this implies:
- Price leadership and capacity moves by the largest players will materially affect regional pricing and service levels—monitoring competitor capex and plant utilization is essential.
- Smaller, nimble producers can compete on customization, speed-to-market and customer intimacy, offering partnership opportunities for downstream processors seeking differentiated formulations.
- M&A and JV activity is likely to remain an efficient route to scale or to secure specialty chemistries—particularly for firms aiming to move quickly into compliance-driven product categories.
Competitive landscape: profiles and practical takeaways
Our research examines the strategic posture and capabilities of both regional specialists and global suppliers active in Southeast Asia. Highlights include:
- US Masterbatch Joint Stock Company (Hanoi) — regional exporter and specialist in additive masterbatches, with a product set oriented to UV stabilizers, flame retardants and process aids. Strategic implication: attractive partner for regional processors seeking localized technical support and export logistics into ASEAN corridors.
- PMJ Greentech Joint Stock Company (Vietnam) — emphasis on additive and filler masterbatches with customization capability. Strategic implication: strong candidate for co-development projects where customer-specific desiccant or PPA solutions are required.
- Tosaf Compounds Ltd (Israel) — global supplier with a history of cross-regional supply; recent capacity expansion activity signals strategic diversification of production footprint. Strategic implication: watch for competitive pressures on premium packaging and industrial segments as global players broaden local supply.
- TPI Polene (Thailand) — integrated compounder with masterbatch offerings aligned to films and lamination markets. Strategic implication: vertically integrated players may offer cost and supply advantages for large converters; evaluate tradeoffs between price, technical service and lead times.
- SCG Chemicals (Thailand) — strong R&D and product breadth, with focus on color masterbatch and functional enhancements for higher-spec applications. Strategic implication: incumbents with broader polymer portfolios can cross-sell and justify premium pricing for technical solutions.
- Specialist local players (e.g., Thaipoly, Chokdee) — focus on color matching and functional additives for consumer goods. Strategic implication: attractive acquisition or distribution partners for brands prioritizing speed-to-market and close service relationships.
Recent industry moves reinforce these competitive dynamics. A notable capacity expansion by a major global supplier in 2026 and a breakthrough product enabling recyclable PET closures underline that both scale investments and circular-economy innovation will be decisive themes through 2026.
What the full report contains (practical, executable modules)
- Market model with baseline and two alternate scenarios (conservative, upside) through 2032, including sensitivity analysis to resin price, freight and regulatory shock events.
- Price matrix and cost-to-serve templates enabling direct input of company-specific purchasing terms and logistics profiles to produce tailored margin projections.
- Supplier and competitor scorecards covering product breadth, technical service, capacity, and strategic intent—designed to support partnership selection, JV diligence and M&A screening.
- Regulatory impact mapping that links additive chemistries to country-level compliance windows and reformulation lead times.
- Commercial playbooks for five archetypal go-to-market strategies: export-led scaling, regional hubbing, vertical integration, premium technical service, and sustainability-first product lines.
- Investment cases with NPV and payback calculations for brownfield expansions, greenfield plants and strategic minority investments—plus a list of shortlist targets and red-flags for deal teams.
- A downloadable Excel model and a slide-ready executive summary tailored for board-level decision-making.
How to use these insights to act in 2026
- Prioritize capex that is modular and reversible. Given freight and input-price volatility, modular capacity reduces downside and accelerates break-even in a mid-single-digit growth market.
- Hedge input exposure through blended procurement strategies: secure long-term access to carrier resins while leveraging spot markets for pigments where feasible.
- Invest in product reformulation and validation for compliance-sensitive applications now—regulatory-driven premium demand will outpace commodity segments.
- Build distribution or toll-manufacture agreements in target countries to reduce transport surcharges and tariff exposure while preserving the ability to serve national champions.
- Pursue partnerships with local specialists for rapid customer onboarding; use M&A selectively to acquire proprietary additive chemistries or to scale quickly in priority sub-markets.
- Embed circularity into the product roadmap—solutions that enable recyclability or closed-loop collection are becoming procurement filters among large brand owners.
Executive checklist for 2026
- Have you stress-tested margin performance at ±20% resin price movement and factoring in potential freight surcharges?
- Is your product pipeline compliant with the most restrictive regional additive regulations expected in the next 18–24 months?
- Do you have contingency plans for supplier disruption in pigment and carrier resin sourcing?
- What is your target share of top-tier customers vs. long-tail processors, and does your commercial model support the service expectations of each?
- Are you tracking competitor capacity moves and consolidation signals that could pressure price or create acquisition opportunities?
PW Consulting’s full South East Asia Additive Masterbatch Market report delivers the data, scenario models and tactical playbooks required to make high-confidence commercial, operational and investment decisions in 2026. For the detailed segment breakdowns, company scorecards, downloadable financial models and the complete set of decision-support tools, please consult the full report—designed specifically to move teams from insight to execution within 90 days.
For detailed analysis of this topic, please visit the official page: South East Asia Additive Masterbatch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com