

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LNG Bunker Fuel Market to Reach USD 646.37M by 2032 (28% CAGR)

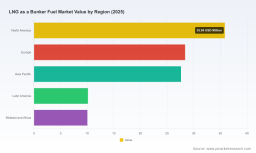
LNG as a Bunker Fuel: Strategic Imperatives for 2026 — PW Consulting Market Preview
Executive snapshot
As the maritime energy transition accelerates, LNG is shifting from a niche compliance strategy to a core element of short- and medium-term fuel planning. PW Consulting’s latest market study, built on a 2025 base and a seven-year forecast through 2032, identifies a market trajectory that requires immediate strategic responses: the market is modelled to expand at an annualized compound growth rate of approximately 28% across 2026–2032, rising from a 2025 baseline to a multi-fold larger market by 2032 (all values expressed in USD, revenue units in Millions). That rapid growth is not academic — it is being driven by convergent forces of regulatory pressure, port-level licensing activity, accelerating fleet adoption and supply-side innovation.
LNG as a Bunker Fuel Market
Historically the sector recorded steady build-out during 2020–2025; starting in 2026 the forecasted growth profile becomes materially steeper, reflecting recent regulatory de-risking and the commissioning of small-scale liquefaction and bunkering assets. These macro dynamics create both an opportunity window for first movers and a hazard for late entrants exposed to stranded-capital risks.
LNG as a Bunker Fuel Market
Why this report matters to decision-makers in 2026
- Clarifies the commercial runway: A 28% CAGR scenario implies compression of time-to-scale — investment and contract timelines that might previously have fit a five-year plan now compress into 18–36 months.
- Aligns capex and offtake strategy with regulatory cadence: Recent policy shifts (including removal of certain STS transfer restrictions and proactive licensing in leading bunkering hubs) change which business models will be viable at scale.
- Distinguishes infrastructure bets from service plays: The economics of shore-based liquefaction, dedicated barges and truck-to-ship models diverge significantly under differing fuel-price and utilization scenarios; the report translates those differences into decision triggers.
- Provides transaction-ready insight: Private-equity and strategic acquirers need valuations and comparable frameworks that reflect market maturation; our study supplies the necessary comparators and negotiation levers.
What PW Consulting’s market study contains — practical, operational deliverables
This is a practitioner’s report designed to be used, not merely read. Highlights include:
LNG as a Bunker Fuel Market
- Demand and supply modelling: A transparent, stress-testable demand model covering 2020–2025 historicals and a granular forecast for 2026–2032, including scenario toggles for fuel prices, carbon policy and alternative-fuel competition.
- Commercial models and contract templates: Playbooks for short- and long-term bunkering contracts, supply guarantees, swing volumes and joint-venture governance structures that reflect real-world negotiation levers.
- Infrastructure economics: Benchmarked capex/opex ranges and utilization thresholds for shore-side liquefaction, small-scale import terminals, bunker barges and truck-to-ship logistics — with sensitivity analyses for gas feedstock pricing.
- Regulatory and permitting matrix: A country- and port-level map of permitting requirements, licensing timelines and recent policy changes that materially affect time-to-market assumptions.
- Operational readiness checklists: Safety, compliance and training templates for shipowners and terminal operators preparing STS operations, bunkering SIMOPS and hybrid fueling operations.
- Competitive and M&A playbook: Profiles and positioning analysis for the leading market participants, acquisition theses, and integration checklists to accelerate value capture.
- Decision support tools: Excel-based models and board-ready slide sets that executives can use to run internal investment approvals and scenario workshops.
Competitive landscape — what incumbents and challengers are doing
The supply side is maturing along two parallel axes: hub-and-spoke terminal development led by integrated players, and nimble, vessel- and truck-based service providers that prioritize rapid coverage. The market concentration is meaningful: the top three firms hold a majority share and the top five approach three-quarters of market throughput by current measures — a structure that favors vertically integrated scale players but leaves space for specialized services and regional champions.
- Seaside LNG (Houston) — An integrated player focused on shoreside liquefaction, storage and Jones Act-compliant bunkering barges. Recent operational milestones include a SIMOPS LNG bunkering of a very large container vessel at a major US port in 2025, demonstrating capability on high-throughput calls and the operational practices required for large-vessel refuelling.
- Titan Clean Fuels (Amsterdam) — A European-origin service provider that combines LNG with biomethane supply options and operates small-scale bunker vessels. Their strategic play mixes fuel decarbonization narratives with the flexibility of smaller, distributed delivery assets.
- Harvey Gulf International Marine (New Orleans) — Operating dedicated LNG bunkering assets at a key Gulf hub, Harvey Gulf’s model emphasizes asset-backed reliability for offshore and coastal fleets, a relevant blueprint for markets prioritizing guaranteed throughput.
- JAX LNG (Jacksonville) — A regional, small-scale liquefaction and truck-to-ship operator whose model highlights speed-to-market and modularity — a template for ports seeking incremental capacity without large terminal commitments.
Across these players the strategic vectors are clear: vertical integration to control value chains, modular small-scale assets to accelerate coverage, and the inclusion of lower-carbon LNG variants (bio-LNG) to broaden the value proposition. The report analyses these vectors and translates them into partnership and investment decision trees.
Market dynamics and regulatory signals to watch
- Licensing and port policy: Some leading ports opened new supplier licensing windows in early 2026 to facilitate sea-based reloading — a strong signal that regulators are actively shaping commercial opportunity and competition.
- Permitting and STS operations: Removal of certain administrative restrictions on ship-to-ship transfers in 2025 materially reduced operational friction for STS models — a change that accelerates adoption where safety regimes are in place.
- Infrastructure density: Industry tracking shows hundreds of ports with LNG bunkering availability and a growing bunker-vessel fleet, yet practical coverage remains uneven. The interplay between port capability and shipping lane economics is central to which deployment models win.
- Fleet adoption: By end-2025 the number of LNG-fueled non-carrier vessels crossed a new threshold, with strong deliveries in 2024 and 2025; fleet mix and retrofit economics remain a cornerstone of demand modelling.
Key risks and scenario considerations
The sector’s upside is matched by concentrated execution risks. PW Consulting’s stress tests focus on:
- Fuel-price shocks and basis differentials that can erode LNG’s near-term differential advantage;
- Competing zero-carbon alternatives — ammonia, hydrogen and advanced biofuels — that may capture premium environmental positioning and policy support;
- Permitting or safety incidents that could trigger more conservative regulatory approaches; and
- Overbuild in specific corridors that produces underutilized assets and margin compression.
Each of these risks is modelled in the study with trigger thresholds and mitigation checklists to help decision-makers choose adaptive strategies.
How to use this intelligence in 2026 — recommended next steps
- Run a 90-day rapid assessment: Use the report’s benchmarking tools to map your portfolio to port readiness and identify 2–3 priority hubs for pilot projects.
- Lock short-term offtake or slot agreements: The report includes contract templates and negotiation playbooks intended to secure first-mover access without overcommitting capital.
- Prioritize modular investments: For ports and terminal operators, small-scale liquefaction and barge assets offer de-risked entry and faster path to utilization; for shipowners, phased retrofit pilots reduce technical and commercial uncertainty.
- Prepare an M&A and partnership roadmap: The consolidation profile and company-level analysis in the study identify target profiles and earn-out structures aligned with the sector’s expected maturation.
Why PW Consulting’s study is uniquely actionable
Unlike purely descriptive industry overviews, this study is an operational toolkit for 2026 decision cycles. It combines a validated growth trajectory with hands-on models, regulatory timelines and competitor playbooks so executives can move from deliberation to deployment. We present both the strategic narratives and the detailed commercial mechanics needed to execute within 6–24 months.
Next step — access the full intelligence
This preview highlights our analytical rigor and the practical value of the study. To preserve the commercial integrity of the underlying segmentation and port-level models we have deliberately withheld the proprietary, granular datasets and company-level financials that inform the report’s forecasts. Clients and subscribers who require the complete dataset — including port-by-port coverage, contractual templates, downloadable financial models and detailed company valuation comparators — can access the full report via PW Consulting’s market portal.
For an executive briefing, a tailored 90-day action plan or to license the full models and datasets, contact PW Consulting’s LNG as a Bunker Fuel practice. The 2026 decision window is narrow; equipping leadership with a robust playbook now will materially affect outcomes over the coming investment cycle.
For detailed analysis of this topic, please visit the official page: LNG as a Bunker Fuel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com