

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 2‑Methyl‑1,3‑Propanediol Market Poised at USD 145 Million in 2025

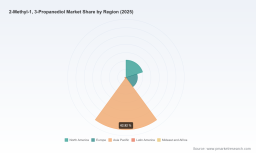
2-Methyl-1,3-Propanediol Market: Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, high-impact perspective on the 2-Methyl-1,3-Propanediol (MPDiol) market geared specifically to inform executive choices in 2026. This short-form brief highlights the structural forces, commercial levers, and competitive dynamics that will determine winners and losers as the market transitions from mid-cycle consolidation to selective growth. It deliberately surfaces the analytical framework and strategic implications while reserving granular segmentation numbers for the full report—your tactical guide to executing with confidence.
2-Methyl-1, 3-Propanediol Market
Executive summary: what this study delivers for near-term strategic decisions
- Validated market trajectory and scenario-ready forecasts anchored on a comprehensive historical baseline (2020–2025), a 2026 decision point, and a forward-looking horizon to 2032.
- A clear assessment of concentration and power: a highly concentrated supplier base governs pricing, availability, and margin capture, creating both barriers and targeted opportunities for market participants.
- Actionable playbooks for commercial, procurement, and investment teams—covering contract structures, capacity strategies, and product & grade prioritization—designed for 12–24 month execution cycles starting in 2026.
- Regulatory and feedstock risk matrices, including recent regulatory developments and their near-term commercial consequences.
Market trajectory and macro view
Our analysis uses 2025 as the base year, with an empirically grounded historical series from 2020–2025 and a forecast window spanning 2026–2032. The MPDiol market has demonstrated steady, low-single-digit growth through the historical period and continues on a moderate upward trajectory into the forecast horizon. The compound annual growth rate (CAGR) applied for the forecast period is 3.0%, reflecting a mature specialty-chemical market where demand gains are driven by performance-led applications rather than commodity volume expansion.
2-Methyl-1, 3-Propanediol Market
Key macro takeaways for 2026 planning:
2-Methyl-1, 3-Propanediol Market
- The market has expanded materially since 2020, and while growth is not exponential, it is reliable—supporting disciplined capacity investments and specialty-mix optimization.
- Near-term upside is linked to engineered-resin demand, coatings performance upgrades, and selected specialty chemical applications; downside is concentrated in cyclical end-markets such as discretionary automotive and capital-intensive construction segments.
Market structure and concentration
MPDiol is supplied predominantly by a small set of global chemical producers with integrated production capabilities and advanced purification technologies. The market exhibits a high degree of concentration among the leading suppliers, a structural feature with important implications:
- Pricing dynamics are supplier-driven: incumbents with scale and integration can defend margins through flexible upstream sourcing and premium-grade product offerings.
- Commercial negotiation power rests with a few large producers, increasing the strategic value of long-term offtake agreements and backward-integration strategies for downstream players.
- High concentration improves predictability of supply in normal cycles but creates single-point risks during plant outages or feedstock disruptions—risk scenarios that demand contingency planning in 2026 procurement playbooks.
Demand dynamics and end-use themes
Demand remains anchored in polyester resin systems—both unsaturated polyester for composites and polyester variants for high-performance coatings—supported by polyurethane applications and specialty plasticizers. The performance attributes of MPDiol (elevated functionality, improved toughness, formulation flexibility) make it attractive where end-product performance commands a premium.
Critical demand-side drivers to monitor in 2026:
- Composite adoption in lightweighting and infrastructure repairs—incremental gains in wind, marine, and selected automotive niches support steady resin demand.
- Coatings and specialty paints—formulation upgrades that emphasize durability and reduced VOCs continue to favor tailored polyester chemistries incorporating MPDiol.
- Shift toward specialty grades and higher-purity streams as formulators extract margin through performance differentiation, increasing the value of purification-capable suppliers.
- Regulatory signals that expand permissible uses or change acceptance in adjacent markets—creating occasional demand spurts that favor nimble suppliers and well-prepared buyers.
Regulatory & feedstock dynamics that will matter in 2026
Two technical-regulatory factors will particularly influence strategy in the near term.
- Regulatory permissibility: Recent exemptions approved by a major regulator in mid-2024 broadened acceptable inert ingredients in certain pesticidal formulations. Such rulings can open adjacent white-space demand for specialty solvents and intermediates, contingent on formulators adapting product specifications. Executives should track approvals and time product qualification processes accordingly.
- Feedstock and process dependencies: Commercial MPDiol production relies on hydroformylation routes converting allyl alcohol (and related intermediates) using carbon monoxide and hydrogen. This creates concentrated feedstock exposure—availability, pricing, and vendor reliability for allyl alcohol and synthesis gas components will directly influence cost curves and spot availability.
Competitive landscape: who matters and why
The market is served by established specialty-chemical companies that combine global supply footprints, technology depth, and customer-facing formulation support. Key participants include long-tenured incumbents and integrated producers with differentiated capabilities:
- LyondellBasell Industries: Offers MPDiol under branded formulations and operates dedicated sites with downstream channel expertise. Its execution strength lies in integrated supply chains and branded customer engagements.
- DuPont de Nemours: Focuses on capacity investments and high-purity grades, aiming at value capture in specialty polyester and engineered applications. Strategy emphasizes quality differentiation and selective capacity growth.
- OXEA GmbH: Utilizes integrated manufacturing and purification know-how to serve quality-sensitive coatings and resin markets across Europe and beyond.
- BASF SE: Positions MPDiol within a broader performance-materials portfolio, enabling cross-selling into adhesives, coatings, and engineered resin systems backed by global application support.
- Dow Inc.: Leverages hydroformylation expertise and broad polymer chemistry capabilities to serve polyester, polyurethane, and personal-care supply chains.
- Perstorp Holding AB: Invests in bio-based process advancements, aligning with sustainability-seeking customers and specialty-coatings applications.
For 2026, the strategic advantage will accrue to players who combine flexible feedstock strategies, grade/purity differentiation, and application support services. New entrants face material technical and commercial barriers; meaningful disruption will likely come from targeted bio-based or purification-led innovations rather than broad-scale commoditization.
Risks, shocks, and scenario planning
Executives must model three interdependent risk vectors when setting 2026 strategies:
- Regulatory shocks—unexpected changes in permissible uses or product stewardship requirements can create short-term surges or sudden demand erosions in certain end-markets.
- Feedstock interruptions—supply-chain constraints for allyl alcohol or synthesis gas can propagate quickly due to limited alternative production routes, amplifying price volatility.
- Concentration-related outages—given the clustered supply base, plant outages at a major supplier can tighten spot markets rapidly; contingency capacity or diversified sourcing agreements are vital mitigants.
What the full PW Consulting report contains (practical tools for 2026)
- Detailed market model (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario toggles for macroeconomic sensitivity, feedstock shocks, and regulatory outcomes.
- Segment and regional demand maps with quantitative splits and growth levers—(note: segmented values are intentionally withheld from this preview and are available in the full report).
- Supplier benchmarking and capability heatmaps, including grade-specific purification capacity, logistics resilience, and innovation pipelines.
- Price-curve and margin simulations tied to feedstock cost inputs (allyl alcohol, CO/H2), plus procurement playbooks for lock-in and flexible-sourcing arrangements.
- M&A and partnership playbook: valuation heuristics, integration risk checklists, and a prioritized list of strategic targets by capability gap.
- Regulatory tracker and impact assessment—mapping recent rulings, such as the mid-2024 inert-ingredient exemptions, to product qualification pathways and addressable market expansion.
How executives should act in 2026
- Prioritize supply resilience: negotiate multi-year offtakes with staggered take-or-pay elements, and identify dual-source strategies for feedstock-sensitive inputs.
- Allocate investment to specialty grades: deploy modest capital to raise purification capability or co-develop high-purity streams with incumbent suppliers to capture formulation-driven margins.
- Embed regulatory intelligence into commercial planning: accelerate qualification timelines for new authorized uses and align technical dossiers to anticipated regulatory shifts.
- Hedge feedstock exposure: where feasible, pursue hedging instruments or backward integration options to stabilize input cost volatility.
- Consider partnership over greenfield: given high concentration and capital intensity, joint ventures or toll-manufacturing agreements can be lower-risk pathways to secure capacity.
In sum, the MPDiol market presents a pragmatic growth story: steady expansion, concentrated supply, and selective pockets of premiumization. For 2026, the imperative is not to chase volume blindly but to orchestrate supply-security, product differentiation, and regulatory readiness. The full PW Consulting study converts these imperatives into executable steps, models, and negotiation playbooks tailored for procurement, commercial, and corporate development teams.
Next steps
PW Consulting’s full report contains the complete datasets, segmented forecasts, and tactical annexes necessary to operationalize the above recommendations. For decision-makers preparing budgets, procurement strategies, product roadmaps, or M&A assessments in 2026, our report is designed as the single-source analytical and tactical companion.
For detailed analysis of this topic, please visit the official page: 2-Methyl-1, 3-Propanediol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com