
Blogs
PW Consulting: TFLN Modulator Market Hits $261M in 2025, 35.53% CAGR to $2.2B by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Photonics Era: Inside the Worldwide Thin Film Lithium Niobate Modulator Market 2026-2032
The global optical communications landscape is undergoing a structural shift. As data center interconnects, telecommunication networks, and emerging quantum applications demand higher bandwidths, lower power consumption, and tighter integration, Thin Film Lithium Niobate (TFLN) modulators have emerged as a cornerstone technology. For enterprise leaders, investors, and technology strategists operating in 2026, understanding the trajectory of this market is no longer optional. It is a prerequisite for capital allocation, supply chain resilience, and product roadmap planning.
PW Consulting's latest Worldwide Thin Film Lithium Niobate Modulator Market study delivers a comprehensive, data-driven foundation for these decisions. Below, we outline the strategic contours of the market, the competitive forces shaping its evolution, and the operational intelligence embedded in the full report.
The Macro Trajectory: A Sector in Hypergrowth
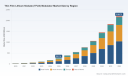
The TFLN modulator market has moved decisively beyond its early adoption phase. Historical data from 2020 through 2025 reveals an acceleration curve that underscores the technology's transition from specialized laboratory demonstrations to production-grade commercial deployment. Beginning at a modest baseline in the early 2020s, the market expanded rapidly as hyperscale data centers, coherent optical networks, and next-generation sensing platforms embraced TFLN's superior electro-optic efficiency, ultra-low half-wave voltage characteristics, and compatibility with scalable photonic integrated circuit architectures.
Looking forward, the forecast period from 2026 to 2032 projects a sustained, high-velocity expansion. The market is expected to grow at a compound annual growth rate of 35.53% over this horizon, reflecting the compounding effect of AI-driven interconnect demand, the rollout of next-generation telecommunication infrastructure, and the nascent but accelerating integration of TFLN devices into quantum and advanced sensing applications. By the close of the forecast window, the total market valuation is projected to reach a level that fundamentally reshapes the competitive landscape for photonic component suppliers and system integrators alike.
This growth trajectory is not merely a function of volume. It reflects a deeper structural realignment: TFLN is becoming the material platform of choice for high-speed, energy-efficient optical modulation across multiple end markets simultaneously. The strategic implication for 2026 decision-makers is clear. Companies that fail to map their product portfolios, supply partnerships, and technology roadmaps against this trajectory risk being left behind as the market compounds.
What the Report Delivers: Actionable Intelligence Beyond Top-Line Numbers
PW Consulting's study is designed for practitioners who require more than aggregate market projections. The report provides a granular, multi-dimensional analysis structured to support strategic planning across several critical dimensions:
Worldwide Thin Film Lithium Niobate (TFLN) Modulator Market
- End-to-end market sizing and forecasting: Detailed revenue projections across the forecast period, anchored in historical performance data from 2020 through the base year of 2025, enable precise demand modeling and investment scenario planning.
- Type-level segmentation analysis: The report dissects the market by modulator architecture, including intensity modulators, phase modulators, and IQ modulators. This breakdown clarifies where performance-differentiated products are capturing value, how application requirements are driving architecture preferences, and where R&D investment is most likely to yield competitive advantage.
- Application-driven demand mapping: Demand is analyzed across data center interconnects, telecommunication networks, aerospace and defense, and quantum and sensing verticals. Understanding the distinct performance thresholds, procurement cycles, and qualification requirements in each segment allows companies to prioritize product development and go-to-market strategies with precision.
- Regional dynamics and competitive positioning: The study maps geographic demand patterns and highlights where manufacturing capacity, design talent, and end-customer concentration are creating localized advantages or bottlenecks. This regional lens is essential for supply chain strategy, partnership evaluation, and market entry timing.
- Competitive landscape profiling: In-depth profiles of leading TFLN modulator developers, photonic foundries, and integrated device manufacturers are included, covering technology roadmaps, product families, foundry capabilities, and recent commercial milestones.
- Industry dynamics and constraint analysis: The report examines standardization progress, manufacturing equipment transitions, wafer supply bottlenecks, and the expanding ecosystem of foundry services, providing a realistic view of where growth may be constrained or accelerated in the near term.
This structure ensures that the report functions as a working document for strategy teams, not merely a reference for market awareness.
Competitive Landscape: Foundries, IDMs, and Technology Differentiation
The TFLN modulator market in 2026 is characterized by a dynamic mix of specialized startups, established photonic foundries, and integrated device manufacturers, many of whom are racing to scale production-grade platforms while locking in design-win pipelines. The competitive field reflects the technology's dual nature: it demands sophisticated materials processing, precision lithography, and packaging expertise, while simultaneously offering differentiation through bandwidth, half-wave voltage, integration density, and wavelength compatibility.
Several organizations have emerged as particularly influential in shaping the market's trajectory:
- HyperLight Corporation (Cambridge, Massachusetts, USA) has rapidly established itself as a leader in production-grade TFLN platforms. The company offers packaged electro-optic modulators spanning amplitude, phase, and IQ configurations, with bandwidth capabilities reaching 145 GHz and ultra-low Vπ specifications. Its TFLN Chiplet™ photonic integrated circuit platform targets IMDD architectures at up to 448 Gbps per lane, as well as DPIQ transmitters for AI and datacom, telecom, and quantum applications. The company supports MPW runs and custom development, and has moved aggressively into high-volume production partnerships.
- Lightium AG (Schlieren, Switzerland) operates a production-grade TFLN photonic foundry delivering 200 mm wafer manufacturing from MPW services through high-volume production. Its platform supports high-speed modulators exceeding 100 GHz with Vπ at or below 1V, and provides PDKs spanning C-band, O-band, and visible wavelengths. This foundry model enables customers to develop next-generation PICs for telecom, datacom, and integrated photonics without owning fab assets.
- Liobate Technologies (Nanjing, China) pursues an IDM approach focused on TFLN photonic devices and high-speed modulators for optical communications. Its portfolio includes TFLN-based chips and sub-assemblies built for mass production of electro-optic modulators and PICs targeting 1.6T and 3.2T applications, aligning closely with the escalating bandwidth requirements of next-generation data center and coherent optical infrastructure.
- Ori-Chip Optoelectronics Technology Co. Ltd. (Ningbo, China) develops and manufactures TFLN MZ modulators and PICs in-house on 4-inch wafers. Its products include folded intensity modulators with ultra-low Vπ below 3.3V and extinction ratios above 20 dB, alongside high-speed chips such as 1.6T DR8 MZ modulators and 4x100G DR4 PICs for high-speed optical communication.
- Quantum Computing Inc. (QCi) (Tempe, Arizona, USA) operates a dedicated TFLN foundry with 150 mm wafer processing for photonic ICs. It fabricates electro-optic modulators and phase modulators with low Vπ-length products tailored to high-baud-rate applications, and provides front-end and back-end capabilities, packaging, and PDK development.
- CCRAFT (CSEM spin-off, Switzerland) has launched what it describes as the world's first production-ready TFLN photonic chip foundry, offering MPW runs, a full PDK, and high-volume manufacturing for electro-optic modulators across telecom, datacom, AI, and quantum applications.
- Additional commercial suppliers including Agiltron Inc., Rofea Optoelectronics, Advanced Fiber Resources, and Neon CQ contribute a broad set of product options across bandwidth classes, modulation types, and application segments, from 20G to 60 GHz intensity and phase modulators, to IQ modulator solutions for OFDM and high-speed systems.
The market concentration among the top players is notable, with the top three firms accounting for approximately 68.5% of market share and the top five reaching 85.2%. This concentration underscores the technology's capital intensity and the advantage that early movers with scalable manufacturing platforms, established PDK ecosystems, and design-win momentum hold. However, it also signals opportunity for well-positioned entrants that can address specific performance niches, wavelength bands, or regional supply chain needs.
Recent Developments Shaping the 2026 Landscape
Recent commercial and ecosystem developments provide a concrete window into how the competitive and manufacturing landscape is evolving in real time:
- In March 2026, HyperLight Corporation introduced 400G-per-lane TFLN PICs on its Chiplet™ platform for AI interconnects, alongside 145 GHz packaged intensity modulators enabling 448 Gbps per lane IMDD and 260 GBaud coherent links. The same month, the company announced a strategic manufacturing partnership with UMC and Wavetek for high-volume production of the TFLN Chiplet platform on 6-inch and 8-inch wafers targeting AI and cloud infrastructure.
- In October 2025, Lightium AG participated in the European-Canadian INGENIOUS consortium, which secured €7.6M to integrate lasers and detectors into next-generation TFLN PICs, signaling the industry's push toward more fully integrated photonic solutions.
- In September 2025, Liobate Technologies showcased its latest TFLN chips and devices, including high-speed modulators, at ECOC 2025, reinforcing its focus on mass-producible solutions for high-throughput optical communications.
- In July 2025, CCRAFt launched a production-ready TFLN photonic chip foundry with MPW runs and a full PDK for scalable electro-optic modulators, expanding the foundry ecosystem and lowering barriers for customers seeking to prototype and scale TFLN-based designs.
These milestones illustrate the convergence of multiple forces: performance breakthroughs, manufacturing partnerships, consortium funding, and the expansion of foundry services. Together, they are compressing the timeline from laboratory demonstration to volume deployment.
Industry Dynamics: Standardization, Manufacturing Shifts, and Supply Constraints
Beyond company-level activity, several macro-level dynamics are influencing how the TFLN modulator market will evolve through the forecast period:
- Standardization toward foundry-compatible platforms: Industry efforts are progressing toward standardized TFLN photonic integrated circuits, including waveguides, modulators, and edge couplers, to support foundry platform compatibility and volume manufacturing. Standardization reduces design risk for customers and strengthens the business case for foundry-based production models, but it also raises the stakes for foundries that must deliver consistent, repeatable performance across multiple customers and designs.
- Manufacturing bottleneck dynamics: Limited commercial manufacturing capacity for high-quality TFLN wafers and specialized cleanroom processes has created supply chain constraints. As of early 2026, only a handful of foundries operate at meaningful scale, which means that even as end-market demand accelerates, the availability of production-grade wafers and processing capacity can become a binding constraint on growth. Companies that secure tightly coupled supply partnerships or invest in captive manufacturing capabilities gain a strategic buffer.
- Lithography transitions enabling yield and performance gains: A shift toward deep-ultraviolet (DUV) stepper lithography on 4-inch TFLN wafers with quartz handles is enabling high-yield volume manufacturing of modulators exceeding 110 GHz with propagation loss below 0.4 dB/cm. This transition is replacing lower-throughput electron-beam lithography for many production applications, reducing per-unit cost and improving consistency. The adoption curve of DUV-based processes will influence which foundries and product lines can scale most efficiently.
- Foundry services ecosystem maturation: Panels and industry discussions at venues such as ECOC 2025 have focused on turnaround times, yield, PDK completeness, and roadmaps to volume production for TFLN foundry services. As these services mature, they lower the barrier to entry for system designers and accelerate the pace of design wins, but they also intensify competition among foundries on quality, support, and scaling capacity.
- Geopolitical and regional capacity developments: In June 2025, China established its first pilot production line for 6-inch TFLN photonic chips at Shanghai Jiao Tong University's CHIPX, supporting domestic ambitions in AI, 6G, and quantum computing. Regional capacity investments of this nature signal a long-term push toward supply chain localization and may reshape competitive dynamics over the forecast period.
For strategists, these dynamics create a dual narrative: the market's growth potential is exceptionally strong, but realizing that potential depends on navigating manufacturing scale-up, supply constraints, standardization timing, and regional capacity investments. The companies that succeed will be those that treat these dynamics not as external noise, but as core inputs to capacity planning, partnership strategy, and technology roadmapping.
Why This Report Matters for 2026 Decision-Making
In a market growing at this pace and shaped by this level of technological and manufacturing complexity, decisions made in 2026 will compound over the entire forecast period. Whether the objective is to evaluate a vendor's scalability, assess a region's supply chain resilience, determine where to prioritize R&D investment, or model demand scenarios for a specific application segment, decision-makers need granular, forward-looking intelligence that goes beyond headline numbers.
PW Consulting's Worldwide Thin Film Lithium Niobate Modulator Market report provides that foundation. It combines rigorous historical analysis with forecast modeling, dissects the market by type, application, and region, maps the competitive landscape molecule by molecule, and embeds the industry dynamics that will determine which players scale and which stall. The report is structured to support board-level strategy discussions, product portfolio reviews, procurement planning, and investment committee evaluations.
Worldwide Phase Electro-optic Modulator Market
The macro trajectory is compelling. The competitive field is actively differentiating. The manufacturing and standardization landscape is evolving quickly. For organizations operating in or adjacent to the TFLN modulator ecosystem, the window for informed strategic positioning is open now.
To access the complete segmentation data, full forecast tables, detailed competitor profiles, and region-specific demand analysis, please visit PW Consulting's official report page. The full study provides the depth required to translate market momentum into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Thin Film Lithium Niobate (TFLN) Modulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Cera Market to Hit $21M by 2032, Driven by 6.01% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Evolving Landscape of Rhus Verniciflua Peel Cera
The global beauty and personal care sector is navigating a period of structural transformation, where ingredient provenance, regulatory alignment, and functional performance converge to redefine formulation strategies. Within this complex ecosystem, Rhus Verniciflua Peel Cera has emerged as a high-value botanical wax, bridging the gap between natural appeasement and sophisticated sensory engineering. As strategic decision-makers prepare for the commercial realities of 2026 and beyond, understanding the trajectory of this specialized market is no longer optional. PW Consulting's latest comprehensive analysis, Worldwide Rhus Verniciflua Peel Cera Market, provides the operational intelligence required to translate macro-trends into actionable enterprise advantage.
Worldwide Rhus Verniciflua Peel Cera Market
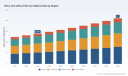
This research does not merely chart historical movement. It engineers a forward-looking decision matrix calibrated for the 2026-2032 forecast horizon. Built upon a rigorous historical foundation spanning 2020 through 2025, the study situates contemporary market behavior within a broader structural context, allowing organizations to stress-test procurement strategies, capacity expansion plans, and innovation roadmaps against verified baseline trajectories. The market has demonstrated consistent expansion, moving from a recorded valuation of 12.45 million USD in 2023 to an estimated 13.96 million USD in 2025. The momentum continues into the early forecast window, positioning the 2026 baseline at 14.8 million USD and projecting a sustained trajectory toward 21.0 million USD by 2032. Driving this progression is a compound annual growth rate of 6.01 percent, a figure that transcends superficial optimism and reflects deep-rooted demand shifts within premium cosmetic architectures.
For executives operating in an environment defined by volatile raw material pricing, tightening sustainability mandates, and increasingly discerning consumer palates, a growth rate of this nature signals more than incremental expansion. It indicates a structural re-rating of botanical wax categories as indispensable functional components rather than peripheral aesthetic additives. The strategic implication is clear: organizations that calibrate their 2026 planning cycles around verified market velocity will secure earlier access to supply chain efficiencies, formulation differentiation opportunities, and regional demand convergence patterns that slower-moving competitors will struggle to replicate.
Market Architecture and Strategic Segmentation Dynamics
The architecture of the Rhus Verniciflua Peel Cera market is defined by a multi-dimensional segmentation framework that directly informs procurement optimization, product development prioritization, and regional expansion sequencing. Our research dissects this architecture across three critical axes: regional distribution, application mapping, and physical form classification. Understanding how value flows through these segments enables formulation directors, sourcing managers, and market entry strategists to allocate capital and technical resources with precision rather than intuition.
The regional dimension reveals a complex interplay of established demand centers and emerging consumption zones. The segmentation data captures the nuanced distribution of market activity across Europe, Asia Pacific, North America, and the Rest of World, reflecting divergent regulatory environments, consumer preference gradients, and supply chain maturity levels. Rather than treating geography as a static backdrop, the analysis maps regional trajectories against procurement feasibility, logistics constraints, and formulation localization requirements. This approach allows organizations to identify where near-term commercial capture is most viable and where long-term positioning will yield compounding returns as regional formulation standards continue to harmonize around natural ingredient compliance.
Application segmentation further illuminates where functional demand is accelerating. The market's value dispersion across core cosmetic categories, including lip care formulations, skin care creams and lotions, stick cosmetics, and other applications, underscores the ingredient's versatility as a structural and sensory enabler. Formulators are increasingly integrating Rhus Verniciflua Peel Cera not merely for its emollient characteristics but for its ability to modulate texture, improve spreadability, and reinforce perceived natural authenticity within finished products. The research provides a detailed functional mapping of these application pathways, equipping R&D teams with the contextual intelligence necessary to align ingredient specification with end-product performance targets.
Form factor distribution adds another layer of operational relevance. The market's segmentation by form, encompassing pellets, flakes, and blocks, directly impacts handling efficiency, dosing precision, and manufacturing integration. Each physical configuration carries distinct implications for production throughput, inventory management, and formulation scalability. By analyzing form preferences through the lens of industrial practicality rather than theoretical categorization, the report enables procurement and operations teams to align material specifications with plant-level capabilities and cost-in-use objectives.
Competitive Field Structure and Strategic Positioning
The supplier landscape for Rhus Verniciflua Peel Cera is characterized by a concentrated yet functionally specialized competitive field. Market concentration metrics indicate that the top three players account for 54.2 percent of total revenue, while the top five firms extend their collective share to 68.45 percent. This structural concentration does not imply a monolithic marketplace. Instead, it reflects a tiered ecosystem where established wax specialists, regional distributors, and application-driven cosmetic brands occupy distinct strategic niches, each competing on technical differentiation, supply reliability, and formulation support rather than price alone.
Leadership in this space requires a clear understanding of how incumbent players are positioning their technical portfolios. Kahl GmbH & Co. KG, operating under the KahlWax brand in Germany, has reinforced its presence by offering KahlWax 6290 Berry, a low-melting soft wax engineered for velvet and powdery skin finishes. Recent documentation updates through August 2025 have emphasized its emollient and conditioning functions within skin care architectures, signaling a deliberate push toward performance-motivated natural wax positioning. In parallel, ROELMI HPC USA, leveraging the ABWAX portfolio through the ROELMI GROUP and Brasca Industrial srl, has maintained visibility through a vegetable-origin wax configured for anhydrous stick systems and personal care smoothness. The December 2025 technical profile update on industry ingredient platforms reaffirmed its melting range and stick-system compatibility, illustrating how documentation precision and technical transparency are becoming competitive differentiators in ingredient procurement decisions.
Complementing these specialized wax suppliers are distribution-focused and brand-integrated participants that shape market accessibility and downstream adoption. Ulrich GmbH operates as a German distribution channel for berry wax supplied in practical industrial packaging, simplifying procurement for cosmetic manufacturers seeking standardized natural wax inputs. Bay House Aromatics, based in the United Kingdom, positions its berry fruit wax around clean-label attributes, emphasizing vegan compliance and Kosher alignment alongside its Chinese Rhus Verniciflua berry peel origin. This profile appeals directly to formulation teams navigating claims substantiation and ingredient integrity requirements. Meanwhile, Olive Tree People, known through its Oliveda brand in Germany, demonstrates the downstream commercial translation of the ingredient by incorporating Rhus Verniciflua Peel Cera into targeted cosmetic products such as concealer serums, blush formulations, and contour systems, where it contributes to texture modulation, emulsification stability, and skin barrier support.
The strategic implication of this competitive mosaic is that procurement and partnership decisions cannot be evaluated on commodity metrics alone. Technical documentation reliability, claim-compatible sourcing narratives, form factor consistency, and application-specific performance data are increasingly decisive factors in supplier selection. Our report maps these competitive postures in detail, allowing organizations to benchmark potential partners against operational criteria that matter in real-world formulation and scale-up environments.
Regulatory Alignment, Sourcing Realities, and Tariff Structuring
The commercial viability of Rhus Verniciflua Peel Cera is inextricably linked to regulatory accessibility and supply chain transparency. Ingredient compliance is no longer a passive checklist item; it is an active architecture that determines market entry speed, formulation flexibility, and multinational scaling potential. Our research integrates a comprehensive regulatory review that situates the ingredient within the operational frameworks governing major cosmetic markets. The analysis confirms alignment with EU Cosmetics Regulation 1223/2009, inclusion in the IECSC inventory for China, and TSCA listing for the United States, with no restrictive designations noted under CLP Regulation as a non-dangerous vegetable substance. This compliance profile reduces regulatory friction and supports formulation teams seeking ingredient architectures that can travel across market jurisdictions without requiring extensive reformulation or claims restructuring.
Sourcing dynamics add an additional layer of strategic complexity. Rhus Verniciflua Peel Cera is derived from the berry fruit peels of the Rhus verniciflua tree through boiling and separation processes, with primary sourcing concentration in China. This geographic concentration intersects with broader themes of supply continuity, extraction consistency, and agricultural supply risk management. For procurement organizations, the operational question is not simply whether the raw material is available, but how sourcing dependencies influence lead time reliability, specification uniformity, and long-term cost predictability. The report addresses these considerations through a structured evaluation of extraction methodology, supply chain structure, and the practical implications of geographically anchored botanical sourcing within a global distribution environment.
Tariff classification represents another frequently underestimated variable in total cost modeling. The assigned tariff code of 15211000 carries direct implications for landed cost calculations, customs clearance efficiency, and regional pricing architecture. Organizations that integrate tariff structuring into their sourcing strategy early can avoid margin erosion that emerges when classification assumptions fail to align with actual clearance procedures. Our research embeds these regulatory and trade dimensions within the broader market narrative, ensuring that strategic recommendations reflect not only demand-side opportunity but also the operational realities that determine whether opportunity can be captured profitably.
Report Structure and the Decision Intelligence It Delivers
The Worldwide Rhus Verniciflua Peel Cera Market study is engineered as a practical decision-support instrument rather than an abstract market summary. Its architecture is designed to move executive teams, formulation leaders, procurement directors, and market development strategists from high-level awareness to executable planning. The report integrates verified market sizing and forecast modeling with segment-specific analysis, competitive participant profiling, regulatory context, and recent industry documentation developments that signal where technical emphasis is shifting.
Worldwide Pellicle Market
Readers will find structured coverage of historical performance baselines, forward-looking forecast trajectories through 2032, and segmentation analysis that clarifies how value distributes across regions, applications, and physical forms. The competitive landscape section delivers participant-level context that supports supplier evaluation, partnership screening, and benchmarking exercises. Recent development records, including technical profile updates and product listing refreshes from late 2025, are incorporated to illustrate how ingredient documentation and platform visibility are evolving in real time. These elements collectively enable organizations to identify where formulation emphasis is trending, which technical attributes are gaining procurement relevance, and how supplier communication strategies may influence selection outcomes.
Equally important, the research is built to support scenario-based planning. Rather than presenting a single deterministic path, the report frames market evolution through multiple lenses, allowing decision-makers to assess how changes in regional demand intensity, application adoption velocity, form preference shifts, or regulatory interpretation may alter commercial outcomes. This flexibility is essential for organizations operating in a market where raw material availability, consumer claim expectations, and formulation performance thresholds are all moving simultaneously.
Translating Market Intelligence into 2026 Strategic Execution
As enterprises enter 2026 planning cycles, the strategic value of this research lies in its ability to convert market movement into structured action. The documented growth trajectory and 6.01 percent compound annual growth rate are not isolated statistics; they are indicators of where formulation investment, supplier relationship development, and regional market prioritization will generate the strongest returns. Organizations that act on this intelligence early can secure advantageous positioning in application categories where natural wax functionality is becoming integral rather than optional, while also optimizing procurement approaches to reflect realistic supply, compliance, and landed cost dynamics.
The report also supports more nuanced competitive strategy. In a concentrated landscape where leading participants compete heavily on technical documentation, application specificity, and claim-compatible sourcing narratives, understanding the differentiation logic of key suppliers allows buyers to negotiate from informed positions and select partners whose capabilities align with product architecture goals. For brands and contract manufacturers seeking to enter or expand within the Rhus Verniciflua Peel Cera value chain, the segmentation and application insights provide a roadmap for identifying the highest-probability pathways to formulation success and market acceptance.
Ultimately, the decision to integrate this research into 2026 strategic planning is a decision to replace ambiguity with evidence. The market is expanding, the competitive field is crystallizing, and the regulatory and sourcing environment is demanding greater precision from ingredient stakeholders. PW Consulting's Worldwide Rhus Verniciflua Peel Cera Market study delivers the analytical depth required to navigate that environment with confidence. The full report provides the detailed segmentation data, regional and application-level breakdowns, supplier-specific evaluations, and forecast modeling necessary to translate market awareness into executable strategy. For decision-makers ready to move beyond surface-level trends and anchor their 2026 plans in verified market intelligence, the complete analysis offers the comprehensive perspective needed to act decisively.
For detailed analysis of this topic, please visit the official page: Worldwide Rhus Verniciflua Peel Cera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Decision Intelligence Market to Reach $59.65 Billion by 2032 at 18.25% CAGR
By pmarketresearch, 2026-09-16
Unlocking Enterprise Value in the Age of Decision Intelligence: PW Consulting's 2026 Market Analysis
The global business landscape in 2026 is defined by a singular imperative: speed, accuracy, and accountability in decision-making. As organizations navigate a complex web of regulatory requirements, volatile market conditions, and an explosion of data assets, the traditional reliance on intuition or siloed analytics is no longer sustainable. Enter Decision Intelligence (DI). This emerging discipline is not merely an extension of business intelligence; it is a rigorous engineering discipline that treats decisions as digital assets, embedding analytics, artificial intelligence, and continuous feedback loops directly into enterprise workflows.
At PW Consulting, we recognize that understanding the trajectory of the Decision Intelligence market is critical for C-suite executives and strategy leaders. Our newly released Worldwide Decision Intelligence Market research offers a comprehensive view of this rapidly evolving sector. This report serves as a strategic compass, guiding organizations through the noise of vendor claims and technological hype to identify where genuine value lies. In this insight piece, we preview the macro trends, competitive forces, and regulatory realities shaping the market, while underscoring the strategic value of deep-dive analysis for 2026 planning.
The Macro Trajectory: From Experimentation to Scale
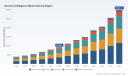
The data tells a compelling story of acceleration. Our analysis tracks market revenue from 2020 through the forecast period ending in 2032, revealing a trajectory that moves beyond early adoption into mainstream enterprise integration. In 2020, the global market was valued at approximately 7,980 million USD. By 2025, that figure had surged to 18,450 million USD, reflecting a significant compound annual growth rate driven by digital transformation initiatives and the maturing of AI capabilities.
Looking forward, the momentum shows no signs of slowing. The market is projected to reach 22,452 million USD in 2026, climbing steadily to exceed 59,649 million USD by 2032. This growth reflects a compound annual growth rate of 18.25 percent across the forecast window. Such expansion signals a fundamental shift in how enterprises allocate technology budgets. Decision Intelligence is transitioning from a niche capability within data science teams to a core infrastructure component supporting operational resilience, risk management, and customer engagement. For strategy leaders, this trajectory implies that waiting to evaluate DI capabilities may result in a competitive disadvantage, as the ecosystem matures and standardization increases.
Market Dynamics: Regulation, Standardization, and the Human Element
The rapid growth of Decision Intelligence does not occur in a vacuum. Several critical dynamics are reshaping the market landscape in 2026, influencing how vendors build platforms and how enterprises deploy them.
Regulatory pressure is a primary catalyst. Frameworks such as the EU AI Act, the OECD Framework for the Classification of AI Systems, and the NIST AI RMF 1.0 mandate human supervision, transparency, and accountability for high-risk automated decisions. These regulations compel organizations to move beyond black-box algorithms toward systems that can explain rationale and audit outcomes. Additionally, ISO/IEC 42001 provides the first international standard for Artificial Intelligence Management Systems, promoting ethical AI development with a focus on fairness, risk management, and accountability. Compliance with these standards is no longer optional for enterprises in regulated industries; it is a prerequisite for deploying DI at scale.
Simultaneously, the definition of Decision Intelligence itself is crystallizing. Gartner defines DI as a practical discipline that advances decision-making by explicitly understanding and engineering how decisions are made. Outcomes are evaluated, managed, and improved via feedback loops, treating decisions as digitized assets. This distinction is vital. Decision intelligence platforms are distinct from agentic AI; they focus on explicit decision modeling, orchestration, and governance rather than fully autonomous agents. Gartner predicts that 75 percent of Global 500 companies will apply decision intelligence practices by 2026. This forecast highlights a shift toward structured, auditable decision processes that augment human judgment rather than replacing it entirely.
Responsible AI governance further emphasizes model explainability, fairness metrics, version control, real-time auditability, and compliance. As InRule and other industry voices note, these elements prevent bias and ensure transparency in high-stakes decisions. For enterprises, this means DI platforms must offer robust governance features to satisfy both internal risk committees and external regulators.
Competitive Landscape: A Fragmented but Maturing Ecosystem
The vendor ecosystem in Decision Intelligence is diverse, spanning established analytics giants, specialized decision management providers, and emerging AI-native platforms. Our report profiles key companies that are defining the boundaries of this market, each bringing distinct strengths to the table.
FICO continues to provide the FICO Platform for managing analytic workflows, decisions, and data integration, deploying models for risk, compliance, and customer engagement. SAS offers SAS Viya and SAS Intelligent Decisioning for unified decision intelligence solutions that automate and deploy rules and models, integrating real-time and batch processing with analytics and machine learning. SAS recently received recognition as a Leader in the inaugural 2026 Gartner Magic Quadrant for Decision Intelligence Platforms, noted for strong financial health, global footprint, and vertical strategies in financial services, healthcare, and manufacturing. IBM supplies decision intelligence capabilities integrated with AI and analytics platforms to support, augment, and automate decision-making processes. ACTICO offers platforms focused on rule-based and AI-enabled decision automation for enterprise use cases.
Software Engineering Intelligence Platform Market
In the realm of specialization, Aera Technology delivers the Aera Decision Cloud, a decision intelligence agent platform that automates and optimizes enterprise decisions in real time using AI for supply chain and finance. Quantexa provides the Quantexa Decision Intelligence Platform using entity resolution, knowledge graphs, and AI to create contextual views for risk, fraud, compliance, and customer intelligence. At QuanCon 2026, Quantexa showcased these capabilities and announced a strategic partnership with Moody's to advance enterprise risk decisioning.
Other notable players include o9 Solutions with its o9 Digital Brain and APEX Model for cross-domain decisions integrated with supply chain planning; Cloverpop, which delivers a platform for structured decision-making, collaboration, and AI insights via the D-Sight engine to reduce bias; Decisions, providing AI-powered platforms for designing, simulating, and operationalizing decisions with process orchestration; and InRule Technology, offering solutions for automating decisions and managing business rules without advanced programming. Rulex provides a platform combining explainable AI, what-if simulators, and optimization in a no-code interface for supply chain, life sciences, and fintech. Sapiens delivers an end-to-end AI-enabled platform for logic extraction, no-code modeling, deployment, and monitoring. Pegasystems integrates decision intelligence with process automation and AI for enterprise decision orchestration. Sparkling Logic offers a cloud-native rules and decision management platform with AI Assistant support, while Taktile provides a platform for building, managing, and optimizing automated decisions with visual modeling and real-time decisioning.
Recent developments underscore the intensity of innovation in this space. In February 2026, EXL was granted 10 new U.S. patents for AI solutions transforming data and enabling AI workflows across insurance, healthcare, retail, utilities, and financial services. EY announced a new patent for decision intelligence supporting hybrid classical-quantum computing models to help enterprises make better decisions in challenging situations. Axonis unveiled a Decision Intelligence offering to create a system of record for AI-driven decisions with role-aware interfaces for operators, analysts, clinicians, case managers, and risk teams. These milestones indicate that intellectual property and platform differentiation are becoming key battlegrounds for market share.
Market concentration data suggests a competitive environment that is accessible yet dynamic. The top three firms hold approximately 22.4 percent of the market, while the top five account for 31.85 percent. This distribution implies that no single vendor dominates the landscape, offering enterprises a range of options to tailor solutions to their specific decision architectures and industry requirements.
Worldwide Decision Intelligence Market
Operational Insights: What Your Organization Needs to Know
To navigate this complex environment, organizations need more than high-level market trends. They require actionable intelligence that bridges the gap between strategy and execution. Our report delivers deep operational content designed to support decision-makers across technology, risk, and business units.
The analysis covers deployment models, examining the shift toward cloud-based infrastructure versus on-premise solutions. Cloud deployments continue to gain traction, driven by scalability, integration capabilities, and the demand for real-time decisioning. However, on-premise solutions remain relevant for sectors with stringent data sovereignty requirements. The report explores how these deployment choices impact total cost of ownership, flexibility, and speed to value.
Component analysis distinguishes between software and services, highlighting where investments are concentrated. Software platforms form the backbone of decision intelligence, enabling rule management, model deployment, and orchestration. Services encompass implementation, consulting, and managed support, which are critical for successful adoption and governance. Understanding the balance between these components helps organizations budget accurately and structure their procurement strategies.
Vertical insights reveal how different industries leverage decision intelligence. BFSI continues to be a major adopter, using DI for risk scoring, fraud detection, and compliance automation. Healthcare applications focus on clinical decision support, resource allocation, and patient engagement. Retail and e-commerce leverage DI for personalization, inventory optimization, and dynamic pricing. Manufacturing utilizes DI for supply chain resilience, predictive maintenance, and quality control. IT and telecom sectors apply DI to network optimization, customer service automation, and churn prediction. Each vertical presents unique regulatory, data, and operational challenges, and our report dissects these nuances to guide industry-specific strategies.
Regional dynamics also play a crucial role. The North American market remains a leader in adoption and innovation, supported by a robust vendor ecosystem and early regulatory frameworks. Europe is characterized by strong regulatory drivers and a focus on ethical AI and compliance. Asia Pacific is emerging as a high-growth region, fueled by digital transformation initiatives and expanding enterprise data capabilities. Latin America and the Middle East and Africa are showing increasing interest as organizations recognize the value of structured decision processes. The report provides context on how regional factors influence vendor selection, deployment models, and implementation timelines.
Strategic Value for 2026 Decision-Makers
Why does this level of detail matter for your 2026 strategy? Because Decision Intelligence is not a plug-and-play technology; it is a strategic capability that requires alignment across people, processes, and technology. Missteps in vendor selection, governance design, or deployment architecture can lead to costly delays, compliance risks, and suboptimal outcomes.
Our report equips leaders to answer critical questions: How do you evaluate vendors against your specific decision use cases? What governance frameworks are necessary to meet evolving regulatory requirements? How do you balance the need for automation with the requirement for human oversight? How do you measure the ROI of decision intelligence investments? By providing granular analysis of market size, growth drivers, competitive positioning, and operational considerations, we enable organizations to make informed choices that reduce risk and accelerate value realization.
The distinction between decision intelligence and broader AI initiatives is particularly important. While generative AI and agentic systems capture headlines, decision intelligence platforms offer the structure, explainability, and auditability required for high-stakes enterprise decisions. Leaders who understand this distinction can allocate resources more effectively, ensuring that automation efforts are grounded in robust decision modeling and continuous improvement loops.
Conclusion: Navigate with Confidence
The Worldwide Decision Intelligence Market is at an inflection point. The convergence of regulatory mandates, technological maturity, and enterprise demand for accountable automation creates a unique window for strategic action. Organizations that invest now in understanding the market landscape, evaluating vendor capabilities, and designing decision architectures aligned with their business goals will be best positioned to thrive.
PW Consulting's full market research goes beyond the insights previewed here. It provides the detailed data, vendor profiles, and scenario analysis necessary to build a resilient decision intelligence strategy. We invite you to access the complete report to unlock the full depth of our analysis. In 2026, the decisions you make about Decision Intelligence will shape the decisions your enterprise can make for years to come. Make them with the confidence that comes from comprehensive, expert-backed intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide Decision Intelligence Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Rotating Gamma System Market to Hit $507M by 2032, Growing at 5.5% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Horizon: Navigating the 2026 Worldwide Rotating Gamma System (RGS) Market
The global landscape for rotating gamma system technology is entering a pivotal phase. As we transition from a historical baseline into a forecast period defined by accelerated adoption and regulatory maturation, the strategic implications for healthcare providers, investors, and industry stakeholders are profound. Our latest Worldwide Rotating Gamma System (RGS) Market research delivers a comprehensive, data-driven blueprint designed specifically to inform high-stakes enterprise decisions throughout 2026 and beyond.
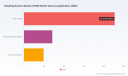
Market evolution over the past half-decade has established a resilient trajectory. Following a historical baseline that tracked consistent annual fluctuations between 2020 and 2025, the sector has demonstrated a clear inflection point. The current market valuation has climbed to approximately USD 348.66 million, reflecting sustained clinical demand and the gradual integration of rotating gamma platforms into both established and emerging treatment protocols. Looking forward, our forecasting models project steady expansion through 2032, with a compound annual growth rate of 5.5 percent. This trajectory points toward a market valuation that will cross the half-billion-dollar threshold by the early 2030s. Such a growth curve is not merely statistical noise; it signals a structural shift in how stereotactic radiosurgery and radiotherapy are conceptualized, procured, and reimbursed across institutional settings.
For strategic decision-makers operating in 2026, understanding this trajectory is the first step toward securing competitive advantage. The research does not simply chart historical performance; it decodes the underlying drivers that will dictate capital allocation, procurement timelines, and partnership strategies over the next seven years. By mapping the convergence of clinical innovation, regulatory clarity, and operational economics, this analysis equips leaders with the foresight required to navigate a rapidly maturing equipment landscape.
Decoding the Report Architecture: Actionable Intelligence Beyond the Surface
A market research publication only delivers value when it translates macro trends into executable strategy. Our Worldwide RGS Market study is engineered for that exact purpose. Rather than offering a superficial survey of equipment types, the report dissects the ecosystem into operational layers that directly impact purchasing cycles, service contracts, and clinical deployment roadmaps. Stakeholders will gain access to granular evaluations of system configurations, maintenance frameworks, and application-specific utilization patterns, all calibrated to reflect real-world procurement and clinical workflow constraints.
Ring Laser Gyroscope (RLG) Market
The analytical framework is structured to answer the questions that hospital administrators, clinical directors, and capital equipment planners actually face. How do rotating gamma platforms compare in terms of source management, rotational delivery mechanics, and long-term service requirements? Which clinical indications are driving sustained utilization, and how do reimbursement pathways align with institutional procurement priorities? What are the operational trade-offs between capital expenditure and lifecycle maintenance when evaluating next-generation rotating architectures? These are the core inquiries that shape the report's methodology.
Each section is built around decision-ready deliverables. Readers will encounter detailed technology benchmarking, lifecycle cost modeling, clinical adoption timelines, and regulatory clearance pathways. The analysis also incorporates procurement friction points, including lead time variability, source replacement logistics, and service-level agreement optimization. By focusing on practical implementation rather than abstract forecasting, the research transforms market data into a strategic playbook for 2026 planning cycles.
Market Dynamics and Operational Realities Shaping 2026
The operational environment for rotating gamma systems is being reshaped by simultaneous forces: technological refinement, regulatory milestones, and reimbursement continuity. A defining characteristic of the current generation of platforms is the reliance on rotating gamma delivery architectures that utilize multiple cobalt-60 sources to generate convergent arcs. This design philosophy offers a compelling alternative to static multi-source configurations, with particular relevance to source replacement complexity and rotational treatment precision. Understanding these technical nuances is essential for procurement teams evaluating total cost of ownership rather than upfront equipment pricing alone.
Regulatory progress has materially reduced market entry friction. Multiple rotating gamma platforms have achieved FDA 510(k) clearance in recent years, with additional clearances extending into Chinese regulatory frameworks. These approvals have normalized the clinical legitimacy of rotating architectures across both intracranial and extracranial applications. At the same time, reimbursement pathways remain relatively stable. Stereotactic radiosurgery procedures utilizing cobalt-60 rotating gamma systems are generally captured under existing CPT codes for intracranial and body SRS/SBRT in hospital settings. This reimbursement continuity means that clinical adoption is increasingly driven by operational fit and treatment workflow integration rather than reimbursement uncertainty.
Clinical implementation momentum is also accelerating. Recent real-world deployments have demonstrated the practical translation of rotating gamma technology into active treatment environments. First-in-region implementations and published retrospective clinical reviews are reinforcing confidence in outcomes across tumor and functional indications. These milestones matter because they convert engineering capability into clinical credibility, which in turn influences procurement prioritization, capital budgeting, and institutional adoption curves.
The competitive environment reflects these dynamics. Market concentration remains high, with a small group of established and emerging manufacturers commanding the majority of revenue share. This concentration shapes pricing expectations, service availability, and long-term partnership structures. For buyers, it means vendor evaluation must extend beyond product specifications to include regulatory standing, service network depth, source lifecycle support, and regional deployment track records. For investors and competitive strategists, it signals that market share gains will likely hinge on regulatory execution, clinical evidence generation, and service ecosystem scalability.
Key manufacturers currently shaping the landscape include American Radiosurgery Inc., which produces cobalt-60 based radiosurgery platforms designed for noninvasive treatment across head, neck, spine, and body indications; Akesis Inc., which offers rotating gamma systems utilizing continuous rotational technology and multiple cobalt-60 sources for stereotactic radiosurgery and radiotherapy; MASEP Medical Science & Technology Development Co. Ltd., which manufactures rotating gamma ray stereotactic systems for intracranial and extracranial applications; and OUR United Corp., which develops image-guided rotating gamma platforms for head and body stereotactic treatments. Each organization represents a distinct strategic positioning within the broader ecosystem, and the research evaluates their product architectures, clearance pathways, and clinical deployment patterns in a manner that allows decision-makers to map competitive moves to procurement and partnership implications.
Strategic Applications of the Forecast: How 2026 Leaders Can Act
The forecast horizon from 2026 through 2032 is not a passive projection; it is a decision framework. As rotating gamma systems continue to gain clinical and operational traction, the organizations that act early will secure advantages in equipment availability, service contracting, clinical program development, and regional market positioning. The research is designed to help leaders convert forecast intelligence into concrete planning actions.
- Capital planning teams can use the forward-looking valuation trajectory to model procurement timing, budget phasing, and multi-year equipment refresh strategies.
- Clinical operations leaders can align service-expansion roadmaps with application-level utilization patterns, ensuring that technology investments support the indications most relevant to institutional patient volume and referral pathways.
- Vendor evaluation committees can benchmark system architecture, source management, and maintenance models against total lifecycle cost expectations rather than isolated purchase price comparisons.
- Strategy and partnership teams can identify where regulatory clearance momentum and clinical evidence are strengthening the competitive position of specific platforms, enabling more informed negotiation and collaboration decisions.
This is particularly important in a market where equipment selection, service contracts, and source lifecycle planning are tightly interconnected. A rotating gamma platform decision affects clinical throughput, radiation safety logistics, maintenance scheduling, and long-term operational expenditure. The research provides the structural clarity needed to assess those interdependencies without relying on oversimplified assumptions.
Why This Research Matters for 2026 Decision-Making
As the rotating gamma system market matures, the margin for strategic error narrows. Procurement windows are increasingly tied to regulatory readiness, clinical program growth, and capital equipment budgeting cycles that demand defensible forecasting. Leaders who rely on fragmented data points or lagged industry commentary risk misaligning investment timing with the actual pace of adoption and regulatory progression. This research closes that gap by delivering an integrated view of market size dynamics, segmentation behavior, competitive positioning, and operational realities.
The strategic payoff is straightforward: better timing, better vendor qualification, and better alignment between clinical ambition and capital reality. Buyers can avoid overcommitting to architectures that do not match their service needs. Investors can distinguish between genuine adoption momentum and short-term market noise. Healthcare executives can plan program expansion with a clearer view of reimbursement continuity and equipment lifecycle implications. In all cases, the objective is the same: replace speculation with structured intelligence.
Worldwide Rotating Gamma System (RGS) Market
Moving From Insight to Execution
The Worldwide Rotating Gamma System (RGS) Market research is built for leaders who need more than a market snapshot. It is a strategic instrument for mapping procurement decisions, clinical program development, competitive positioning, and long-term capital planning against a market that is expanding steadily and evolving technologically. As the forecast period unfolds, the organizations that succeed will be those that ground their decisions in rigorous analysis rather than assumption. The complete report provides the segmentation depth, competitive profiling, regulatory chronology, and forward forecasts required to make those decisions with confidence.
To access the full intelligence package, including detailed market forecasts, segmentation analysis, competitive benchmarking, and actionable procurement guidance, visit the official source page for this study and secure the complete dataset for your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Rotating Gamma System (RGS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Optical Networking IC Market to Hit $15.7B by 2032, Growing at 13.5% CAGR
By pmarketresearch, 2026-09-16
Navigating the Next Wave: Strategic Imperatives in the Global Optical Networking IC Market
The global communications infrastructure is undergoing a structural transformation driven by the convergence of artificial intelligence workloads, cloud hyperscale expansion, and next-generation telecom architectures. At the core of this shift lies the optical networking integrated circuit market, a critical enabler of high-bandwidth, low-latency, and energy-efficient data transmission. PW Consulting's latest Worldwide Optical Networking IC Market research provides decision-makers with a comprehensive, forward-looking intelligence framework designed to navigate the complexities of a rapidly scaling industry. As enterprises, semiconductor firms, and system integrators chart their paths through 2026 and beyond, understanding the macroeconomic trajectory, technological inflection points, and competitive dynamics of this sector is no longer optional—it is a strategic imperative.
The Macro Trajectory: A Market Accelerating Under Convergent Demand
The optical networking IC sector has evolved from a specialized telecommunications component space into a foundational pillar of global digital infrastructure. Historical data reveals a pronounced acceleration in revenue generation, with the market expanding from approximately $3.42 billion in 2020 to $6.45 billion by 2025. This growth trajectory reflects not merely cyclical demand but a fundamental re-architecture of how data moves across networks. The transition to 800G and 1.6T optical modules, the proliferation of co-packaged optics, and the deployment of silicon photonics platforms are fundamentally reshaping component requirements and supply chain priorities.
Looking ahead, the forecast period spanning 2026 through 2032 projects continued robust expansion, supported by a compound annual growth rate of 13.52 percent. The market is expected to surpass the $15.6 billion threshold by the close of the forecast window, underscoring the sustained capital allocation toward optical interconnect technologies. This growth is not uniformly distributed across applications or product categories; rather, it is heavily weighted toward high-performance computing environments, cloud infrastructure buildouts, and advanced coherent transmission systems. Decision-makers must recognize that this trajectory is deeply intertwined with broader infrastructure economics, including the capital intensity of fiber deployment, the energy constraints of large-scale data centers, and the policy-driven expansion of broadband backbones. These intersecting forces create both tailwinds and constraints that will define procurement strategies, manufacturing investments, and product roadmaps throughout the decade.
2026 Decision-Making: Why This Research Matters Now
Entering 2026, the optical networking IC landscape presents a uniquely complex decision environment. Technology nodes are advancing at a pace that outstrips traditional procurement cycles, while energy efficiency mandates and thermal constraints are forcing architects to reconsider pluggable versus co-packaged approaches. Simultaneously, supply chain resilience, geopolitical considerations, and the consolidation of foundry and packaging capabilities are reshaping competitive positioning. In this context, strategic planning cannot rely on historical benchmarks or fragmented vendor narratives. It requires a unified, data-grounded view of market sizing, segmentation behavior, technology adoption curves, and competitive maneuvering.
This research is engineered to serve as a decision-support instrument for executives, product planners, investors, and procurement leaders. Rather than offering static snapshots, it maps the causal links between architectural shifts, component demand, and revenue flows. It clarifies where growth is structurally anchored, which product categories are emerging as critical bottlenecks or enablers, and how regional deployment patterns influence supply chain strategy. By synthesizing historical performance with forward-looking modeling, the report equips organizations to align capital allocation, partnership strategies, and technology roadmaps with the realities of a market that is scaling faster than legacy planning cycles can accommodate.
Inside the Report: What Decision-Makers Will Gain
The research is structured to deliver actionable intelligence across multiple dimensions of the optical networking IC ecosystem. The analytical framework integrates quantitative market modeling with qualitative technology and competitive assessment, ensuring that readers can translate high-level trends into operational strategy. Key components of the study include:
Comprehensive Market Modeling and Forecast Architecture
The report establishes a rigorous baseline using historical data from 2020 through 2025, then extends the analytical scope across the 2026–2032 forecast horizon. Revenue projections are modeled at the aggregate market level, with segmentation frameworks that dissect demand by product type, application vertical, and geographic region. This layered approach allows readers to understand not only where the market is heading, but how different technology categories and end-use environments contribute to overall growth dynamics. The modeling accounts for architectural transitions, module form-factor evolution, and the shifting economics of high-speed interconnect deployment.
Worldwide Optical Networking IC Market
Product Category and Application Deep Dives
Optical networking ICs encompass a diverse set of functional blocks, each with distinct performance requirements, manufacturing considerations, and demand drivers. The report examines the market position and growth trajectory of core product categories, including digital signal processors, laser drivers, transimpedance amplifiers, and clock and data recovery circuits. Each category is evaluated within the context of system-level architecture, highlighting how advancements in signaling rates, power efficiency, and integration complexity influence adoption patterns. Application-level analysis further maps demand to data center environments, telecommunication networks, and enterprise infrastructure, clarifying how workload characteristics and deployment scales shape procurement behavior.
Competitive Positioning and Strategic Movement Analysis
The report delivers a structured assessment of the companies shaping the optical networking IC landscape. Profiles capture corporate positioning, technology portfolios, recent strategic actions, and the implications of those moves for market structure. The analysis tracks product launches, technology acquisitions, interoperability initiatives, and architectural demonstrations that signal shifting competitive priorities. By mapping these activities against broader market trends, the research helps readers identify which players are extending leadership in high-performance DSP and coherent platforms, which are expanding silicon photonics and co-packaged optics capabilities, and how industry consortia and standards bodies are influencing multi-vendor compatibility.
Infrastructure, Energy, and Policy Contextualization
Optical networking IC demand does not exist in isolation. The report embeds component-level analysis within the broader context of infrastructure economics, energy consumption patterns, and policy-driven deployment programs. This contextual layer clarifies how capital intensity in fiber deployment, electricity constraints in large-scale computing facilities, and public investment in broadband expansion influence the pace and geography of optical interconnect adoption. Understanding these external drivers is essential for forecasting demand resilience, evaluating regional opportunity sets, and anticipating regulatory or sustainability-related shifts in procurement criteria.
Competitive Dynamics and the Shape of Market Leadership
The optical networking IC market is characterized by a concentrated yet highly active competitive environment. Incumbent semiconductor and optoelectronic firms are racing to advance process nodes, integrate coherent and PAM4 DSP capabilities, and scale silicon photonics platforms to meet the demands of AI-scale data centers and high-capacity telecom networks. System vendors and vertically integrated players are simultaneously strengthening their control over optical engines, transceiver architectures, and packaging technologies. This dynamic has produced a landscape where leadership is increasingly defined by the ability to deliver low-power, high-density, and interoperable solutions across multiple module form factors and networking architectures.
Recent industry activity illustrates the intensity of this competition. Broadcom has advanced its optical DSP roadmap with the introduction of its 3nm 400G-per-lane PAM-4 DSP, targeting low-power 1.6T pluggable modules for AI-driven networks. Marvell has expanded its technology footprint through the acquisition of plasmonics-based silicon photonics capabilities, positioning itself to scale modulation performance toward 3.2T and beyond. Semtech has demonstrated next-generation 224G-per-lane transimpedance amplifiers and modulator drivers supporting multiple optical architectures for AI data center interconnects. Meanwhile, industry-wide interoperability efforts led by standards organizations have showcased multi-vendor alignment across 800ZR, 400ZR, and emerging 224G/448G electrical and optical interfaces, signaling a concerted push toward energy-efficient, compatible AI cluster networking. These developments, among others, reflect a market where product cadence, technology integration, and ecosystem alignment are becoming decisive competitive differentiators.
The report's competitive analysis goes beyond company profiles to examine how these moves reshape market concentration, influence supply chain dependencies, and alter the balance between integrated solutions and disaggregated component procurement. By mapping strategic actions against market structure, the research helps readers anticipate where consolidation may accelerate, which technology stacks are likely to dominate specific application segments, and how new entrants or acquisitions could shift bargaining dynamics among suppliers and system integrators.
Strategic Takeaways for 2026 and Beyond
As organizations enter 2026, several strategic imperatives emerge from the market's structural evolution. First, technology roadmapping must account for the rapid migration toward higher-per-lane data rates and the parallel push for power reduction through architectural innovation. Decision-makers should evaluate how pluggable, linear pluggable, and co-packaged optics approaches align with their performance, thermal, and cost constraints. Second, supply chain strategy requires a clear view of where advanced DSP, silicon photonics, and high-speed analog integration are concentrating, as well as how packaging and testing capabilities influence time-to-market. Third, investment and partnership decisions should be informed by a nuanced understanding of application-led demand, recognizing that data center buildouts, telecom network upgrades, and enterprise infrastructure modernization are progressing at different speeds and under different economic conditions.
Optical Transceivers Market
The research also underscores the importance of monitoring interoperability and standards alignment. As multi-vendor demonstrations and consortium-driven initiatives gain momentum, compatibility across electrical and optical interfaces will increasingly influence procurement flexibility and deployment risk. Organizations that integrate standards awareness into their technology selection and vendor evaluation processes will be better positioned to manage transition costs and avoid premature lock-in to architectures that may face ecosystem headwinds.
Finally, the market's growth trajectory is intertwined with broader infrastructure and energy realities. Capital intensity in fiber deployment, electricity consumption trends in large-scale computing, and public investment in broadband expansion all shape the demand environment for optical networking ICs. Strategic planners should treat these factors not as peripheral context but as integral inputs to forecasting, capacity planning, and regional opportunity assessment.
Conclusion: Turning Market Intelligence into Strategic Advantage
The Worldwide Optical Networking IC Market is entering a phase of sustained, technology-driven expansion. The convergence of AI workload demands, high-capacity interconnect requirements, and architectural innovation is creating a market environment where insight quality directly correlates with strategic agility. PW Consulting's research is designed to provide the depth, structure, and forward-looking clarity needed to navigate that environment with confidence. By integrating market sizing, segmentation behavior, competitive movement, and infrastructure context into a single analytical framework, the report enables leaders to make informed decisions about product direction, partnership strategy, procurement posture, and investment prioritization.
For organizations seeking to understand where value is being created, which technologies are gaining structural advantage, and how competitive dynamics are evolving across the optical networking IC landscape, this research offers a comprehensive foundation for 2026 planning and beyond. The full analysis, including detailed segmentation breakdowns, regional demand patterns, product-type growth trajectories, application-level revenue distributions, and extended competitive profiling, is available through the complete report. Access the full study to equip your team with the intelligence required to act decisively in a market that is scaling rapidly and redefining the boundaries of high-performance optical networking.
For detailed analysis of this topic, please visit the official page: Worldwide Optical Networking IC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Small Flexible OLED Market Hits $40.55B in 2025, Poised to Reach $70.9B by 2032 at 8.31% CAGR
By pmarketresearch, 2026-09-16
Global Small Size Flexible OLED Panel Market: Strategic Intelligence for 2026 Decision-Makers
The small size flexible OLED panel market stands at a critical inflection point in 2026. As consumer electronics manufacturers navigate intensifying competition, evolving form factors, and shifting supply chain dynamics, having access to precise, forward-looking market intelligence is no longer optional; it is a prerequisite for strategic planning. This comprehensive market research report, covering historical performance from 2020 through 2025 and providing detailed forecasts through 2032, offers business leaders the analytical foundation required to make informed capital allocation, product roadmap, and competitive positioning decisions in the year ahead.
The industry has demonstrated remarkable resilience and growth trajectory over the past half-decade. Starting from a baseline of $22,500 million in 2020, the market expanded steadily to reach $40,550 million by 2025, reflecting a compound annual growth rate trajectory that underscores the accelerating adoption of flexible display technologies across multiple device categories. The forecast period extending to 2032 projects continued expansion, with market valuations anticipated to surpass $70,900 million by the end of the forecast horizon. These figures represent more than statistical progression; they signal a structural transformation in how manufacturers approach display technology integration, particularly in smartphone platforms, wearable devices, and emerging automotive applications where form factor flexibility delivers tangible user experience advantages.
For executives operating in this space, the strategic question is no longer whether flexible OLED will continue its growth path, but rather how to position organizations to capture disproportionate value within an increasingly concentrated and technologically demanding marketplace. This report provides the granular analysis necessary to answer that question with confidence.
Worldwide OLED Display for Smartwatch Market
Market Structure and Growth Architecture
Understanding the underlying architecture of this market requires moving beyond aggregate figures to examine the structural forces that will shape competitive outcomes through 2032. The analysis presented in this report dissects market composition across three primary dimensions, each carrying distinct implications for supply chain strategy, investment prioritization, and risk management.
The regional distribution of market activity reveals pronounced geographic concentration patterns that enterprise strategists must account for when evaluating supply chain resilience, manufacturing partnerships, and market entry timing. Similarly, the application segmentation framework illuminates where demand intensity is concentrated and where incremental growth opportunities are likely to emerge as device categories mature at different rates. Material substrate considerations further compound the strategic calculus, as the choice between established plastic polyimide solutions and emerging ultra-thin glass hybrid approaches introduces trade-offs between cost efficiency, mechanical reliability, and end-user durability expectations.
Rather than presenting static snapshots, this research traces how these structural elements interact over time, identifying the inflection points where supply constraints, technology transitions, or demand shifts will create both threats and opportunities for market participants. Readers gain access to scenario-based assessments that model how variations in key variables could alter competitive trajectories, enabling more robust strategic contingency planning.
Competitive Landscape and Strategic Positioning
The competitive dynamics of the small size flexible OLED panel market are characterized by pronounced concentration among a select group of manufacturing leaders, with the top three participants commanding a combined market share exceeding 82 percent and the top five entities consolidating approximately 91.5 percent of total market value. This concentration level has significant implications for both established players and new entrants seeking to navigate procurement relationships, pricing negotiations, and technology licensing arrangements.
Samsung Display continues to anchor its position as the leading global producer of small-to-medium size flexible AMOLED panels, maintaining dominance across smartphone, foldable, and wearable segments through advanced crease reduction technologies and high-volume production line optimization. Samsung Display's ongoing capacity investments, including announced expansion plans for its A4 factory commencing in the second quarter of 2026, signal a strategic commitment to capturing growing foldable smartphone volumes while reinforcing supply reliability for key customers.
LG Display maintains its standing as a major manufacturer focused on flexible OLED panels for smartphones, wearables, and increasingly automotive applications, supplying high-volume flexible panels including to major smartphone OEMs. The company's production architecture and customer relationships position it as a critical node within the broader supply network, particularly as automotive display integration begins incorporating flexible form factor requirements.
The competitive picture extends significantly into China, where multiple manufacturers have built substantial flexible AMOLED production capabilities. BOE Technology Group has emerged as a key producer with multiple Generation 6 flexible lines operating at high shipment volumes, complemented by active development in crease-free display technologies. BOE's recent technological demonstrations, including the Mirror-sense 0-Crease or Glaze Fold foldable OLED technology unveiled at MWC 2026 which reduces crease visibility by over 40 percent, illustrates the pace of innovation occurring among Chinese manufacturers. Additionally, BOE's activation of its first OLED panel prototype in the new Generation 8.6 B16 fab, demonstrating a 14-inch LTPO OLED notebook panel, underscores capacity expansion ambitions that extend beyond small size applications.
Tianma Microelectronics, Visionox, China Star Optoelectronics Technology, Everdisplay Optronics, and Truly Semiconductors each contribute specialized flexible OLED production capabilities targeting smartphones, wearables, and various consumer electronics applications. Their aggregate output and technology development trajectories warrant close monitoring, as Chinese manufacturers continue refining yield performance in Generation 6 and newer fabrication facilities while expanding flexible-dedicated production architectures.
Futaba Corporation represents a distinct competitive presence through its focus on small flexible PMOLED displays primarily serving wearable and consumer applications, highlighting the technology diversity that persists within the broader flexible display ecosystem.
Industry Dynamics Shaping 2026 Outcomes
Several concurrent industry dynamics will materially influence market conditions throughout 2026 and establish the operational context within which strategic decisions must be executed. Pricing environment expectations indicate that average flexible AMOLED prices are anticipated to experience downward pressure during the first half of 2026 due to prevailing market conditions, with stabilization projected for the second half as supply-demand equilibrium recalibrates. Organizations reliant on flexible OLED panel procurement must factor these pricing trajectories into component cost forecasting, margin planning, and product pricing strategies to avoid margin compression from unanticipated input cost fluctuations.
Production volume patterns suggest that flexible smartphone AMOLED shipments will encounter moderated growth rates entering 2026, influenced by broader economic factors affecting consumer electronics demand cycles. This moderation does not signal market contraction but rather a normalization phase following periods of accelerated adoption, requiring manufacturers and brand owners to recalibrate volume expectations and align production schedules with more measured demand projections.
Supply chain geography continues to exert decisive influence, with the Asia Pacific region, particularly South Korea and China, maintaining dominant positions in flexible OLED production and supply chain operations for small size panels. This geographic concentration, driven by the clustering of major fabrication facilities and manufacturing entities, creates both efficiency advantages and concentration risk considerations that procurement organizations and product planners must address through supplier diversification strategies, inventory buffer planning, and geopolitical risk assessments.
Technical standardization efforts around advanced LTPO backplane architectures and polyimide substrate processing remain central to ongoing industry development, with manufacturing focus intensifying around yield improvement initiatives in Generation 6 and newer fabrication facilities. The interplay between process maturity, defect rate reduction, and cost-per-unit economics will increasingly determine which manufacturers achieve sustainable competitive advantage as the market matures toward 2032.
Report Contents and Analytical Framework
This research publication delivers a comprehensive analytical toolkit designed to support multi-functional decision-making across corporate strategy, supply chain management, product development, and investor relations teams. The report structure integrates multiple analytical dimensions to provide both macro-level market orientation and micro-level competitive intelligence.
The historical analysis component traces market evolution from 2020 through 2025, establishing baseline performance patterns and identifying the demand drivers, technology adoption cycles, and supply-side developments that shaped past outcomes. This retrospective foundation enables readers to distinguish between temporary fluctuations and structural shifts, improving the accuracy of forward-looking projections applied to internal planning processes.
The forecast architecture provides detailed projections spanning 2026 through 2032, incorporating scenario modeling that accounts for variations in macroeconomic conditions, technology transition pacing, and competitive response dynamics. These projections are constructed to support capital investment evaluation, capacity planning, and revenue forecasting with sufficient granularity to inform board-level strategic discussions and operational budgeting cycles.
Worldwide Small Size Flexible OLED Panel Market
Competitive profiling extends beyond entity descriptions to examine strategic positioning, production capacity trajectories, technology roadmap alignment, and customer relationship structures across the principal market participants. By mapping the competitive field in operational rather than purely financial terms, the report equips readers to anticipate competitor moves, identify partnership opportunities, and assess vulnerability exposure within their own market positions.
The segmentation analysis framework enables readers to isolate performance characteristics across regional markets, application categories, and substrate technology choices without relying on oversimplified aggregate representations. This structured approach supports targeted strategy development, whether the priority involves optimizing product mix for specific geographic markets, evaluating entry timing for emerging application segments, or assessing the commercial viability of alternative substrate technology pathways.
Strategic Imperatives for 2026 Planning
As organizations prepare their 2026 strategic agendas, several priority actions emerge from the market intelligence synthesized in this research. First, procurement and supply chain leadership teams should evaluate supplier concentration exposure against the backdrop of pronounced market consolidation, developing contingency arrangements that balance cost efficiency with supply security. Second, product planning functions should align roadmap assumptions with realistic demand moderation scenarios for flexible smartphone AMOLED segments while identifying adjacent applications where flexible display integration may deliver differentiated user value propositions. Third, technology investment committees should assess the commercial implications of ongoing substrate technology evolution, weighing the maturity and cost advantages of established plastic polyimide approaches against the performance potential and market differentiation opportunities presented by ultra-thin glass hybrid solutions.
The market data, competitive analysis, and industry dynamic assessment contained within this report collectively provide the evidence base necessary to transform strategic ambiguity into actionable planning clarity. Whether the objective involves sizing market opportunity for new product introduction, evaluating partnership or acquisition targets, benchmarking internal performance against competitive norms, or constructing investor communications grounded in credible market projections, this research delivers the analytical rigor required to support confident decision-making.
The full Worldwide Small Size Flexible OLED Panel Market research publication contains the complete dataset, detailed segmentation breakdowns, company-level competitive assessments, and forward-looking scenario analyses that executive teams need to navigate the 2026 to 2032 market landscape with strategic precision. Access to the complete report enables organizations to move beyond general industry awareness into quantified, opportunity-specific strategic planning that aligns resources with the most promising market pathways.
For detailed analysis of this topic, please visit the official page: Worldwide Small Size Flexible OLED Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 4.78% CAGR for Global Coconut Oil Methyl Esters Market to Reach $1.3 Billion by 2032
By pmarketresearch, 2026-09-16
Global Coconut Oil Methyl Esters Market: Navigating Strategic Growth Through 2032
The worldwide Coconut Oil Methyl Esters Market is undergoing a period of measured expansion driven by shifting regulatory frameworks, evolving end-use demands, and the ongoing transition toward bio-based chemical intermediates. As industries seek to decouple from petrochemical derivatives while maintaining performance standards, methyl esters derived from coconut oil have emerged as a versatile feedstock spanning personal care, industrial cleaning, lubricants, and agro applications. Our latest market intelligence study maps the trajectory from 2020 through the forecast horizon of 2032, delivering a data-backed foundation for capital allocation, supply chain optimization, and competitive positioning.
Palm Methyl Ester Derivatives Market
Strategic decision-makers operating in 2026 face a landscape defined by modest but consistent growth, concentrated supplier dynamics, and heightened sensitivity to raw material pricing. This research briefing outlines the architecture of our analysis and explains how the full report equips corporate teams with the granularity required to navigate volatility, anticipate regulatory shifts, and identify actionable growth corridors within the oleochemical value chain.
Macro Trajectory: From Baseline Recovery to Sustained Expansion
The market has demonstrated steady revenue progression over the historical window. Starting from an estimated 742.15 million USD in 2020, the sector advanced through successive annual increments, reflecting both post-pandemic demand normalization and structural adoption of coconut-derived methyl esters across multiple verticals. By 2023, industry revenue reached approximately 885.02 million USD, and the upward cadence continued into 2024 with 929.19 million USD and 2025 with 945.5 million USD.
The forecast period from 2026 through 2032 indicates a compound annual growth rate of 4.78 percent, translating the sector toward a projected revenue level above 1.3 billion USD by the terminal year. This trajectory is not a simple linear extrapolation; it reflects compounding effects from regulatory mandates in select regions, gradual substitution of conventional solvents and surfactants, and sustained investment in downstream formulation capabilities. The base year of 2025 anchors the model, enabling stakeholders to benchmark current operational performance against forward-looking demand signals and evaluate whether existing capacity pipelines are sized appropriately for the coming cycle.
Importantly, the growth profile is differentiated across product families, application channels, and geographic corridors. While aggregate figures provide a directional compass, the strategic value of this study lies in unpacking the variance beneath the headline numbers—revealing where supply tightness intersects with pricing power, where formulation innovation accelerates adoption, and where policy environments create durable procurement advantages.
Market Segmentation Fundamentals
The worldwide Coconut Oil Methyl Esters Market is structured across three analytical dimensions that collectively determine competitive exposure and commercial opportunity. By product type, the market encompasses distinct methyl ester ranges that serve different solvency, emulsification, and lubricity requirements. The lighter C8-C10 segment and the broader C12-C14 range cater to divergent downstream applications, from high-performance surfactants and cleaning intermediates to emollient carriers and lubricant additives. Understanding the relative weight of these families is essential for assessing margin profiles, feedstock utilization efficiency, and the risk of regulatory or consumer preference shifts.
By application, end-use channels span personal care and cosmetics, detergents and cleaning agents, industrial lubricants and additives, and food alongside agrochemical segments. Each vertical imposes its own specification thresholds, regulatory scrutiny, and procurement cadence. Formulators in personal care, for example, prioritize purity, color, and free fatty acid constraints, while industrial and agro end-users focus on bulk availability, solvency behavior, and compatibility with existing process streams. The interplay between these application demands and the supply side’s fractionation and distillation capabilities shapes both volume distribution and pricing architecture.
Regional distribution further informs procurement strategy, capacity placement, and trade exposure. The study evaluates how local feedstock availability, refining infrastructure, and downstream manufacturing density influence consumption patterns across major economic corridors. For enterprises assessing distribution partnerships, blending facilities, or contract manufacturing arrangements, granular regional insight is indispensable for balancing incremental market access against logistical cost and regulatory compliance overhead.
Competitive Landscape and Strategic Positioning
Concentration within the market remains a defining feature of competitive dynamics. Our analysis indicates a consolidated environment in which a minority of leading participants command a significant share of revenue, while a broader ecosystem of specialized producers and distributors serves niche specification requirements. The reported market concentration metrics underscore the importance of supply relationship durability, technical service capability, and product consistency in securing long-term contracts with formulators and industrial buyers.
Several established players shape the competitive baseline. Wilmar International Limited operates extensive oleochemical production facilities in Southeast Asia and delivers fractionated methyl ester ranges, including stripped coconut methyl ester variants, through transesterification processes. Its portfolio is positioned across surfactants, lubricants, and intermediate applications, supported by integrated regional manufacturing capacity. Tantuco Enterprises, Inc. maintains a vertically integrated model anchored in the Philippines, with a coconut methyl ester operation linked to its oleochemical division and RBD coconut oil and glycerine lines, supported by substantial annual production capacity and direct copra sourcing. Stepan Company provides coconut-derived methyl ester series, including methyl laurate and related solvent and intermediate products, addressing surfactant, cleaner, and agricultural formulation needs.
Oleon NV contributes methyl ester offerings for oleochemical applications such as emollients and surfactants in personal care and industrial segments, reinforcing the European and global supply network for specialized specifications. Covalent Chemical distributes methyl cocoate as a surfactant raw material applicable across skin care, cosmetics, textiles, rubber, plastics, paints, and inks, serving formulators who require consistent quality and technical documentation. Parchem Fine & Specialty Chemicals supplies coconut oil methyl ester globally as an intermediate across agriculture, asphalt, cleaners, coatings, personal care, lubricants, metalworking, and biodiesel adjacencies, with defined specification parameters including free fatty acid limits and color thresholds.
These participants illustrate the spectrum of competitive approaches: large-scale integrated producers, regionally anchored manufacturers, and specification-focused distributors. Our report assesses the relative positioning of each, the implications of their capacity strategies and regional footprints, and the competitive pressure points likely to influence procurement terms, specification availability, and pricing stability over the forecast period.
Regulatory and Raw Material Dynamics Shaping 2026
Decision-making in 2026 must account for an active policy environment and raw material conditions that directly influence feedstock economics. International coconut oil prices, which serve as the primary input for coconut oil methyl ester production, have trended within an elevated band relative to pre-pandemic levels. Annual pricing has generally remained in a range anchored around the low thousands of USD per metric ton, reflecting modest production recovery, persistent demand from food, cosmetic, and bio-based industrial channels, and supply constraints linked to weather impacts. February 2026 pricing signals from key producing regions indicate continued tightness, reinforcing the importance of hedging strategies, contract structuring, and supply diversification for buyers exposed to input cost fluctuation.
On the policy front, regulatory mandates in select markets are actively shaping demand composition. In the Philippines, diesel fuel has maintained a mandatory blend requirement for coconut methyl ester following increases implemented in late 2024, with planned incremental increases to higher blend levels subject to ongoing review due to feedstock cost pressures. This regulatory stance carries broad implications for domestic production viability, copra price support, and the balance between imported alternatives and locally sourced methyl esters.
Recent policy positions underscore this tension. In March 2026, the Philippine Coconut Authority opposed any full suspension of the mandatory biodiesel blend program, advocating instead to preserve the current blend level or revert to a lower threshold rather than allow substitution with imported palm methyl ester. The stated rationale centered on protecting local copra prices, supporting farmers, and safeguarding the viability of domestic CME production facilities. This stance reflects a broader strategic concern: when policy design intersects with feedstock economics, procurement architectures must account not only for cost but also for continuity of supply, domestic content requirements, and potential future blending increments.
For enterprises operating across food, cosmetics, cleaning, lubricants, and agro segments, these dynamics translate into practical considerations. Procurement teams must evaluate the resilience of supply contracts under variable feedstock pricing, assess the likelihood of regulatory adjustments in blend mandates, and determine whether regional sourcing or blended feedstock strategies can mitigate exposure. Our complete study maps these dynamics against end-use demand and competitive capacity, enabling teams to model scenarios rather than react to them.
Actionable Intelligence Inside the Report
This research is designed as a decision-support instrument rather than a static overview. It combines historical tracking, forward modeling, segmentation detail, and competitive assessment into a coherent framework that can be applied across planning functions. The full publication includes:
Worldwide Coconut Oil Methyl Esters Market
- Historical reconstruction and forecast modeling that align baseline performance with projected growth corridors, enabling scenario testing around blend mandates, feedstock pricing, and downstream substitution trends.
- Product-type and application-level analysis that isolates the relative contribution, specification requirements, and procurement characteristics of each segment to inform product portfolio decisions and technical service investments.
- Regional consumption and supply context that connects feedstock availability, refining capacity, and end-user density to procurement footprints and distribution strategies.
- Competitor positioning and capability mapping that evaluates integrated producers, specialty manufacturers, and distributors by production approach, geographic reach, and application coverage, highlighting where differentiation is most durable.
- Regulatory and policy tracking that integrates mandates, blend trajectories, and industry association positions into a practical view of demand risk and supply continuity.
- Strategic recommendations for 2026 and beyond that translate market structure and dynamics into actionable guidance for capacity planning, contracting strategy, specification management, and market entry or expansion decisions.
The report also documents key specification parameters, quality controls, and application compatibility considerations that directly influence supplier selection and formulation adoption. For teams evaluating supplier qualification, contract terms, or technical collaboration, these details reduce uncertainty and accelerate internal decision cycles.
Why This Study Matters for 2026 Strategy
In a market where aggregate growth is steady but underlying conditions are variable, strategic advantage arises from knowing where concentration creates margin resilience, where application demand is expanding fastest, and where policy and feedstock economics may alter procurement economics. The 4.78 percent compound annual growth rate projected across the forecast window signals durability, yet the composition of that growth differs materially by segment and region. Generic market narratives are insufficient for capital planning, vendor selection, or portfolio optimization in this environment.
Our analysis equips leadership teams to answer targeted questions: which product ranges align with high-specification end-use channels and command premium positioning; how regional supply structures influence availability and trade exposure; what capacity strategies are being pursued by leading participants; and how blend mandate trajectories and feedstock pricing may alter the cost base and sourcing options over the next several years. By linking macro direction with segment-level context and competitive intelligence, the study helps organizations prioritize investments where the risk-reward profile is most favorable.
Access the Full Worldwide Coconut Oil Methyl Esters Market Research
The full report extends beyond headline growth figures to deliver detailed segment context, company-level capability assessment, policy tracking, and scenario-ready forecasting that can be integrated into procurement, R&D, and commercial strategy workflows. For organizations preparing for 2026 and the multi-year horizon through 2032, comprehensive intelligence is the difference between reactive positioning and deliberate market strategy.
To obtain the complete dataset, segmentation detail, competitive profiles, and forward-looking strategic guidance, request the full Worldwide Coconut Oil Methyl Esters Market research. The publication is structured to support executive review, operational planning, and supplier evaluation with the specificity required to act confidently in a dynamic oleochemical environment.
For detailed analysis of this topic, please visit the official page: Worldwide Coconut Oil Methyl Esters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Sparkling Water Maker Market to Hit $2.7B by 2032
By pmarketresearch, 2026-09-16
Global Sparkling Water Maker Market 2026–2032: Strategic Intelligence for Decision Makers
The worldwide sparkling water maker market is entering a phase of disciplined expansion, driven by shifting consumer habits, supply chain recalibration, and intensifying product innovation. At PW Consulting, we recognize that sustainable growth in this category requires more than headline revenue figures. It demands a rigorous understanding of how unit economics, channel dynamics, regional maturity, and competitive positioning intersect across the forecast horizon. Our Worldwide Sparkling Water Maker Market research was built to provide exactly that operational clarity.
Worldwide Sparkling Water Maker Market
Between 2020 and 2025, the category moved from post-pandemic normalization into a structurally stronger demand environment. Revenue progressed from approximately USD 1,020.15 million in 2020 to an estimated USD 1,533.95 million in 2025, reflecting a compound trajectory that underscores both household adoption and sustained commercial interest. The forecast window from 2026 through 2032 extends this momentum, projecting revenues to reach USD 1,732.84 million in 2026 and advance toward USD 2,715.31 million by 2032. This growth path corresponds to a forecast-period CAGR of 8.5 percent, a rate that rewards organizations able to align product portfolios, pricing architectures, and distribution strategies with evolving consumer expectations.
For executives planning 2026 budgets, capacity decisions, and channel investments, these aggregate numbers are only the starting point. The strategic value of our analysis lies in translating macro growth into actionablesegmentation, competitive mapping, and risk-aware scenario planning. The following overview outlines the structure, content, and decision utility of the full report, while intentionally leaving the granular regional, application, and channel data for the complete intelligence package.
Report Architecture: From Market Physics to Execution Roadmaps
What the Full Study Delivers
Our research is structured to support cross-functional planning across product, sales, supply chain, and corporate development teams. The report integrates historical performance tracking with forward-looking scenario modeling, ensuring that strategy teams can test assumptions against both demand-side shifts and input-cost realities.
Commercial Soda Water Dispenser Market
The core analytical modules include:
- Historical market sizing and trajectory analysis covering 2020 through 2025, establishing baseline momentum and post-cycle normalization patterns
- Forecast modeling for 2026–2032 with explicit growth drivers, moderation risks, and sensitivity considerations
- Type-level evaluation distinguishing manual sparkling water makers from electric sparkling water makers, with attention to performance trade-offs, consumer preference gradients, and portfolio implications
- Distribution channel assessment spanning online retail, hypermarkets and supermarkets, and specialty stores, including channel-mix dynamics and go-to-market leverage points
- Competitive benchmarking across the leading global and regional players, with emphasis on product architecture, brand positioning, and strategic differentiation
- Regulatory and input-cost context, particularly around beverage-grade carbon dioxide supply, purity standards, and cost volatility exposure
- Consumer habit analysis supporting demand forecasting, messaging strategy, and premiumization pathways
Each section is designed to avoid generic market description and instead surface implications for pricing power, channel selection, model mix, and capacity planning. The report also bridges market-level insights with operational reality, allowing teams to assess where growth is concentrated, where competition is intensifying, and where margin protection requires deliberate structuring.
Growth Dynamics and the 2026 DecisionHorizon
Why the Forecast Period Matters Now
The 2026–2032 window is not simply an extension of recent historical performance. It reflects a market where adoption is broadening beyond early innovators, yet competitive intensity is rising in parallel. Organizations entering this period with static product assortments or fixed channel assumptions risk losing share to players who are recalibrating around design, convenience, versatility, and input-cost resilience.
Several structural forces shape the trajectory:
- Demand normalization in developed markets, where carbonated water has become a recurring household staple rather than an occasional purchase
- Continued expansion in higher-growth regions, where urbanization, retail modernization, and aspirational kitchen appliance spending support incremental adoption
- Product-tier divergence, with premium design-led models competing alongside affordable, utility-focused offerings
- Channel evolution as digital retail infrastructure matures and omnichannel purchase journeys become more relevant to durable home appliances
Our forecast frames these dynamics within a disciplined growth path, but the real decision value lies in understanding which levers matter most in each strategic context. For instance, a manufacturer prioritizing volume may focus on accessible price points and mass retail reach, while a design-led brand may emphasize limited colorways, premium materials, and specialty retail credibility. The report helps leaders identify where their strategic posture aligns with market structure and where it may require adjustment.
Competitive Landscape: Strategic Archetypes and Positioning Pressure
Who Shapes the Market and How
The competitive environment is defined by a mix of scale leaders, design-focused specialists, versatile appliance players, and professional-grade tool manufacturers. Rather than treating competition as a static ranking, our analysis maps companies into strategic archetypes that reveal where differentiation is durable and where commoditization risk is rising.
At the center of the category sits a dominant global leader with broad product lines, strong retail distribution, and ecosystem advantages in flavor compatibility and brand recognition. This scale position supports shelf presence, consumer trust, and cross-selling potential, but it also invites targeted challenges from brands that compete on aesthetics, material quality, or functional flexibility.
Alongside the leader, a set of premium specialists competes through Scandinavian and European design language, stainless steel construction, and emphasis on durability and kitchen aesthetics. These players often target consumers willing to pay for appearance, perceived craftsmanship, and long-term product identity. Their relevance grows in markets where kitchen appliances are treated as lifestyle statements as much as utility devices.
A second competitive cluster focuses on versatility and beverage expansion. Some manufacturers position their systems as capable of carbonating more than plain water, including juices, cocktails, and other liquids. This functional breadth can widen use cases and justify higher price points, but it also introduces complexity in consumer education and usage expectations.
Budget-conscious and high-volume segments are served by affordable offerings that emphasize simplicity, quick bottle systems, and water-focused performance. These models compete on accessibility and ease of adoption, often relying on retail visibility and value messaging to capture first-time purchasers.
The landscape also includes iconic design brands that integrate carbonation into premium kitchen styling, appliance conglomerates extending into beverage carbonation within broader small-appliance portfolios, and niche specialists focused on siphons and professional-grade tools for culinary applications. Together, these players illustrate the category’s breadth: sparkling water makers are no longer a single product story but a spectrum of solutions spanning utility, design, versatility, and professional use.
Our corporate profiles examine each major player’s positioning, product architecture, and market relevance, then connect those profiles to broader strategic questions. Where does each brand win? Which consumer segments are most accessible? What product iterations signal future competition? These are the kinds of questions the full report is built to answer.
Demand Shifts, Input-Cost Realities, and Supply-Chain Implications
Beyond Consumer Adoption
Market growth cannot be understood in isolation from input availability and cost behavior. Beverage-grade carbon dioxide is a core enabler of sparkling water makers, and its supply dynamics directly influence production economics and margin planning. Recent analysis indicates that the U.S. beverage-grade carbon dioxide market was estimated at USD 547.0 million in 2025, with projections reaching USD 780.1 million by 2033. This trajectory signals expanding input demand, but also underscores the importance of sourcing stability.
Equally important is volatility. Beverage-grade CO2 has experienced price volatility exceeding 40 percent annually in recent periods, influenced by feedstock costs from ethanol and fertilizer production cycles. For sparkling water maker manufacturers and brand owners, this level of variability can affect cost structures, replenishment timing, and pricing flexibility. Even when final consumer pricing does not move in lockstep with input costs, internal budgeting and supplier negotiation strategies must anticipate fluctuation.
Regulatory expectations add another layer of complexity. Beverage manufacturers and carbonation system providers prioritize high-purity CO2 that meets FDA and food-safety requirements, with traceability for use in both home and commercial systems. This focus on purity and documentation matters not only for compliance but also for brand assurance, especially as consumers become more attentive to ingredient integrity and product safety.
Broader environmental policy trends also shape the operating environment. Global carbon pricing instruments covered around 28 percent of emissions in 2025, creating potential cost implications across CO2 production and beverage carbonation supply chains. While the direct impact will vary by region and supplier footprint, organizations with internationally exposed operations should consider how carbon-related costs may influence total landed cost and long-term competitiveness.
Consumer Behavior: The Demand Floor and the Premium Ceiling
Why Household Habits Translate into Category Resilience
Consumer adoption is the engine behind sustained category performance. Recent sector analysis indicates that more than 62 percent of urban households in developed markets considered carbonated water a weekly staple as of Q4 2025. This habit formation supports a durable demand base for home sparkling water makers, especially where convenience, cost-per-serving considerations, and flavor customization align with everyday usage.
Importantly, habit strength does not automatically translate into uniform purchasing behavior. Some households prefer low-friction manual systems, while others seek electric convenience. Some prioritize simplicity and price, while others choose premium design or multi-beverage capability. This behavioral diversity is precisely why segment-level evaluation matters: the market reward goes to companies that can match product architecture to the right consumer job-to-be-done, rather than relying on a single universal offering.
For 2026 planning, the implication is clear. Growth is supported by habitual usage, but differentiation is determined by how well brands serve distinct preference clusters. Messaging, packaging, accessory ecosystems, and after-sale support all influence whether a first purchase becomes repeat usage or category churn.
Recent Product Developments: Signals of Competitive Acceleration
What Launches Reveal About Direction
New product activity in this category is not merely cosmetic. It reflects shifting priorities in design, performance, and use-case expansion. In September 2025, MySoda Oy introduced the Ruby 2 All Black premium sparkling water maker, designed to compete with established brands through enhanced aesthetics and performance. This launch underscores the continued importance of premium positioning and material-led differentiation, especially where design credibility can support margin resilience.
In September 2024, SodaStream International Ltd. launched the enso and ART GOLD sparkling water makers alongside new SodaStream Crafted cocktail mixers, expanding home carbonation offerings into flavor and mixology adjacent use cases. Moves like these illustrate how category leaders seek to deepen engagement by broadening the functional and experiential appeal of home carbonation, rather than competing solely on the device itself.
These developments are consistent with a broader pattern: brands are refining aesthetics, expanding model ranges, and exploring adjacent consumption occasions. Our report contextualizes such launches within competitive strategy, helping readers interpret whether new products represent incremental line extensions, defensive positioning, or genuine differentiation.
How to Use This Research for 2026 Planning
From Intelligence to Action
The Worldwide Sparkling Water Maker Market report is designed to support concrete decisions rather than abstract market awareness. Depending on organizational role, the analysis can be applied to:
- Portfolio prioritization, including which product types and feature sets deserve investment in the next planning cycle
- Channel strategy, identifying where distribution effort should be concentrated and how channel mix may evolve
- Competitive response planning, especially as premium design players, versatile appliance brands, and value-oriented manufacturers all advance distinct propositions
- Supply chain and sourcing sensitivity, particularly regarding input volatility and the need for resilience in CO2-dependent categories
- Geographic expansion assessment, using regional maturity and demand structure to inform rollout sequencing without overcommitting to underdeveloped or saturated contexts
- Pricing and value architecture, aligning price tiers with consumer willingness to pay for design, convenience, and versatility
Because the market is projected to grow at an 8.5 percent CAGR across the 2026–2032 forecast period, pacing matters. Organizations that move early with well-targeted product and channel decisions may secure advantageous positions before competitive density increases further. At the same time, indiscriminate expansion can erode margins, especially where input costs fluctuate and regional demand structures differ. The full report provides the segmentation depth and strategic context required to make these trade-offs explicit.
Concentration, Risk, and the Case for Detailed Market Intelligence
Why Aggregation Is Not Enough
Market-level revenue and growth rates are essential, but they do not reveal the distribution of opportunity or the concentration of competitive advantage. The sparkling water maker market reflects a moderately concentrated structure, with the top three players accounting for approximately 68.45 percent of market share and the top five reaching about 76.12 percent. This level of concentration suggests that scale, distribution strength, and brand recognition continue to matter, while also implying that targeted differentiation can still create meaningful footholds for specialist and emerging players.
Concentration also shapes competitive behavior. In a market where leading positions are meaningful but not absolute, incumbents must defend shelf space, consumer attention, and product relevance, while challengers must identify niches where design, versatility, or value can break through. Understanding how these forces interact across segments and channels is central to strategic planning.
The report’s detailed segmentation and company-level analysis is intended to make these dynamics legible. By separating regional performance patterns, type-based demand profiles, and channel-specific behavior, the study allows decision makers to assess where concentration is an advantage, where it is a vulnerability, and where it can be disrupted through disciplined positioning.
Conclusion: A Market Ready for Disciplined Strategy
The worldwide sparkling water maker market is moving into a period where growth is supported by habitual demand and broadening product relevance, yet challenged by input volatility, competitive overlap, and the need for targeted differentiation. An 8.5 percent forecast-period CAGR through 2032 signals opportunity, but the real strategic advantage will belong to organizations that can translate that growth into segment-appropriate product strategies, channel choices, and supply-chain resilience.
This article has outlined the strategic architecture of our research and the decision problems it is built to address. To access the complete segmentation detail, competitive profiles, regional and channel-level intelligence, and the full forecast dataset needed for 2026 planning, we invite you to explore the full Worldwide Sparkling Water Maker Market report on the PW Consulting platform.
For detailed analysis of this topic, please visit the official page: Worldwide Sparkling Water Maker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Green Elevators Hit $52.38B in 2025, Eyeing 7.51% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Vertical Transportation Transition: Inside the Worldwide Green Elevator Market 2026-2032
The global building sector stands at a critical inflection point. Decarbonization mandates, tightening energy performance standards, and evolving urban density requirements are rewriting the rules of vertical transportation. No longer treated as a secondary building service, elevators have become a core variable in a structure's overall energy profile. Decision-makers who treat elevator procurement as a static CapEx line item risk misaligning with regulatory trajectories, operational cost curves, and competitive procurement requirements that will define the next half-decade.
Our newly released Worldwide Green Elevator Market research report is engineered to cut through the noise. Built on historical tracking from 2020 through our 2025 base year and calibrated across a forecast horizon extending to 2032, the study provides a structured, forward-looking framework for strategists, procurement leaders, and investors. The following preview outlines the strategic architecture of the report, maps the competitive and regulatory forces reshaping the industry, and demonstrates how the full intelligence suite can be operationalized for 2026 decision cycles.
Why 2026 Is a Pivotal Planning Year
The market has already demonstrated a sustained growth arc. Revenue scaled from approximately $36.45 billion in 2020 to $52.38 billion in 2025, and our baseline trajectory projects expansion to roughly $55.47 billion in 2026, accelerating toward $86.89 billion by 2032. This translates to a compound annual growth rate of 7.51% across the 2026-2032 window, a pace that reflects more than cyclical building activity. It signals a structural reallocation of capital toward energy-optimized vertical transport systems.
Several forces are converging at once. Building owners face mounting pressure to demonstrate measurable energy savings and align with green certification frameworks. Regulatory bodies are tightening performance floors for existing and newly constructed facilities. At the same time, the industrial supply chain is absorbing significant input cost volatility. In 2025, U.S. steel mill product prices climbed roughly 17% amid tariff increases pushing toward 50%, directly influencing construction inputs and manufacturing economics for elevator components. By January 2026, the hot-rolled coil steel index had moved to approximately $947 per ton, reflecting tighter domestic supply and sustained trade policy pressure. These are not peripheral details; they shape margin structures, project timelines, and total cost of ownership calculations that buyers must model carefully.
The strategic implication is clear: organizations that wait for the next procurement cycle to evaluate green elevator portfolios will face compressed decision windows, less flexible supplier negotiations, and elevated exposure to both regulatory compliance risk and cost unpredictability. Mapping the market now creates optionality.
A Market Reshaped by Regulation and Measurement Standards
Policy momentum is actively tilting procurement toward low-energy systems. In Europe, the revised Energy Efficiency Directive sets annual energy savings obligations that rise to 1.9% for the 2028-2030 period, reinforcing the business case for energy-efficient elevators integrated into broader building retrofits. Concurrently, the revised Energy Performance of Buildings Directive requires transposition by May 2026, establishing minimum energy performance standards for non-residential buildings and zero-emission requirements for new buildings beginning in 2030. These frameworks do not merely encourage sustainability; they create compliance timelines that influence specification decisions today.
Complementing regulatory pressure is the maturation of measurement rigor. The EN ISO 25745-1/2/3 standards provide defined methodologies for measuring and classifying lift energy efficiency, and they have been integrated into European and international lift regulations. As these standards gain operational traction, they reduce ambiguity in product comparisons and enable buyers to benchmark systems against verifiable performance criteria rather than marketing claims.
Elevators Market
This regulatory and standardization environment changes the nature of the buying conversation. Specification teams are increasingly expected to justify energy performance using comparable metrics, anticipate future compliance thresholds, and evaluate lifecycle energy costs rather than upfront pricing alone.
Competitive Architecture and the Green Technology Race
The green elevator segment is contested by a concentrated set of globally scaled manufacturers, each pursuing energy efficiency through different technological pathways and commercial positioning. Our report profiles the principal players shaping the current competitive landscape and evaluates how their product strategies intersect with procurement needs across building types and geographies.
Otis Worldwide Corporation continues to emphasize machine-room-less systems paired with regenerative drives and coated-steel belts, highlighting energy reductions relative to geared systems alongside lubrication-free operation designed to support green building certifications. KONE Corporation has advanced EcoSpace MRL platforms and UltraRope high-rise technology with regenerative solutions focused on gearless, low-energy operation, alongside a strategic move to discontinue hydraulic models in favor of sustainability-aligned product lines. Schindler Group markets Power Factor 1 regenerative drives and ECO mode standby systems that reduce consumption and return power to the building grid, reinforcing a broader emphasis on sustainable materials and efficient vertical transportation.
TK Elevator has pursued a digitally native direction through EOX eco-efficient elevators and destination dispatch architectures aimed at improving handling capacity while meeting low-VOC cabin standards. Mitsubishi Electric Corporation supplies energy-efficient systems built around permanent magnet synchronous motors and smart controls targeting meaningful energy reduction for sustainable building applications. Hitachi Ltd. and Fujitec Co., Ltd. continue to expand energy-saving component design and smart-building-aligned solutions for international markets, while Hyundai Elevator Co., Ltd. has developed smart power systems and eco-friendly elevator technologies for commercial and residential projects.
Recent trade activity underscores the pace of product iteration. In November 2025, TK Elevator showcased next-generation solutions at GEE Fiera Milano, including a new home lift cabin developed with Italdesign and its EOX eco-efficient elevator, framing the event around sustainability and urban mobility. In October 2025, multiple manufacturers presented the latest elevator technologies with a strong emphasis on sustainability and energy efficiency at the Vietnam International Lift Expo. These events are more than product launches; they reveal where incumbents are concentrating R&D, which performance claims are gaining visibility, and how regional demand signals are being addressed.
Beyond firm-level profiles, the report situates this competitive field within broader market concentration dynamics. A meaningful share of market revenue is captured by a relatively small group of dominant suppliers, and understanding this concentration is essential for evaluating supplier leverage, technology access, and long-term pricing behavior. Strategic buyers need to know not only who is competing, but how competitive density affects negotiation posture, specification flexibility, and innovation roadmaps.
What the Report Delivers for Operating Teams
The full study is structured to move from macro context to actionable intelligence. It integrates historical performance into a coherent baseline, extends the trajectory across the 2026-2032 forecast period, and provides the analytical scaffolding needed to test assumptions before committing to specifications or investment decisions.
The report covers commercial, residential, industrial, and institutional deployment contexts, tracing how green elevator adoption patterns differ across building functions and project types. It examines product architectures including machine-room-less systems, traction systems, and hydraulic systems, and situates them within energy-performance priorities rather than treating them as generic categories. Regional analysis is used to reveal where demand intensity, regulatory exposure, and procurement behavior diverge, enabling readers to calibrate go-to-market and sourcing strategies by market rather than relying on single global averages.
Equally important, the report connects market structure to procurement reality. By mapping competitive concentration, technology roadmaps, and input-cost pressures alongside regulatory timelines, it supports several practical decision uses:
Worldwide Green Elevator Market
- Portfolio and specification planning aligned with projected energy-efficiency requirements and certification pathways
- Total cost of ownership models that account for regenerative performance, standby consumption, and lifecycle maintenance implications
- Supplier evaluation frameworks that compare technological approaches, energy measurement alignment, and compatibility with regional compliance schedules
- Risk assessment for procurement teams navigating material cost volatility and shifting supply conditions
- Strategic positioning for manufacturers, distributors, and building-service players seeking to align product portfolios with demand signals through 2032
How to Read This Market Without Guesswork
One of the most valuable outcomes of rigorous market research is the ability to separate durable trends from short-term market commentary. In a segment where sustainability rhetoric can outpace verifiable performance, decision-makers benefit from a structured baseline that ties market size, growth trajectory, and competitive behavior to measurable drivers. The Worldwide Green Elevator Market report is designed to provide exactly that orientation.
The study frames green elevator adoption as part of a broader operational transformation: buildings are being evaluated not only on appearance or occupancy capacity, but on energy behavior across systems. Elevators are increasingly expected to contribute to that outcome through regenerative operation, efficient standby management, improved traffic handling, and lower-emission cabin environments. Understanding how these attributes translate into procurement preferences, specification requirements, and compliance readiness is central to building a defensible strategy.
For 2026, this matters because planning cycles are compressing. Organizations must choose equipment, service models, and sourcing approaches while regulatory transposition schedules, certification expectations, and input-cost conditions continue to evolve. A report that integrates historical validation, forward projection, and competitive context gives leadership a clearer basis for timing, prioritization, and negotiation.
Next Steps for Strategy and Procurement Teams
The Worldwide Green Elevator Market research report is intended for teams that need more than directional optimism. It provides a detailed, analytically grounded view of how the market is expanding, where competition is concentrating, what regulatory and cost pressures are reshaping procurement, and how technology strategies are diverging among leading suppliers. By integrating the trajectory from 2020 through the 2025 base year and projecting across 2026-2032, it gives readers a coherent framework for evaluating opportunity, exposure, and execution priorities.
To access the full segmentation analysis, competitive benchmarking, regional demand mapping, and the complete strategic recommendations embedded in the study, request the comprehensive report through our official market research portal. The full edition contains the detailed data architecture, supplier profiles, and scenario-ready forecasts designed to support procurement, product strategy, and investment planning throughout the 2026 decision cycle and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Green Elevator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Laser Direct Structuring Resin Market Hits $824.5M in 2025, 8.21% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Wave of Mobile Connectivity and Miniaturization
Introducing the Worldwide Laser Direct Structuring Grade Resin Market Outlook Through 2032
The convergence of advanced antenna architectures, 3D molded interconnect devices, and high-reliability electronics has elevated laser direct structuring grade resins from a niche material category to a cornerstone of modern design engineering. As manufacturers navigate tighter RF performance requirements, space constraints in consumer devices, and emerging electrification mandates in mobility, selecting the right engineering thermoplastic becomes a strategic lever rather than a passive procurement decision. PW Consulting’s latest Worldwide Laser Direct Structuring Grade Resin Market study provides a decision-grade intelligence framework tailored to executive, R&D, and supply chain leaders navigating the 2026 planning cycle and beyond. This research is designed to translate material-level evolution into enterprise-level advantage, offering a structured view of how LDS-enabled resin formulations are reshaping competitive positioning across electronics, automotive, medical, and industrial ecosystems.
Laser Direct Structuring (LDS) Grade Resin Market
Markets do not move in straight lines, but the structural trajectory of this segment is unmistakable. Based on our 2020 through 2025 historical baseline and the 2026 to 2032 forecast horizon, the global market for LDS grade resins is expanding from approximately 706 million USD in 2023 to a projected 1.43 billion USD by 2032, supported by a forecast CAGR of 8.21 percent. These figures are not merely financial abstractions. They encode a deeper story: accelerating product cycles, progressive substitution of traditional PCB-centric layouts with 3D MID architectures, and broad-based demand for resins that deliver consistent laser activation, reliable plating adhesion, and durable electrical performance. For decision-makers, the strategic question is no longer whether LDS resins matter, but which material pathways, partnerships, and geographic footprints will define margin capture over the next seven years.
Why This Research Matters for 2026 Executive Decision-Making
The 2026 operating environment demands forethought that extends beyond quarterly budgeting. Supply chain regionalization, evolving qualification expectations from equipment manufacturers, and the rapid commercialization of 5G and advanced sensing platforms are compressing the window for informed material selection. Our study is built for leaders who need to reconcile engineering ambition with commercial realism. It provides a structured assessment of how LDS-grade compounds are being reformulated, qualified, and deployed across high-growth applications, helping organizations anticipate demand shifts, identify supplier vulnerabilities, and map technology roadmaps against actual market uptake.
A defining feature of this research is its emphasis on decision utility. Instead of presenting generic market summaries, the report maps the LDS resin landscape to points of operational consequence. We analyze how different resin families perform under laser activation and electroless metallization, what qualification pathways are currently shaping supplier credibility, and how material substitutions ripple through cost structures, processing windows, and design flexibility. The study also contextualizes the competitive field by evaluating the strategic posture of key resin developers and compounders, highlighting who is expanding product lines, securing equipment-maker approvals, and targeting specific application verticals. This approach equips leadership teams with a practical framework for sourcing strategy, innovation investment, and risk-adjusted entry timing.
Structural Foundations of the LDS Resin Landscape
The technical backbone of this market lies in the careful compounding of engineering thermoplastics with specialized additives that enable precise laser activation and subsequent metallization. Material architectures based on PC, PC/ABS, PA and PPA, LCP, as well as higher-performance systems such as PEEK and PPS, are being refined to meet increasingly demanding performance and processing requirements. The result is a segmented market where each material family serves a distinct balance of mechanical strength, thermal resistance, dielectric behavior, and processability. Understanding these trade-offs is essential for organizations evaluating whether to standardize across a narrower resin portfolio or diversify to capture application-specific advantages.
From a commercial perspective, the forecast shows consistent value creation as end-use platforms mature. Consumer electronics and 5G antenna applications continue to anchor strong demand, reflecting the ongoing need for compact, high-performance wireless architectures. Automotive electronics represents another substantial demand node, driven by sensor integration, electronic control expansion, and structure-based interconnect solutions that support lightweighting and design consolidation. Medical device applications contribute a differentiated growth path, where biocompatibility considerations, sterilization tolerance, and precision circuitry requirements shape material selection. Industrial and telecommunications use cases add further breadth, reinforcing the market’s resilience as LDS solutions migrate into broader signal management and interconnect functions.
Worldwide Laser Direct Structuring Grade Resin Market
Our segmentation analysis also clarifies how regional value creation is distributed among manufacturing and demand centers. Asia Pacific remains the dominant commercial axis, reflecting the concentration of electronics assembly, consumer device manufacturing, and a large base of engineering compound activity. Europe and North America sustain strong, specialized demand linked to automotive, medical, and industrial applications, while Rest of World regions contribute incremental but strategically meaningful growth. Rather than presenting narrow split percentages, the report emphasizes the operational implications of this geography: where qualification momentum is accelerating, where supplier coverage is most complete, and where local application ecosystems create differentiated opportunities for material developers and end-product manufacturers alike.
Competitive Posture and Qualification-Driven Differentiation
The LDS resin space is characterized by a concentrated but strategically active competitive landscape. Market leadership is not defined by scale alone; it is increasingly shaped by qualification status, application-specific formulation depth, and the ability to demonstrate repeatable metallization performance on LPKF and equivalent processing platforms. High market concentration underscores the importance of trusted supplier relationships, but it also reveals strategic openings for companies that can combine material performance with clear application engineering support.
RTP Company continues to be a reference point in LDS and molded interconnect device compounds, offering formulations spanning PC/ABS, reinforced PA 6/6, and LCP grades designed for platable laser direct structuring. Teijin’s Panlite family reflects a strong focus on low dielectric behavior and reliable plating deposition for 3D circuitry in MID applications. Ensinger brings a differentiated high-performance angle through TECACOMP PEEK LDS, notable for its qualification status and suitability in demanding environments requiring thermal and chemical resilience. Kingfa’s Vismid LDS series addresses a broad spectrum of flame retardancy and colorability needs, supporting design flexibility for LDS-enabled parts. SABIC contributes LNP THERMOCOMP LDS compounds engineered for 3D-MID activation and metallization in antennas and interconnects. DIC Corporation has expanded the material frontier with its LP-150-LDS PPS grade, targeting automotive sensor applications and broadening the pool of LPKF-approved options. Celanese provides high-performance Vectra LCP grades suited to complex 3D circuitry, while Mitsubishi Engineering-Plastics and LG Chem support LDS-compatible PC and engineering plastic solutions for automotive and electronics platforms.
Recent developments reinforce how quickly qualification and product announcements can reshape commercial expectations. In late 2025, JSP Corporation broadened its offering of LDS resins intended for automotive parts, while Huntsman targeted high-volume manufacturing environments with new LDS resin solutions. More recently, DIC’s LP-150-LDS PPS grade received LPKF approval, an announcement that illustrates how equipment alignment can open access to more demanding automotive sensing applications and diversify material options beyond earlier LCP, PA, and PEEK categories. These moves matter because they signal where supplier attention is being directed and which application requirements are becoming commercially actionable.
Strategic Implications and Sourcing Decision Frameworks
Effective strategy in this market depends on recognizing the interplay between material performance, qualification pathways, and application timing. LDS grades must satisfy stringent processing expectations so that laser activation and electroless metallization deliver dependable 3D circuit formation in MID production. That requirement creates a natural hurdle for new entrants and simultaneously rewards established suppliers that can document performance consistency, provide application support, and align with equipment ecosystem expectations. For procurement and engineering teams, this means supplier selection should incorporate qualification pedigree and metallization reliability, not just unit cost or nominal material properties.
The forecast period also invites portfolio thinking. Organizations can choose to concentrate on high-volume consumer and connectivity applications where speed-to-market and processing efficiency dominate, or pursue higher-value niches in automotive electronics, medical devices, and industrial platforms where reliability, regulatory alignment, and miniaturization justify premium formulations. High-performance options such as LPKF-qualified PEEK and newly approved PPS grades illustrate how performance differentiation can support entry into more demanding segments, but they also require careful alignment with application thermal, chemical, and mechanical requirements. As DIC’s PPS approval shows, material expansion is not just about chemistry; it is about removing barriers to adoption in specific end-use scenarios.
Geography adds another layer of strategy. The concentration of activity in Asia Pacific reflects where demand and manufacturing density intersect, yet European and North American ecosystems remain highly influential in automotive, medical, and industrial qualification pathways. Leaders should therefore approach supply strategy with a dual lens: securing material reliability and technical support in core demand regions while remaining agile enough to respond to regional qualification and sourcing preferences. Pricing, lead times, and regional compounding capacity will increasingly interact with application roadmap decisions, making visibility into regional momentum an essential part of 2026 planning.
What the Study Delivers
This research is structured to give leadership teams a clear, usable picture of where the LDS grade resin market stands and where it is headed. The study details total market sizing and forecast evolution across the 2026 to 2032 period, then translates that trajectory into segmentation insight by region, material type, and application without reducing the analysis to narrow numeric splits. Executives gain context around demand drivers, material substitution patterns, and the role of qualification standards in shaping competitive outcomes. The report also maps the strategies of key companies, recent product and certification developments, and the operational implications of raw material formulation choices across the engineering thermoplastic families that anchor LDS performance.
Beyond descriptive intelligence, the study supports concrete strategic action. It helps evaluate supplier concentration dynamics, assess where differentiation is most achievable, and identify application segments where LDS adoption is likely to accelerate over the forecast horizon. It also clarifies how material performance requirements intersect with processing realities, enabling more informed decisions about molding parameters, plating compatibility, and design-for-MID considerations. For organizations planning 2026 investments, this means less guesswork and more disciplined alignment between material strategy, application roadmap, and supplier selection.
Prepared for Executive Use
The Worldwide Laser Direct Structuring Grade Resin Market study is designed for decision-makers who need more than a market snapshot. It offers a cohesive view of how resin technology, equipment qualification, application cycles, and regional demand patterns converge to shape commercial opportunity. In a market where LPKF alignment, metallization reliability, and application-specific formulation increasingly determine supplier relevance, having a structured intelligence base is not optional; it is a strategic necessity. The full report provides the depth required to translate these dynamics into sourcing plans, innovation priorities, and go-to-market positioning.
For teams preparing 2026 strategies, the core takeaway is straightforward: the LDS resin market is expanding in both value and strategic importance, and the organizations that win will be those that connect material selection to application performance, qualification readiness, and regional opportunity with precision. To access the complete segmentation analysis, company profiles, forecast detail, and decision frameworks, visit the source page for the full PW Consulting market research release.
For detailed analysis of this topic, please visit the official page: Worldwide Laser Direct Structuring Grade Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com