

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Laser Direct Structuring Resin Market Hits $824.5M in 2025, 8.21% CAGR to 2032

Strategic Intelligence for the Next Wave of Mobile Connectivity and Miniaturization
Introducing the Worldwide Laser Direct Structuring Grade Resin Market Outlook Through 2032
The convergence of advanced antenna architectures, 3D molded interconnect devices, and high-reliability electronics has elevated laser direct structuring grade resins from a niche material category to a cornerstone of modern design engineering. As manufacturers navigate tighter RF performance requirements, space constraints in consumer devices, and emerging electrification mandates in mobility, selecting the right engineering thermoplastic becomes a strategic lever rather than a passive procurement decision. PW Consulting’s latest Worldwide Laser Direct Structuring Grade Resin Market study provides a decision-grade intelligence framework tailored to executive, R&D, and supply chain leaders navigating the 2026 planning cycle and beyond. This research is designed to translate material-level evolution into enterprise-level advantage, offering a structured view of how LDS-enabled resin formulations are reshaping competitive positioning across electronics, automotive, medical, and industrial ecosystems.
Laser Direct Structuring (LDS) Grade Resin Market
Markets do not move in straight lines, but the structural trajectory of this segment is unmistakable. Based on our 2020 through 2025 historical baseline and the 2026 to 2032 forecast horizon, the global market for LDS grade resins is expanding from approximately 706 million USD in 2023 to a projected 1.43 billion USD by 2032, supported by a forecast CAGR of 8.21 percent. These figures are not merely financial abstractions. They encode a deeper story: accelerating product cycles, progressive substitution of traditional PCB-centric layouts with 3D MID architectures, and broad-based demand for resins that deliver consistent laser activation, reliable plating adhesion, and durable electrical performance. For decision-makers, the strategic question is no longer whether LDS resins matter, but which material pathways, partnerships, and geographic footprints will define margin capture over the next seven years.
Why This Research Matters for 2026 Executive Decision-Making
The 2026 operating environment demands forethought that extends beyond quarterly budgeting. Supply chain regionalization, evolving qualification expectations from equipment manufacturers, and the rapid commercialization of 5G and advanced sensing platforms are compressing the window for informed material selection. Our study is built for leaders who need to reconcile engineering ambition with commercial realism. It provides a structured assessment of how LDS-grade compounds are being reformulated, qualified, and deployed across high-growth applications, helping organizations anticipate demand shifts, identify supplier vulnerabilities, and map technology roadmaps against actual market uptake.
A defining feature of this research is its emphasis on decision utility. Instead of presenting generic market summaries, the report maps the LDS resin landscape to points of operational consequence. We analyze how different resin families perform under laser activation and electroless metallization, what qualification pathways are currently shaping supplier credibility, and how material substitutions ripple through cost structures, processing windows, and design flexibility. The study also contextualizes the competitive field by evaluating the strategic posture of key resin developers and compounders, highlighting who is expanding product lines, securing equipment-maker approvals, and targeting specific application verticals. This approach equips leadership teams with a practical framework for sourcing strategy, innovation investment, and risk-adjusted entry timing.
Structural Foundations of the LDS Resin Landscape
The technical backbone of this market lies in the careful compounding of engineering thermoplastics with specialized additives that enable precise laser activation and subsequent metallization. Material architectures based on PC, PC/ABS, PA and PPA, LCP, as well as higher-performance systems such as PEEK and PPS, are being refined to meet increasingly demanding performance and processing requirements. The result is a segmented market where each material family serves a distinct balance of mechanical strength, thermal resistance, dielectric behavior, and processability. Understanding these trade-offs is essential for organizations evaluating whether to standardize across a narrower resin portfolio or diversify to capture application-specific advantages.
From a commercial perspective, the forecast shows consistent value creation as end-use platforms mature. Consumer electronics and 5G antenna applications continue to anchor strong demand, reflecting the ongoing need for compact, high-performance wireless architectures. Automotive electronics represents another substantial demand node, driven by sensor integration, electronic control expansion, and structure-based interconnect solutions that support lightweighting and design consolidation. Medical device applications contribute a differentiated growth path, where biocompatibility considerations, sterilization tolerance, and precision circuitry requirements shape material selection. Industrial and telecommunications use cases add further breadth, reinforcing the market’s resilience as LDS solutions migrate into broader signal management and interconnect functions.
Worldwide Laser Direct Structuring Grade Resin Market
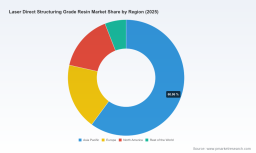
Our segmentation analysis also clarifies how regional value creation is distributed among manufacturing and demand centers. Asia Pacific remains the dominant commercial axis, reflecting the concentration of electronics assembly, consumer device manufacturing, and a large base of engineering compound activity. Europe and North America sustain strong, specialized demand linked to automotive, medical, and industrial applications, while Rest of World regions contribute incremental but strategically meaningful growth. Rather than presenting narrow split percentages, the report emphasizes the operational implications of this geography: where qualification momentum is accelerating, where supplier coverage is most complete, and where local application ecosystems create differentiated opportunities for material developers and end-product manufacturers alike.
Competitive Posture and Qualification-Driven Differentiation
The LDS resin space is characterized by a concentrated but strategically active competitive landscape. Market leadership is not defined by scale alone; it is increasingly shaped by qualification status, application-specific formulation depth, and the ability to demonstrate repeatable metallization performance on LPKF and equivalent processing platforms. High market concentration underscores the importance of trusted supplier relationships, but it also reveals strategic openings for companies that can combine material performance with clear application engineering support.
RTP Company continues to be a reference point in LDS and molded interconnect device compounds, offering formulations spanning PC/ABS, reinforced PA 6/6, and LCP grades designed for platable laser direct structuring. Teijin’s Panlite family reflects a strong focus on low dielectric behavior and reliable plating deposition for 3D circuitry in MID applications. Ensinger brings a differentiated high-performance angle through TECACOMP PEEK LDS, notable for its qualification status and suitability in demanding environments requiring thermal and chemical resilience. Kingfa’s Vismid LDS series addresses a broad spectrum of flame retardancy and colorability needs, supporting design flexibility for LDS-enabled parts. SABIC contributes LNP THERMOCOMP LDS compounds engineered for 3D-MID activation and metallization in antennas and interconnects. DIC Corporation has expanded the material frontier with its LP-150-LDS PPS grade, targeting automotive sensor applications and broadening the pool of LPKF-approved options. Celanese provides high-performance Vectra LCP grades suited to complex 3D circuitry, while Mitsubishi Engineering-Plastics and LG Chem support LDS-compatible PC and engineering plastic solutions for automotive and electronics platforms.
Recent developments reinforce how quickly qualification and product announcements can reshape commercial expectations. In late 2025, JSP Corporation broadened its offering of LDS resins intended for automotive parts, while Huntsman targeted high-volume manufacturing environments with new LDS resin solutions. More recently, DIC’s LP-150-LDS PPS grade received LPKF approval, an announcement that illustrates how equipment alignment can open access to more demanding automotive sensing applications and diversify material options beyond earlier LCP, PA, and PEEK categories. These moves matter because they signal where supplier attention is being directed and which application requirements are becoming commercially actionable.
Strategic Implications and Sourcing Decision Frameworks
Effective strategy in this market depends on recognizing the interplay between material performance, qualification pathways, and application timing. LDS grades must satisfy stringent processing expectations so that laser activation and electroless metallization deliver dependable 3D circuit formation in MID production. That requirement creates a natural hurdle for new entrants and simultaneously rewards established suppliers that can document performance consistency, provide application support, and align with equipment ecosystem expectations. For procurement and engineering teams, this means supplier selection should incorporate qualification pedigree and metallization reliability, not just unit cost or nominal material properties.
The forecast period also invites portfolio thinking. Organizations can choose to concentrate on high-volume consumer and connectivity applications where speed-to-market and processing efficiency dominate, or pursue higher-value niches in automotive electronics, medical devices, and industrial platforms where reliability, regulatory alignment, and miniaturization justify premium formulations. High-performance options such as LPKF-qualified PEEK and newly approved PPS grades illustrate how performance differentiation can support entry into more demanding segments, but they also require careful alignment with application thermal, chemical, and mechanical requirements. As DIC’s PPS approval shows, material expansion is not just about chemistry; it is about removing barriers to adoption in specific end-use scenarios.
Geography adds another layer of strategy. The concentration of activity in Asia Pacific reflects where demand and manufacturing density intersect, yet European and North American ecosystems remain highly influential in automotive, medical, and industrial qualification pathways. Leaders should therefore approach supply strategy with a dual lens: securing material reliability and technical support in core demand regions while remaining agile enough to respond to regional qualification and sourcing preferences. Pricing, lead times, and regional compounding capacity will increasingly interact with application roadmap decisions, making visibility into regional momentum an essential part of 2026 planning.
What the Study Delivers
This research is structured to give leadership teams a clear, usable picture of where the LDS grade resin market stands and where it is headed. The study details total market sizing and forecast evolution across the 2026 to 2032 period, then translates that trajectory into segmentation insight by region, material type, and application without reducing the analysis to narrow numeric splits. Executives gain context around demand drivers, material substitution patterns, and the role of qualification standards in shaping competitive outcomes. The report also maps the strategies of key companies, recent product and certification developments, and the operational implications of raw material formulation choices across the engineering thermoplastic families that anchor LDS performance.
Beyond descriptive intelligence, the study supports concrete strategic action. It helps evaluate supplier concentration dynamics, assess where differentiation is most achievable, and identify application segments where LDS adoption is likely to accelerate over the forecast horizon. It also clarifies how material performance requirements intersect with processing realities, enabling more informed decisions about molding parameters, plating compatibility, and design-for-MID considerations. For organizations planning 2026 investments, this means less guesswork and more disciplined alignment between material strategy, application roadmap, and supplier selection.
Prepared for Executive Use
The Worldwide Laser Direct Structuring Grade Resin Market study is designed for decision-makers who need more than a market snapshot. It offers a cohesive view of how resin technology, equipment qualification, application cycles, and regional demand patterns converge to shape commercial opportunity. In a market where LPKF alignment, metallization reliability, and application-specific formulation increasingly determine supplier relevance, having a structured intelligence base is not optional; it is a strategic necessity. The full report provides the depth required to translate these dynamics into sourcing plans, innovation priorities, and go-to-market positioning.
For teams preparing 2026 strategies, the core takeaway is straightforward: the LDS resin market is expanding in both value and strategic importance, and the organizations that win will be those that connect material selection to application performance, qualification readiness, and regional opportunity with precision. To access the complete segmentation analysis, company profiles, forecast detail, and decision frameworks, visit the source page for the full PW Consulting market research release.
For detailed analysis of this topic, please visit the official page: Worldwide Laser Direct Structuring Grade Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com