
Blogs
PW Consulting: Global AMC CPU Card Market to Reach $844.22M by 2032 Backed by 8.24% CAGR
By pmarketresearch, 2026-09-17
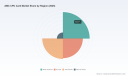
Strategic Intelligence for the Next Decade: Inside the Worldwide AMC CPU Card Market
The embedded computing landscape is undergoing a structural transformation. As industries converge around edge intelligence, 5G infrastructure, and mission-critical reliability, the Advanced Mezzanine Card (AMC) CPU segment has emerged as a critical enabler of next-generation system architectures. For executive teams navigating capital allocation, supply chain resilience, and technology roadmapping in 2026, understanding the trajectory of the Worldwide AMC CPU Card Market is no longer optional. It is a strategic imperative.
This article serves as a strategic preview of our latest market research initiative. It outlines the macro-level dynamics shaping the sector, highlights the competitive forces at play, and demonstrates why data-driven clarity in this space will directly influence enterprise decision-making through the end of the decade. The full intelligence package, complete with granular segmentation, regional revenue breakdowns, and forward-looking scenario modeling, is available through our comprehensive report.
The Macro Trajectory: Growth, Acceleration, and Structural Leverage
The market for AMC CPU cards has demonstrated consistent, compounding expansion over the past five years. Historical revenue data from 2020 through 2025 reveals a clear upward trajectory, with the sector surpassing the half-billion-dollar threshold in the base year and continuing to scale into the forecast horizon. Our analysis projects that this momentum will carry the market steadily toward higher valuation tiers through 2032, driven by entrenched demand in telecommunications, defense, and industrial automation.
The compound annual growth rate across the forecast period stands at a robust 8.24 percent, signaling that AMC-based processing architectures are not experiencing a cyclical spike but rather a structural adoption curve. This rate of expansion reflects the widening integration of MicroTCA and ATCA platforms across high-performance edge deployments, where thermal resilience, I/O flexibility, and processor density intersect. For organizations evaluating capacity planning or vendor partnerships, this macro outlook underscores the importance of aligning procurement strategies with a market that is scaling at a pace faster than general-purpose embedded compute segments.
Revenue projections through the end of the forecast window indicate that the market will continue to compound, with incremental year-over-year gains accelerating as next-generation processor architectures gain mainstream deployment in AMC form factors. The implication for enterprise strategists is clear: early positioning in supply agreements, standards-aligned procurement, and platform diversification will likely yield disproportionate competitive advantages as the market matures.
Architecture and Application: Where Value Is Concentrated
The segmentation landscape of the AMC CPU card market is defined by distinct architecture preferences and application-driven demand clusters. Processor architecture remains a foundational axis of differentiation, with x86-based modules commanding the largest share of market revenue, supported by established ecosystem maturity, extensive software compatibility, and broad availability of high-core-count processors. ARM-based architectures follow, reflecting the growing emphasis on power efficiency, edge AI inference, and specialized telecommunications workloads, while PowerPC architectures maintain a strategic presence in environments where long lifecycle support and deterministic processing remain paramount.
On the application side, demand is heavily weighted toward sectors that require ruggedized, high-availability computing fabric. Telecommunications continues to represent the largest application vertical, driven by the deployment of distributed baseband units, edge packet processing, and MicroTCA-based infrastructure modernization. Aerospace and defense follow as a critical adoption zone, where thermal tolerance, extended temperature operation, and compliance with stringent reliability standards make AMC CPU modules a preferred choice for mission systems and tactical communication platforms. Industrial automation and medical computing round out the demand landscape, with automation leveraging the modularity and backplane scalability of AMC architectures, and medical systems increasingly adopting compact, high-reliability compute nodes for imaging, patient monitoring, and diagnostic edge applications.
Regional distribution further illustrates the global nature of this market, with North America, Europe, and Asia Pacific each contributing substantial revenue streams. The balance across these regions reflects both mature adoption in established industrial and defense markets and accelerating deployment in Asia Pacific as manufacturing and telecom infrastructure investments expand. The global footprint of demand reinforces the need for multi-region supply chain strategies and localized technical support capabilities.
Competitive Landscape: Established Players and Innovation Velocity
The competitive environment in the AMC CPU card market is defined by a concentrated group of specialized manufacturers that have built deep expertise in MicroTCA and ATCA ecosystems. Market concentration metrics indicate that the top three players account for a notable share of total revenue, while the top five collectively represent a substantial majority of market activity. This concentration reflects the high barriers to entry associated with advanced backplane compliance, thermal design, processor integration, and long-term enterprise support commitments.
Kontron AG has maintained a strong position through its AdvancedMC processor modules, including the AM4010 and AM4022 series, which bring Intel Core processor performance, ECC memory support, and high I/O density to telecom, industrial, and defense applications. VadaTech has similarly expanded its Processor AMC portfolio, offering single- and double-width variants based on Intel Core and Xeon architectures, with a clear emphasis on PCIe, Ethernet, and storage flexibility for MicroTCA environments. Recent product activity from VadaTech, including the introduction of 11th Generation Intel Core i7-based modules with quad-core performance up to 4.4 GHz turbo and the continued expansion of its MicroTCA product line, signals an ongoing commitment to performance upgrades and form-factor versatility.
Worldwide AMC CPU Card Market
N.A.T. Europe has carved out a distinct niche through versatile AMC CPU boards that span both ARM-based and COM Express-enabled designs, such as the NAT-AMC-LX2 with 16-core ARM A72 processors and the NAT-AMC-COMex supporting COM Express Type 7 modules with high-bandwidth backplane connectivity. This dual-architecture approach positions the company to serve deployment scenarios that require either power-efficient ARM processing or Intel-based ecosystem compatibility. EMCOMO Solutions AG has pursued a similarly broad strategy, supplying MicroTCA AMC CPU modules built around Intel Xeon E3, Xeon E5, and Xeon D processors, alongside NXP QorIQ and Cavium-based options, with features including NVMe support, 10GbE connectivity, and industrial temperature ranges. Advantech Corp. rounds out the competitive field with embedded computing solutions that include AMC-compatible modules and network mezzanine cards, targeting industrial, telecom, and edge applications with systems that support high-core Intel Xeon processors.
The competitive dynamics in this space are not solely defined by product portfolios. They are increasingly shaped by the speed at which manufacturers can align with updated standards, integrate next-generation processor families, and maintain supply continuity amid broader semiconductor capacity constraints. Organizations evaluating vendor partnerships must therefore assess not just current module availability, but also roadmap alignment, compliance certification depth, and long-term support commitments.
Industry Dynamics and Supply-Side Pressures
The operational environment for AMC CPU card deployment is being reshaped by several intersecting forces. One of the most consequential developments is the ratification of the MicroTCA.0 Revision 3.0 specification, which introduces 100 GbE and PCIe Gen 5 fabrics, delivering a fourfold performance improvement while expanding thermal design power limits to accommodate higher-performance processors. This standards evolution directly enables more aggressive compute deployments within the same AMC form factor, broadening the addressable use cases for edge and server-adjacent applications and supporting up to 12 slots in demanding configurations.
At the same time, supply-side dynamics are introducing new layers of complexity. TSMC expansion has triggered shortages and price surges for certain filter materials used in wafer manufacturing processes critical to advanced semiconductor production, creating upstream constraints that ripple through CPU and component availability. Concurrently, major processor manufacturers are boosting CPU production capacities amid strong demand, yet lead times for certain CPUs have extended to as long as one year, with pricing continuing to escalate. These supply pressures elevate the strategic importance of forward purchasing, alternative architecture evaluation, and multi-sourcing strategies for organizations that depend on AMC CPU modules for critical deployments.
For enterprise decision-makers, these dynamics create a dual challenge: maintaining performance and reliability targets while managing cost volatility and lead-time uncertainty. The ability to anticipate standards-aligned upgrades, secure supply commitments, and evaluate architecture alternatives will differentiate organizations that can sustain deployment timelines from those that face costly delays.
Inside the Research: What Decision-Makers Will Find
Our Worldwide AMC CPU Card Market research is designed to translate these macro dynamics, competitive forces, and supply-side pressures into actionable intelligence. The report provides a structured, data-rich view of the market across multiple analytical dimensions, enabling teams to evaluate growth opportunities, assess competitive positioning, and align procurement and technology strategies with a rapidly evolving landscape.
The research package includes detailed historical and forecast revenue analysis spanning the full 2020 to 2032 window, offering a clear view of how the market has evolved and where it is headed. Segmentation analysis breaks down revenue and growth trajectories across processor architecture families and application verticals, allowing readers to identify which domains are driving expansion and where demand intensity is expected to intensify. Regional breakdowns provide a global perspective on market distribution, supporting supply chain mapping and geographic prioritization.
Beyond quantitative segmentation, the report delivers a competitive landscape assessment that profiles key manufacturers, outlines their product strategies, and contextualizes recent product launches, standard ratification impacts, and supply chain developments. This section is designed to help organizations benchmark vendor offerings, evaluate roadmap alignment, and understand the strategic implications of recent industry events. The research also incorporates an analysis of market concentration dynamics, highlighting how competitive balance, barriers to entry, and standards evolution are shaping the trajectory of the sector.
Motherboard Market
Operational relevance is a core design principle of the report. Rather than presenting abstract market statistics, the analysis is structured to support concrete decision-making processes, including vendor selection, capacity planning, architecture evaluation, and risk assessment in the face of semiconductor supply constraints. The goal is to provide executive and technical teams with a shared, evidence-based foundation for strategic planning.
Why 2026 Is a Pivotal Year for Strategic Positioning
The convergence of standards modernization, processor architecture evolution, and supply-side volatility makes 2026 a defining year for organizations operating in or adjacent to the AMC CPU card market. MicroTCA.0 Revision 3.0 is opening the door to higher-performance deployments within established form factors, while demand from telecommunications, aerospace and defense, industrial automation, and medical computing continues to expand the addressable market. At the same time, lead-time extensions and material-driven cost pressures are testing the resilience of procurement and deployment strategies.
In this environment, strategic clarity is a competitive asset. Organizations that understand the relative growth intensity of different architectures and applications, that can anticipate the implications of standards evolution, and that have visibility into competitive dynamics and supply constraints will be better positioned to make informed decisions about platform investments, vendor relationships, and deployment roadmaps. The market's projected expansion through 2032 reinforces the long-term nature of this opportunity and the importance of getting strategic positioning right early.
This preview provides a high-level view of the forces shaping the Worldwide AMC CPU Card Market and the strategic value embedded in comprehensive market intelligence. The full research report delivers the detailed segmentation, regional revenue distributions, competitive assessments, and forward-looking analysis needed to translate these insights into concrete action. For teams seeking to navigate the market with precision and confidence in 2026 and beyond, the complete intelligence package offers the depth and structure required to support decisive, evidence-based strategy.
For detailed analysis of this topic, please visit the official page: Worldwide AMC CPU Card Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hyperhidrosis Treatment Market Hits $1,815.71M in 2025, Projected to Reach $2,751.86M by 2032 at 6.12% CAGR
By pmarketresearch, 2026-09-17
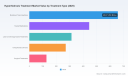
Strategic Foresight for a Growing Dermatology Segment: Inside the Worldwide Hyperhidrosis Treatment Market Intelligence
The hyperhidrosis treatment landscape is entering a decisive phase of commercial maturation. Where excessive sweating was long dismissed as a niche comfort issue, it is now increasingly recognized as a billable clinical condition spanning dermatology, primary care, and aesthetic medicine. Our newest Worldwide Hyperhidrosis Treatment Market research synthesizes seven years of historical tracking with a full forecast arc through 2032, giving executive teams a precision tool for capacity planning, portfolio positioning, and partnership strategy. Below is a structured preview of the analytical depth, competitive mapping, and operational frameworks contained in the full report.
Market Trajectory and the Strategic Signal Behind the Numbers
The global hyperhidrosis treatment market reached approximately 1,815.71 million USD in our 2025 base year, building steadily on a 2020 baseline of 1,350.5 million USD. The trajectory reflects a compound annual growth rate of 6.12 percent across the forecast window, with the market projected to surpass 1,934.5 million USD in 2026 and continue expanding toward 2,751.86 million USD by 2032. This growth is not simply a function of population expansion; it reflects shifting clinical uptake, reimbursement experimentation, and a broadening treatment continuum that now spans botulinum toxin injections, topical formulations, energy-based procedures, iontophoresis devices, and surgical interventions.
For corporate strategists, the most actionable insight is the market's structural acceleration. The forecast period captures a transition from early adoption curves to more normalized prescription pathways and procedural utilization. Companies that treat this segment as a static dermatology niche risk misreading the pace at which patient awareness, physician familiarity, and payer exposure are converging. The full study translates this trajectory into scenario-based planning frameworks, enabling leadership to test how changes in prescription dynamics, procedural pricing, and clinical referrals will reshape addressable demand over multiple planning cycles.
Treatment Continuum: Why Differentiation Is No Longer Optional
Hyperhidrosis care is being redefined by a widening spectrum of modalities, each with distinct clinical positioning, patient adherence profiles, and reimbursement exposure. The breadth of this continuum is one of the central themes of the report. Rather than analyzing treatment types in isolation, the study examines how they compete, complement, and cannibalize one another across different patient segments and clinical settings. This matters because product strategy in this market increasingly depends on understanding substitution effects as much as primary demand.
Overactive Bladder Treatment Market
- Botulinum toxin injections remain anchored by strong clinical recognition and well-established treatment protocols, particularly in axillary indications, but their commercial trajectory is shaped by administration logistics, duration of effect, and payer quantity limits.
- Topical medications are expanding the front door of treatment by offering non-invasive options with improving patient convenience, though their uptake is mediated by step-therapy expectations and real-world persistence patterns.
- Laser and energy-based treatments occupy a distinctive position at the intersection of dermatology and aesthetic service delivery, often facing classification questions that influence reimbursement and patient out-of-pocket economics.
- Iontophoresis devices serve both clinic-administered and home-use pathways, creating a dual distribution logic that rewards device accessibility, patient training, and repeat-use adherence.
- Surgical treatments remain a smaller share of the overall market but are critical for refractory cases, where clinical decision-making, procedural risk, and irreversible outcomes impose highly specialized demand dynamics.
Our segmentation review explains how these categories interact across the patient journey rather than presenting them as static silos. That approach is especially valuable for companies deciding whether to compete within an existing modality, extend into adjacent services, or position hybrid offerings that reduce friction between prescription, procedural, and maintenance phases of care.
Competitive Landscape: Where Growth Meets Defensible Positioning
The hyperhidrosis market features a diverse set of participants, from large biologics and aesthetics players to focused dermatology innovators and device manufacturers. The report profiles the companies shaping commercial velocity in this space, assessing how their pipeline activity, regulatory milestones, and go-to-market models influence competitive intensity. Rather than simply listing incumbents, the study evaluates the strategic logic behind each player's footprint and the implications for market share dynamics.
- AbbVie Inc. (Allergan) maintains a prominent position through its botulinum toxin franchise, supported by the only FDA-approved botulinum toxin specifically indicated for primary axillary hyperhidrosis, giving it a distinctive regulatory and clinical anchor in a high-recognition treatment category.
- Botanix Pharmaceuticals advanced the topical segment with FDA approval of Sofdra in mid-2024, reinforcing the trend toward non-invasive pharmacologic options for younger patient populations and expanding the prescription topical armamentarium.
- Journey Medical Corporation commercializes Qbrexza, building on a topical anticholinergic pathway with continued patent protection extending into the next decade, which carries implications for competitive entry timing and pricing durability.
- Candesant Biomedical pursued a device-based non-invasive approach with FDA clearance for its sweat-control patch, illustrating how targeted thermolysis concepts are being translated into practical, clinic-friendly treatment options.
- Sientra Inc. and miraDry, Inc. represent the energy-based procedural side of the market, where permanent reduction claims, procedural economics, and cosmetic-versus-medical classification create both opportunity and reimbursement complexity.
- Dermadry Laboratories Inc. and RA Fischer Co. anchor the iontophoresis segment, where home-use and clinic-based device programs compete on convenience, patient education, and repeat-use economics.
- Merz Pharma, Hugel Inc., and Kaken Pharmaceutical Co., Ltd. reflect broader botulinum toxin participation across regions, emphasizing the importance of local market access, brand recognition, and service infrastructure in sustaining prescription volume.
- Revance Therapeutics and Brickell Biotech Inc. sit within a broader innovation pipeline, illustrating ongoing interest in next-generation toxin formulations and topical anticholinergic candidates that could shift future competitive baselines.
- Dermavant Sciences Inc. adds to the pipeline landscape with dermatology-focused development activity that underscores how hyperhidrosis remains an attractive indication for specialized therapeutic programs.
Beyond company profiles, the research connects recent commercial events to structural change. A January 2025 clinical trial collaboration evaluating a topical combination approach signaled continued interest in optimizing non-invasive treatment regimens. Earlier regulatory milestones in 2024 and 2023 reinforced the broadening approval and clearance environment, showing how the market is accumulating viable options rather than relying on a single dominant standard. These events are analyzed not as isolated headlines but as inputs to competitive timing, launch sequencing, and regional expansion planning.
Regulatory, Reimbursement, and Supply Chain Realities
A market can expand on paper while remaining difficult to monetize in practice. The report devotes substantial attention to the institutional frictions that determine which growth is accessible to which business models. Regulatory approval is only one part of the equation; reimbursement policy, step-therapy design, and classification logic frequently determine whether clinical adoption converts into sustainable revenue.
In the United States, payers often require step therapy with antiperspirants before approving prescription topicals, and botulinum toxin reimbursements are commonly subject to quantity limits. These policies shape prescription behavior, patient access, and the economics of repeat treatment cycles. At the same time, advanced procedures may be categorized as cosmetic in certain settings, limiting coverage and increasing reliance on patient-funded demand. The study evaluates these dynamics across the treatment continuum so that commercial teams can anticipate the operational restrictions that will accompany clinical opportunity.
Supply chain considerations also feature prominently. Recent renegotiation of an active pharmaceutical ingredient supply agreement for a leading topical candidate illustrates how procurement structure can influence cost of goods sold, margin durability, and launch resilience. For strategists, the lesson is clear: in a market with multiple modalities and a growing list of specialty entrants, financial defensibility depends as much on input costs and distribution readiness as on clinical differentiation. The full report integrates these themes into a cohesive market-dynamics assessment, linking policy, pricing, production, and access into a single decision-relevant framework.
What the Full Study Delivers for 2026 Decision-Making
This research is designed to support concrete strategic actions rather than general market awareness. It provides an integrated view of market size evolution, segmentation interactions, competitive positioning, and operational constraints, allowing teams to move from observation to planning with greater confidence. The study's architecture is built for users who must make resource allocation choices under uncertainty and need evidence that connects market momentum to execution risks.
- A forecast model spanning 2026 through 2032 that ties historical trends to forward-looking demand drivers, giving planners a defensible basis for revenue modeling and investment timing.
- Segment-level analysis that explains how treatment types, end-user settings, and regional demand patterns interact, helping teams identify where adoption is most likely to accelerate and where barriers remain strongest.
- Competitive profiling that connects company strategies, regulatory status, and commercial assets to likely market-share implications, supporting benchmarking, partnership evaluation, and white-space identification.
- Market-structure metrics that illuminate concentration and competitive intensity, allowing leadership to gauge the balance between incumbent stability and entry opportunity.
- Practical context on reimbursement logic, clinical classification, and supply-side considerations, ensuring that commercial strategies are built around what the market can actually monetize, not just what it can theoretically absorb.
The study also includes analytical tools that help users pressure-test assumptions. Because hyperhidrosis care spans prescription therapy, device use, procedural services, and surgical intervention, the report considers how changing patient pathways, clinical referral behavior, and access policies can alter the shape of demand over time. That breadth is especially useful for organizations operating across multiple business lines or considering expansion into adjacent dermatology and aesthetics segments.
Why Strategic Timing Matters Now
The hyperhidrosis treatment market is maturing at a moment when differentiation, access strategy, and execution discipline will increasingly separate durable winners from temporary participants. Growth is projected to continue at a steady pace, but the more important question for leadership is not whether the market expands; it is where value will concentrate as treatment options multiply and payer systems adapt. Companies that understand the interplay between clinical acceptance, reimbursement constraints, and competitive entry timing will be better positioned to allocate capital, shape launch plans, and negotiate partnerships with precision.
Worldwide Hyperhidrosis Treatment Market
Our full Worldwide Hyperhidrosis Treatment Market report translates these strategic questions into a complete intelligence package. It goes beyond headline market size to show how the segments connect, how the competitive field is being organized, and which structural factors will determine commercial outcomes over the next several years. For executives preparing for 2026 planning cycles, the report offers a fact-based foundation for scenario planning, portfolio decisions, and market entry or expansion strategy.
To access the complete analysis, including segment-level forecasts, competitive profiles, and the detailed dynamics framework, request the full report through our official research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Hyperhidrosis Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Sandwich Car Heat Shield Market to Hit $1.64 Billion by 2032, CAGR 5.18%
By pmarketresearch, 2026-09-17
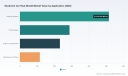
Strategic Insulation: Navigating the Worldwide Sandwich Car Heat Shield Market 2026-2032
The automotive thermal management landscape is undergoing a structural transformation. As original equipment manufacturers (OEMs) face mounting pressure to reduce vehicle weight, improve fuel efficiency, and manage the intense thermal loads of electrification, the demand for advanced heat shielding solutions has never been more critical. Sandwich car heat shields, with their multi-layered composite structures, have emerged as a pivotal technology in this evolution.
PW Consulting is pleased to introduce our comprehensive Worldwide Sandwich Car Heat Shield Market research. This study is designed not merely as a data repository, but as a strategic compass for industry stakeholders navigating the complexities of the 2026-2032 forecast period. By synthesizing historical performance with forward-looking analysis, this report equips decision-makers with the intelligence required to allocate capital, identify partnership opportunities, and mitigate supply chain risks in a rapidly evolving sector.
Market Trajectory and Historical Context
Understanding the momentum of the sandwich car heat shield market requires a clear view of its recent historical performance. The global market has demonstrated resilience and steady growth, reflecting the broader trends in automotive engineering. From a revenue base of approximately 890.12 Million USD in 2020, the market expanded to 962.59 Million USD in 2021. Although a minor contraction was observed in 2022 with figures around 956.71 Million USD, the sector quickly regained traction, surpassing 977.65 Million USD in 2023 and accelerating to 1089.99 Million USD in 2024.
By the base year of 2025, the market reached an estimated 1150.45 Million USD. This trajectory sets a robust foundation for the forecast period. Our analysis projects the market size to reach 1212.98 Million USD in 2026, continuing its upward climb to approximately 1350.73 Million USD by 2027 and 1377.48 Million USD by 2028. Long-term projections indicate sustained growth, with the market expected to approach 1434.69 Million USD in 2029, 1494.87 Million USD in 2030, and reaching roughly 1505.12 Million USD in 2031 before culminating at 1640.5 Million USD in 2032.
These figures translate to a Compound Annual Growth Rate (CAGR) of 5.18 percent over the forecast horizon. This growth rate underscores the essential nature of thermal management components in modern vehicle architecture. For strategic planners, this indicates a stable yet dynamic market environment where volume growth is coupled with increasing technical sophistication. The shift from simple metallic sheets to complex sandwich structures implies value migration within the supply chain, creating opportunities for suppliers who can innovate on material science and manufacturing efficiency.
Sandwich Panels Market
Key Industry Dynamics and Drivers
The expansion of the sandwich car heat shield market is propelled by a confluence of regulatory, technological, and environmental factors. Our research identifies several critical dynamics that are reshaping the competitive landscape.
Regulatory and Emission Standards
Strict emission regulations are compelling OEMs to adopt advanced lightweight materials. The necessity to reduce overall vehicle weight to meet fuel economy and carbon emission targets favors materials such as aluminum, composites, and multilayer insulation. Sandwich heat shields, which often combine high temperature resistant fiber fillers with aluminum or metallic layers, offer enhanced thermal insulation without the penalty of excessive weight. This regulatory push is not merely a compliance hurdle but a catalyst for innovation in material selection and structural design.
Electrification and Powertrain Evolution
The increasing adoption of plug-in hybrid electric vehicles (PHEVs) and battery electric vehicles (BEVs) is driving demand for specialized lightweight heat shields. Unlike internal combustion engine (ICE) vehicles, EVs require protection for battery packs and sensitive electronic components against thermal runaway and external heat sources. This shift necessitates shielding solutions that offer superior thermal propagation protection and electromagnetic interference (EMI) shielding. The transition to electrification is not just changing the volume of demand but fundamentally altering the specification requirements for heat shielding components.
Material Innovation
Aluminum-based heat shields are widely used due to their lightweight properties and heat-resistant qualities in sandwich and multi-layer constructions. However, the industry is seeing a diversification into advanced ceramics and fiber-based composites. Companies are developing adhesive-backed Thermal Dissipating Systems (TDS) that reflect and absorb heat while offering lighter weight alternatives to traditional metal options. Furthermore, new ranges of ceramic coatings are enabling the substitution of heavy steel with coated aluminum or composites, particularly in EV battery and heat-shield designs. These material advancements are critical for balancing cost, lightweight goals, and durable thermal performance.
Competitive Landscape and Strategic Positioning
The market is characterized by a mix of specialized component manufacturers and broader automotive suppliers. Our analysis indicates a moderately concentrated market structure, where the top three companies hold a significant portion of the market share at 42.35 percent, while the top five companies account for 58.12 percent. This concentration suggests that while scale economies exist, there is still ample room for niche players and innovators to capture value through specialized technology or regional expertise.
Several key enterprises define the competitive dynamics of this sector. Carcoustics International GmbH, based in Germany, specializes in aluminum components and sandwich-type structures for thermal heat shields. Their approach combines glass, ceramic, PE, or nonwovens to achieve specific thermal and acoustical properties, highlighting the convergence of sound management and thermal protection. Morgan Advanced Materials from the United Kingdom provides custom engineered multi-layered automotive heat shields using Superwool Fibres and WDS Microporous insulation, focusing on balanced cost and lightweight performance.
Autoneum, headquartered in Switzerland, offers acoustic and thermal management solutions with a focus on lightweight fiber-based options suitable for both ICE and EV platforms. Their recent establishment of a new Research & Technology Center in Shanghai underscores the strategic importance of the Asia Pacific region for new mobility and e-mobility components. ElringKlinger AG, also based in Germany, develops shielding solutions including ElroForm and ElroSafe products for engine compartments, exhaust systems, and battery thermal protection. Their recent introduction of ElroForm TP-ECO and ElroSafe shielding solutions at the International Suppliers Fair in 2024 highlights the industry's focus on thermal propagation protection and EMI shielding for battery systems.
Regional coverage is also provided by major players such as Dana Incorporated and Tenneco Inc. in the United States, who supply heat shields as part of broader thermal management portfolios. Vibrant Power Inc. in Canada produces multi-layered metallic heat shields from stainless steel, aluminized steel, or aluminum for OEM and aftermarket applications. Specialized manufacturing capabilities are represented by firms like JBC Technologies, Inc., which specializes in custom die-cutting of heat shielding and thermal management materials, and Argent International, which develops adhesive-backed TDS heat shields. Additionally, companies like Alkegen and innovators like Zircotec, who unveiled new ceramic coatings for lighter EV battery designs, are pushing the boundaries of material performance.
Regional Insights and Market Distribution
Geographically, the market exhibits distinct characteristics driven by local automotive production volumes and adoption rates of advanced vehicle technologies. The Asia Pacific region remains a dominant force in the global landscape, reflecting the high concentration of vehicle manufacturing hubs. Europe continues to be a key market, driven by stringent emission standards and a strong presence of luxury and performance vehicle manufacturers. North America represents a significant demand center, supported by a large automotive industry and a growing aftermarket sector for vehicle protection and modification.
Emerging regions such as Latin America and the Mideast and Africa are also contributing to the global demand, albeit at different scales. Understanding the specific penetration rates, growth vectors, and local regulatory landscapes within these regions is essential for companies planning market entry or expansion strategies. Our full report provides a granular breakdown of these regional dynamics, allowing stakeholders to tailor their go-to-market approaches to local conditions without relying on broad generalizations.
Product Segmentation and Application Diversity
The utility of sandwich car heat shields spans various critical vehicle systems. By material composition, the market is segmented into aluminum, stainless steel, and ceramic and others. Aluminum remains a prevalent choice due to its favorable strength-to-weight ratio, while stainless steel offers durability in high-stress environments. Ceramic and other advanced materials are gaining traction for applications requiring superior heat resistance and electrical insulation.
In terms of application, heat shields are integral to exhaust systems, turbochargers, engine compartments, and underbody protection. Exhaust systems represent a substantial portion of demand, given the high thermal loads involved. Turbochargers require precise shielding to manage heat concentration near sensitive components. Engine compartments need comprehensive coverage to protect surrounding parts from radiant heat. Finally, underbody and other applications are growing in importance, particularly for EVs where battery packs are often located in the chassis area. Each application segment presents unique engineering challenges and cost structures. Detailed analysis of these segments reveals specific volume drivers and pricing trends that are vital for production planning and R&D prioritization.
Recent Developments Shaping the Future
Recent industry activities highlight the pace of innovation and the strategic focus of key players. In late 2024, ElringKlinger AG introduced ElroForm TP-ECO and ElroSafe shielding solutions for battery systems, emphasizing thermal propagation protection and EMI shielding. This move aligns with the broader industry shift towards safety-critical thermal management for electrification.
Around the same time, Autoneum opened a new Research and Technology Center in Shanghai, focusing on New Mobility and e-mobility components including thermal management solutions. This facility opening signals a long-term commitment to developing technologies tailored for the Asian market and the global shift towards electrification. In early 2025, Autoneum further developed lightweight fiber-based heat shields offering thermal and acoustic insulation with improved recyclability for ICE and electric vehicles, addressing both performance and sustainability concerns.
More recently, in late 2025, Zircotec unveiled a new range of ceramic coatings for lighter EV battery and heat-shield designs. This launch enables the substitution of heavy steel with coated aluminum or composites, marking a significant step forward in material efficiency. These developments illustrate the continuous iteration of product offerings to meet the evolving demands of automotive OEMs. Companies that can rapidly integrate such innovations into their supply chains or collaborate with innovators stand to gain a competitive advantage.
Worldwide Sandwich Car Heat Shield Market
Strategic Value of the Report
PW Consulting's Worldwide Sandwich Car Heat Shield Market report is more than a collection of statistics; it is a decision-support tool designed for executives, investors, and strategists. The report provides an in-depth description of operational content, covering manufacturing processes, supply chain dynamics, and technology roadmaps. It offers actionable insights into cost structures, pricing models, and the economic viability of different material choices.
For companies looking to assess market opportunities, the report details the competitive positioning of key players, including their product portfolios, recent advancements, and strategic moves. Understanding the strengths and weaknesses of competitors like Carcoustics, Morgan Advanced Materials, Autoneum, and others allows for better positioning in bids, partnerships, and product development. The report also explores the regulatory environment in depth, helping stakeholders anticipate compliance costs and leverage regulatory changes as market drivers.
Furthermore, the analysis of raw material trends, such as the widespread use of aluminum-based heat shields and sandwich-type structures combining fiber fillers with metallic layers, provides a clear view of supply chain dependencies. This is crucial for risk management in the face of commodity price volatility. The integration of macro trends, such as the shift towards PHEVs and EVs, ensures that the forecast models are grounded in the realistic trajectory of automotive adoption.
Conclusion and Call to Action
As the automotive industry accelerates towards electrification and sustainability, the role of advanced thermal management solutions becomes increasingly strategic. The Worldwide Sandwich Car Heat Shield Market is poised for significant growth, driven by the need for lightweight, efficient, and high-performance insulation. However, capturing this value requires a nuanced understanding of regional dynamics, material science advancements, and competitive maneuvers.
This executive summary provides a glimpse into the depth of our analysis, highlighting the market trajectory, key drivers, and major players. To unlock the full potential of this intelligence for your organization, we invite you to access the complete Worldwide Sandwich Car Heat Shield Market report. The full study contains detailed segmentation data, comprehensive regional breakdowns, precise market sizing for every application and material type, and exhaustive competitor profiles. Equip your leadership team with the detailed intelligence needed to make informed investment decisions and secure a leadership position in the evolving landscape of automotive thermal protection.
For detailed analysis of this topic, please visit the official page: Worldwide Sandwich Car Heat Shield Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Fireproof Materials Market Hits $48,250M in 2025, Projected to Reach $73,416M by 2032
By pmarketresearch, 2026-09-17
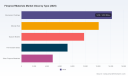
Strategic Imperatives in the Global Fireproof Materials Market: A 2026 Outlook
As we navigate the complex landscape of 2026, the global fireproof materials market stands at a critical juncture where safety regulations, sustainability mandates, and infrastructure development converge. For enterprise leaders and strategic planners, understanding the trajectory of this sector is not merely about compliance, but about securing long-term operational resilience and capitalizing on emerging growth vectors. PW Consulting is pleased to introduce our latest comprehensive study, the Worldwide Fireproof Materials Market research, designed to equip decision-makers with the granular intelligence needed to navigate these shifting tides.
The market has demonstrated robust expansion over the past half-decade, recovering from pandemic-era disruptions and accelerating through a period of intensified regulatory scrutiny and construction activity. Our analysis provides a detailed examination of this growth trajectory, offering a roadmap for stakeholders aiming to optimize their market positioning through 2032. This report is not just a collection of numbers; it is a strategic toolkit built on primary research, expert interviews, and deep-dive analytics.
Market Trajectory and Growth Dynamics
The historical performance of the fireproof materials sector underscores its fundamental importance to the global economy. From 2020 to 2025, the market navigated supply chain challenges and evolving safety codes, yet maintained a steady upward course. Our data indicates that the market valuation has progressed significantly, moving from approximately 36,112 million USD in 2020 to an estimated 48,250 million USD by 2025. This growth reflects a compound annual increase that highlights the non-discretionary nature of fire protection in modern infrastructure.
Looking forward, the forecast period from 2026 to 2032 projects continued expansion driven by urbanization and industrialization. We anticipate the market size to reach roughly 52,332 million USD in 2026, gaining momentum to surpass 73,416 million USD by the end of the forecast window in 2032. This projection is supported by a calculated CAGR of 6.18 percent over the forecast period. Such growth rates suggest that demand will outpace many traditional construction material sectors, fueled by stricter building codes in emerging economies and retrofitting initiatives in developed markets.
Key Growth Drivers
- Regulatory Tightening:** Global jurisdictions are increasingly mandating higher fire resistance ratings for both new constructions and renovations. This regulatory pressure creates a baseline demand that insulates the market from economic downturns.
- Infrastructure Investment:** Major government initiatives focused on transportation networks, energy facilities, and public buildings require specialized fireproofing solutions that meet rigorous performance standards.
- Sustainability Shift:** The industry is undergoing a transformation where traditional halogenated flame retardants are being phased out in favor of non-halogenated and sustainable alternatives. This shift opens new avenues for innovation and product differentiation.
Strategic Segmentation Insights
To effectively allocate resources, executives must understand where value is concentrated within the market. Our report dissects the industry across multiple dimensions, revealing which technologies and applications are capturing the greatest share of investment. The breadth of materials available allows for tailored solutions across diverse project requirements, from high-rise commercial structures to specialized industrial facilities.
Technology and Material Types
The competitive landscape is defined by a variety of material technologies, each serving specific functional needs. Intumescent coatings represent a significant portion of the market, valued for their ability to swell when exposed to heat and protect structural steel. Mineral wool and gypsum boards remain foundational for insulation and compartmentalization, while fire-resistant glass is gaining traction in aesthetic and safety-critical applications. Our analysis details the performance metrics, cost structures, and adoption rates of each category, enabling clients to identify gaps in their current product portfolios or supply chains.
Application Verticals
Demand is not uniformly distributed across end-use sectors. Commercial construction continues to be a primary driver, reflecting the ongoing development of office spaces, retail environments, and hospitality venues. However, industrial and manufacturing sectors present high-growth opportunities, particularly where chemical processing and energy production require robust fire safety measures. Residential buildings, oil and gas facilities, and transportation infrastructure also contribute meaningfully to the total demand. Understanding the specific fireproofing requirements for each vertical is essential for suppliers looking to maximize penetration rates.
Worldwide Fireproof Materials Market
Regional Dynamics
Geography plays a pivotal role in market strategy. The Asia Pacific region exhibits substantial volume due to rapid urbanization and large-scale infrastructure projects. North America and Europe maintain mature markets characterized by high regulatory standards and a focus on retrofitting existing structures. Latin America and the Middle East and Africa offer emerging opportunities tied to resource development and urban expansion. Our report provides nuanced regional analysis that goes beyond simple volume metrics, exploring local regulatory environments, supply chain logistics, and competitive intensity in each territory.
Competitive Landscape and Corporate Strategy
The market structure is moderately fragmented, with consolidation occurring through acquisitions and strategic partnerships. Our analysis of market concentration indicates that while top players hold significant influence, there is ample room for specialized firms to compete on technology and service. The CR3 and CR5 metrics suggest that no single entity dominates the entire value chain, allowing for diverse strategic approaches ranging from broad portfolio management to niche technology leadership.
Profiles of Key Market Players
Success in this sector requires a mix of chemical innovation, coating technology expertise, and strong distribution networks. Several multinational corporations define the current competitive baseline.
3M Company continues to leverage its broad portfolio of passive fire protection materials, including firestop systems and intumescent products for construction and electrical applications. Their recent enhancements to fire barrier solutions demonstrate a commitment to incremental innovation. AkzoNobel N.V. maintains a strong presence through high-performance coatings under brands like Interchar and Chartek, specifically targeting structural steel protection in construction and oil and gas sectors. BASF SE supplies essential flame retardant chemicals and additives, underpinning many downstream fireproofing solutions with their chemical expertise.
PPG Industries, Inc. manufactures intumescent and fire-resistant protective coatings, recently expanding their fire testing and certification capabilities to ensure third-party validation of structural steel coatings. Hilti Group specializes in firestop and fire protection systems, providing sprays, sealants, and passive fire protection products crucial for infrastructure integrity. Rockwool International A/S produces stone wool-based insulation materials known for high fire resiliency, catering to both building and industrial needs. Sika AG delivers comprehensive firestop systems and intumescent coatings, integrating fire protection into broader construction chemical solutions.
Magnesium Fireproof Board Market
The Sherwin-Williams Company offers FIRETEX intumescent coatings for structural steel, focusing on commercial and industrial settings where on-site application is required. Hempel A/S provides intumescent coatings for marine and infrastructure sectors, addressing corrosive and high-temperature environments. Morgan Advanced Materials supplies advanced fire protection materials and insulation for high-temperature industrial applications, distinguishing itself through material science capabilities. Isolatek International specializes in spray-applied fire resistive materials for structural steel, a critical component in large-scale construction projects.
Owens Corning and Saint-Gobain S.A. contribute through fire-resistant insulation materials and boards, utilizing their extensive manufacturing footprints. DuPont de Nemours, Inc. develops high-performance fire-resistant fabrics and coatings for specialty applications, while LANXESS AG and Albemarle Corporation focus on the upstream supply of flame retardant additives and chemicals. Their role is critical as raw material volatility and regulatory changes regarding substances like antimony trioxide impact cost structures and formulation strategies across the industry.
Recent Strategic Moves and Market Signals
The competitive landscape is dynamic, with recent developments signaling shifts in technology and partnership strategies. In April 2026, OUSHIBAO New Materials upgraded their MGO fireproof board production technology, obtaining key international certifications including ASTM E84 Class A and EN 13501-1 A1. This move highlights the importance of certification in accessing global markets. Also in April 2026, CitroTech and Hexion formed a 50/50 joint venture to advance next-generation fire-protected wood products using EPA Safer Choice recognized chemistry, indicating a trend toward sustainable solutions in wood-based construction materials.
Earlier developments also set the tone for current strategies. In October 2025, 3M Company introduced enhanced fire barrier solutions including upgraded electrical box inserts and tuck-in wrap strips with advanced intumescent technology. Similarly, in September 2025, PPG Industries expanded their fire testing and certification capabilities, focusing on validated structural steel fire coatings. These actions underscore the industry's focus on performance validation and product enhancement to meet evolving safety standards.
Regulatory and Supply Chain Dynamics
Navigating the regulatory environment is perhaps the most complex challenge for market participants. Regulations are not static; they evolve in response to health concerns and environmental data. For instance, Massachusetts issued final regulations in May 2025 banning or restricting specific flame retardants, including antimony trioxide and certain organophosphorus compounds, in consumer products above specific thresholds. This type of localized regulation can ripple through global supply chains, forcing reformulation and sourcing changes.
Furthermore, the global shift toward non-halogenated and sustainable flame retardants continues to accelerate due to environmental and health concerns over traditional compounds. This transition requires R&D investment and may alter cost structures. Supply side volatility also remains a concern. Raw material pricing, particularly for inputs like antimony trioxide, has experienced fluctuation driven by supply constraints and export controls in key manufacturing regions such as China. These factors necessitate robust supply chain risk management and flexible procurement strategies.
Our report delves deep into these dynamics, analyzing how regulatory trends in major markets will shape product development roadmaps and how raw material volatility might impact margin stability. Understanding the interplay between chemical restrictions and performance requirements is vital for maintaining compliance without compromising safety or cost-efficiency.
The Strategic Value of This Research
In an environment where capital allocation decisions must be justified by rigorous data, the Worldwide Fireproof Materials Market report serves as an essential asset. It provides more than just historical data; it offers forward-looking intelligence that supports strategic planning. Whether you are a manufacturer looking to expand your product line, a contractor seeking reliable supply partners, or an investor evaluating market entry opportunities, this study provides the context needed to make informed choices.
The report integrates macroeconomic factors, regulatory forecasts, and competitive benchmarking to present a holistic view of the industry. It identifies not only where the market is going but also the potential pitfalls and opportunities that lie along the path. By understanding the segmentation dynamics, regional nuances, and competitive movements, organizations can tailor their strategies to capture value in specific niches or dominate broader categories.
Access to this level of detail allows stakeholders to anticipate market shifts rather than react to them. With the forecast period extending to 2032, the insights contained within this research will remain relevant for multiple planning cycles. The combination of quantitative data and qualitative analysis ensures that readers gain a comprehensive understanding of the forces driving the industry.
Conclusion
The global fireproof materials market is poised for sustained growth, driven by an unyielding demand for safety and compliance in an increasingly complex built environment. As regulations tighten and sustainability becomes a core requirement, the companies that thrive will be those with access to precise, actionable intelligence. PW Consulting's latest research offers that intelligence, providing a detailed map of the terrain ahead. We invite you to explore the full findings of this report to deepen your understanding of the market mechanisms, competitive forces, and strategic opportunities that will define the sector through the next decade. The full depth of our analysis, including detailed segment breakdowns and proprietary forecasts, is available through our comprehensive report suite.
For detailed analysis of this topic, please visit the official page: Worldwide Fireproof Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global PCR Plate Sealer Market to Hit $923M by 2032, 7.8% CAGR
By pmarketresearch, 2026-09-17
Strategic Insights into the Worldwide PCR Plate Sealer Market: Navigating Growth and Innovation Through 2032
In the rapidly evolving landscape of life sciences and diagnostic research, the integrity of sample preparation remains paramount. PCR plate sealers play a critical role in ensuring that samples remain uncontaminated and viable throughout thermal cycling and storage processes. As laboratories scale operations and regulatory standards tighten, the demand for reliable sealing solutions has grown substantially. This article introduces our latest comprehensive study on the Worldwide PCR Plate Sealer Market, designed to equip industry leaders with the actionable intelligence needed for strategic decision-making in 2026 and beyond.
Market Trajectory and Growth Dynamics
The global PCR plate sealer market has demonstrated resilient expansion over the past five years, reflecting the broader acceleration in molecular diagnostics and pharmaceutical research. Analysis indicates that the market has progressed from approximately 385 million USD in 2020 to an estimated 545 million USD in 2025. This historical progression underscores a steady adoption rate driven by increasing throughput requirements in high-complexity laboratories.
Looking forward, the forecast period from 2026 to 2032 projects a robust compound annual growth rate of 7.8 percent. By the end of this forecast window, the market is anticipated to reach significant valuation milestones, surpassing 923 million USD by 2032. This growth trajectory is not merely a function of volume but is deeply intertwined with technological advancements in automation and the shifting needs of end-users who require higher consistency and reduced manual intervention. For stakeholders planning capital expenditures or product roadmaps in 2026, understanding the velocity of this growth is essential for capacity planning and market entry strategies.
Technological Segmentation and Product Evolution
The market is diversified across several product categories, each catering to specific operational needs within the laboratory environment. Automated heat sealers currently represent a substantial portion of revenue, reflecting the industry's shift toward high-throughput workflows where consistency is non-negotiable. Semi-automated and manual sealers continue to hold relevance, particularly in settings where flexibility and lower capital outlay are prioritized. Additionally, adhesive and pressure sealers serve niche applications where thermal exposure must be minimized.
The choice of sealing technology often depends on the specific workflow constraints of the end-user. Pharmaceutical and biotechnology firms typically lean toward automated solutions to ensure batch-to-batch reproducibility, while academic institutions may balance cost with functionality. The interplay between these product types creates a complex ecosystem where vendors must differentiate not just on hardware, but on the compatibility of consumables such as films and foils. Our report delves into the specific strengths and weaknesses of each segment, providing a nuanced view of where innovation is most urgently required.
Regional Performance and Geographic Opportunities
Geographically, the market exhibits distinct characteristics shaped by local regulatory environments, healthcare infrastructure, and research funding levels. North America remains a dominant force, driven by a dense concentration of biotechnology firms and advanced diagnostic laboratories. Europe follows as a significant contributor, supported by strong public research initiatives and stringent quality standards that favor high-quality sealing equipment.
Worldwide PCR Plate Sealer Market
Meanwhile, the Asia Pacific region presents a compelling growth story, fueled by expanding healthcare infrastructure and increasing outsourcing of clinical research activities. Latin America and the Middle East and Africa, while smaller in current valuation, are emerging as areas of interest for companies looking to diversify their geographic footprint. Understanding the regional nuances is critical for distributors and manufacturers aiming to tailor their go-to-market strategies. The full study provides a detailed breakdown of regional dynamics without disclosing the specific percentage splits that constitute our proprietary depth analysis.
End-User Drivers and Application Demands
The demand for PCR plate sealers is fundamentally anchored by the needs of end-users who rely on precise molecular techniques. Pharmaceutical and biotechnology companies constitute a primary driver, as they require robust sealing solutions for drug discovery and development pipelines. Diagnostic laboratories represent another major pillar, where the accuracy of PCR results directly impacts patient care and disease monitoring.
Academic and research institutes also contribute significantly to the market, often seeking versatile equipment that can handle varied plate formats. Forensic laboratories, though smaller in volume, require high reliability for evidentiary samples. Each of these segments imposes different requirements on sealing equipment regarding speed, compatibility, and ease of use. Our analysis maps these requirements against available solutions to help buyers and sellers align their expectations with market realities.
Competitive Landscape and Key Players
The market is characterized by a moderate level of concentration, with a handful of established players commanding a significant share of the global revenue. Leading companies such as Thermo Fisher Scientific, Bio-Rad Laboratories, Eppendorf, Agilent Technologies, Hamilton Company, Labnet International, and Genesee Scientific are at the forefront of this industry. These organizations compete through product innovation, strategic partnerships, and the expansion of their consumable portfolios.
For instance, Thermo Fisher Scientific offers the ALPS5000 automated plate heat sealer alongside manual options, complemented by a range of adhesive seals and foils designed to prevent evaporation. Bio-Rad Laboratories provides the PX1 PCR Plate Sealer, known for consistent uniform heat sealing, along with compatible films for 96- and 384-well plates. Eppendorf manufactures the HeatSealer S100 and S200 models, catering to 96-well and 384-well formats as well as deepwell plates. Agilent Technologies supplies the PlateLoc Thermal Microplate Sealer, focusing on automated sealing to maintain sample integrity. Hamilton Company specializes in aluminum plate seals and automation-compatible options free from nucleic acids. Labnet International and Genesee Scientific round out the competitive field with their respective instrumentation and high-quality sealing films and accessories.
Recent developments highlight the active nature of this competitive space. In October 2024, Bio-Rad Laboratories was awarded a contract by the National Cancer Institute for the supply of Digital PCR Plate Sealers and PCR systems, signaling strong endorsement from key government health entities. Such moves illustrate how strategic contracts can solidify market position and drive brand credibility. Our report analyzes the strategic moves of these key companies, including their product launches, partnerships, and regional expansion efforts, to provide a clear picture of the competitive intensity.
Regulatory Standards and Material Considerations
Compliance and material quality are increasingly becoming differentiators in the PCR plate sealer market. Equipment and associated consumables used for clinical molecular diagnostics are often manufactured under ISO 13485 quality management standards for medical devices. This regulatory framework ensures that products meet rigorous safety and performance criteria, which is particularly important for laboratories operating in regulated environments.
Furthermore, the raw materials used in PCR-related plastics and sealers are subject to evolving market dynamics. The global medical plastic compounds market, relevant for PCR plate and sealer consumables production, was valued at 10.2 billion USD in 2024 and is projected to reach 15.8 billion USD by 2033. Within this, the high-performance medical plastics market, used in diagnostic consumables, is estimated at 1.2 billion USD in 2025, with polycarbonate holding a significant share.
Tray Sealing Machines Market
Laboratory plastic consumables must also maintain mechanical integrity and clarity after exposure to common sterilization methods such as gamma radiation, ethylene oxide, and steam. These factors influence the selection of sealing materials and the longevity of the sealing equipment itself. Understanding the intersection of material science, regulatory compliance, and equipment performance is vital for manufacturers sourcing components and for laboratories validating their workflows.
Strategic Value of the Full Report for 2026 Decision-Making
Access to granular data and forward-looking analysis is indispensable for navigating the complexities of the PCR plate sealer market. While the overview provided here highlights the broad trends and key players, the complete Worldwide PCR Plate Sealer Market research offers a depth of insight that can directly inform investment, procurement, and strategic planning.
Decision-makers in 2026 require more than just top-line numbers. They need to understand the specific growth vectors within product types, the nuanced demand patterns across different end-user groups, and the precise competitive positioning of each major vendor. Our report includes detailed segmentation analysis, historical data tracking, and forecast models that isolate key growth drivers and potential restraints. It also examines the impact of raw material cost fluctuations and regulatory changes on market pricing and availability.
For organizations looking to capitalize on the projected 7.8 percent CAGR, the ability to pinpoint high-growth segments and evaluate competitor strategies is a distinct advantage. Whether you are a manufacturer seeking to identify white spaces for new product development, a distributor planning inventory based on regional demand shifts, or an investor assessing the viability of market entrants, the full report provides the evidence base required to mitigate risk and maximize opportunity.
The study also covers recent developments and industry context noise that could impact market trajectories, such as procurement awards and shifts in medical plastic pricing. By integrating these external factors with internal market data, we provide a holistic view that supports robust scenario planning.
Conclusion
The Worldwide PCR Plate Sealer Market is poised for sustained growth, driven by the indispensable role of PCR technology in modern science and medicine. As the market expands from its current valuation toward the 900 million USD mark by 2032, the competitive landscape will likely intensify, rewarding those who can innovate in automation, compliance, and material quality.
This introduction serves as a preview of the comprehensive intelligence available in our full market research report. To access the detailed segmentation data, regional breakdowns, competitor profiles, and strategic recommendations that will empower your 2026 decisions, we invite you to explore the complete study. The depth of analysis contained within is designed to transform uncertainty into clarity, enabling stakeholders to act with confidence in a dynamic global marketplace.
For detailed analysis of this topic, please visit the official page: Worldwide PCR Plate Sealer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Portable pH Meter Market Hits $425.61M in 2025, Projected 5.12% CAGR to 2032
By pmarketresearch, 2026-09-17
Strategic Intelligence in a Changing Field: Navigating the Worldwide Portable pH Meter Market with PW Consulting
In an era where environmental compliance, food safety, and pharmaceutical quality control demand faster, more accurate, and more mobile measurement tools, the portable pH meter market has evolved from a niche laboratory accessory into a strategically critical segment of the broader instrumentation landscape. Over the past five years, stakeholders across water management, food and beverage production, biotechnology, and environmental testing have recalibrated their procurement strategies, driven by tightening regulatory expectations, supply chain realignment, and a growing appetite for connected, field-ready devices. PW Consulting’s latest worldwide market study is designed not merely as a numerical snapshot, but as a decision-making framework for executives who must allocate capital, prioritize product development, and position their organizations against an increasingly competitive and technologically sophisticated vendor landscape in 2026 and beyond.
The strategic value of this research lies in its ability to translate historical momentum into forward-looking operational intelligence. Drawing on a comprehensive historical window and extending through a seven-year forecast horizon, the analysis captures the inflection points that separate short-term demand fluctuations from structural market shifts. For leadership teams preparing their 2026 budgets, product roadmaps, and regional expansion plans, the report offers a disciplined lens through which to evaluate where growth is organically emerging, where competitive intensity is compressing margins, and where regulatory and technological tailwinds are creating durable advantages for early movers. Rather than presenting a static aggregation of figures, the study situates every metric within the operational realities of procurement cycles, field-deployment constraints, compliance workflows, and R&D investment timelines that actually drive purchasing behavior on the ground.
From a top-down perspective, the worldwide portable pH meter market has demonstrated a clear trajectory of expansion across the historical period, with total revenue climbing from approximately 331.45 million USD in 2020 to 434.03 million USD in 2024, before settling at an estimated 425.61 million USD in 2025 as the sector experienced a brief normalization following several years of accelerated adoption. Looking ahead, the forecast window projects a measured but consistent expansion path, anchored by a compound annual growth rate of 5.12 percent and a projected market valuation that reaches roughly 470.48 million USD in 2026 and continues climbing toward 603.68 million USD by 2032. This growth cadence is neither explosive nor stagnant; instead, it reflects a mature yet still dynamic category in which incremental gains are increasingly tied to product differentiation, application-specific engineering, and the ability to integrate measurement workflows into broader digital quality systems.
The forecast narrative carries particular weight for 2026 because it aligns with a period in which several structural pressures are converging. Field teams across municipal water operations, industrial process monitoring, and decentralized environmental sampling are demanding instruments that can withstand harsher deployment conditions, deliver repeatable data under variable temperatures and sample matrices, and feed results directly into centralized reporting platforms without sacrificing portability. At the same time, regulated end-use sectors are under growing scrutiny to demonstrate chain-of-custody integrity, calibration traceability, and sensor lifecycle management. These forces are reshaping purchasing criteria: buyers are increasingly evaluating total cost of ownership, electrode service life, connectivity features, and compliance readiness alongside upfront price. The study captures these shifts by mapping revenue movements against the operational realities that influence procurement decisions, helping readers distinguish between short-lived promotional demand and longer-term adoption curves.
A defining feature of the research is its application- and type-level dissection of demand drivers, presented with enough granularity to guide portfolio and segmentation strategy while preserving the analytical discipline necessary for actionable interpretation. On the product side, the market naturally bifurcates between digital and analog portable pH meters, each serving different operational priorities. Digital units continue to gain traction in environments where data logging, calibration documentation, and multi-parameter integration matter most, particularly in commercial testing laboratories, regulated processing facilities, and field programs that must produce auditable records. Analog instruments, meanwhile, retain relevance in applications where simplicity, lower acquisition cost, and straightforward field operation remain decisive, especially in educational settings, intermittent field sampling, and price-sensitive distribution channels.
By application, the research examines how demand is distributed across water and wastewater treatment, food and beverage processing, pharmaceutical and biotechnology workflows, environmental testing, and agriculture and soil testing. Each vertical presents a distinct combination of compliance pressure, sampling frequency, measurement environment, and procurement governance. Water and wastewater operations, for example, are shaped by continuous monitoring expectations, seasonal discharge variations, and the need for rugged field instruments capable of handling turbid or chemically variable samples. Food and beverage demand is driven by hygiene verification, process control, and batch-release requirements that often demand rapid turnaround and documented calibration histories. Pharmaceutical and biotechnology applications impose the most stringent expectations around measurement integrity, sensor qualification, and documentation, frequently linking portable measurement tools to broader quality management systems. Environmental testing and agricultural soil monitoring contribute additional layers of complexity, with decentralized sampling networks, variable field conditions, and cost-conscious procurement patterns influencing volume, replacement cycles, and feature preferences.
The regional dimension of the study completes this operational picture. Demand patterns differ materially across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, reflecting variations in regulatory frameworks, industrial concentration, distributed monitoring programs, and the pace of technology adoption in field environments. Rather than treating geography as a simple revenue split, the analysis explores how regional procurement cultures, public-sector testing mandates, export-driven manufacturing activity, and local service infrastructure shape the commercial logic of portable measurement devices. This regional lens is especially useful for organizations evaluating where to prioritize sales coverage, service networks, distribution partnerships, or localized product adaptations.
Competitive Dynamics and Strategic Postures
No market analysis is complete without a rigorous reading of the competitive field, and the portable pH meter segment is shaped by a group of established manufacturers whose product strategies, certification portfolios, and channel capabilities create both barriers and opportunities for incoming competition. The study profiles leading participants including Hanna Instruments, Horiba, Thermo Fisher Scientific, Mettler Toledo, YSI (Xylem), Oakton (Cole-Parmer), Extech Instruments (FLIR), and Milwaukee Instruments, each of which brings a distinct combination of engineering heritage, application focus, and go-to-market strength.
Worldwide Portable pH Meter Market
Several of these players illustrate how product strategy is being realigned around field readiness, connectivity, and compliance documentation. Hanna Instruments has extended its portable portfolio with edge pH meters incorporating Bluetooth modules and wireless probe options, signaling a push toward more flexible data transfer and field connectivity. Horiba has broadened its Americas catalog with pocket and handheld offerings optimized for low-volume samples and microelectrode configurations, reinforcing its emphasis on measurement flexibility in environmental, aquaculture, and portable clinical use cases. Thermo Fisher Scientific has reinforced the ruggedness and multi-parameter capability of its Orion Star A series, including updated certifications that support deployment in demanding lab, field, and industrial settings. Mettler Toledo continues to position its portable instruments around intelligent sensor management, protection ratings, and compliance-oriented features relevant to pharmaceutical, food, and environmental testing workflows. YSI, operating within the Xylem ecosystem, integrates portable pH measurement with multi-parameter sondes designed for wastewater, surface water, and environmental monitoring programs where correlated parameters and durable field deployment are essential. Oakton and Extech Instruments maintain strong positions in education, HVAC, water treatment, and general field testing through waterproof designs, data logging, electrode diagnostics, and calibration alerting features. Milwaukee Instruments serves more price-sensitive and specialized niche segments with compact instruments tailored to hydroponics, aquariums, and routine field use.
These product movements matter because they reveal where the market’s value creation is heading. Competition is increasingly less about offering a bare-bones measurement function and more about delivering a dependable field workflow: instruments must survive deployment, provide stable readings across sample conditions, simplify calibration and electrode replacement, and reduce the administrative burden of documentation. In that context, the study’s competitive assessment focuses not only on current product positioning but also on the strategic implications of certification upgrades, trade-show introductions, catalog expansions, and wireless-integration initiatives. Organizations reading this section can better anticipate where rival vendors may strengthen channel advantages, where feature parity could compress price-based differentiation, and where underserved application requirements may still create room for targeted product strategies.
Regulatory, Technical, and Commercial Undercurrents
Strategic planning in this category also requires a clear understanding of the non-market forces that influence purchasing behavior and product design. Portable pH meters used in medical or clinical-adjacent settings must navigate quality management expectations such as ISO 13485 and electrical safety considerations including IEC 60601-1, which raises the bar for manufacturers seeking to serve regulated healthcare workflows. In the United States, benchtop and portable pH meters are generally classified as Class I exempt devices under 21 CFR 872.3770 for certain dental applications, but that classification does not eliminate the operational need for careful documentation, calibration control, and intended-use clarity. In hospital and clinical environments, portable pH meters are typically restricted to research and non-invasive diagnostic use, and reimbursement frameworks do not assign dedicated CPT or DRG codes to these instruments; instead, they are treated as general laboratory supplies within institutional budgets. These realities shape procurement volume, purchasing authorization pathways, and the relative importance of service and compliance support.
On the technical side, glass pH electrodes remain a central cost and lifecycle consideration. Medical-grade borosilicate construction is commonly required for durable performance, with electrode life typically ranging from 12 to 18 months under continuous use. This replacement cadence has direct implications for total cost of ownership, service planning, inventory management, and customer retention strategies, particularly in high-frequency testing environments where electrode failure translates into downtime and data gaps. For vendors, this creates both a recurring-revenue dynamic and a differentiation opportunity through electrode design, sensor management software, and field service support. For buyers, it reinforces the importance of evaluating not just the upfront instrument price but the long-term cost and reliability of consumables, calibration standards, and replacement parts.
What the Study Delivers for 2026 Decision-Making
PW Consulting’s worldwide portable pH meter market research is built to move beyond headline figures and into the operational questions that determine commercial outcomes. The report integrates historical performance, forecast trajectories, segmentation logic, competitive profiling, and regulatory context into a single decision-oriented framework. It is designed to help executives answer practical questions such as where demand is most resilient, which application segments justify feature investment versus cost optimization, how regional procurement environments influence go-to-market sequencing, and which vendor strategies are most likely to shape price, service, and differentiation dynamics over the forecast period.
Portable Keratometer Market
Readers will find detailed analysis of revenue movement across the historical and forecast windows, with particular attention to the inflection patterns that explain why the market expanded, normalized, and is now advancing at a moderate but sustained pace. The segmentation discussion provides a structured view of how product type and application needs interact to shape purchasing priorities, without reducing those needs to oversimplified ratios. The competitive section maps the strategic postures of leading manufacturers, linking recent product launches, certification updates, catalog changes, and trade-show activity to broader positioning implications. Regulatory and technical undercurrents are addressed as commercial factors rather than abstract compliance notes, helping teams evaluate how quality management expectations, electrical safety standards, electrode lifecycle economics, and reimbursement realities affect demand volatility and channel strategy.
For organizations preparing 2026 investments, the study functions as a risk-calibrated roadmap. It helps identify where growth is supported by durable drivers such as compliance pressure, decentralized monitoring needs, and digital workflow integration, and where growth may be more sensitive to macroeconomic fluctuations, replacement cycles, or competitive substitution. It also provides the context needed to interpret regional demand with operational nuance, enabling more informed decisions about distribution partnerships, service coverage, localization priorities, and application-specific marketing.
The most consequential insights, however, are necessarily reserved for the full report. Detailed segmentation profiles, regional and application-level revenue structures, concentration metrics, forecast scenarios, and company-level strategic assessments are presented in depth within the complete study, where they can be examined alongside methodology notes, primary research context, and scenario-based interpretation. This preview is intended to convey the analytical rigor and practical relevance of the research while preserving the specifics that give the full report its decision-making power.
In a market where field portability, data integrity, compliance readiness, and total cost of ownership are increasingly inseparable, strategic foresight is not a luxury but a requirement. PW Consulting’s worldwide portable pH meter market study is structured to give leaders that foresight: a disciplined, evidence-based view of where the market has been, how it is currently organized, and what the next phase of competition and adoption is likely to demand. For teams shaping product priorities, procurement strategies, market-entry plans, or investment theses in 2026, the full intelligence suite offers the detail, structure, and interpretive guidance needed to move from awareness to action.
For detailed analysis of this topic, please visit the official page: Worldwide Portable pH Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Heparin Market Hits $6.85B in 2025, Forecasted 5.85% CAGR to Reach $10.2B by 2032
By pmarketresearch, 2026-09-17
Navigating the Global Heparin Market: Strategic Intelligence for 2026 and Beyond
The global medical heparin market stands at a critical intersection of clinical necessity, supply chain complexity, and regulatory scrutiny. As one of the most foundational anticoagulants in modern medicine, heparin continues to anchor treatment protocols across surgical, cardiovascular, and renal care settings. Yet, despite decades of established use, the market has entered a phase of structural recalibration. For pharmaceutical leaders, procurement executives, and healthcare strategists, understanding the trajectory of this market through 2032 is no longer optional; it is a core component of risk mitigation and growth planning.
Our latest Worldwide Medical Heparin Market research report translates historical performance, forward-looking projections, and operational dynamics into a single strategic framework. Designed for decision-makers operating in the 2026 business environment, the study moves beyond headline figures to expose the mechanics driving product adoption, regional balance, competitive positioning, and supply chain resilience. Below, we outline the analytical architecture and strategic utility of the report, illustrating why it should serve as a foundational reference for your 2026 planning cycle.
Worldwide Medical Heparin Market
Why Heparin Demands Renewed Strategic Attention in 2026
Heparin's clinical indispensability is counterbalanced by a supply ecosystem that remains vulnerable to biological, geopolitical, and regulatory shocks. The active pharmaceutical ingredient relies predominantly on porcine intestinal mucosa, with sourcing heavily concentrated in a single geographic corridor. This dependence has repeatedly demonstrated its capacity to translate livestock health events, export policy shifts, and sudden demand spikes into pricing volatility and availability constraints. Simultaneously, regulatory agencies across major markets continue to tighten quality expectations, traceability mandates, and contamination safeguards for animal-derived APIs.
In parallel, clinical utilization patterns are evolving. Venous thromboembolism management, renal dialysis support, and coronary artery disease interventions remain central demand pillars, but product form preferences, premixed hospital formulations, and catheter lock innovations are reshaping procurement behavior. The result is a market where historical volume trends are necessary but insufficient for forward planning. Decision-makers require a structured view of how type differentiation, application mix, and regional dynamics interact with competitive moves and supply-side risks.
Market Sizing and Projected Trajectory: Reading the Numbers Strategically
The market's historical arc from 2020 through 2025 establishes a clear baseline of expansion punctuated by brief cyclical adjustments. Starting from a base in the early 2020s, revenue progressed through a period of recovery and growth, ultimately reaching approximately 6,850.40 million USD in 2025. This trajectory reflects both renewed hospital activity post-pandemic and consistent institutional reliance on heparin-based anticoagulation across multiple care settings.
Heparin Market
Looking ahead, the forecast window from 2026 to 2032 projects sustained expansion at a compound annual growth rate of 5.85 percent. The progression from roughly 7,188.34 million USD in 2026 to a projected 10,198.87 million USD by 2032 signals more than incremental growth; it indicates a market that is scaling structural demand while navigating the cost and availability pressures inherent to its raw material base. For executives, the strategic implication is twofold. First, growth is broad-based enough to warrant capacity and portfolio planning rather than opportunistic bets. Second, the pace of expansion will be moderated or accelerated by supply chain performance, regulatory compliance costs, and the speed at which alternative sourcing and processing innovations are commercialized.
Rather than presenting these figures as isolated endpoints, the report embeds them within sensitivity considerations. Readers are guided through the ways macroeconomic shifts, disease-driven supply interruptions, and pricing negotiations affect realized revenue versus projected tops. This approach ensures that financial planning is anchored to realistic operational scenarios rather than optimistic abstractions.
What the Report Covers: Operating Intelligence for Execution Teams
A market study is only as valuable as the actions it enables. Accordingly, this research is structured to support cross-functional teams tasked with sourcing, commercialization, regulatory alignment, and competitive positioning. The report delivers detailed breakdowns across the following operational dimensions:
- Type-based segmentation dynamics examining how unfractionated heparin, low molecular weight heparin, and ultra-low molecular weight heparin occupy distinct clinical and procurement niches, and how formulation preferences are shifting in hospital and outpatient settings.
- Application-level demand mapping that traces usage intensity across major therapeutic areas, helping teams anticipate where volume growth, substitution risk, and pricing pressure are likely to converge.
- Regional balance and sourcing geography detailing where consumption is concentrated, how import dependency varies, and where localized manufacturing or partnership strategies can reduce exposure to concentrated supply risk.
- Competitive positioning and strategic moves profiling the companies shaping supply, formulation innovation, and hospital integration, including recent product launches, joint ventures, and commercial availability milestones that alter procurement options.
- Supply chain vulnerability analysis focusing on raw material concentration, porcine mucosa dependency, historical disruption patterns, and the practical implications for inventory planning, contract negotiation, and diversification roadmaps.
- Regulatory and quality compliance context covering the standards imposed by major health authorities, the operational burden of traceability and contamination prevention, and how compliance readiness can become a competitive differentiator.
- Scenario planning tools that allow users to stress-test growth assumptions against raw material shocks, tariff or export shifts, and changes in hospital procurement behavior.
By integrating these layers, the report equips readers to coordinate across procurement, R&D, regulatory affairs, and commercial strategy without relying on fragmented data sources. Each section is built to feed directly into budgeting, contract strategy, product roadmap decisions, and regional expansion evaluation.
Competitive Landscape: How Leading Players Are Shaping the Next Cycle
The heparin market is characterized by a mix of global pharmaceutical manufacturers, specialized API producers, and regional suppliers with strong footprint advantages in specific distributions channels. Concentration remains significant, with a handful of firms capturing a substantial share of revenue, while a broader field of manufacturers competes on formulation breadth, supply reliability, and cost positioning.
Several incumbents illustrate the strategic diversity within the market. Pfizer Inc. maintains a prominent role in unfractionated and low molecular weight heparin formulations, with strong relevance in surgical, cardiovascular, and hospital-use injectable products. Sanofi S.A. is a recognized producer of low molecular weight heparin therapies, including enoxaparin, supporting thrombosis prevention and treatment on a global scale. Baxter International Inc. supplies heparin sodium injections and premixed bags designed for intravenous hospital use, focusing on anticoagulant solutions that support clinical procedures and dialysis workflows. B. Braun SE emphasizes premixed infusion solutions and supply security, with an emphasis on hospital pharmacy integration for catheter patency and anticoagulation. Fresenius SE & Co. KGaA, through its Fresenius Kabi operations, provides heparin sodium injection for anticoagulation in hospital and critical care environments, including dialysis and surgical applications.
Beyond these established players, a broad tier of firms contributes to global availability and pricing dynamics. LEO Pharma A/S develops and markets low molecular weight heparin and heparin-based anticoagulants for thromboembolic disorders. Dr. Reddy's Laboratories Ltd. and Teva Pharmaceutical Industries Ltd. extend cheaper or institutionally focused generic heparin and LMWH offerings, broadening access for hospital and institutional buyers. Aspen Pharmacare Holdings Ltd. reinforces distribution reach across multiple regions and maintains a visible presence in emerging markets. On the API and processing side, Shenzhen Hepalink Pharmaceutical Group Co., Ltd. stands out as one of the largest integrated producers of heparin API and finished dosage forms, leveraging a vertically connected porcine mucosa supply chain. Opocrin S.p.A. and Bioiberica S.A.U. specialize in heparin API production and purification, with Bioiberica also directing attention toward sustainable extraction, traceability, and joint venture structures aimed at circular production models. Additional contributors such as Hebei Changshan Biochemical Pharmaceutical Co., Ltd., Changzhou Qianhong Bio-pharma Co., Ltd., and Nanjing King-friend Biochemical Pharmaceutical Co., Ltd. reinforce the breadth of API and derivative manufacturing feeding global demand.
Recent corporate activity underscores how competition is being contested in the near term. B. Braun Medical Inc. expanded its U.S. premixed portfolio with a Heparin Sodium 25,000 Units in 0.45% Sodium Chloride bag in mid-2025, following an earlier launch of a domestically manufactured Heparin Sodium 2,000 units in 0.9% Sodium Chloride Injection in early 2024. These moves reflect a broader push toward ready-to-administer hospital solutions and domestic manufacturing options. In a complementary clinical direction, CorMedix Inc. announced the inpatient commercial availability of DefenCath, a taurolidine and heparin catheter lock solution designed to reduce catheter-related bloodstream infections in hemodialysis patients, signaling product innovation at the intersection of anticoagulation and device-related infection control. Meanwhile, Bioiberica S.A.U. celebrated its 50th anniversary with a refreshed brand identity and continued exploration of innovative heparin applications through global research partnerships, while its earlier joint venture with Vall Companys, the Biovall Heparin Science partnership, committed meaningful investment toward sustainable crude heparin production using porcine intestinal mucosa co-products.
The report situates these developments within a wider competitive logic. It examines how formulation expansion, domestic manufacturing, infection-control adjuncts, and sustainable API initiatives alter buyer negotiation dynamics and regional availability. Readers gain a structured view of which moves are likely to influence hospital formulary decisions, which are primarily positioning signals, and where supplier diversification or partnership opportunities may emerge.
Market Dynamics: Supply Chain, Regulation, and the Risk Landscape
Any credible heparin strategy must account for the forces that can rapidly alter cost structures and availability. The strongest of these is raw material concentration. Porcine intestinal mucosa remains the primary source of heparin, and China supplies an overwhelming share of global crude heparin. This concentration creates a market that is efficient under stable conditions but highly exposed when livestock disease, export policy, or trade friction intervenes. African Swine Fever outbreaks have historically demonstrated how quickly porcine supply disruptions can translate into price volatility, prompting the industry to explore diversification through bovine sources and biosynthetic or semi-synthetic alternatives.
Geopolitical and trade dynamics compound this exposure. Reliance on concentrated sourcing channels leaves buyers vulnerable to export controls, tariff adjustments, and logistics disruptions. For hospitals, distributors, and manufacturers, the practical challenge is not only identifying backup suppliers but also verifying that alternate sources meet stringent quality expectations without introducing compliance risk or prohibitively high switching costs.
Regulatory oversight adds another layer of discipline. Major health authorities maintain rigorous standards for heparin quality, including adherence to monographs and enhanced emphasis on traceability and contamination prevention in animal-derived APIs. These requirements raise the operational bar for suppliers and increase the importance of documented chain-of-custody, process control, and testing integrity. In practice, compliance readiness can function as a competitive advantage, particularly when buyers are evaluating suppliers under supply-stress conditions.
On the product side, heparin remains subject to periodic recalls or conservation protocols where endotoxin contamination risks or supply tightness emerge. Historical episodes have shown how quickly availability concerns can affect hospital procurement and clinical workflow. As a result, prudent teams are increasingly embedding contingency planning, dual sourcing, and demand smoothing into their heparin procurement strategies rather than treating availability as a given.
How to Use This Research for 2026 Decision-Making
The strategic value of this report lies in its ability to convert market complexity into actionable orientation. For 2026 planning, teams can use the analysis to:
- Calibrate volume and revenue assumptions using a growth trajectory anchored in historical behavior and forward forecasts, while adjusting for supply-side sensitivities.
- Evaluate where type and application dynamics will create margin opportunity, substitution risk, or pricing negotiation leverage.
- Assess regional exposure and identify where import dependency or concentrated sourcing increases vulnerability, then align sourcing strategies accordingly.
- Benchmark competitor activity, including premixed formulation launches, domestic manufacturing moves, infection-control adjuncts, and API sustainability partnerships, to anticipate changes in hospital and institutional purchasing behavior.
- Build regulatory and quality narratives that support supplier qualification, internal compliance readiness, and risk communication with clinical stakeholders.
- Develop scenario plans that connect raw material concentration, disease-event risk, and regulatory trends to inventory buffers, contract structures, and alternative sourcing roadmaps.
The study is designed to be referenced, not just read. Sections can be extracted for procurement reviews, commercial planning sessions, regulatory briefings, and board-level strategic updates. By keeping the analysis tied to operational decisions rather than abstract market descriptions, the report helps organizations convert intelligence into execution.
What You Will Find in the Full Report
The complete Worldwide Medical Heparin Market research delivers the detailed segmentation frameworks, competitive profiles, regional demand structures, and supply chain diagnostics needed to support multi-year planning with precision. Because many of the actionable figures, internal breakdowns, and company-specific strategic readouts require close examination, the full document provides the granularity that an executive overview cannot. Readers seeking complete quantitative segmentation, detailed company analysis, and region-specific procurement implications will find those materials structured for direct use in budgeting, sourcing, and product strategy discussions.
For teams preparing for the 2026 operating environment, this research offers a defensible basis for assumption-setting, risk identification, and opportunity prioritization. The broader market trajectory points to continued expansion, but the real strategic work lies in managing the forces that determine whether growth is captured efficiently or eroded by supply, pricing, and compliance pressures. The full report is built to give decision-makers the clarity required to act on that reality.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Heparin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Medical Film Equipment Market Hits $2.2B in 2025, Projects 3.65% CAGR to 2032
By pmarketresearch, 2026-09-17
Strategic Intelligence for the Worldwide Medical Film Equipment Market: Navigating Growth Amidst Transition
The global medical film equipment sector stands at a critical juncture where legacy imaging technologies intersect with evolving digital workflows and regulatory frameworks. For executives, investors, and strategic planners operating in healthcare imaging, understanding this landscape requires more than surface-level metrics—it demands a granular, actionable intelligence framework that connects macro trends to segment-level realities. Our newly released Worldwide Medical Film Equipment Market report delivers precisely that. Designed for decision-makers operating in 2026, this study translates historical performance, forward-looking projections, and competitive dynamics into a strategic roadmap. The market has demonstrated measurable resilience and expansion over the past half-decade, culminating in a 2025 revenue baseline of 2,195.99 million USD. With a forecasted compound annual growth rate of 3.65 percent spanning the 2026 to 2032 projection window, the trajectory points toward sustained, though carefully paced, expansion. By the end of 2032, cumulative market revenues are projected to approach 2.82 billion USD, underscoring the enduring relevance of radiographic imaging hardware, consumables, and digitization workflows even as digital modalities continue to reshape clinical environments.
Why This Report Matters for 2026 Decision-Making
Healthcare procurement leaders, imaging equipment manufacturers, and diagnostic service providers face a unique set of pressures in 2026. Supply chain volatility, evolving reimbursement structures, and the gradual but uneven pace of digital transition in imaging departments all influence capital allocation and product strategy. This report is structured to cut through noise and deliver decision-grade insight. It begins by anchoring historical performance across the 2020 to 2025 baseline period, where the market navigated post-pandemic recovery, raw material cost fluctuations, and incremental shifts in imaging department purchasing behavior. The historical record reveals how revenue levels climbed from 1,822.4 million USD in 2020 to 2,195.99 million USD in 2025, reflecting both volume adjustments and pricing dynamics driven by input cost pressures and sustained demand in specific imaging workflows.
From there, the forecast horizon 2026 through 2032 is modeled with scenario-aware granularity. Rather than presenting a single linear projection, the study maps how segment mix, regional adoption patterns, and regulatory developments will shape revenue realization across the forecast window. The 3.65 percent CAGR is not merely a headline figure; it is the output of a structured analytical framework that accounts for product lifecycle dynamics, substitution effects, and pockets of sustained analog demand in facilities where digital infrastructure remains incomplete or financially constrained. Decision-makers will find value in how the report ties these projections to real-world operational levers: pricing strategy, service contract positioning, consumablesbundling, and capital equipment lifecycle planning.
Core Report Architecture and Actionable Coverage
The study is engineered for immediate applicability. Rather than staying at the level of aggregate trends, it decomposes the market into analytically distinct dimensions that map directly to commercial and operational planning cycles.
-
Product and Technology Segmentation: The report evaluates hardware and consumable categories across dry medical printers, laser medical imagers, and medical film digitizers. Each category is assessed for demand drivers, pricing elasticity, replacement cycles, and integration pathways with existing radiographic workflows. This enables readers to pinpoint where margin expansion opportunities exist, where competitive intensity is highest, and how digitization hardware is reshaping the value chain for traditional film-based imaging.
-
Application Pathways: Diagnostic imaging deployments are analyzed across radiology and diagnostic imaging, mammography, orthopedics, and dental imaging. For each application, the study examines clinical workflow dependencies, procurement cycles, and the extent to which analog film remains embedded in departmental routines. This application-level view is particularly useful for manufacturers aligning product roadmaps and for distributors tailoring channel strategies to specific specialty segments.
Industrial X-ray Film Market -
Regional Intelligence: The analysis provides a structured regional view that captures how market maturity, healthcare infrastructure development, and procurement practices influence revenue distribution. Rather than offering blunt geographic rankings, the report contextualizes regional performance within broader healthcare investment patterns and imaging modality adoption curves, allowing readers to assess where near-term growth is most actionable and where long-term positioning requires patience and partnership development.
-
Competitive Positioning and Benchmarking: A dedicated competitive section profiles key players and maps strategic behaviors across product portfolios, regulatory engagement, and pricing maneuvers. This is complemented by concentration metrics that reveal how market share is distributed among leading participants, giving stakeholders a clear sense of where barriers to entry sit and where consolidation or partnership opportunities may emerge.
-
Regulatory and Reimbursement Context: The study integrates device classification considerations, premarket notification expectations, and the role of existing diagnostic imaging reimbursement frameworks in sustaining certain analog workflows. By connecting regulatory structure to commercial reality, the report helps teams anticipate compliance burdens, evaluate market access pathways, and understand why specific product categories retain traction even as digital alternatives expand.
Competitive Landscape: Players, Moves, and Structural Dynamics
The worldwide medical film equipment market is characterized by a concentrated but diversified competitive field. Market concentration metrics indicate that leading participants collectively command a substantial share of revenue, with the top three competitors accounting for approximately 62.45 percent and the top five reaching roughly 78.12 percent. This concentration reflects the entrenched position of established imaging suppliers, the capital intensity of product development and regulatory compliance, and the reliance of many imaging departments on familiar consumables and processing ecosystems. Yet the competitive environment is not static. Strategic moves, regulatory milestones, and raw material cost volatility continue to reshape how players compete on price, performance, and service.
Among the central participants, Agfa-Gevaert stands out for its long-standing portfolio of medical X-ray films and radiographic imaging films serving diagnostic facilities globally. Its market presence is reinforced by continuous engagement with clinical workflows and a supply footprint that supports recurring consumables demand. Fujifilm Holdings Corporation complements this landscape with medical X-ray films and digital imaging X-ray film offerings, alongside related consumables designed for radiographic applications. The company's integration of imaging technology heritage with consumables strategy positions it as a significant force in segments where image quality consistency and processing reliability are paramount. Carestream Health contributes a focused set of radiographic films and X-ray film processing solutions tailored for medical imaging departments, emphasizing workflow compatibility and support infrastructure. Konica Minolta maintains a strong position in medical X-ray film manufacturing and supports traditional radiographic imaging systems, serving facilities that continue to rely on established film-based processes.
Beyond the core imaging film manufacturers, the competitive field includes suppliers whose materials and processing technologies indirectly shape the ecosystem. Tekra, LLC specializes in medical-grade polyester, polycarbonate, COC, and PMMA films used in diagnostic testing and medical device components, linking film material innovation to broader diagnostic applications. Berry Global Inc. produces medical films and flexible materials suitable for healthcare packaging and device applications, reflecting the adjacent demand streams that influence film material supply dynamics. Dürr Dental manufactures dental and medical X-ray film processors, including automatic processors such as Periomat Plus, anchoring its position in processing hardware that supports film-based imaging workflows. Dunmore Corp. supplies specialized coated and laminated films for medical applications, adding further depth to the materials and coatings dimension of the marketplace.
Competitive dynamics in 2025 and 2026 have also been influenced by notable regulatory and commercial developments. In March 2026, Agfa HealthCare announced a price increase for medical X-ray film, attributed to rising input costs. This move highlights how raw material economics and production cost pressures can translate directly into pricing strategy, with potential ripple effects across procurement budgets and substitution decisions. At the same time, regulatory updates continue to clarify the boundaries of film-based imaging within broader device ecosystems. In November 2025, Adaptix Limited received FDA 510(k) clearance for its Ortho350 system as a radiographic imaging system, an event noted in the context of film marking and related radiographic equipment. In January 2025, Ziehm Imaging GmbH secured FDA 510(k) clearance for its imaging system, with device specifications explicitly noting that the system does not support direct radiographic film exposures. These developments illustrate how regulatory clearances increasingly reflect a market where digital and film-based pathways coexist but diverge in design intent, reinforcing the importance of understanding exactly where film equipment fits within each clinical and procurement context.
Market Dynamics Shaping the 2026 to 2032 Window
Several structural forces will determine how revenue evolves across the forecast period. First, raw material cost trends remain a persistent consideration. Rising silver costs have historically driven increases in medical X-ray film pricing, influencing production economics for silver-halide based radiographic films. Pricing decisions by leading suppliers will continue to interact with procurement sensitivity, particularly in price-regulated or budget-constrained settings. Second, reimbursement practices and departmental budgeting continue to support traditional analog radiographic film usage in settings without full digital transition. Existing hospital radiology budgets and CPT coding for diagnostic imaging procedures provide ongoing financial pathways that sustain demand for certain film-based workflows, even as digital infrastructure expands elsewhere.
Third, device regulation adds both structure and complexity. Radiographic film is classified by the FDA as a Class I or II device under product code IWZ with regulation 892.1840, subject to general controls and certain exemptions from 510(k) and GMP requirements. Automatic radiographic film processors are regulated under FDA 892.1900 as Class II devices requiring premarket notification in many cases. These classification frameworks shape development timelines, compliance responsibilities, and market entry strategies for both incumbents and new entrants. At the same time, the growing orientation of certain C-arm and fluoroscopic systems toward digital imaging workflows means that film compatibility is no longer a default assumption. Buyers increasingly evaluate equipment not only on image quality but also on integration with existing digital ecosystems, service availability, and consumables economics over the full equipment lifecycle.
Worldwide Medical Film Equipment Market
Fourth, digitization hardware and conversion technologies introduce a distinct value layer. Medical film digitizers and related conversion workflows create opportunities for facilities that must manage archival film, transition legacy studies, or maintain compatibility with hybrid imaging environments. The extent to which digitization adoption accelerates will depend on capital availability, internal IT readiness, and the perceived cost-benefit balance relative to full digital replacement. In this context, the market's measured CAGR reflects a landscape where growth is real but uneven, with some categories expanding on the back of replacement cycles and consumables demand, while others evolve more slowly as digital substitution progresses.
What the Report Reveals—and What It Reserves for Subscribers
This introduction is intentionally structured to demonstrate analytical rigor while preserving the full granularity of the dataset for clients who need to act on it. What we can share publicly is that the study provides a coherent view of how the market has evolved from 2020 through 2025, how it is projected to unfold through 2032, and how competitive, regulatory, and materials-driven forces interact across product types, application areas, and regional contexts. What remains within the full report are the segment-level revenue splits, detailed regional breakdowns, precise category allocations across types and applications, and the supporting methodology that allows subscribers to test assumptions, benchmark positioning, and build internal forecasts with confidence. Those details matter because strategic decisions rarely hinge on aggregate market size alone. They depend on knowing where demand is most durable, which product categories are most exposed to input cost volatility, how competitive concentration shapes pricing freedom, and where regional dynamics create openings for targeted expansion or partnership.
For organizations planning 2026 investment, procurement strategy, product roadmap adjustments, or market entry evaluations, this report is designed to serve as a decision infrastructure. It connects historical evidence to forward-looking scenarios, embeds regulatory and reimbursement context into commercial interpretation, and maps the competitive field in enough detail to support positioning decisions without resorting to generic industry commentary.
Who Should Use This Study and How
This report is built for cross-functional use. Commercial leaders can leverage it to align pricing, channel, and service strategies with segment-level demand realities. Product and technology teams can use it to prioritize development and integration work where workflow fit and replacement cycles create the strongest pull. Procurement and supply chain planners can apply its insights to anticipate cost pressure points, evaluate consumables bundling opportunities, and structure contracts that reflect likely pricing behavior in response to materials cost trends. Investor and corporate strategy teams can draw on the forecast architecture and concentration analysis to assess growth durability, competitive moats, and the extent to which legacy imaging segments will continue to contribute meaningfully to revenue pools over the next several years.
The study is also designed to be actionable for organizations operating across different levels of digital maturity. In markets and facilities where analog radiographic film remains embedded in routine diagnostic workflows, the report clarifies the economic and regulatory factors that sustain demand and the pricing dynamics that influence procurement decisions. In settings where digital transition is more advanced, it provides a framework for understanding how film-related equipment, consumables, and digitization hardware fit into hybrid environments and transitional procurement strategies. In both cases, the goal is the same: to enable decisions grounded in evidence rather than assumption.
Access the Full Intelligence
The Worldwide Medical Film Equipment Market report offers a complete, segment-resolved view of market size, growth trajectory, competitive positioning, and operational context across the 2026 to 2032 forecast window. It is built for teams that need more than directional insight and less than static data tables—decision-makers who want a structured, defensible basis for planning in a market where legacy technologies, digital transition, and regulatory and materials dynamics all interact at once. To access the full segmentation data, regional detail, competitive benchmarking, and supporting forecast architecture, download the complete report through our official research portal. The macro trajectory is clear; the strategic implications are in the details.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Film Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Aircraft Wind Tunnel Testing Market to Hit $929.95M by 2032 with 5.25% CAGR
By pmarketresearch, 2026-09-17
Strategic Imperatives in Aircraft Wind Tunnel Testing Services: A 2026 Market Perspective
The global aerospace industry stands at a critical inflection point. As aircraft design philosophies evolve toward unconventional configurations, hypersonic mission profiles, and sustainable propulsion architectures, the dependency on empirical aerodynamic validation has never been more pronounced. Wind tunnel testing remains the indispensable bridge between computational simulation and certified flight reality. Against this backdrop, the Aircraft Wind Tunnel Testing Services Market is projected to demonstrate a compound annual growth rate of 5.25% across the forecast horizon, with total market revenue climbing from an estimated 650.0 million USD in the base year to approximately 929.95 million USD by 2032. This trajectory is not merely a reflection of incremental capacity expansion; it signals a structural realignment of how aerospace OEMs, defense contractors, and emerging mobility developers approach aerodynamic certification, performance optimization, and risk mitigation.
For executive teams, capital allocators, and program managers navigating the 2026 decision cycle, understanding the underlying mechanics of this market is no longer a peripheral analytical exercise. It is a strategic prerequisite. The following analysis outlines the macro-financial contours, competitive architecture, regulatory pressures, and technological catalysts that define the current testing services landscape. While high-level indicators illuminate the direction of travel, the granular segmentation, regional demand distribution, and service-type valuation multipliers that truly inform procurement strategy, partnership selection, and capacity planning are explored in depth within our latest market intelligence publication.
Aircraft Wind Tunnel Testing Services Market
Macro Trajectory and Capital Allocation Signals
The historical progression from 2020 through 2025 reveals a market that has consistently outperformed baseline industrial growth expectations. Revenue expanded from 503.27 million USD to 650.0 million USD, demonstrating resilient demand even amid broader supply chain disruptions and shifting defense procurement cycles. The forward forecast period from 2026 through 2032 continues this upward arc, crossing the 700.0 million USD threshold in 2027 and approaching the 900.0 million USD mark by the end of the decade. This expansion is underpinned by several mutually reinforcing dynamics: the proliferation of clean-sheet aircraft programs, the re-emergence of high-speed aerodynamic research, and the operational necessity of validating novel airframe geometries that fall outside legacy certification playbooks.
However, raw growth figures alone do not dictate investment logic. The market's structural economics are defined by formidable infrastructure barriers. Constructing a large transonic wind tunnel facility requires capital expenditure exceeding 500 million USD, accompanied by sustained operational overhead, specialized workforce requirements, and continuous calibration demands. This cost architecture naturally concentrates market activity among established operators with long amortization horizons and entrenched client relationships. For organizations evaluating external testing partnerships, capacity reservations, or strategic service integrations, the distribution of spend across service categories, aircraft platforms, and geographic testing hubs becomes a decisive variable. These allocation patterns, along with the precise revenue weighting of each segment, are mapped in full within our comprehensive report.
Competitive Architecture and Facility Specialization
The testing services ecosystem is characterized by a blend of independent specialists, state-aligned research organizations, and OEM-affiliated testing divisions. Industry concentration metrics indicate a moderately consolidated landscape, with the top three operators accounting for 45.5% of market share and the top five capturing 62.2%. This concentration reflects both the technical moat inherent in large-scale aerodynamics testing and the long-cycle nature of aerospace program commitments. Yet within this consolidated framework, competitive differentiation remains highly nuanced, driven by test section dimensions, Mach regime coverage, instrumentation sophistication, and program management capabilities.
Calspan Corporation operates a prominent transonic testing capability centered on an 8 ft × 8 ft test section extending to Mach 1.3, complemented by turn-key model manufacturing, positioning systems, balance integration, and calibration services tailored to aerospace programs. The Aircraft Research Association Limited (ARA) functions as an independent specialist delivering comprehensive wind tunnel services, including transonic tunnel operations designed for advanced aircraft concepts and next-generation aerospace configurations. Boeing Testing Services leverages a multi-facility portfolio encompassing the Transonic Wind Tunnel (BTWT), polysonic, subsonic, and icing tunnels, enabling customized aerodynamic, propulsion, and acoustic validation for complex aircraft programs. DNW (German-Dutch Wind Tunnels) provides advanced testing across subsonic to supersonic regimes, with specialized sites such as Marknesse supporting takeoff and landing configuration analysis alongside emerging rotorcraft and hydrogen-electric platform validation.
ONERA's Modane-Avrieux center operates six facilities capable of aerodynamic testing up to hypersonic speeds, supporting both civil and military aircraft development trajectories. RUAG Aerodynamics offers a large low-speed wind tunnel (LWTE) alongside complementary infrastructure, delivering end-to-end support spanning model design, instrumentation, testing, and full development cycle integration. AeroTEC specializes in the design, fabrication, instrumentation, and testing of complex wind tunnel models, with program management woven into its service delivery model. Lockheed Martin maintains low-speed and high-speed wind tunnel assets dedicated to aerodynamic force and moment characterization, store separation analysis, propulsion integration, and dynamic stability evaluation for aircraft and missile systems. Meanwhile, the privately operated San Diego Wind Tunnel (LSWT|SD) focuses on low-turbulence subsonic testing for scaled jet aircraft, unmanned platforms, and specialized aerospace applications.
Evaluating which provider aligns with a given program requires more than facility comparison. It demands an understanding of lead-time pipelines, instrumentation compatibility, data processing methodologies, and contractual flexibility under multi-phase testing schedules. The competitive positioning matrix, service differentiation themes, and recent capability upgrades that shape vendor selection are unpacked in detail within our market study.
Regulatory Mandates and Certification Economics
Physical wind tunnel validation is not optional in modern aerospace certification pathways. Regulatory authorities including the FAA, EASA, and CAAC mandate empirical aerodynamic validation through physical testing as a condition of type certification and ongoing airworthiness compliance. As aviation safety and performance criteria continue to tighten under evolving regulatory frameworks, the volume and complexity of required test campaigns have expanded accordingly. This regulatory floor creates a baseline demand that is relatively insulated from short-term economic volatility, while simultaneously raising the technical bar for testing service providers.
For program planners, the certification dimension introduces two strategic realities. First, test campaigns must be sequenced early enough to inform design iterations without triggering costly late-stage rework. Second, the data packages submitted for certification must withstand rigorous regulatory scrutiny, making instrumentation accuracy, repeatability, and documented calibration histories critical procurement criteria. Organizations that treat wind tunnel engagement as a transactional service rather than an integrated certification strategy often encounter schedule compression, data reconciliation challenges, and elevated compliance risk. The interplay between regulatory timelines, testing scope definition, and cost optimization is a recurring theme in our analysis, and readers seeking actionable frameworks for certification-aligned testing planning will find structured guidance in the full report.
Technology Drivers and Emerging Demand Vectors
The demand profile for wind tunnel testing services is being reshaped by several convergent technology trends. Hypersonic research programs are driving intensified utilization of transonic and supersonic facilities, as mission profiles push beyond conventional subsonic envelopes. Simultaneously, sustainable aviation objectives are accelerating testing around sustainable aviation fuel (SAF) compatibility, blended wing body configurations, truss-braced wing architectures, and alternative propulsion integration. These programs often require specialized model articulation, cryogenic or high-energy flow conditions, and advanced measurement techniques that strain legacy facility configurations.
Climatic Wind Tunnel Market
Recent industry activity underscores this shifting demand mix. In February 2026, Calspan Corporation was awarded a five-year contract with the U.S. Naval Test Pilot School for flight and related testing services, reinforcing long-cycle institutional demand for integrated aerodynamic and flight test support. Also in February 2026, DNW opened an Automotive Test Section at Marknesse while conducting helicopter rotor active twist testing and contributing to Beyond Aero hydrogen-electric aircraft evaluations, illustrating how established facilities are expanding into adjacent mobility and clean-propulsion domains. In December 2025, the Aircraft Research Association completed the design, fabrication, and testing of the SWiFT research wind tunnel model in its Transonic Wind Tunnel, highlighting continued investment in research-grade aerodynamic instrumentation and scaled concept validation. Earlier, in October 2025, Calspan's Transonic Wind Tunnel was featured for successful test system modernization, signaling ongoing capability upgrades that extend facility relevance across new test regimes. More recently, in May 2026, NASA and Boeing completed wind tunnel tests on a truss-braced wing concept for advanced aircraft design within the QinetiQ facility, demonstrating how collaborative testbed access supports high-visibility advanced configuration programs.
These developments are not isolated milestones; they are indicators of a market moving toward higher-complexity test articles, multi-disciplinary data capture, and cross-sector facility utilization. The precise allocation of testing demand across speed regimes, platform categories, and emerging application areas is detailed in the report's segmentation analysis, where service-level and platform-level revenue distributions provide a clearer picture of where capacity constraints and pricing dynamics are most pronounced.
Strategic Decision Frameworks for 2026 and Beyond
For aerospace manufacturers, defense prime contractors, emerging mobility developers, and testing service providers themselves, the 2026 landscape presents both opportunity and operational complexity. Organizations must decide how to balance in-house testing assets against external service partnerships, how to sequence model fabrication and instrumentation investments alongside tunnel availability, and how to structure contracts that accommodate iterative design changes without eroding margin or schedule integrity. Facilities operators, meanwhile, face the challenge of modernizing instrumentation suites, expanding hypersonic and sustainable-aviation test capabilities, and maintaining competitive positioning in a market where capital intensity limits new entry.
The strategic questions that matter most cannot be answered by headline market size alone. They require a disciplined assessment of segmentation dynamics, regional demand intensity, service-type pricing structures, and the evolving capability gaps among leading providers. They also require visibility into recent contract awards, facility modernization timelines, and collaborative testing arrangements that signal where capacity is tightening and where new access pathways are emerging. Our latest Aircraft Wind Tunnel Testing Services Market research is designed to provide that visibility. It translates macro-financial indicators into operational intelligence, maps competitive positioning against actual program requirements, and identifies the structural factors that will shape procurement strategy, partnership selection, and capacity planning through 2032.
The full study contains the segmented revenue breakdowns, regional demand distributions, service-type and aircraft-type market splits, concentration analysis, and provider-specific capability assessments that executives and analysts need to build defensible strategies. To access the complete dataset, detailed segmentation tables, competitive profiles, and forward-looking scenario analysis, we invite you to explore the full report through our official research portal. In a market defined by high infrastructure barriers, stringent certification requirements, and accelerating technological ambition, precision intelligence is not an advantage; it is the foundation of sound 2026 decision-making.
For detailed analysis of this topic, please visit the official page: Aircraft Wind Tunnel Testing Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Nacelle Test Rig Market to Reach $908M in 2025, Growing at 6.1% CAGR Through 2032
By pmarketresearch, 2026-09-17
The Nacelle Test Rig Market in 2026: Strategic Intelligence for Next-Gen Wind Energy Investments
Executive Overview
The nacelle test rig market stands at a critical inflection point in 2026. As wind turbine architectures push toward larger rotor diameters, higher capacity ratings, and increasingly complex drivetrain configurations, the infrastructure required to validate these systems under realistic operational conditions has evolved from a niche engineering requirement to a foundational pillar of global wind energy deployment. Our latest Nacelle Test Rig Market research study is designed to equip executives, project developers, testing facility operators, and equipment manufacturers with the analytical clarity needed to navigate this rapidly maturing landscape.
This article serves as a strategic preview of the full report. It outlines the macro trajectory of the market, highlights the operational and regulatory forces shaping procurement and facility planning, and maps the competitive architecture that defines today’s testing ecosystem. In keeping with a trailer-style approach, we surface the methodological depth and actionable frameworks contained in the study while reserving granular segmentation breakdowns, regional allocation matrices, and company-level revenue benchmarks for the complete publication. Decision-makers who require precise allocation models, scenario-based forecasting, and vendor capability comparisons will find the full report structured to support board-level strategy, capital budgeting, and partnership evaluation.
Market Trajectory and Growth Architecture
The market has demonstrated consistent expansion across the historical review window, with global revenue climbing from approximately $612 million in 2020 to an estimated $908 million by 2025. This growth trajectory reflects a compounding set of tailwinds: accelerated turbine upscaling, tighter certification timelines, and the strategic imperative to de-risk performance before field installation. Looking forward, the forecast period through 2032 projects a compound annual growth rate of 6.1 percent, signaling a market that is not merely expanding in absolute terms but also maturing in its testing methodologies, geographic distribution, and application diversity.
The forward revenue path does not follow a straight line. The forecast model captures the natural cadence of capital deployment cycles, the staggered commissioning of large-scale test facilities, and the periodic recalibration of testing demand as turbine platforms move through prototype, pre-series, and commercial validation phases. By embedding these dynamics into a structured scenario framework, the study enables stakeholders to distinguish between baseline growth, downside risk from supply chain or permitting delays, and upside potential driven by offshore program acceleration or new certification mandates.
It is important to note that the aggregate figures presented here are deliberately high-level. The complete report decomposes the market by region, test rig type, and application vertical, providing the granular revenue splits and growth differentials that procurement leaders and strategy teams require for capacity planning and market entry decisions. Those segmentation details are surfaced within the full intelligence package, where they are cross-referenced with facility utilization trends, lead-time dynamics, and regional certification timelines.
Structural Drivers Shaping 2026 Decision-Making
Several interconnected forces are redefining how testing capacity is specified, justified, and deployed in 2026. The most consequential among them is turbine upscaling. As drivetrain architectures are engineered for higher torque loads and multi-megawatt output classes, test rigs must accommodate expanded motor drive systems, advanced wind load application units, and high-fidelity grid simulation capabilities. The testing envelope is no longer limited to functional verification; it must span endurance validation, extreme load simulation, and electrical certification under grid code conditions.
Regulatory and certification requirements reinforce this technical trajectory. Nacelle test rigs play an integral role in demonstrating compliance with grid code mandates and industry standards such as IEC 61400-21 and FGW TR3. For original equipment manufacturers and independent test houses alike, the ability to generate certified, repeatable test data directly influences time-to-market, warranty exposure, and the credibility of performance guarantees. In an environment where certification delays can cascade into project finance timelines and offshore installation windows, testing infrastructure becomes a strategic asset rather than a back-office function.
A second structural driver is the material and domestic content profile of nacelle assembly. Wind turbine nacelles require substantial steel and cast iron inputs for critical components, and in key markets such as the United States, domestic content for nacelle assembly exceeds 80 percent. This supply chain reality intersects with testing strategy in two ways. First, it heightens the importance of localized validation for components and subsystems intended for regionally assembled turbines. Second, it increases the strategic value of test facilities that can support domestic manufacturing roadmaps, supplier qualification programs, and content compliance documentation.
Finally, the market is being shaped by the growing differentiation between onshore and offshore testing demands. Offshore platforms impose more stringent validation requirements around corrosion environments, grid stability, maintenance access, and system reliability under variable offshore conditions. This divergence is expanding the scope of test rig specifications and encouraging operators to design multi-purpose facilities that can pivot between onshore and offshore validation protocols. The full report examines how these application and type-level dynamics influence capacity allocation, equipment configuration, and long-term utilization forecasts.
Competitive Landscape and Strategic Positioning
The competitive architecture of the nacelle test rig ecosystem is characterized by a mix of specialized system integrators, research-driven test laboratories, and manufacturer-operated validation centers. Market concentration remains moderately high, with the top three players accounting for approximately 58.7 percent of market revenue and the top five expanding that share to roughly 72.4 percent. This concentration reflects the technical complexity of high-capacity test systems, the capital intensity of facility development, and the importance of established certification relationships in winning repeat engagements.
Several organizations illustrate the breadth of strategic positioning within the market. RENK Test Systems, based in Augsburg, Germany, provides nacelle test rigs featuring expandable multi-motor drive systems capable of reaching 35 MW, alongside wind load application units and grid simulators that support development, quality assurance, endurance, and extreme load testing. R&D Test Systems, located in Hinnerup, Denmark, specializes in highly accelerated lifetime testing rigs and has developed one of the largest HALT XL test benches, with a 25 MW drive motor designed for offshore nacelle testing. Fraunhofer IWES, operating in Bremerhaven, Germany, runs the Dynamic Nacelle Testing Laboratory, known as DyNaLab, which enables realistic multi-megawatt nacelle testing and supports electrical certification through HiL-GridCoP capabilities. ZF Wind Power, headquartered in Lommel, Belgium, operates a 30 MW drivetrain and powertrain test rig at its Test and Prototype Center to validate onshore and offshore wind turbine systems. Calspan, based in Buffalo, New York, supplies engine test nacelle equipment including bellmouths, cowlings, and boat tails for aircraft engine testing, with licensed applications across CFM and Rolls-Royce engines.
While these companies differ in scope and end-use orientation, they collectively demonstrate the market’s movement toward higher power classes, broader simulation fidelity, and more integrated certification support. The study goes beyond corporate profiles to evaluate competitive dynamics through a structured lens: technology roadmaps, facility scalability, service attachment rates, and the strategic value of long-term testing partnerships. Understanding how these players differentiate themselves is essential for organizations evaluating vendor selection, co-development opportunities, or the feasibility of in-house test capability versus third-party outsourcing.
Recent Developments and Facility Investment Signals
Recent facility announcements and contract awards provide a real-time read on how the market is deploying capital and expanding testing capacity. In April 2025, ZF Wind Power commissioned a 30 MW drivetrain test rig at its Test and Prototype Centre in Lommel, Belgium, designed to validate full powertrain systems for both onshore and offshore wind turbines. This commissioning reflects the broader industry trend of increasing test capacity in step with turbine platform scaling and the need for integrated drivetrain validation before commercial rollout.
In February 2025, ORE Catapult appointed RENK Test System GmbH to design, manufacture, and install a new drive train test rig at its Blyth facility, initially capable of testing up to 23 MW. This engagement underscores how public-private and research-oriented testing infrastructure is being upgraded to support next-generation drivetrain validation and to provide regional testing access for developers and manufacturers. Taken together, these developments illustrate a market in which test capacity expansion is being aligned with immediate technology needs while also creating headroom for future higher-capacity platforms. The complete report places such events within a wider deployment timeline, allowing readers to assess the cumulative impact of new rigs, retrofits, and facility upgrades on regional testing availability and utilization patterns through 2032.
Report Framework and Operational Contents
The full Nacelle Test Rig Market study is built to support practical, multi-functional decision-making. It combines macro market modeling with operational content that strategy, engineering, procurement, and finance teams can apply directly to planning cycles. The report framework is organized to move from high-level market architecture to actionable detail, ensuring that readers can extract both strategic context and execution-oriented intelligence.
- Macro market sizing and forecast modeling across the historical review window and the 2026 through 2032 forecast period
- Segmentation analysis covering region, test rig type, and application, with qualitative commentary on growth differentials and demand drivers
- Competitive profiling of core participants, including technology capabilities, facility footprints, and strategic positioning within the testing value chain
- Market concentration assessment and implications for vendor negotiation, partnership structuring, and capacity risk management
- Regulatory and standards context, including the role of test rigs in grid code compliance, IEC 61400-21 alignment, and FGW TR3 certification support
- Recent deployments and contract activity that signal near-term capacity expansion and testing demand shifts
- Scenario-based outlooks that help decision-makers stress-test assumptions around turbine scaling, offshore program timing, and certification requirements
This structure is intentionally designed to serve multiple audiences. Executive teams can use the macro framing and competitive assessment to guide investment priorities and partnership strategy. Engineering and testing leaders can draw on the type- and application-level discussion to inform rig specification, validation scope, and facility planning. Procurement and supply chain professionals can leverage the concentration analysis and recent development tracking to benchmark vendor options and anticipate capacity constraints. Across all functions, the report aims to convert market complexity into a usable strategic map.
How to Use This Intelligence in 2026
As wind energy portfolios scale and turbine platforms become more demanding, the cost of testing uncertainty rises. Facilities that cannot accommodate higher power classes, simulate realistic grid and load conditions, or produce certification-grade data risk becoming bottlenecks in product development and project execution. At the same time, organizations that invest in the right testing capabilities or partnerships can accelerate validation cycles, strengthen performance credibility, and improve alignment with regional content and compliance expectations.
Engine Nacelle Market
The strategic value of this research lies in its ability to help leaders separate signal from noise. The market is large enough to offer opportunity and concentrated enough to require careful vendor and facility evaluation. It is growing steadily, yet subject to periodic resequencing as new rigs come online and testing demand shifts across onshore and offshore programs. By combining historical context, forward-looking modeling, competitive profiling, and regulatory grounding, the report provides a decision-ready foundation for capital allocation, vendor selection, and technology planning.
Conclusion
The nacelle test rig market in 2026 is defined by higher technical thresholds, tighter certification expectations, and a competitive field in which a limited number of players command a substantial share of revenue. The sector’s projected growth path supports continued investment in test capacity, but the practical details of segmentation, regional availability, and vendor capability will determine which organizations capture the most value from that expansion. Our full Nacelle Test Rig Market report is intended to provide those details in a structured, executive-ready format. Readers seeking the complete segmentation breakdowns, concentration analysis, and forward-looking scenario framework are encouraged to access the full study for comprehensive market intelligence and strategic guidance.
Nacelle Test Rig Market
For detailed analysis of this topic, please visit the official page: Nacelle Test Rig Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com