

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global AMC CPU Card Market to Reach $844.22M by 2032 Backed by 8.24% CAGR

Strategic Intelligence for the Next Decade: Inside the Worldwide AMC CPU Card Market
The embedded computing landscape is undergoing a structural transformation. As industries converge around edge intelligence, 5G infrastructure, and mission-critical reliability, the Advanced Mezzanine Card (AMC) CPU segment has emerged as a critical enabler of next-generation system architectures. For executive teams navigating capital allocation, supply chain resilience, and technology roadmapping in 2026, understanding the trajectory of the Worldwide AMC CPU Card Market is no longer optional. It is a strategic imperative.
This article serves as a strategic preview of our latest market research initiative. It outlines the macro-level dynamics shaping the sector, highlights the competitive forces at play, and demonstrates why data-driven clarity in this space will directly influence enterprise decision-making through the end of the decade. The full intelligence package, complete with granular segmentation, regional revenue breakdowns, and forward-looking scenario modeling, is available through our comprehensive report.
The Macro Trajectory: Growth, Acceleration, and Structural Leverage
The market for AMC CPU cards has demonstrated consistent, compounding expansion over the past five years. Historical revenue data from 2020 through 2025 reveals a clear upward trajectory, with the sector surpassing the half-billion-dollar threshold in the base year and continuing to scale into the forecast horizon. Our analysis projects that this momentum will carry the market steadily toward higher valuation tiers through 2032, driven by entrenched demand in telecommunications, defense, and industrial automation.
The compound annual growth rate across the forecast period stands at a robust 8.24 percent, signaling that AMC-based processing architectures are not experiencing a cyclical spike but rather a structural adoption curve. This rate of expansion reflects the widening integration of MicroTCA and ATCA platforms across high-performance edge deployments, where thermal resilience, I/O flexibility, and processor density intersect. For organizations evaluating capacity planning or vendor partnerships, this macro outlook underscores the importance of aligning procurement strategies with a market that is scaling at a pace faster than general-purpose embedded compute segments.
Revenue projections through the end of the forecast window indicate that the market will continue to compound, with incremental year-over-year gains accelerating as next-generation processor architectures gain mainstream deployment in AMC form factors. The implication for enterprise strategists is clear: early positioning in supply agreements, standards-aligned procurement, and platform diversification will likely yield disproportionate competitive advantages as the market matures.
Architecture and Application: Where Value Is Concentrated
The segmentation landscape of the AMC CPU card market is defined by distinct architecture preferences and application-driven demand clusters. Processor architecture remains a foundational axis of differentiation, with x86-based modules commanding the largest share of market revenue, supported by established ecosystem maturity, extensive software compatibility, and broad availability of high-core-count processors. ARM-based architectures follow, reflecting the growing emphasis on power efficiency, edge AI inference, and specialized telecommunications workloads, while PowerPC architectures maintain a strategic presence in environments where long lifecycle support and deterministic processing remain paramount.
On the application side, demand is heavily weighted toward sectors that require ruggedized, high-availability computing fabric. Telecommunications continues to represent the largest application vertical, driven by the deployment of distributed baseband units, edge packet processing, and MicroTCA-based infrastructure modernization. Aerospace and defense follow as a critical adoption zone, where thermal tolerance, extended temperature operation, and compliance with stringent reliability standards make AMC CPU modules a preferred choice for mission systems and tactical communication platforms. Industrial automation and medical computing round out the demand landscape, with automation leveraging the modularity and backplane scalability of AMC architectures, and medical systems increasingly adopting compact, high-reliability compute nodes for imaging, patient monitoring, and diagnostic edge applications.
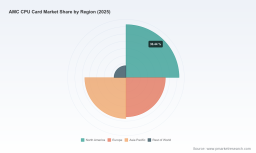
Regional distribution further illustrates the global nature of this market, with North America, Europe, and Asia Pacific each contributing substantial revenue streams. The balance across these regions reflects both mature adoption in established industrial and defense markets and accelerating deployment in Asia Pacific as manufacturing and telecom infrastructure investments expand. The global footprint of demand reinforces the need for multi-region supply chain strategies and localized technical support capabilities.
Competitive Landscape: Established Players and Innovation Velocity
The competitive environment in the AMC CPU card market is defined by a concentrated group of specialized manufacturers that have built deep expertise in MicroTCA and ATCA ecosystems. Market concentration metrics indicate that the top three players account for a notable share of total revenue, while the top five collectively represent a substantial majority of market activity. This concentration reflects the high barriers to entry associated with advanced backplane compliance, thermal design, processor integration, and long-term enterprise support commitments.
Kontron AG has maintained a strong position through its AdvancedMC processor modules, including the AM4010 and AM4022 series, which bring Intel Core processor performance, ECC memory support, and high I/O density to telecom, industrial, and defense applications. VadaTech has similarly expanded its Processor AMC portfolio, offering single- and double-width variants based on Intel Core and Xeon architectures, with a clear emphasis on PCIe, Ethernet, and storage flexibility for MicroTCA environments. Recent product activity from VadaTech, including the introduction of 11th Generation Intel Core i7-based modules with quad-core performance up to 4.4 GHz turbo and the continued expansion of its MicroTCA product line, signals an ongoing commitment to performance upgrades and form-factor versatility.
Worldwide AMC CPU Card Market
N.A.T. Europe has carved out a distinct niche through versatile AMC CPU boards that span both ARM-based and COM Express-enabled designs, such as the NAT-AMC-LX2 with 16-core ARM A72 processors and the NAT-AMC-COMex supporting COM Express Type 7 modules with high-bandwidth backplane connectivity. This dual-architecture approach positions the company to serve deployment scenarios that require either power-efficient ARM processing or Intel-based ecosystem compatibility. EMCOMO Solutions AG has pursued a similarly broad strategy, supplying MicroTCA AMC CPU modules built around Intel Xeon E3, Xeon E5, and Xeon D processors, alongside NXP QorIQ and Cavium-based options, with features including NVMe support, 10GbE connectivity, and industrial temperature ranges. Advantech Corp. rounds out the competitive field with embedded computing solutions that include AMC-compatible modules and network mezzanine cards, targeting industrial, telecom, and edge applications with systems that support high-core Intel Xeon processors.
The competitive dynamics in this space are not solely defined by product portfolios. They are increasingly shaped by the speed at which manufacturers can align with updated standards, integrate next-generation processor families, and maintain supply continuity amid broader semiconductor capacity constraints. Organizations evaluating vendor partnerships must therefore assess not just current module availability, but also roadmap alignment, compliance certification depth, and long-term support commitments.
Industry Dynamics and Supply-Side Pressures
The operational environment for AMC CPU card deployment is being reshaped by several intersecting forces. One of the most consequential developments is the ratification of the MicroTCA.0 Revision 3.0 specification, which introduces 100 GbE and PCIe Gen 5 fabrics, delivering a fourfold performance improvement while expanding thermal design power limits to accommodate higher-performance processors. This standards evolution directly enables more aggressive compute deployments within the same AMC form factor, broadening the addressable use cases for edge and server-adjacent applications and supporting up to 12 slots in demanding configurations.
At the same time, supply-side dynamics are introducing new layers of complexity. TSMC expansion has triggered shortages and price surges for certain filter materials used in wafer manufacturing processes critical to advanced semiconductor production, creating upstream constraints that ripple through CPU and component availability. Concurrently, major processor manufacturers are boosting CPU production capacities amid strong demand, yet lead times for certain CPUs have extended to as long as one year, with pricing continuing to escalate. These supply pressures elevate the strategic importance of forward purchasing, alternative architecture evaluation, and multi-sourcing strategies for organizations that depend on AMC CPU modules for critical deployments.
For enterprise decision-makers, these dynamics create a dual challenge: maintaining performance and reliability targets while managing cost volatility and lead-time uncertainty. The ability to anticipate standards-aligned upgrades, secure supply commitments, and evaluate architecture alternatives will differentiate organizations that can sustain deployment timelines from those that face costly delays.
Inside the Research: What Decision-Makers Will Find
Our Worldwide AMC CPU Card Market research is designed to translate these macro dynamics, competitive forces, and supply-side pressures into actionable intelligence. The report provides a structured, data-rich view of the market across multiple analytical dimensions, enabling teams to evaluate growth opportunities, assess competitive positioning, and align procurement and technology strategies with a rapidly evolving landscape.
The research package includes detailed historical and forecast revenue analysis spanning the full 2020 to 2032 window, offering a clear view of how the market has evolved and where it is headed. Segmentation analysis breaks down revenue and growth trajectories across processor architecture families and application verticals, allowing readers to identify which domains are driving expansion and where demand intensity is expected to intensify. Regional breakdowns provide a global perspective on market distribution, supporting supply chain mapping and geographic prioritization.
Beyond quantitative segmentation, the report delivers a competitive landscape assessment that profiles key manufacturers, outlines their product strategies, and contextualizes recent product launches, standard ratification impacts, and supply chain developments. This section is designed to help organizations benchmark vendor offerings, evaluate roadmap alignment, and understand the strategic implications of recent industry events. The research also incorporates an analysis of market concentration dynamics, highlighting how competitive balance, barriers to entry, and standards evolution are shaping the trajectory of the sector.
Motherboard Market
Operational relevance is a core design principle of the report. Rather than presenting abstract market statistics, the analysis is structured to support concrete decision-making processes, including vendor selection, capacity planning, architecture evaluation, and risk assessment in the face of semiconductor supply constraints. The goal is to provide executive and technical teams with a shared, evidence-based foundation for strategic planning.
Why 2026 Is a Pivotal Year for Strategic Positioning
The convergence of standards modernization, processor architecture evolution, and supply-side volatility makes 2026 a defining year for organizations operating in or adjacent to the AMC CPU card market. MicroTCA.0 Revision 3.0 is opening the door to higher-performance deployments within established form factors, while demand from telecommunications, aerospace and defense, industrial automation, and medical computing continues to expand the addressable market. At the same time, lead-time extensions and material-driven cost pressures are testing the resilience of procurement and deployment strategies.
In this environment, strategic clarity is a competitive asset. Organizations that understand the relative growth intensity of different architectures and applications, that can anticipate the implications of standards evolution, and that have visibility into competitive dynamics and supply constraints will be better positioned to make informed decisions about platform investments, vendor relationships, and deployment roadmaps. The market's projected expansion through 2032 reinforces the long-term nature of this opportunity and the importance of getting strategic positioning right early.
This preview provides a high-level view of the forces shaping the Worldwide AMC CPU Card Market and the strategic value embedded in comprehensive market intelligence. The full research report delivers the detailed segmentation, regional revenue distributions, competitive assessments, and forward-looking analysis needed to translate these insights into concrete action. For teams seeking to navigate the market with precision and confidence in 2026 and beyond, the complete intelligence package offers the depth and structure required to support decisive, evidence-based strategy.
For detailed analysis of this topic, please visit the official page: Worldwide AMC CPU Card Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com