

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Portable pH Meter Market Hits $425.61M in 2025, Projected 5.12% CAGR to 2032

Strategic Intelligence in a Changing Field: Navigating the Worldwide Portable pH Meter Market with PW Consulting
In an era where environmental compliance, food safety, and pharmaceutical quality control demand faster, more accurate, and more mobile measurement tools, the portable pH meter market has evolved from a niche laboratory accessory into a strategically critical segment of the broader instrumentation landscape. Over the past five years, stakeholders across water management, food and beverage production, biotechnology, and environmental testing have recalibrated their procurement strategies, driven by tightening regulatory expectations, supply chain realignment, and a growing appetite for connected, field-ready devices. PW Consulting’s latest worldwide market study is designed not merely as a numerical snapshot, but as a decision-making framework for executives who must allocate capital, prioritize product development, and position their organizations against an increasingly competitive and technologically sophisticated vendor landscape in 2026 and beyond.
The strategic value of this research lies in its ability to translate historical momentum into forward-looking operational intelligence. Drawing on a comprehensive historical window and extending through a seven-year forecast horizon, the analysis captures the inflection points that separate short-term demand fluctuations from structural market shifts. For leadership teams preparing their 2026 budgets, product roadmaps, and regional expansion plans, the report offers a disciplined lens through which to evaluate where growth is organically emerging, where competitive intensity is compressing margins, and where regulatory and technological tailwinds are creating durable advantages for early movers. Rather than presenting a static aggregation of figures, the study situates every metric within the operational realities of procurement cycles, field-deployment constraints, compliance workflows, and R&D investment timelines that actually drive purchasing behavior on the ground.
From a top-down perspective, the worldwide portable pH meter market has demonstrated a clear trajectory of expansion across the historical period, with total revenue climbing from approximately 331.45 million USD in 2020 to 434.03 million USD in 2024, before settling at an estimated 425.61 million USD in 2025 as the sector experienced a brief normalization following several years of accelerated adoption. Looking ahead, the forecast window projects a measured but consistent expansion path, anchored by a compound annual growth rate of 5.12 percent and a projected market valuation that reaches roughly 470.48 million USD in 2026 and continues climbing toward 603.68 million USD by 2032. This growth cadence is neither explosive nor stagnant; instead, it reflects a mature yet still dynamic category in which incremental gains are increasingly tied to product differentiation, application-specific engineering, and the ability to integrate measurement workflows into broader digital quality systems.
The forecast narrative carries particular weight for 2026 because it aligns with a period in which several structural pressures are converging. Field teams across municipal water operations, industrial process monitoring, and decentralized environmental sampling are demanding instruments that can withstand harsher deployment conditions, deliver repeatable data under variable temperatures and sample matrices, and feed results directly into centralized reporting platforms without sacrificing portability. At the same time, regulated end-use sectors are under growing scrutiny to demonstrate chain-of-custody integrity, calibration traceability, and sensor lifecycle management. These forces are reshaping purchasing criteria: buyers are increasingly evaluating total cost of ownership, electrode service life, connectivity features, and compliance readiness alongside upfront price. The study captures these shifts by mapping revenue movements against the operational realities that influence procurement decisions, helping readers distinguish between short-lived promotional demand and longer-term adoption curves.
A defining feature of the research is its application- and type-level dissection of demand drivers, presented with enough granularity to guide portfolio and segmentation strategy while preserving the analytical discipline necessary for actionable interpretation. On the product side, the market naturally bifurcates between digital and analog portable pH meters, each serving different operational priorities. Digital units continue to gain traction in environments where data logging, calibration documentation, and multi-parameter integration matter most, particularly in commercial testing laboratories, regulated processing facilities, and field programs that must produce auditable records. Analog instruments, meanwhile, retain relevance in applications where simplicity, lower acquisition cost, and straightforward field operation remain decisive, especially in educational settings, intermittent field sampling, and price-sensitive distribution channels.
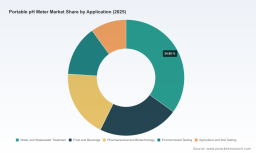
By application, the research examines how demand is distributed across water and wastewater treatment, food and beverage processing, pharmaceutical and biotechnology workflows, environmental testing, and agriculture and soil testing. Each vertical presents a distinct combination of compliance pressure, sampling frequency, measurement environment, and procurement governance. Water and wastewater operations, for example, are shaped by continuous monitoring expectations, seasonal discharge variations, and the need for rugged field instruments capable of handling turbid or chemically variable samples. Food and beverage demand is driven by hygiene verification, process control, and batch-release requirements that often demand rapid turnaround and documented calibration histories. Pharmaceutical and biotechnology applications impose the most stringent expectations around measurement integrity, sensor qualification, and documentation, frequently linking portable measurement tools to broader quality management systems. Environmental testing and agricultural soil monitoring contribute additional layers of complexity, with decentralized sampling networks, variable field conditions, and cost-conscious procurement patterns influencing volume, replacement cycles, and feature preferences.
The regional dimension of the study completes this operational picture. Demand patterns differ materially across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, reflecting variations in regulatory frameworks, industrial concentration, distributed monitoring programs, and the pace of technology adoption in field environments. Rather than treating geography as a simple revenue split, the analysis explores how regional procurement cultures, public-sector testing mandates, export-driven manufacturing activity, and local service infrastructure shape the commercial logic of portable measurement devices. This regional lens is especially useful for organizations evaluating where to prioritize sales coverage, service networks, distribution partnerships, or localized product adaptations.
Competitive Dynamics and Strategic Postures
No market analysis is complete without a rigorous reading of the competitive field, and the portable pH meter segment is shaped by a group of established manufacturers whose product strategies, certification portfolios, and channel capabilities create both barriers and opportunities for incoming competition. The study profiles leading participants including Hanna Instruments, Horiba, Thermo Fisher Scientific, Mettler Toledo, YSI (Xylem), Oakton (Cole-Parmer), Extech Instruments (FLIR), and Milwaukee Instruments, each of which brings a distinct combination of engineering heritage, application focus, and go-to-market strength.
Worldwide Portable pH Meter Market
Several of these players illustrate how product strategy is being realigned around field readiness, connectivity, and compliance documentation. Hanna Instruments has extended its portable portfolio with edge pH meters incorporating Bluetooth modules and wireless probe options, signaling a push toward more flexible data transfer and field connectivity. Horiba has broadened its Americas catalog with pocket and handheld offerings optimized for low-volume samples and microelectrode configurations, reinforcing its emphasis on measurement flexibility in environmental, aquaculture, and portable clinical use cases. Thermo Fisher Scientific has reinforced the ruggedness and multi-parameter capability of its Orion Star A series, including updated certifications that support deployment in demanding lab, field, and industrial settings. Mettler Toledo continues to position its portable instruments around intelligent sensor management, protection ratings, and compliance-oriented features relevant to pharmaceutical, food, and environmental testing workflows. YSI, operating within the Xylem ecosystem, integrates portable pH measurement with multi-parameter sondes designed for wastewater, surface water, and environmental monitoring programs where correlated parameters and durable field deployment are essential. Oakton and Extech Instruments maintain strong positions in education, HVAC, water treatment, and general field testing through waterproof designs, data logging, electrode diagnostics, and calibration alerting features. Milwaukee Instruments serves more price-sensitive and specialized niche segments with compact instruments tailored to hydroponics, aquariums, and routine field use.
These product movements matter because they reveal where the market’s value creation is heading. Competition is increasingly less about offering a bare-bones measurement function and more about delivering a dependable field workflow: instruments must survive deployment, provide stable readings across sample conditions, simplify calibration and electrode replacement, and reduce the administrative burden of documentation. In that context, the study’s competitive assessment focuses not only on current product positioning but also on the strategic implications of certification upgrades, trade-show introductions, catalog expansions, and wireless-integration initiatives. Organizations reading this section can better anticipate where rival vendors may strengthen channel advantages, where feature parity could compress price-based differentiation, and where underserved application requirements may still create room for targeted product strategies.
Regulatory, Technical, and Commercial Undercurrents
Strategic planning in this category also requires a clear understanding of the non-market forces that influence purchasing behavior and product design. Portable pH meters used in medical or clinical-adjacent settings must navigate quality management expectations such as ISO 13485 and electrical safety considerations including IEC 60601-1, which raises the bar for manufacturers seeking to serve regulated healthcare workflows. In the United States, benchtop and portable pH meters are generally classified as Class I exempt devices under 21 CFR 872.3770 for certain dental applications, but that classification does not eliminate the operational need for careful documentation, calibration control, and intended-use clarity. In hospital and clinical environments, portable pH meters are typically restricted to research and non-invasive diagnostic use, and reimbursement frameworks do not assign dedicated CPT or DRG codes to these instruments; instead, they are treated as general laboratory supplies within institutional budgets. These realities shape procurement volume, purchasing authorization pathways, and the relative importance of service and compliance support.
On the technical side, glass pH electrodes remain a central cost and lifecycle consideration. Medical-grade borosilicate construction is commonly required for durable performance, with electrode life typically ranging from 12 to 18 months under continuous use. This replacement cadence has direct implications for total cost of ownership, service planning, inventory management, and customer retention strategies, particularly in high-frequency testing environments where electrode failure translates into downtime and data gaps. For vendors, this creates both a recurring-revenue dynamic and a differentiation opportunity through electrode design, sensor management software, and field service support. For buyers, it reinforces the importance of evaluating not just the upfront instrument price but the long-term cost and reliability of consumables, calibration standards, and replacement parts.
What the Study Delivers for 2026 Decision-Making
PW Consulting’s worldwide portable pH meter market research is built to move beyond headline figures and into the operational questions that determine commercial outcomes. The report integrates historical performance, forecast trajectories, segmentation logic, competitive profiling, and regulatory context into a single decision-oriented framework. It is designed to help executives answer practical questions such as where demand is most resilient, which application segments justify feature investment versus cost optimization, how regional procurement environments influence go-to-market sequencing, and which vendor strategies are most likely to shape price, service, and differentiation dynamics over the forecast period.
Portable Keratometer Market
Readers will find detailed analysis of revenue movement across the historical and forecast windows, with particular attention to the inflection patterns that explain why the market expanded, normalized, and is now advancing at a moderate but sustained pace. The segmentation discussion provides a structured view of how product type and application needs interact to shape purchasing priorities, without reducing those needs to oversimplified ratios. The competitive section maps the strategic postures of leading manufacturers, linking recent product launches, certification updates, catalog changes, and trade-show activity to broader positioning implications. Regulatory and technical undercurrents are addressed as commercial factors rather than abstract compliance notes, helping teams evaluate how quality management expectations, electrical safety standards, electrode lifecycle economics, and reimbursement realities affect demand volatility and channel strategy.
For organizations preparing 2026 investments, the study functions as a risk-calibrated roadmap. It helps identify where growth is supported by durable drivers such as compliance pressure, decentralized monitoring needs, and digital workflow integration, and where growth may be more sensitive to macroeconomic fluctuations, replacement cycles, or competitive substitution. It also provides the context needed to interpret regional demand with operational nuance, enabling more informed decisions about distribution partnerships, service coverage, localization priorities, and application-specific marketing.
The most consequential insights, however, are necessarily reserved for the full report. Detailed segmentation profiles, regional and application-level revenue structures, concentration metrics, forecast scenarios, and company-level strategic assessments are presented in depth within the complete study, where they can be examined alongside methodology notes, primary research context, and scenario-based interpretation. This preview is intended to convey the analytical rigor and practical relevance of the research while preserving the specifics that give the full report its decision-making power.
In a market where field portability, data integrity, compliance readiness, and total cost of ownership are increasingly inseparable, strategic foresight is not a luxury but a requirement. PW Consulting’s worldwide portable pH meter market study is structured to give leaders that foresight: a disciplined, evidence-based view of where the market has been, how it is currently organized, and what the next phase of competition and adoption is likely to demand. For teams shaping product priorities, procurement strategies, market-entry plans, or investment theses in 2026, the full intelligence suite offers the detail, structure, and interpretive guidance needed to move from awareness to action.
For detailed analysis of this topic, please visit the official page: Worldwide Portable pH Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com