

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Medical Film Equipment Market Hits $2.2B in 2025, Projects 3.65% CAGR to 2032

Strategic Intelligence for the Worldwide Medical Film Equipment Market: Navigating Growth Amidst Transition
The global medical film equipment sector stands at a critical juncture where legacy imaging technologies intersect with evolving digital workflows and regulatory frameworks. For executives, investors, and strategic planners operating in healthcare imaging, understanding this landscape requires more than surface-level metrics—it demands a granular, actionable intelligence framework that connects macro trends to segment-level realities. Our newly released Worldwide Medical Film Equipment Market report delivers precisely that. Designed for decision-makers operating in 2026, this study translates historical performance, forward-looking projections, and competitive dynamics into a strategic roadmap. The market has demonstrated measurable resilience and expansion over the past half-decade, culminating in a 2025 revenue baseline of 2,195.99 million USD. With a forecasted compound annual growth rate of 3.65 percent spanning the 2026 to 2032 projection window, the trajectory points toward sustained, though carefully paced, expansion. By the end of 2032, cumulative market revenues are projected to approach 2.82 billion USD, underscoring the enduring relevance of radiographic imaging hardware, consumables, and digitization workflows even as digital modalities continue to reshape clinical environments.
Why This Report Matters for 2026 Decision-Making
Healthcare procurement leaders, imaging equipment manufacturers, and diagnostic service providers face a unique set of pressures in 2026. Supply chain volatility, evolving reimbursement structures, and the gradual but uneven pace of digital transition in imaging departments all influence capital allocation and product strategy. This report is structured to cut through noise and deliver decision-grade insight. It begins by anchoring historical performance across the 2020 to 2025 baseline period, where the market navigated post-pandemic recovery, raw material cost fluctuations, and incremental shifts in imaging department purchasing behavior. The historical record reveals how revenue levels climbed from 1,822.4 million USD in 2020 to 2,195.99 million USD in 2025, reflecting both volume adjustments and pricing dynamics driven by input cost pressures and sustained demand in specific imaging workflows.
From there, the forecast horizon 2026 through 2032 is modeled with scenario-aware granularity. Rather than presenting a single linear projection, the study maps how segment mix, regional adoption patterns, and regulatory developments will shape revenue realization across the forecast window. The 3.65 percent CAGR is not merely a headline figure; it is the output of a structured analytical framework that accounts for product lifecycle dynamics, substitution effects, and pockets of sustained analog demand in facilities where digital infrastructure remains incomplete or financially constrained. Decision-makers will find value in how the report ties these projections to real-world operational levers: pricing strategy, service contract positioning, consumablesbundling, and capital equipment lifecycle planning.
Core Report Architecture and Actionable Coverage
The study is engineered for immediate applicability. Rather than staying at the level of aggregate trends, it decomposes the market into analytically distinct dimensions that map directly to commercial and operational planning cycles.
-
Product and Technology Segmentation: The report evaluates hardware and consumable categories across dry medical printers, laser medical imagers, and medical film digitizers. Each category is assessed for demand drivers, pricing elasticity, replacement cycles, and integration pathways with existing radiographic workflows. This enables readers to pinpoint where margin expansion opportunities exist, where competitive intensity is highest, and how digitization hardware is reshaping the value chain for traditional film-based imaging.
-
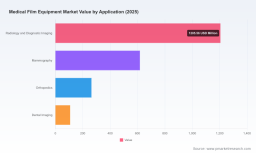
Application Pathways: Diagnostic imaging deployments are analyzed across radiology and diagnostic imaging, mammography, orthopedics, and dental imaging. For each application, the study examines clinical workflow dependencies, procurement cycles, and the extent to which analog film remains embedded in departmental routines. This application-level view is particularly useful for manufacturers aligning product roadmaps and for distributors tailoring channel strategies to specific specialty segments.
Industrial X-ray Film Market -
Regional Intelligence: The analysis provides a structured regional view that captures how market maturity, healthcare infrastructure development, and procurement practices influence revenue distribution. Rather than offering blunt geographic rankings, the report contextualizes regional performance within broader healthcare investment patterns and imaging modality adoption curves, allowing readers to assess where near-term growth is most actionable and where long-term positioning requires patience and partnership development.
-
Competitive Positioning and Benchmarking: A dedicated competitive section profiles key players and maps strategic behaviors across product portfolios, regulatory engagement, and pricing maneuvers. This is complemented by concentration metrics that reveal how market share is distributed among leading participants, giving stakeholders a clear sense of where barriers to entry sit and where consolidation or partnership opportunities may emerge.
-
Regulatory and Reimbursement Context: The study integrates device classification considerations, premarket notification expectations, and the role of existing diagnostic imaging reimbursement frameworks in sustaining certain analog workflows. By connecting regulatory structure to commercial reality, the report helps teams anticipate compliance burdens, evaluate market access pathways, and understand why specific product categories retain traction even as digital alternatives expand.
Competitive Landscape: Players, Moves, and Structural Dynamics
The worldwide medical film equipment market is characterized by a concentrated but diversified competitive field. Market concentration metrics indicate that leading participants collectively command a substantial share of revenue, with the top three competitors accounting for approximately 62.45 percent and the top five reaching roughly 78.12 percent. This concentration reflects the entrenched position of established imaging suppliers, the capital intensity of product development and regulatory compliance, and the reliance of many imaging departments on familiar consumables and processing ecosystems. Yet the competitive environment is not static. Strategic moves, regulatory milestones, and raw material cost volatility continue to reshape how players compete on price, performance, and service.
Among the central participants, Agfa-Gevaert stands out for its long-standing portfolio of medical X-ray films and radiographic imaging films serving diagnostic facilities globally. Its market presence is reinforced by continuous engagement with clinical workflows and a supply footprint that supports recurring consumables demand. Fujifilm Holdings Corporation complements this landscape with medical X-ray films and digital imaging X-ray film offerings, alongside related consumables designed for radiographic applications. The company's integration of imaging technology heritage with consumables strategy positions it as a significant force in segments where image quality consistency and processing reliability are paramount. Carestream Health contributes a focused set of radiographic films and X-ray film processing solutions tailored for medical imaging departments, emphasizing workflow compatibility and support infrastructure. Konica Minolta maintains a strong position in medical X-ray film manufacturing and supports traditional radiographic imaging systems, serving facilities that continue to rely on established film-based processes.
Beyond the core imaging film manufacturers, the competitive field includes suppliers whose materials and processing technologies indirectly shape the ecosystem. Tekra, LLC specializes in medical-grade polyester, polycarbonate, COC, and PMMA films used in diagnostic testing and medical device components, linking film material innovation to broader diagnostic applications. Berry Global Inc. produces medical films and flexible materials suitable for healthcare packaging and device applications, reflecting the adjacent demand streams that influence film material supply dynamics. Dürr Dental manufactures dental and medical X-ray film processors, including automatic processors such as Periomat Plus, anchoring its position in processing hardware that supports film-based imaging workflows. Dunmore Corp. supplies specialized coated and laminated films for medical applications, adding further depth to the materials and coatings dimension of the marketplace.
Competitive dynamics in 2025 and 2026 have also been influenced by notable regulatory and commercial developments. In March 2026, Agfa HealthCare announced a price increase for medical X-ray film, attributed to rising input costs. This move highlights how raw material economics and production cost pressures can translate directly into pricing strategy, with potential ripple effects across procurement budgets and substitution decisions. At the same time, regulatory updates continue to clarify the boundaries of film-based imaging within broader device ecosystems. In November 2025, Adaptix Limited received FDA 510(k) clearance for its Ortho350 system as a radiographic imaging system, an event noted in the context of film marking and related radiographic equipment. In January 2025, Ziehm Imaging GmbH secured FDA 510(k) clearance for its imaging system, with device specifications explicitly noting that the system does not support direct radiographic film exposures. These developments illustrate how regulatory clearances increasingly reflect a market where digital and film-based pathways coexist but diverge in design intent, reinforcing the importance of understanding exactly where film equipment fits within each clinical and procurement context.
Market Dynamics Shaping the 2026 to 2032 Window
Several structural forces will determine how revenue evolves across the forecast period. First, raw material cost trends remain a persistent consideration. Rising silver costs have historically driven increases in medical X-ray film pricing, influencing production economics for silver-halide based radiographic films. Pricing decisions by leading suppliers will continue to interact with procurement sensitivity, particularly in price-regulated or budget-constrained settings. Second, reimbursement practices and departmental budgeting continue to support traditional analog radiographic film usage in settings without full digital transition. Existing hospital radiology budgets and CPT coding for diagnostic imaging procedures provide ongoing financial pathways that sustain demand for certain film-based workflows, even as digital infrastructure expands elsewhere.
Third, device regulation adds both structure and complexity. Radiographic film is classified by the FDA as a Class I or II device under product code IWZ with regulation 892.1840, subject to general controls and certain exemptions from 510(k) and GMP requirements. Automatic radiographic film processors are regulated under FDA 892.1900 as Class II devices requiring premarket notification in many cases. These classification frameworks shape development timelines, compliance responsibilities, and market entry strategies for both incumbents and new entrants. At the same time, the growing orientation of certain C-arm and fluoroscopic systems toward digital imaging workflows means that film compatibility is no longer a default assumption. Buyers increasingly evaluate equipment not only on image quality but also on integration with existing digital ecosystems, service availability, and consumables economics over the full equipment lifecycle.
Worldwide Medical Film Equipment Market
Fourth, digitization hardware and conversion technologies introduce a distinct value layer. Medical film digitizers and related conversion workflows create opportunities for facilities that must manage archival film, transition legacy studies, or maintain compatibility with hybrid imaging environments. The extent to which digitization adoption accelerates will depend on capital availability, internal IT readiness, and the perceived cost-benefit balance relative to full digital replacement. In this context, the market's measured CAGR reflects a landscape where growth is real but uneven, with some categories expanding on the back of replacement cycles and consumables demand, while others evolve more slowly as digital substitution progresses.
What the Report Reveals—and What It Reserves for Subscribers
This introduction is intentionally structured to demonstrate analytical rigor while preserving the full granularity of the dataset for clients who need to act on it. What we can share publicly is that the study provides a coherent view of how the market has evolved from 2020 through 2025, how it is projected to unfold through 2032, and how competitive, regulatory, and materials-driven forces interact across product types, application areas, and regional contexts. What remains within the full report are the segment-level revenue splits, detailed regional breakdowns, precise category allocations across types and applications, and the supporting methodology that allows subscribers to test assumptions, benchmark positioning, and build internal forecasts with confidence. Those details matter because strategic decisions rarely hinge on aggregate market size alone. They depend on knowing where demand is most durable, which product categories are most exposed to input cost volatility, how competitive concentration shapes pricing freedom, and where regional dynamics create openings for targeted expansion or partnership.
For organizations planning 2026 investment, procurement strategy, product roadmap adjustments, or market entry evaluations, this report is designed to serve as a decision infrastructure. It connects historical evidence to forward-looking scenarios, embeds regulatory and reimbursement context into commercial interpretation, and maps the competitive field in enough detail to support positioning decisions without resorting to generic industry commentary.
Who Should Use This Study and How
This report is built for cross-functional use. Commercial leaders can leverage it to align pricing, channel, and service strategies with segment-level demand realities. Product and technology teams can use it to prioritize development and integration work where workflow fit and replacement cycles create the strongest pull. Procurement and supply chain planners can apply its insights to anticipate cost pressure points, evaluate consumables bundling opportunities, and structure contracts that reflect likely pricing behavior in response to materials cost trends. Investor and corporate strategy teams can draw on the forecast architecture and concentration analysis to assess growth durability, competitive moats, and the extent to which legacy imaging segments will continue to contribute meaningfully to revenue pools over the next several years.
The study is also designed to be actionable for organizations operating across different levels of digital maturity. In markets and facilities where analog radiographic film remains embedded in routine diagnostic workflows, the report clarifies the economic and regulatory factors that sustain demand and the pricing dynamics that influence procurement decisions. In settings where digital transition is more advanced, it provides a framework for understanding how film-related equipment, consumables, and digitization hardware fit into hybrid environments and transitional procurement strategies. In both cases, the goal is the same: to enable decisions grounded in evidence rather than assumption.
Access the Full Intelligence
The Worldwide Medical Film Equipment Market report offers a complete, segment-resolved view of market size, growth trajectory, competitive positioning, and operational context across the 2026 to 2032 forecast window. It is built for teams that need more than directional insight and less than static data tables—decision-makers who want a structured, defensible basis for planning in a market where legacy technologies, digital transition, and regulatory and materials dynamics all interact at once. To access the full segmentation data, regional detail, competitive benchmarking, and supporting forecast architecture, download the complete report through our official research portal. The macro trajectory is clear; the strategic implications are in the details.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Film Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com