

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hyperhidrosis Treatment Market Hits $1,815.71M in 2025, Projected to Reach $2,751.86M by 2032 at 6.12% CAGR

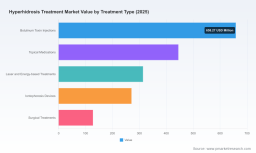
Strategic Foresight for a Growing Dermatology Segment: Inside the Worldwide Hyperhidrosis Treatment Market Intelligence
The hyperhidrosis treatment landscape is entering a decisive phase of commercial maturation. Where excessive sweating was long dismissed as a niche comfort issue, it is now increasingly recognized as a billable clinical condition spanning dermatology, primary care, and aesthetic medicine. Our newest Worldwide Hyperhidrosis Treatment Market research synthesizes seven years of historical tracking with a full forecast arc through 2032, giving executive teams a precision tool for capacity planning, portfolio positioning, and partnership strategy. Below is a structured preview of the analytical depth, competitive mapping, and operational frameworks contained in the full report.
Market Trajectory and the Strategic Signal Behind the Numbers
The global hyperhidrosis treatment market reached approximately 1,815.71 million USD in our 2025 base year, building steadily on a 2020 baseline of 1,350.5 million USD. The trajectory reflects a compound annual growth rate of 6.12 percent across the forecast window, with the market projected to surpass 1,934.5 million USD in 2026 and continue expanding toward 2,751.86 million USD by 2032. This growth is not simply a function of population expansion; it reflects shifting clinical uptake, reimbursement experimentation, and a broadening treatment continuum that now spans botulinum toxin injections, topical formulations, energy-based procedures, iontophoresis devices, and surgical interventions.
For corporate strategists, the most actionable insight is the market's structural acceleration. The forecast period captures a transition from early adoption curves to more normalized prescription pathways and procedural utilization. Companies that treat this segment as a static dermatology niche risk misreading the pace at which patient awareness, physician familiarity, and payer exposure are converging. The full study translates this trajectory into scenario-based planning frameworks, enabling leadership to test how changes in prescription dynamics, procedural pricing, and clinical referrals will reshape addressable demand over multiple planning cycles.
Treatment Continuum: Why Differentiation Is No Longer Optional
Hyperhidrosis care is being redefined by a widening spectrum of modalities, each with distinct clinical positioning, patient adherence profiles, and reimbursement exposure. The breadth of this continuum is one of the central themes of the report. Rather than analyzing treatment types in isolation, the study examines how they compete, complement, and cannibalize one another across different patient segments and clinical settings. This matters because product strategy in this market increasingly depends on understanding substitution effects as much as primary demand.
Overactive Bladder Treatment Market
- Botulinum toxin injections remain anchored by strong clinical recognition and well-established treatment protocols, particularly in axillary indications, but their commercial trajectory is shaped by administration logistics, duration of effect, and payer quantity limits.
- Topical medications are expanding the front door of treatment by offering non-invasive options with improving patient convenience, though their uptake is mediated by step-therapy expectations and real-world persistence patterns.
- Laser and energy-based treatments occupy a distinctive position at the intersection of dermatology and aesthetic service delivery, often facing classification questions that influence reimbursement and patient out-of-pocket economics.
- Iontophoresis devices serve both clinic-administered and home-use pathways, creating a dual distribution logic that rewards device accessibility, patient training, and repeat-use adherence.
- Surgical treatments remain a smaller share of the overall market but are critical for refractory cases, where clinical decision-making, procedural risk, and irreversible outcomes impose highly specialized demand dynamics.
Our segmentation review explains how these categories interact across the patient journey rather than presenting them as static silos. That approach is especially valuable for companies deciding whether to compete within an existing modality, extend into adjacent services, or position hybrid offerings that reduce friction between prescription, procedural, and maintenance phases of care.
Competitive Landscape: Where Growth Meets Defensible Positioning
The hyperhidrosis market features a diverse set of participants, from large biologics and aesthetics players to focused dermatology innovators and device manufacturers. The report profiles the companies shaping commercial velocity in this space, assessing how their pipeline activity, regulatory milestones, and go-to-market models influence competitive intensity. Rather than simply listing incumbents, the study evaluates the strategic logic behind each player's footprint and the implications for market share dynamics.
- AbbVie Inc. (Allergan) maintains a prominent position through its botulinum toxin franchise, supported by the only FDA-approved botulinum toxin specifically indicated for primary axillary hyperhidrosis, giving it a distinctive regulatory and clinical anchor in a high-recognition treatment category.
- Botanix Pharmaceuticals advanced the topical segment with FDA approval of Sofdra in mid-2024, reinforcing the trend toward non-invasive pharmacologic options for younger patient populations and expanding the prescription topical armamentarium.
- Journey Medical Corporation commercializes Qbrexza, building on a topical anticholinergic pathway with continued patent protection extending into the next decade, which carries implications for competitive entry timing and pricing durability.
- Candesant Biomedical pursued a device-based non-invasive approach with FDA clearance for its sweat-control patch, illustrating how targeted thermolysis concepts are being translated into practical, clinic-friendly treatment options.
- Sientra Inc. and miraDry, Inc. represent the energy-based procedural side of the market, where permanent reduction claims, procedural economics, and cosmetic-versus-medical classification create both opportunity and reimbursement complexity.
- Dermadry Laboratories Inc. and RA Fischer Co. anchor the iontophoresis segment, where home-use and clinic-based device programs compete on convenience, patient education, and repeat-use economics.
- Merz Pharma, Hugel Inc., and Kaken Pharmaceutical Co., Ltd. reflect broader botulinum toxin participation across regions, emphasizing the importance of local market access, brand recognition, and service infrastructure in sustaining prescription volume.
- Revance Therapeutics and Brickell Biotech Inc. sit within a broader innovation pipeline, illustrating ongoing interest in next-generation toxin formulations and topical anticholinergic candidates that could shift future competitive baselines.
- Dermavant Sciences Inc. adds to the pipeline landscape with dermatology-focused development activity that underscores how hyperhidrosis remains an attractive indication for specialized therapeutic programs.
Beyond company profiles, the research connects recent commercial events to structural change. A January 2025 clinical trial collaboration evaluating a topical combination approach signaled continued interest in optimizing non-invasive treatment regimens. Earlier regulatory milestones in 2024 and 2023 reinforced the broadening approval and clearance environment, showing how the market is accumulating viable options rather than relying on a single dominant standard. These events are analyzed not as isolated headlines but as inputs to competitive timing, launch sequencing, and regional expansion planning.
Regulatory, Reimbursement, and Supply Chain Realities
A market can expand on paper while remaining difficult to monetize in practice. The report devotes substantial attention to the institutional frictions that determine which growth is accessible to which business models. Regulatory approval is only one part of the equation; reimbursement policy, step-therapy design, and classification logic frequently determine whether clinical adoption converts into sustainable revenue.
In the United States, payers often require step therapy with antiperspirants before approving prescription topicals, and botulinum toxin reimbursements are commonly subject to quantity limits. These policies shape prescription behavior, patient access, and the economics of repeat treatment cycles. At the same time, advanced procedures may be categorized as cosmetic in certain settings, limiting coverage and increasing reliance on patient-funded demand. The study evaluates these dynamics across the treatment continuum so that commercial teams can anticipate the operational restrictions that will accompany clinical opportunity.
Supply chain considerations also feature prominently. Recent renegotiation of an active pharmaceutical ingredient supply agreement for a leading topical candidate illustrates how procurement structure can influence cost of goods sold, margin durability, and launch resilience. For strategists, the lesson is clear: in a market with multiple modalities and a growing list of specialty entrants, financial defensibility depends as much on input costs and distribution readiness as on clinical differentiation. The full report integrates these themes into a cohesive market-dynamics assessment, linking policy, pricing, production, and access into a single decision-relevant framework.
What the Full Study Delivers for 2026 Decision-Making
This research is designed to support concrete strategic actions rather than general market awareness. It provides an integrated view of market size evolution, segmentation interactions, competitive positioning, and operational constraints, allowing teams to move from observation to planning with greater confidence. The study's architecture is built for users who must make resource allocation choices under uncertainty and need evidence that connects market momentum to execution risks.
- A forecast model spanning 2026 through 2032 that ties historical trends to forward-looking demand drivers, giving planners a defensible basis for revenue modeling and investment timing.
- Segment-level analysis that explains how treatment types, end-user settings, and regional demand patterns interact, helping teams identify where adoption is most likely to accelerate and where barriers remain strongest.
- Competitive profiling that connects company strategies, regulatory status, and commercial assets to likely market-share implications, supporting benchmarking, partnership evaluation, and white-space identification.
- Market-structure metrics that illuminate concentration and competitive intensity, allowing leadership to gauge the balance between incumbent stability and entry opportunity.
- Practical context on reimbursement logic, clinical classification, and supply-side considerations, ensuring that commercial strategies are built around what the market can actually monetize, not just what it can theoretically absorb.
The study also includes analytical tools that help users pressure-test assumptions. Because hyperhidrosis care spans prescription therapy, device use, procedural services, and surgical intervention, the report considers how changing patient pathways, clinical referral behavior, and access policies can alter the shape of demand over time. That breadth is especially useful for organizations operating across multiple business lines or considering expansion into adjacent dermatology and aesthetics segments.
Why Strategic Timing Matters Now
The hyperhidrosis treatment market is maturing at a moment when differentiation, access strategy, and execution discipline will increasingly separate durable winners from temporary participants. Growth is projected to continue at a steady pace, but the more important question for leadership is not whether the market expands; it is where value will concentrate as treatment options multiply and payer systems adapt. Companies that understand the interplay between clinical acceptance, reimbursement constraints, and competitive entry timing will be better positioned to allocate capital, shape launch plans, and negotiate partnerships with precision.
Worldwide Hyperhidrosis Treatment Market
Our full Worldwide Hyperhidrosis Treatment Market report translates these strategic questions into a complete intelligence package. It goes beyond headline market size to show how the segments connect, how the competitive field is being organized, and which structural factors will determine commercial outcomes over the next several years. For executives preparing for 2026 planning cycles, the report offers a fact-based foundation for scenario planning, portfolio decisions, and market entry or expansion strategy.
To access the complete analysis, including segment-level forecasts, competitive profiles, and the detailed dynamics framework, request the full report through our official research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Hyperhidrosis Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com