

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Heparin Market Hits $6.85B in 2025, Forecasted 5.85% CAGR to Reach $10.2B by 2032

Navigating the Global Heparin Market: Strategic Intelligence for 2026 and Beyond
The global medical heparin market stands at a critical intersection of clinical necessity, supply chain complexity, and regulatory scrutiny. As one of the most foundational anticoagulants in modern medicine, heparin continues to anchor treatment protocols across surgical, cardiovascular, and renal care settings. Yet, despite decades of established use, the market has entered a phase of structural recalibration. For pharmaceutical leaders, procurement executives, and healthcare strategists, understanding the trajectory of this market through 2032 is no longer optional; it is a core component of risk mitigation and growth planning.
Our latest Worldwide Medical Heparin Market research report translates historical performance, forward-looking projections, and operational dynamics into a single strategic framework. Designed for decision-makers operating in the 2026 business environment, the study moves beyond headline figures to expose the mechanics driving product adoption, regional balance, competitive positioning, and supply chain resilience. Below, we outline the analytical architecture and strategic utility of the report, illustrating why it should serve as a foundational reference for your 2026 planning cycle.
Worldwide Medical Heparin Market
Why Heparin Demands Renewed Strategic Attention in 2026
Heparin's clinical indispensability is counterbalanced by a supply ecosystem that remains vulnerable to biological, geopolitical, and regulatory shocks. The active pharmaceutical ingredient relies predominantly on porcine intestinal mucosa, with sourcing heavily concentrated in a single geographic corridor. This dependence has repeatedly demonstrated its capacity to translate livestock health events, export policy shifts, and sudden demand spikes into pricing volatility and availability constraints. Simultaneously, regulatory agencies across major markets continue to tighten quality expectations, traceability mandates, and contamination safeguards for animal-derived APIs.
In parallel, clinical utilization patterns are evolving. Venous thromboembolism management, renal dialysis support, and coronary artery disease interventions remain central demand pillars, but product form preferences, premixed hospital formulations, and catheter lock innovations are reshaping procurement behavior. The result is a market where historical volume trends are necessary but insufficient for forward planning. Decision-makers require a structured view of how type differentiation, application mix, and regional dynamics interact with competitive moves and supply-side risks.
Market Sizing and Projected Trajectory: Reading the Numbers Strategically
The market's historical arc from 2020 through 2025 establishes a clear baseline of expansion punctuated by brief cyclical adjustments. Starting from a base in the early 2020s, revenue progressed through a period of recovery and growth, ultimately reaching approximately 6,850.40 million USD in 2025. This trajectory reflects both renewed hospital activity post-pandemic and consistent institutional reliance on heparin-based anticoagulation across multiple care settings.
Heparin Market
Looking ahead, the forecast window from 2026 to 2032 projects sustained expansion at a compound annual growth rate of 5.85 percent. The progression from roughly 7,188.34 million USD in 2026 to a projected 10,198.87 million USD by 2032 signals more than incremental growth; it indicates a market that is scaling structural demand while navigating the cost and availability pressures inherent to its raw material base. For executives, the strategic implication is twofold. First, growth is broad-based enough to warrant capacity and portfolio planning rather than opportunistic bets. Second, the pace of expansion will be moderated or accelerated by supply chain performance, regulatory compliance costs, and the speed at which alternative sourcing and processing innovations are commercialized.
Rather than presenting these figures as isolated endpoints, the report embeds them within sensitivity considerations. Readers are guided through the ways macroeconomic shifts, disease-driven supply interruptions, and pricing negotiations affect realized revenue versus projected tops. This approach ensures that financial planning is anchored to realistic operational scenarios rather than optimistic abstractions.
What the Report Covers: Operating Intelligence for Execution Teams
A market study is only as valuable as the actions it enables. Accordingly, this research is structured to support cross-functional teams tasked with sourcing, commercialization, regulatory alignment, and competitive positioning. The report delivers detailed breakdowns across the following operational dimensions:
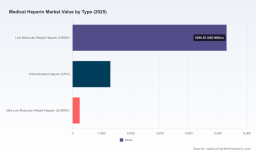
- Type-based segmentation dynamics examining how unfractionated heparin, low molecular weight heparin, and ultra-low molecular weight heparin occupy distinct clinical and procurement niches, and how formulation preferences are shifting in hospital and outpatient settings.
- Application-level demand mapping that traces usage intensity across major therapeutic areas, helping teams anticipate where volume growth, substitution risk, and pricing pressure are likely to converge.
- Regional balance and sourcing geography detailing where consumption is concentrated, how import dependency varies, and where localized manufacturing or partnership strategies can reduce exposure to concentrated supply risk.
- Competitive positioning and strategic moves profiling the companies shaping supply, formulation innovation, and hospital integration, including recent product launches, joint ventures, and commercial availability milestones that alter procurement options.
- Supply chain vulnerability analysis focusing on raw material concentration, porcine mucosa dependency, historical disruption patterns, and the practical implications for inventory planning, contract negotiation, and diversification roadmaps.
- Regulatory and quality compliance context covering the standards imposed by major health authorities, the operational burden of traceability and contamination prevention, and how compliance readiness can become a competitive differentiator.
- Scenario planning tools that allow users to stress-test growth assumptions against raw material shocks, tariff or export shifts, and changes in hospital procurement behavior.
By integrating these layers, the report equips readers to coordinate across procurement, R&D, regulatory affairs, and commercial strategy without relying on fragmented data sources. Each section is built to feed directly into budgeting, contract strategy, product roadmap decisions, and regional expansion evaluation.
Competitive Landscape: How Leading Players Are Shaping the Next Cycle
The heparin market is characterized by a mix of global pharmaceutical manufacturers, specialized API producers, and regional suppliers with strong footprint advantages in specific distributions channels. Concentration remains significant, with a handful of firms capturing a substantial share of revenue, while a broader field of manufacturers competes on formulation breadth, supply reliability, and cost positioning.
Several incumbents illustrate the strategic diversity within the market. Pfizer Inc. maintains a prominent role in unfractionated and low molecular weight heparin formulations, with strong relevance in surgical, cardiovascular, and hospital-use injectable products. Sanofi S.A. is a recognized producer of low molecular weight heparin therapies, including enoxaparin, supporting thrombosis prevention and treatment on a global scale. Baxter International Inc. supplies heparin sodium injections and premixed bags designed for intravenous hospital use, focusing on anticoagulant solutions that support clinical procedures and dialysis workflows. B. Braun SE emphasizes premixed infusion solutions and supply security, with an emphasis on hospital pharmacy integration for catheter patency and anticoagulation. Fresenius SE & Co. KGaA, through its Fresenius Kabi operations, provides heparin sodium injection for anticoagulation in hospital and critical care environments, including dialysis and surgical applications.
Beyond these established players, a broad tier of firms contributes to global availability and pricing dynamics. LEO Pharma A/S develops and markets low molecular weight heparin and heparin-based anticoagulants for thromboembolic disorders. Dr. Reddy's Laboratories Ltd. and Teva Pharmaceutical Industries Ltd. extend cheaper or institutionally focused generic heparin and LMWH offerings, broadening access for hospital and institutional buyers. Aspen Pharmacare Holdings Ltd. reinforces distribution reach across multiple regions and maintains a visible presence in emerging markets. On the API and processing side, Shenzhen Hepalink Pharmaceutical Group Co., Ltd. stands out as one of the largest integrated producers of heparin API and finished dosage forms, leveraging a vertically connected porcine mucosa supply chain. Opocrin S.p.A. and Bioiberica S.A.U. specialize in heparin API production and purification, with Bioiberica also directing attention toward sustainable extraction, traceability, and joint venture structures aimed at circular production models. Additional contributors such as Hebei Changshan Biochemical Pharmaceutical Co., Ltd., Changzhou Qianhong Bio-pharma Co., Ltd., and Nanjing King-friend Biochemical Pharmaceutical Co., Ltd. reinforce the breadth of API and derivative manufacturing feeding global demand.
Recent corporate activity underscores how competition is being contested in the near term. B. Braun Medical Inc. expanded its U.S. premixed portfolio with a Heparin Sodium 25,000 Units in 0.45% Sodium Chloride bag in mid-2025, following an earlier launch of a domestically manufactured Heparin Sodium 2,000 units in 0.9% Sodium Chloride Injection in early 2024. These moves reflect a broader push toward ready-to-administer hospital solutions and domestic manufacturing options. In a complementary clinical direction, CorMedix Inc. announced the inpatient commercial availability of DefenCath, a taurolidine and heparin catheter lock solution designed to reduce catheter-related bloodstream infections in hemodialysis patients, signaling product innovation at the intersection of anticoagulation and device-related infection control. Meanwhile, Bioiberica S.A.U. celebrated its 50th anniversary with a refreshed brand identity and continued exploration of innovative heparin applications through global research partnerships, while its earlier joint venture with Vall Companys, the Biovall Heparin Science partnership, committed meaningful investment toward sustainable crude heparin production using porcine intestinal mucosa co-products.
The report situates these developments within a wider competitive logic. It examines how formulation expansion, domestic manufacturing, infection-control adjuncts, and sustainable API initiatives alter buyer negotiation dynamics and regional availability. Readers gain a structured view of which moves are likely to influence hospital formulary decisions, which are primarily positioning signals, and where supplier diversification or partnership opportunities may emerge.
Market Dynamics: Supply Chain, Regulation, and the Risk Landscape
Any credible heparin strategy must account for the forces that can rapidly alter cost structures and availability. The strongest of these is raw material concentration. Porcine intestinal mucosa remains the primary source of heparin, and China supplies an overwhelming share of global crude heparin. This concentration creates a market that is efficient under stable conditions but highly exposed when livestock disease, export policy, or trade friction intervenes. African Swine Fever outbreaks have historically demonstrated how quickly porcine supply disruptions can translate into price volatility, prompting the industry to explore diversification through bovine sources and biosynthetic or semi-synthetic alternatives.
Geopolitical and trade dynamics compound this exposure. Reliance on concentrated sourcing channels leaves buyers vulnerable to export controls, tariff adjustments, and logistics disruptions. For hospitals, distributors, and manufacturers, the practical challenge is not only identifying backup suppliers but also verifying that alternate sources meet stringent quality expectations without introducing compliance risk or prohibitively high switching costs.
Regulatory oversight adds another layer of discipline. Major health authorities maintain rigorous standards for heparin quality, including adherence to monographs and enhanced emphasis on traceability and contamination prevention in animal-derived APIs. These requirements raise the operational bar for suppliers and increase the importance of documented chain-of-custody, process control, and testing integrity. In practice, compliance readiness can function as a competitive advantage, particularly when buyers are evaluating suppliers under supply-stress conditions.
On the product side, heparin remains subject to periodic recalls or conservation protocols where endotoxin contamination risks or supply tightness emerge. Historical episodes have shown how quickly availability concerns can affect hospital procurement and clinical workflow. As a result, prudent teams are increasingly embedding contingency planning, dual sourcing, and demand smoothing into their heparin procurement strategies rather than treating availability as a given.
How to Use This Research for 2026 Decision-Making
The strategic value of this report lies in its ability to convert market complexity into actionable orientation. For 2026 planning, teams can use the analysis to:
- Calibrate volume and revenue assumptions using a growth trajectory anchored in historical behavior and forward forecasts, while adjusting for supply-side sensitivities.
- Evaluate where type and application dynamics will create margin opportunity, substitution risk, or pricing negotiation leverage.
- Assess regional exposure and identify where import dependency or concentrated sourcing increases vulnerability, then align sourcing strategies accordingly.
- Benchmark competitor activity, including premixed formulation launches, domestic manufacturing moves, infection-control adjuncts, and API sustainability partnerships, to anticipate changes in hospital and institutional purchasing behavior.
- Build regulatory and quality narratives that support supplier qualification, internal compliance readiness, and risk communication with clinical stakeholders.
- Develop scenario plans that connect raw material concentration, disease-event risk, and regulatory trends to inventory buffers, contract structures, and alternative sourcing roadmaps.
The study is designed to be referenced, not just read. Sections can be extracted for procurement reviews, commercial planning sessions, regulatory briefings, and board-level strategic updates. By keeping the analysis tied to operational decisions rather than abstract market descriptions, the report helps organizations convert intelligence into execution.
What You Will Find in the Full Report
The complete Worldwide Medical Heparin Market research delivers the detailed segmentation frameworks, competitive profiles, regional demand structures, and supply chain diagnostics needed to support multi-year planning with precision. Because many of the actionable figures, internal breakdowns, and company-specific strategic readouts require close examination, the full document provides the granularity that an executive overview cannot. Readers seeking complete quantitative segmentation, detailed company analysis, and region-specific procurement implications will find those materials structured for direct use in budgeting, sourcing, and product strategy discussions.
For teams preparing for the 2026 operating environment, this research offers a defensible basis for assumption-setting, risk identification, and opportunity prioritization. The broader market trajectory points to continued expansion, but the real strategic work lies in managing the forces that determine whether growth is captured efficiently or eroded by supply, pricing, and compliance pressures. The full report is built to give decision-makers the clarity required to act on that reality.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Heparin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com