

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Aircraft Wind Tunnel Testing Market to Hit $929.95M by 2032 with 5.25% CAGR

Strategic Imperatives in Aircraft Wind Tunnel Testing Services: A 2026 Market Perspective
The global aerospace industry stands at a critical inflection point. As aircraft design philosophies evolve toward unconventional configurations, hypersonic mission profiles, and sustainable propulsion architectures, the dependency on empirical aerodynamic validation has never been more pronounced. Wind tunnel testing remains the indispensable bridge between computational simulation and certified flight reality. Against this backdrop, the Aircraft Wind Tunnel Testing Services Market is projected to demonstrate a compound annual growth rate of 5.25% across the forecast horizon, with total market revenue climbing from an estimated 650.0 million USD in the base year to approximately 929.95 million USD by 2032. This trajectory is not merely a reflection of incremental capacity expansion; it signals a structural realignment of how aerospace OEMs, defense contractors, and emerging mobility developers approach aerodynamic certification, performance optimization, and risk mitigation.
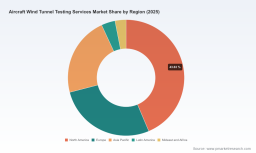
For executive teams, capital allocators, and program managers navigating the 2026 decision cycle, understanding the underlying mechanics of this market is no longer a peripheral analytical exercise. It is a strategic prerequisite. The following analysis outlines the macro-financial contours, competitive architecture, regulatory pressures, and technological catalysts that define the current testing services landscape. While high-level indicators illuminate the direction of travel, the granular segmentation, regional demand distribution, and service-type valuation multipliers that truly inform procurement strategy, partnership selection, and capacity planning are explored in depth within our latest market intelligence publication.
Aircraft Wind Tunnel Testing Services Market
Macro Trajectory and Capital Allocation Signals
The historical progression from 2020 through 2025 reveals a market that has consistently outperformed baseline industrial growth expectations. Revenue expanded from 503.27 million USD to 650.0 million USD, demonstrating resilient demand even amid broader supply chain disruptions and shifting defense procurement cycles. The forward forecast period from 2026 through 2032 continues this upward arc, crossing the 700.0 million USD threshold in 2027 and approaching the 900.0 million USD mark by the end of the decade. This expansion is underpinned by several mutually reinforcing dynamics: the proliferation of clean-sheet aircraft programs, the re-emergence of high-speed aerodynamic research, and the operational necessity of validating novel airframe geometries that fall outside legacy certification playbooks.
However, raw growth figures alone do not dictate investment logic. The market's structural economics are defined by formidable infrastructure barriers. Constructing a large transonic wind tunnel facility requires capital expenditure exceeding 500 million USD, accompanied by sustained operational overhead, specialized workforce requirements, and continuous calibration demands. This cost architecture naturally concentrates market activity among established operators with long amortization horizons and entrenched client relationships. For organizations evaluating external testing partnerships, capacity reservations, or strategic service integrations, the distribution of spend across service categories, aircraft platforms, and geographic testing hubs becomes a decisive variable. These allocation patterns, along with the precise revenue weighting of each segment, are mapped in full within our comprehensive report.
Competitive Architecture and Facility Specialization
The testing services ecosystem is characterized by a blend of independent specialists, state-aligned research organizations, and OEM-affiliated testing divisions. Industry concentration metrics indicate a moderately consolidated landscape, with the top three operators accounting for 45.5% of market share and the top five capturing 62.2%. This concentration reflects both the technical moat inherent in large-scale aerodynamics testing and the long-cycle nature of aerospace program commitments. Yet within this consolidated framework, competitive differentiation remains highly nuanced, driven by test section dimensions, Mach regime coverage, instrumentation sophistication, and program management capabilities.
Calspan Corporation operates a prominent transonic testing capability centered on an 8 ft × 8 ft test section extending to Mach 1.3, complemented by turn-key model manufacturing, positioning systems, balance integration, and calibration services tailored to aerospace programs. The Aircraft Research Association Limited (ARA) functions as an independent specialist delivering comprehensive wind tunnel services, including transonic tunnel operations designed for advanced aircraft concepts and next-generation aerospace configurations. Boeing Testing Services leverages a multi-facility portfolio encompassing the Transonic Wind Tunnel (BTWT), polysonic, subsonic, and icing tunnels, enabling customized aerodynamic, propulsion, and acoustic validation for complex aircraft programs. DNW (German-Dutch Wind Tunnels) provides advanced testing across subsonic to supersonic regimes, with specialized sites such as Marknesse supporting takeoff and landing configuration analysis alongside emerging rotorcraft and hydrogen-electric platform validation.
ONERA's Modane-Avrieux center operates six facilities capable of aerodynamic testing up to hypersonic speeds, supporting both civil and military aircraft development trajectories. RUAG Aerodynamics offers a large low-speed wind tunnel (LWTE) alongside complementary infrastructure, delivering end-to-end support spanning model design, instrumentation, testing, and full development cycle integration. AeroTEC specializes in the design, fabrication, instrumentation, and testing of complex wind tunnel models, with program management woven into its service delivery model. Lockheed Martin maintains low-speed and high-speed wind tunnel assets dedicated to aerodynamic force and moment characterization, store separation analysis, propulsion integration, and dynamic stability evaluation for aircraft and missile systems. Meanwhile, the privately operated San Diego Wind Tunnel (LSWT|SD) focuses on low-turbulence subsonic testing for scaled jet aircraft, unmanned platforms, and specialized aerospace applications.
Evaluating which provider aligns with a given program requires more than facility comparison. It demands an understanding of lead-time pipelines, instrumentation compatibility, data processing methodologies, and contractual flexibility under multi-phase testing schedules. The competitive positioning matrix, service differentiation themes, and recent capability upgrades that shape vendor selection are unpacked in detail within our market study.
Regulatory Mandates and Certification Economics
Physical wind tunnel validation is not optional in modern aerospace certification pathways. Regulatory authorities including the FAA, EASA, and CAAC mandate empirical aerodynamic validation through physical testing as a condition of type certification and ongoing airworthiness compliance. As aviation safety and performance criteria continue to tighten under evolving regulatory frameworks, the volume and complexity of required test campaigns have expanded accordingly. This regulatory floor creates a baseline demand that is relatively insulated from short-term economic volatility, while simultaneously raising the technical bar for testing service providers.
For program planners, the certification dimension introduces two strategic realities. First, test campaigns must be sequenced early enough to inform design iterations without triggering costly late-stage rework. Second, the data packages submitted for certification must withstand rigorous regulatory scrutiny, making instrumentation accuracy, repeatability, and documented calibration histories critical procurement criteria. Organizations that treat wind tunnel engagement as a transactional service rather than an integrated certification strategy often encounter schedule compression, data reconciliation challenges, and elevated compliance risk. The interplay between regulatory timelines, testing scope definition, and cost optimization is a recurring theme in our analysis, and readers seeking actionable frameworks for certification-aligned testing planning will find structured guidance in the full report.
Technology Drivers and Emerging Demand Vectors
The demand profile for wind tunnel testing services is being reshaped by several convergent technology trends. Hypersonic research programs are driving intensified utilization of transonic and supersonic facilities, as mission profiles push beyond conventional subsonic envelopes. Simultaneously, sustainable aviation objectives are accelerating testing around sustainable aviation fuel (SAF) compatibility, blended wing body configurations, truss-braced wing architectures, and alternative propulsion integration. These programs often require specialized model articulation, cryogenic or high-energy flow conditions, and advanced measurement techniques that strain legacy facility configurations.
Climatic Wind Tunnel Market
Recent industry activity underscores this shifting demand mix. In February 2026, Calspan Corporation was awarded a five-year contract with the U.S. Naval Test Pilot School for flight and related testing services, reinforcing long-cycle institutional demand for integrated aerodynamic and flight test support. Also in February 2026, DNW opened an Automotive Test Section at Marknesse while conducting helicopter rotor active twist testing and contributing to Beyond Aero hydrogen-electric aircraft evaluations, illustrating how established facilities are expanding into adjacent mobility and clean-propulsion domains. In December 2025, the Aircraft Research Association completed the design, fabrication, and testing of the SWiFT research wind tunnel model in its Transonic Wind Tunnel, highlighting continued investment in research-grade aerodynamic instrumentation and scaled concept validation. Earlier, in October 2025, Calspan's Transonic Wind Tunnel was featured for successful test system modernization, signaling ongoing capability upgrades that extend facility relevance across new test regimes. More recently, in May 2026, NASA and Boeing completed wind tunnel tests on a truss-braced wing concept for advanced aircraft design within the QinetiQ facility, demonstrating how collaborative testbed access supports high-visibility advanced configuration programs.
These developments are not isolated milestones; they are indicators of a market moving toward higher-complexity test articles, multi-disciplinary data capture, and cross-sector facility utilization. The precise allocation of testing demand across speed regimes, platform categories, and emerging application areas is detailed in the report's segmentation analysis, where service-level and platform-level revenue distributions provide a clearer picture of where capacity constraints and pricing dynamics are most pronounced.
Strategic Decision Frameworks for 2026 and Beyond
For aerospace manufacturers, defense prime contractors, emerging mobility developers, and testing service providers themselves, the 2026 landscape presents both opportunity and operational complexity. Organizations must decide how to balance in-house testing assets against external service partnerships, how to sequence model fabrication and instrumentation investments alongside tunnel availability, and how to structure contracts that accommodate iterative design changes without eroding margin or schedule integrity. Facilities operators, meanwhile, face the challenge of modernizing instrumentation suites, expanding hypersonic and sustainable-aviation test capabilities, and maintaining competitive positioning in a market where capital intensity limits new entry.
The strategic questions that matter most cannot be answered by headline market size alone. They require a disciplined assessment of segmentation dynamics, regional demand intensity, service-type pricing structures, and the evolving capability gaps among leading providers. They also require visibility into recent contract awards, facility modernization timelines, and collaborative testing arrangements that signal where capacity is tightening and where new access pathways are emerging. Our latest Aircraft Wind Tunnel Testing Services Market research is designed to provide that visibility. It translates macro-financial indicators into operational intelligence, maps competitive positioning against actual program requirements, and identifies the structural factors that will shape procurement strategy, partnership selection, and capacity planning through 2032.
The full study contains the segmented revenue breakdowns, regional demand distributions, service-type and aircraft-type market splits, concentration analysis, and provider-specific capability assessments that executives and analysts need to build defensible strategies. To access the complete dataset, detailed segmentation tables, competitive profiles, and forward-looking scenario analysis, we invite you to explore the full report through our official research portal. In a market defined by high infrastructure barriers, stringent certification requirements, and accelerating technological ambition, precision intelligence is not an advantage; it is the foundation of sound 2026 decision-making.
For detailed analysis of this topic, please visit the official page: Aircraft Wind Tunnel Testing Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com