
Blogs
The CMO Services Market: Strategic Trends and Commercial Opportunities in a High-Growth Landscape
Market Overview: Scale, Trajectory, and Structural Challenges
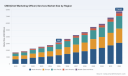
The executive marketing services market has transitioned from a niche advisory function into a core growth infrastructure for organizations navigating rapid digital and strategic change. Valued at approximately $3.2 billion in 2025, the market has expanded at a compound annual growth rate of 13.5 percent between 2020 and 2025, driven by shifting organizational priorities, the proliferation of fragmented marketing workloads, and the strategic recalibration of leadership capacity. Projections indicate the market will cross $5.9 billion by 2030 and reach $7.76 billion by 2032, reflecting sustained demand for specialized marketing leadership that bridges strategy, execution, and technology adoption. This trajectory places the CMO services space among the fastest-growing segments within the broader professional services and consulting ecosystem.
Behind the headline growth lies a structural inflection point. Organizations are no longer treating marketing leadership as a static, full-time executive appointment. Instead, they are decomposing the traditional CMO mandate into modular, outcome-oriented engagements. This shift is particularly pronounced among small and medium enterprises, which now account for a larger share of market activity than large enterprises. The fractional CMO model has become the dominant service architecture, reflecting a broader preference for scalable, variable-cost leadership that can be deployed across specific growth phases, market entries, or digital transformation initiatives. Strategic marketing consulting and digital transformation advisory represent the other major service pillars, each addressing distinct but overlapping organizational needs around positioning, go-to-market design, and technology-enabled execution.
Despite the strong growth trajectory, the market faces three interconnected challenges that will shape competitive dynamics over the next several years. First, demand fragmentation is outpacing standardization. Clients span multiple industries, growth stages, and regulatory environments, each requiring tailored leadership approaches, yet service providers are still consolidating repeatable frameworks that can scale without diluting effectiveness. Second, the talent supply chain remains constrained. The fractional CMO model depends on a pipeline of experienced marketing executives willing to operate across multiple engagements, and the limited depth of senior practitioners capable of managing AI-enabled, data-driven, and compliance-sensitive programs creates bottlenecks in high-demand verticals. Third, measurement and attribution expectations are rising faster than organizational maturity. Buyers increasingly expect clear ROI linkage, but many engagements still struggle to align strategic marketing inputs with quantified revenue outcomes, particularly in complex B2B and regulated environments. These challenges are not barriers to growth, but they are defining the terms on which providers will compete.
Key Drivers Shaping Market Expansion
Technological innovation is the most immediate catalyst reshaping demand for CMO services. Marketing organizations are adopting AI-enabled tools at a rapid pace, yet the gap between adoption and mature implementation remains wide. In 2026, three-quarters of marketing organizations reported using AI in some capacity, but only a small fraction had achieved mature deployment. This mismatch creates a structural need for strategic leadership that can translate technology capability into coherent marketing strategy, operating model design, and execution discipline. Fractional and advisory CMO engagements are increasingly anchored in AI-enabled marketing, digital transformation, and brand reinvention, particularly in sectors where experimentation velocity, personalization, and automation must be balanced with governance and compliance.
Regulatory and policy environments are also elevating the value of strategic marketing leadership. Data privacy expectations, content provenance concerns, and sector-specific compliance requirements are making marketing operations more complex, especially in healthcare, financial services, and other regulated industries. Organizations are finding that technology adoption alone does not resolve compliance risk; it requires leadership that can align marketing strategy with governance frameworks, data usage policies, and brand trust considerations. As a result, CMO services are expanding beyond growth acceleration into areas such as compliant demand generation, regulated content strategy, and cross-functional alignment between marketing, legal, and technology teams.
PW Consulting Information & Electronics Research Center
Demand-side behavior is shifting on both the buyer and consumer side. On the enterprise side, the rise of fractional leadership profiles has moved from experimental to mainstream. LinkedIn data shows a dramatic increase in profiles referencing fractional leadership roles, reflecting a broader organizational willingness to engage flexible executive talent for defined strategic missions. This adoption curve is reinforced by cost dynamics: fractional CMO engagements typically range from $3,000 to $15,000 per month, compared with full-time CMO total compensation that often falls between $275,000 and $500,000 annually. For many organizations, this cost differential is not simply about savings; it is about unlocking senior marketing leadership at a scale and duration that matches specific growth initiatives, market entries, or transformation programs.
Performance outcomes are reinforcing the demand shift. Organizations utilizing fractional CMO leadership have reported meaningfully stronger revenue growth compared with those operating without such leadership, suggesting that the model is delivering not only cost efficiency but also strategic lift. This is particularly relevant for B2B and B2B SaaS companies, where positioning, demand generation, product-led and sales-led integration, and repeatable go-to-market playbooks require experienced direction. The ability to embed leadership that can connect strategy with execution, analytical rigor, and team development is becoming a decisive factor in growth trajectories.
Cost structures and operating models are changing in parallel. Marketing budgets are under greater scrutiny, and organizations are increasingly optimizing for flexibility, specialized expertise, and measurable outcomes rather than fixed executive headcount. This is accelerating demand for service models that blend strategy, execution, analytics, and team capability building. Providers that can integrate SEO, content, analytics, and growth engineering into a coherent CMO-level engagement are positioning themselves to capture demand that would otherwise be spread across multiple agencies and consultants. The result is a market in which strategic marketing leadership is becoming more modular, more technology-integrated, and more closely tied to revenue outcomes.
Competitive Landscape and Leading Strategies
The competitive landscape is defined by a fragmented but increasingly specialized provider base. Market concentration remains relatively low, with the largest three participants holding roughly 12.5 percent of the market and the top five around 18.2 percent. This dispersion reflects the diversity of service models, industry focus, and operating approaches across the sector. Rather than competing on scale alone, leading providers are differentiating through vertical specialization, proprietary operating frameworks, and the ability to combine strategy with execution discipline.
Management Consulting Services Market
Several providers illustrate the strategic variety shaping the market. Chief Outsiders has built a broad fractional CMO and go-to-market executive practice focused on revenue growth, strategy, and execution across B2B, healthcare, and technology. Its recent executive additions reflect a deliberate push into digital transformation, AI-enabled marketing, brand reinvention, and sector-specific expansion across healthcare, financial services, technology, industrial, and infrastructure markets. This pattern signals a strategy of deepening sector coverage while broadening the leadership capability set required for complex transformation programs.
CMOx emphasizes process-driven strategy through a Functional Marketing Framework, focusing on team development, scalable growth, and agile marketing leadership. Its differentiation lies in operationalizing marketing leadership as a repeatable system rather than a purely advisory engagement. Kalungi, by contrast, has concentrated on B2B SaaS, with fractional CMO services centered on positioning, demand generation, product-led and sales-led growth integration, and execution playbooks such as T2D3. This vertical 좁히기 allows it to speak directly to the growth mechanics of software companies seeking predictable demand and scalable GTM motion.
Customer Insights Marketing Platform Market
NoGood targets high-velocity experimentation for SaaS, AI, fintech, and healthtech, blending growth engineering and rapid iteration with fractional leadership. Its positioning captures demand from technology-focused companies that value speed, testing discipline, and data-rich execution. Authentic Brand approaches the market through W-2 embedded fractional leadership, using an Authentic Growth framework that emphasizes alignment, change management, and sustained execution for B2B growth-stage companies. The emphasis on embedded leadership reflects a different answer to the same underlying need: not just strategy, but leadership presence that can drive organizational adoption.
Other participants illustrate further specialization. The Geisheker Group and Marketri focus on B2B and B2B SaaS, with emphasis on strategic direction, scalable systems, analytics, and ROI optimization. Digital Authority Partners blends fractional CMO services with analytics, SEO, and content for healthcare, regulated, and complex industries, where compliance and technical depth matter. Moving Minds emphasizes integrated strategy and execution across multi-channel marketing, serving sectors that include entertainment and private equity. Collectively, these providers demonstrate that the market is not converging on a single winning model; it is diversifying around industry focus, delivery model, and the balance between advisory and embedded execution.
The evolution of the competitive landscape is likely to move along three axes. First, consolidation will remain selective rather than wholesale. Larger consulting and services platforms may acquire or partner with specialized fractional CMO practices to add marketing leadership depth, but the market's fragmentation and vertical specificity will preserve room for independent specialists. Second, differentiation will increasingly hinge on measurable outcomes, operating frameworks, and technology integration rather than seniority alone. Providers that can connect leadership engagement to revenue growth, demand efficiency, and team capability will gain advantage. Third, new entrants will continue to emerge around AI-enabled marketing, regulated-industry compliance, and sector-specific GTM playbooks, particularly where demand is growing faster than the supply of experienced, sector-literate leaders. The market is therefore not simply expanding; it is becoming more structurally diverse, with competition shifting toward capability depth, delivery reliability, and evidenced impact.
Future Trends and Strategic Implications
Over the next three to five years, the CMO services market is likely to be shaped by three interrelated trends. The first is the maturation of AI-enabled marketing leadership. As adoption widens, the demand will shift from experimentation to integration: organizations will need leadership that can embed AI into positioning, content operations, demand generation, personalization, and performance measurement without losing strategic coherence. This creates opportunity for providers that can pair executive marketing leadership with practical AI operating models, governance, and change management. The risk is that AI capability becomes commoditized at the tool level, placing greater premium on the strategic judgment and execution discipline that sit above the technology layer.
The second trend is the continued expansion of sector-specialized fractional CMO services. Regulated and complex industries, B2B SaaS, fintech, healthtech, and industrial markets are all generating demand for leadership that understands both growth mechanics and sector constraints. Providers that develop deep vertical playbooks, compliance-aware execution, and repeatable GTM frameworks will be better positioned to command premium engagements and longer-term relationships. The counter risk is market overextension: providers that spread across too many verticals without sufficient depth may struggle to differentiate or deliver consistent outcomes.
The third trend is the growing expectation of outcome-linked engagements. As cost dynamics and performance data become more visible, buyers will increasingly compare fractional CMO engagements against full-time leadership not only on cost but on measurable revenue impact, team development, and execution reliability. This will reward providers that can articulate clear success metrics, embed analytics and accountability, and demonstrate how marketing leadership contributes to growth. A related uncertainty is the pace of organizational maturity: if measurement expectations rise faster than the ability to attribute marketing impact, some engagements may face heightened scrutiny, particularly in complex B2B and regulated contexts. The commercial opportunity lies in leading that transition rather than reacting to it.
Actionable Guidance for Decision-Makers
For organizations evaluating marketing leadership investments, the strategic priority is to match the service model to the mission. Fractional CMO engagements are most effective when tied to a defined growth phase, market entry, transformation program, or capability gap, rather than used as a generic substitute for executive headcount. Buyers should assess providers against vertical relevance, operating framework clarity, execution capability, and evidence of revenue impact, not just seniority or brand presence. For investors and strategic partners, the opportunity lies in providers that combine sector specialization with measurable outcomes and AI-ready operating models, since these characteristics are likely to command durable demand as the market matures. For service providers and ecosystem participants, the imperative is to strengthen delivery consistency, attribution rigor, and team development capabilities, because these will increasingly separate scaled impact from advisory only engagements.
Given the speed of change across AI adoption, sector demand, and leadership models, decision-makers benefit from current, segmented intelligence that goes beyond headline growth figures. Detailed segmentation data, provider benchmarking, and sector-specific demand signals can sharpen procurement decisions, partnership strategies, and investment timing. For organizations seeking a more granular view of service type dynamics, regional demand patterns, business-size adoption, and competitive positioning, the full PW Consulting research report provides expanded data and customized strategic guidance to support more precise planning.
For detailed analysis of this topic, please visit the official page: CMO(Chief Marketing Officer) Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Bathroom Product Market 2026: 5.85% CAGR Growth Drivers & Key Shifts Until 2032
By pmarketresearch, 2026-09-18
The Changing Face of the Global Bathroom Product Market: Strategic Trends and Commercial Opportunities
Market Landscape: Size, Growth, and Structural Headwinds
The worldwide bathroom product market has transitioned from a mature, slow-growth sector into a structurally expanding market defined by steady capital deployment, product differentiation, and regional recalibration. Over the past half-decade, the industry moved from just under 100 billion USD in 2020 to approximately 128 billion USD in 2025, reflecting consistent annual expansion despite periodic supply disruptions and shifting demand patterns. The forward trajectory points to continued growth, with the market projected to reach roughly 137 billion USD by 2026 and approach 191 billion USD by 2032. This implies a compound annual growth rate of approximately 5.85 percent across the forecast horizon, a pace that signals more than cyclical recovery and instead indicates underlying shifts in how bathroom spaces are designed, purchased, and experienced. Growth is being distributed across the full product spectrum, from foundational ceramic sanitaryware to faucets, showers, vanities, and bathtubs, with the mix continually weighted by regional consumption habits and construction activity.
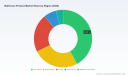
The regional footprint of the market reflects long-standing demand centers alongside faster-moving emerging corridors. Asia Pacific currently accounts for the largest share of global consumption, supported by strong residential construction, urbanization, and increasing per-capita spending on bathroom upgrades. North America and Europe together represent a substantial portion of the market, anchored by replacement demand, renovation cycles, and a consumer base that increasingly values design-led and water-efficient solutions. Latin America and the Middle East and Africa, while smaller in absolute scale, contribute meaningful pockets of growth tied to infrastructure development and expanding middle-class households. Distribution channels remain anchored in offline retail and wholesale networks, reflecting the tactile, specification-driven nature of many bathroom purchases, though digital channels continue to gain traction for catalog browsing, comparison, and direct-to-consumer experimentation. The market remains relatively fragmented, with no single company commanding dominant share, and the top few players collectively representing a modest concentration. This open structure creates room for new entrants, brand differentiation, and targeted geographic expansion.
Despite the favorable growth trajectory, the market faces several structural challenges that will shape competitive outcomes over the next several years. First, input cost volatility and material availability continue to pressure margins across ceramic production, metal fabrication, and finishing processes. Fluctuations in raw material pricing and energy costs have forced manufacturers to balance price increases with consumer sensitivity, particularly in mid-tier segments where substitution and deferred purchases are more likely. Second, regulatory pressures around water efficiency, safety, and sustainability are reshaping product requirements and compliance timelines. Buyers and specifiers increasingly expect fixtures that reduce consumption without compromising performance, while safety standards in certain categories, including infant and baby bath products, have drawn heightened scrutiny and recall activity. Third, trade policy uncertainty adds complexity to cross-border sourcing strategies. Announcements regarding potential tariffs on imported bathroom vanities and related products illustrate how quickly cost structures and supply routes can be disrupted, prompting companies to reconsider manufacturing footprints, inventory buffers, and regional sourcing mixes. These challenges do not threaten the overall growth narrative, but they do raise the bar for operational agility, product planning, and market entry timing.
Core Drivers Reshaping Demand and Competitive Advantage
Technology innovation is moving from a differentiator to a baseline expectation in bathroom products. Smart fixtures, sensor-based faucets, thermostatic shower controls, and integrated hygiene features are increasingly appearing across premium and mid-premium segments, driven by consumer interest in convenience, water management, and modern aesthetics. Recent trade show activity highlights how quickly product roadmaps are evolving. At the International Bathroom Exhibition in Milan in 2026, multiple manufacturers showcased sustainable materials, connected functions, and refined design language as central themes. The same pattern appeared at the Kitchen & Bath Industry Show in Orlando in 2026, where launches emphasized smart fixtures and sustainable solutions. These events reflect a broader shift in product strategy: companies are no longer treating smart features as isolated gadgets, but as part of integrated bathroom experiences that combine water efficiency, user interface design, and durability. TOTO’s unveiling of next-generation smart, sustainable, and luxury innovations, including matte color vessel lavatories at KBIS in 2025, illustrates how leading brands are pairing surface aesthetics with functional sophistication to capture attention in crowded showrooms and specification processes.
Policy and regulatory dynamics are equally influential in shaping product selection and market access. Water-saving requirements, safety mandates, and sustainability certifications are becoming more visible in procurement criteria and consumer preferences. The broader industry context is also seeing sustainability move into event and supply-chain standards themselves, as reflected by CERSAIE’s ISO 20121:2024 certification for sustainable event management in the ceramic tile and bathroom furnishings sector. Such signals matter because they indicate that sustainability is being institutionalized across the value chain, not simply used as a marketing message. For manufacturers and distributors, this means that compliance readiness, documentation, and transparent sustainability claims are becoming part of competitive positioning. Regulatory attention in specific categories can also have immediate commercial consequences. Recent safety warnings and recalls involving unstable infant and baby bath seats point to the importance of design validation and post-market monitoring, especially for products used by vulnerable populations. Companies that embed rigorous testing and usability review into product development are better positioned to avoid disruptions and protect brand trust.
Consumer and specifier behavior is shifting in ways that favor design coherence, performance reliability, and total cost perception. In renovation and new-construction settings, bathroom decisions are increasingly made with a broader view of water usage, maintenance, and long-term durability rather than initial sticker price alone. Ceramic continues to hold strong appeal in sanitaryware due to its durability and chemical resistance, a reputation that supports its continued dominance in many markets. At the same time, consumers are responding to broader style shifts, including matte finishes, integrated vanities, and coordinated fixture families that make smaller or aging bathrooms feel more contemporary. The purchasing journey is also evolving. Offline retail and wholesale channels still handle the majority of transactions because bathroom products often require physical evaluation, measurement, and installation coordination. Yet online channels are growing as a discovery and comparison layer, and in some cases as a transaction channel for accessories, replacement parts, and simpler fixtures. This dual-channel reality means that brands must maintain consistent product information, visual presentation, and availability signals across both environments to avoid losing prospects during the specification journey.
Supply chain and cost structure changes are becoming a strategic variable rather than a background condition. Tariffs and trade policy risk can quickly alter the economics of imported vanities and related bathroom products, and operators in North America and other import-dependent markets have had to plan for potential cost shocks. In parallel, producer price movements in key manufacturing regions have affected the economics of ceramic sanitary fixtures. Recent eurozone data showed producer prices for ceramic sanitary fixtures in France at elevated index levels in late 2025, underscoring how regional cost conditions can differ materially even within a globalized industry. These dynamics are encouraging companies to diversify sourcing, consider regional production or assembly where feasible, and improve demand forecasting to reduce inventory risk. For suppliers that can manage cost, quality, and lead times simultaneously, the current environment offers an opportunity to win share from competitors that are slower to adapt their sourcing or pricing models.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive field is broad and geographically diverse, with strong representation from established multinational brands and increasingly capable regional players. Kohler continues to compete on the strength of a comprehensive product range spanning faucets, showers, sinks, toilets, bidets, and smart fixtures, with emphasis on design, water efficiency, and the residential and commercial segments. TOTO has built a reputation around advanced sanitaryware, smart toilet systems, and water-saving technology that links hygiene, sustainability, and luxury performance. LIXIL operates through a portfolio of well-known brands and offers complete bathroom solutions across faucets, showers, sanitaryware, and water-efficient systems for global use. Roca combines ceramic sanitaryware, faucets, showers, and bathroom furniture with a focus on design, sustainability, and quality. Geberit is distinct in its emphasis on concealed plumbing systems and innovative bathroom technologies for both commercial and residential installations. European premium players such as Villeroy & Boch and Duravit compete through luxury design, high-quality materials, and modern aesthetics, while Hansgrohe focuses on premium shower systems and faucets with water-saving technology and design-led positioning. In the North American market, American Standard and Moen maintain strong recognition for reliable, accessible fixtures, and Masco plays a significant role through brands that serve residential plumbing needs. In emerging markets, RAK Ceramics, Jaquar, CERA, and Hindware are expanding the middle-to-premium pipeline, using local market knowledge and scale to compete across sanitaryware, faucets, and related products.
The differentiating success factors in this landscape are becoming clearer. First, product breadth and system thinking matter. Companies that can offer coordinated faucets, showers, sanitaryware, and vanities reduce friction for specifiers and renovators who want a unified look and predictable installation outcome. Second, technology integration and water efficiency are increasingly linked to brand relevance. Smart functions, flush performance, sensor-based hygiene, and reduced water consumption are no longer niche features; they are central to winning in premium and semi-premium segments where buyers expect a combination of comfort and sustainability. Third, regional credibility remains powerful. Multinational brands benefit from global scale and design language, but regional players often win by tailoring products to local tastes, price points, and installation practices. This is especially visible in markets where bathroom styles, water conditions, and consumer price sensitivity differ substantially from the global average.
Bathroom Vanities Market
The market structure is evolving through a mix of consolidation pressure and segmentation depth. Concentration remains moderate, which leaves space for brand specialization and regional expansion, but the competitive center of gravity is shifting toward companies that can manage design, technology, and supply chain performance at the same time. Recent industry events suggest that innovation is being presented in more integrated ways, with sustainability, technology, and design presented as a combined narrative rather than separate product claims. This points to a future in which the winners are less defined by a single hero product and more by the ability to deliver consistent experiences across categories. At the same time, new entrants and brand extensions continue to test niche positioning in wellness, designer collaborations, and smart home connectivity, keeping the market dynamic. The most important structural question for incumbents is whether they can scale innovation without eroding the margin and quality control that support premium positioning.
Forward Outlook: Three Trends Shaping the 2026–2030 Horizon
One of the clearest forward trends is the accelerating normalization of smart and water-conscious bathroom products as mainstream expectations rather than premium add-ons. Over the next few years, sensor-driven fixtures, efficient flush technologies, and more intuitive control interfaces are likely to move further down the price pyramid as manufacturing processes mature and component costs stabilize. This will create opportunity for brands that can deliver reliability and simple user experiences rather than feature-heavy products that complicate installation or maintenance. The commercial opportunity lies in specification-friendly systems that help contractors and renovators meet efficiency goals without sacrificing design quality, especially in multifamily housing, hospitality, and renovation programs where long-term operating costs matter.
A second trend is the growing importance of regional supply resilience and pricing agility. Trade policy uncertainty, raw material price variation, and shifting production costs will continue to reward companies that can adjust sourcing strategies and portfolio pricing with speed. This does not necessarily mean abandoning global sourcing, but it does favor organizations that maintain flexible manufacturing networks, clear visibility into cost drivers, and disciplined portfolio management. Businesses that can hold quality steady while responding to tariff exposure and input price movement will gain share in markets where competitors are slower to recalibrate. There is also an opportunity in mid-market segments, where consumers may delay upgrades if price increases outpace perceived value, making value engineering and design coherence particularly important.
A third trend is the continued blending of hygiene, wellness, and design in bathroom product offers. Post-pandemic attention to cleanliness did not disappear; it evolved into broader expectations for easy-to-clean surfaces, controlled water contact, and finishes that support both aesthetics and maintenance. Combined with consumer interest in spas, relaxation, and contemporary interiors, bathroom products are increasingly positioned as part of a wellness experience rather than purely utilitarian fixtures. The risk here is that trend-led launches can outpace practical performance, especially if features add complexity or reduce durability. Companies that balance style with robust engineering and clear installation guidance will be better positioned to convert interest into repeat business and favorable specification outcomes. A related uncertainty is the pace of regulatory change and trade policy adjustments, which can alter regional economics quickly and require companies to revise launch timing, channel strategy, and sourcing plans with limited lead time.
Actionable Priorities for Decision-Makers
For manufacturers, the priority is to strengthen portfolio coherence and reduce friction across the specification-to-installation journey. That means aligning faucets, sanitaryware, showers, and vanities in ways that make it easier for buyers to choose a complete solution, while ensuring that smart and water-saving features add genuine value rather than complexity. Equally important is building flexibility into sourcing and pricing so that potential tariff exposure and raw material movement can be managed without sudden erosion of margin or inconsistent product availability. Companies that can demonstrate reliable lead times, stable quality, and clear sustainability and safety documentation will have an advantage when specifiers compare options.
PW Consulting
For investors, the opportunity lies in identifying operators with durable brand relevance, disciplined cost structures, and the ability to scale innovation without compromising quality. The market’s moderate concentration and continued growth create room for selective value creation, especially where companies have strong regional positioning or differentiated technology in water efficiency, hygiene, or designer appeal. Attention should be paid to supply chain resilience and product mix, since businesses overly reliant on a narrow set of cost-sensitive inputs or import-heavy routes may face more volatility than peers with diversified production and channel strategies.
For procurement and retail leaders, the strategic task is to keep product information, availability, and visual presentation consistent across offline and online touchpoints while managing exposure to policy and cost shocks. This includes developing clear category plans that balance replacement demand with upgrade cycles, maintaining relationship strength with installation partners, and using flexible sourcing options to reduce vulnerability to tariff-related price increases. For deeper segmentation detail, regional sizing, competitive share estimates, and channel-specific scenarios, the full research report provides the supporting data and structured frameworks needed for more precise portfolio and sourcing decisions.
Toilet Seat Market
For detailed analysis of this topic, please visit the official page: Worldwide Bathroom Product Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
p.p'-Dibromobiphenyl Market Outlook: Why 4.12% CAGR Masks SKU-Level Value Shifts Through 2032
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the p.p'-Dibromobiphenyl Market
Market Overview and Core Challenges
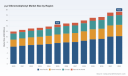
The p.p'-Dibromobiphenyl market has demonstrated steady, incremental growth over the past half-decade, transitioning from a niche specialty chemical segment to a recognized component in advanced materials supply chains. Valued at approximately USD 11.95 million in 2020, the overall market expanded to an estimated USD 14.5 million in 2025, reflecting a compound annual growth rate of roughly 4.12% projected through 2032. This trajectory underscores a maturing but still evolving ecosystem where demand is increasingly tied to high-performance electronic materials and specialty polymer applications. The market structure remains moderately concentrated, with the top three players accounting for approximately 64% of total revenue and the top five representing over 81%. Such concentration suggests established relationships between key manufacturers and end-users, yet also leaves room for agile entrants and regional specialists to capture value through differentiation in purity, logistics, or service integration.
Despite the positive growth trajectory, the segment faces several structural challenges that are reshaping how participants navigate pricing, compliance, and capacity allocation. First, raw material volatility has become a persistent pressure point. Bromine pricing has experienced sharp fluctuations in recent months, with Chinese supply experiencing a notable 46% surge between mid-2025 and early 2026, while Northeast Asian and European markets have seen more moderate but still upward movements. These swings cascade into synthesis costs, affecting margin resilience for producers who lack hedging strategies or diversified sourcing arrangements. Second, regulatory scrutiny around polybrominated biphenyl compounds continues to tighten across major jurisdictions. Substances falling within this chemical family are subject to monitoring frameworks that emphasize environmental persistence and aquatic toxicity, prompting stricter documentation requirements, supply chain transparency, and end-of-life considerations for downstream users. While p.p'-Dibromobiphenyl itself is not broadly restricted, its regulatory adjacency introduces compliance overhead and can influence procurement preferences toward fully traceable, audited supply lines. Third, the market is experiencing a divergence in purity expectations across application tiers. Certain end-use segments prioritize cost-efficient intermediate grades, while advanced electronic and pharmaceutical-adjacent applications demand consistent high-purity specifications with rigorous batch-to-batch validation. Balancing these competing requirements without compromising operational efficiency or qualification timelines remains a central challenge for producers and buyers alike.
Key Drivers Shaping Market Dynamics
Technological Innovation and Material Advancements
Progress in electronic materials and specialty polymers continues to anchor demand for brominated biphenyl derivatives. The compound serves as a building block in the synthesis of organic semiconductors and small-molecule materials, where precise substitution patterns and controlled purity levels directly influence device performance. Concurrently, liquid crystal polymer formulations increasingly rely on specialized intermediates to achieve targeted thermal stability, mechanical strength, and processing characteristics. These applications reward suppliers that can provide consistent specifications, robust technical data packages, and responsive support during product qualification cycles. The trend is not merely about volume; it is about reliability and technical compatibility. Manufacturers able to standardize production protocols, reduce impurity profiles, and streamline documentation are gaining an edge in applications where development timelines are compressed and failure costs are high.
Worldwide Bromobenzene Market
Regulatory and Compliance Evolution
The regulatory landscape is reinforcing a preference for transparent, documented supply chains. Monitoring frameworks for brominated compounds place additional emphasis on environmental fate, aquatic toxicity, and responsible handling across the value chain. In practice, this translates into more rigorous batch testing, clearer safety data alignment, and enhanced traceability from feedstock to finished intermediate. Companies that proactively align with these expectations are better positioned to serve multinational end-users who must satisfy internal audit requirements and downstream compliance obligations. The regulatory environment also encourages regional diversification of supply, as procurement teams seek to reduce exposure to concentrations that could be disrupted by policy shifts or inspection regimes. Over time, compliance capability is becoming a competitive differentiator rather than a baseline cost of doing business.
Demand-Side Shifts in Electronics and Specialty Chemicals
Demand patterns are being shaped by the expansion of high-value applications that require controlled molecular architectures. Organic light-emitting diode material intermediates represent one of the larger demand pools, driven by continued development in display technologies and related optoelectronic components. At the same time, liquid crystal polymer uses are supported by sectors that value dimensional stability, chemical resistance, and performance under demanding operating conditions. Beyond these core uses, laboratory and analytical applications sustain a steady baseline of demand, particularly among organizations that require certified reference materials or high-purity samples for method development and quality assurance. Across these segments, buyers are increasingly balancing cost considerations against the need for consistency, lead-time reliability, and technical support. This shift favors suppliers that can present clear value propositions beyond unit price alone, including packaging flexibility, inventory availability in key regions, and documented purity verification.
Supply Chain and Cost Structure Dynamics
Cost structures are being influenced by feedstock dynamics and regional capacity configurations. Bromine pricing has been notably volatile, with significant increases observed in China and upward pressure recorded across Northeast Asia and Europe. These movements affect not only direct input costs but also the economics of transportation, warehousing, and inventory planning for intermediaries and end-users. At the same time, the broader biphenyl feedstock environment remains sensitive to benzene-related volatility, adding another layer of uncertainty to upstream economics. In response, many participants are reevaluating sourcing strategies, exploring longer-term supply agreements, and considering regional production footprints that reduce exposure to single-market shocks. Capacity expansion in certain locales has also introduced a more tiered supply environment, where scale players compete on volume and cost while specialty suppliers compete on purity, certification, and application-focused service. This bifurcation is gradually redefining negotiation dynamics and encouraging more segmented procurement strategies.
Competitive Landscape and Leading Strategies
The competitive field blends established specialty chemical suppliers with regional manufacturers that have expanded their footprint through targeted product positioning. Tokyo Chemical Industry Co., Ltd. (TCI) exemplifies a reagent-focused model, offering p.p'-Dibromobiphenyl as a building block for organic semiconductors and small-molecule materials, with packaging options tailored to laboratory and pilot-scale needs and inventory positioned in Japanese warehouses. This orientation emphasizes availability, specification clarity, and support for research and early-stage development workflows. On the pharmaceutical-adjacent side, Simson Pharma Limited and Pharmaffiliates approach the material as a reference standard and analytical/reuse-grade intermediate, aligning their offerings with documentation rigor and traceability that appeal to regulated environments. Deep Pharm Chem further reinforces this angle through certified quality systems and assay specifications suited to analytical applications. In the manufacturing segment, several China-based producers, including Alfa Chem, Zhejiang Free Trade Zone Violet Trade Co., Ltd., Nantong Reform Petro-Chemical Co., Ltd., Henan Violet Technology Co., Ltd., Mascot Chem, and Ruifu Chem, demonstrate a spectrum of capabilities ranging from cost-efficient bulk supply to higher-purity pharmaceutical-grade output. Ruifu Chem’s export-oriented presence across multiple regions highlights how certain suppliers leverage scale and logistics to serve diverse downstream markets, while others differentiate through purity tiers and melting-point specifications that cater to particular application tolerances.
Leading players are pursuing differentiation along three primary axes: purity and specification control, application-specific packaging and service, and geographic availability. Suppliers that can demonstrate tight control over assay, impurity profiles, and batch consistency are gaining preference in segments where downstream processing is sensitive to variability. Packaging flexibility, from small-scale trial quantities to multi-ton batches, allows manufacturers to serve both early-stage qualification and larger production campaigns without forcing customers into suboptimal inventory commitments. Geographic positioning also matters; having stock or production capacity near key demand centers reduces lead times and improves responsiveness during qualification windows or supply disruptions. These strategic choices are especially relevant given the market’s moderate concentration, where incumbents hold meaningful share but do not fully lock out competitors that offer compelling technical or commercial combinations.
4,4-Biphenol Market
The landscape is evolving through a blend of consolidation pressure and niche expansion. On one hand, larger entities benefit from established supplier qualifications, broader distribution networks, and the ability to absorb raw material fluctuations more effectively. On the other hand, regional manufacturers and specialized suppliers continue to enter or expand by focusing on purity grades, certification depth, or application-aligned technical support. New entrants that can deliver consistent quality, transparent documentation, and reliable logistics are finding pathways into procurement considerations, particularly where incumbent supply is constrained or where end-users seek to diversify risk. The result is a market that is neither fully commoditized nor tightly controlled, but rather segmented by value drivers that reward capabilities beyond simple volume pricing.
Forecasting the Next Three to Five Years
Several interconnected trends are likely to shape the market through the end of the decade. First, purity segmentation will become more pronounced as downstream applications continue to differentiate. Higher-purity offerings will remain critical for electronic materials and regulated environments, while intermediate grades will continue to serve cost-sensitive polymer and specialty synthesis uses. Suppliers that can efficiently manage multiple purity tiers within streamlined operations will be better positioned to capture demand across segments without diluting margin quality. Second, supply chain resilience will move from a procurement preference to a strategic requirement. Given the observed volatility in bromine pricing and the sensitivity of feedstock economics, buyers and producers alike will increasingly favor arrangements that reduce exposure to abrupt cost shocks and regional disruptions. This may include longer-term agreements, diversified sourcing, inventory buffering in strategic locations, and closer collaboration between suppliers and end-users on demand forecasting. Third, regulatory and documentation expectations will continue to intensify, reinforcing the value of traceability, certified quality systems, and clear safety and handling information. Companies that treat compliance as part of their value proposition, rather than a back-office function, will find it easier to qualify in multinational supply chains and to maintain preferred-supplier status over time.
These trends create clear commercial opportunities for participants willing to invest in differentiation and operational discipline. Producers that align capacity with application-specific purity needs, strengthen documentation, and secure reliable feedstock access can command more stable negotiations and improve customer retention. For buyers, the opportunity lies in building multi-source strategies that balance cost, quality, and continuity, while avoiding overreliance on a single region or supplier tier. At the same time, uncertainty persists. Raw material pricing could continue to fluctuate, regulatory definitions and monitoring expectations may evolve, and demand from electronic materials applications remains linked to broader technology adoption cycles. Navigating these variables will require continuous monitoring of pricing signals, feedstock conditions, and policy developments, as well as the flexibility to adjust sourcing and production strategies as the landscape changes.
Actionable Recommendations for Decision-Makers
For manufacturers, the priority is to align product portfolios with the purity and documentation expectations of the most value-intensive applications while maintaining efficient pathways for intermediate-grade demand. Investing in batch consistency, certification readiness, and technical support capabilities can improve positioning with end-users who prioritize reliability in qualification and scale-up. Exploring feedstock hedging or diversified sourcing arrangements may also help cushion the impact of bromine price volatility and improve margin predictability.
PW Consulting Chemical & Energy Research Center
For investors, the market’s moderate concentration and segmentation by purity, application, and geography suggest selective opportunities rather than broad-based exposure. Due diligence should focus on suppliers with demonstrated quality systems, credible export capabilities, and supply chain practices that reduce regulatory and operational risk. Tracking feedstock economics and regional pricing trends will be essential for assessing cost resilience and long-term competitiveness.
For procurement teams, a balanced sourcing strategy that combines primary suppliers with qualified alternates can mitigate disruption risk while preserving cost discipline. Prioritizing partners that offer transparent documentation, consistent specifications, and flexible packaging can shorten qualification cycles and improve supply continuity. As regulatory expectations and raw material dynamics continue to evolve, maintaining access to current market intelligence will be valuable for timing contracts, evaluating regional sourcing options, and anticipating shifts in supplier capability.
For organizations seeking a more granular view of regional demand patterns, purity-grade economics, application-level volume trajectories, and competitive positioning, a comprehensive market study can provide the detailed segmentation and scenario context needed for planning. Deeper data on pricing structures, capacity developments, and compliance-related purchasing behavior can support more precise sourcing decisions, investment prioritization, and product strategy refinement.
For detailed analysis of this topic, please visit the official page: p.p'-Dibromobiphenyl Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Fluorozirconic Acid Market: Asia Pacific's 4.6% CAGR Leads to $71.8M by 2032
By pmarketresearch, 2026-09-18
Scaling Production, Navigating Volatility: Strategic Dynamics in the Global Fluorozirconic Acid Market
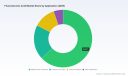
The worldwide fluorozirconic acid market has entered a phase of measured expansion, characterized by steady revenue growth, shifting regional purchasing patterns, and evolving supply chain economics. From 2020 through 2025, the sector demonstrated consistent demand absorption across industrial and specialty applications, with total market revenue reaching approximately 52.4 million in the most recent base year. Looking ahead to the forecast horizon ending in 2032, the market is projected to maintain a compound annual growth rate of 4.6 percent, gradually scaling toward the mid-70 million range. This trajectory reflects a market that is neither in hyper-growth nor in structural decline, but rather in a maturation stage that rewards disciplined capacity planning, application diversification, and supply chain resilience.
Current industry conditions present a set of interlocking challenges that will define competitive outcomes over the next several years. First, raw material input volatility remains a persistent pressure point. The primary feedstocks required for fluorozirconic acid synthesis have experienced notable price fluctuations, particularly in key producing regions, forcing manufacturers to navigate margin compression while attempting to preserve pricing stability for downstream buyers. Second, regulatory and environmental compliance requirements are tightening across multiple jurisdictions, altering procurement standards and raising the operational baseline for production facilities. Third, the market is experiencing a gradual realignment in how purchasing organizations evaluate supply partners, shifting from pure price optimization toward reliability, technical support, and consistent specification compliance. These forces are compelling companies to recalibrate their operating models rather than rely on historical growth assumptions.
The broader market structure also reflects meaningful concentration dynamics. A relatively small group of established participants accounts for a substantial share of total industry revenue, indicating that scale, technical reputation, and long-standing distribution networks continue to exert strong influence on commercial positioning. At the same time, the presence of mid-tier manufacturers and regional suppliers signals an ecosystem that retains room for specialized entrants, particularly those capable of serving specific application verticals or concentration requirements. This combination of concentration and fragmentation creates a competitive environment where differentiation is increasingly tied to execution quality rather than product novelty alone.
For executives and strategic planners, the immediate implication is clear: the market rewards operators who can balance cost discipline with service reliability. Companies that treat fluorozirconic acid as a commodity input risk exposure to margin swings and supply disruptions, while those that integrate the chemical into broader application ecosystems—such as surface treatment workflows, specialty glass processing, or catalyst formulations—can capture more defensive margin profiles. Similarly, procurement teams face a market in which supplier selection has become a strategic decision, not a routine purchasing task. Understanding where capacity is expanding, where feedstock economics are shifting, and how regional demand is evolving will separate organizations that simply absorb cost pressure from those that convert market dynamics into commercial advantage.
Key Drivers Reshaping Market Trajectory
Market movement in fluorozirconic acid is being shaped by a combination of technical, regulatory, demand-side, and cost-structure factors. These drivers do not operate in isolation; they interact in ways that determine which applications grow, which production regions gain leverage, and how suppliers position themselves for the forecast period.
PW Consulting
Technical Innovation and Application Expansion
Advancements in process efficiency and application engineering are gradually reshaping how fluorozirconic acid is produced and utilized. On the production side, manufacturers are increasingly focused on optimizing concentration consistency, reducing impurity profiles, and improving batch-to-batch reliability. These improvements matter particularly for industries where chemical performance directly affects downstream outcomes, such as metal surface treatment and optical glass manufacturing. In parallel, application-side innovation is expanding the relevance of fluorozirconic acid beyond legacy use cases. Surface treatment formulations continue to evolve as manufacturers seek stronger corrosion resistance, better adhesion characteristics, and more controlled conversion coating performance. In ceramics and glass segments, the chemical's functional role in specialized processing has supported steady demand from producers looking to maintain material quality while managing cost structures.
For businesses, this means the value of fluorozirconic acid is increasingly tied to performance reliability rather than volume alone. Suppliers that can demonstrate consistent specifications, provide technical guidance, and adapt to formulation changes are better positioned to retain and expand account relationships. Conversely, buyers that standardize on poorly characterized supply risk quality variability that can cascade into production inefficiencies.
Policy and Regulatory Environment
Regulatory expectations are becoming a more prominent factor in procurement and manufacturing decisions. Environmental compliance, chemical handling standards, and industrial safety requirements are influencing how producers operate and how end-users qualify suppliers. In several regions, tighter oversight of fluoride-related chemicals and related industrial processes has raised the bar for documentation, traceability, and operational controls. These requirements are not uniform across markets, which creates a differentiated landscape where companies with stronger compliance systems can use them as a commercial asset rather than viewing them purely as cost centers.
The policy environment also interacts with trade dynamics. Cross-border supply arrangements are increasingly evaluated through the lens of regulatory alignment, customs considerations, and long-term supply assurance. As a result, organizations that depend on imported fluorozirconic acid are placing greater emphasis on supplier consistency, certification coverage, and regional availability. This dynamic favors established distributors and manufacturers with clear compliance records, while raising the entry threshold for less-documented supply sources.
Demand-Side Behavior and Industrial Purchasing Patterns
End-user demand is evolving in ways that influence both volume and purchasing behavior. In metal surface treatment, continued industrial activity and maintenance-driven coating requirements sustain baseline consumption, while performance expectations push buyers toward products that deliver predictable results across varied substrates and process conditions. In specialty applications such as ceramics, glass, and chemical catalysis, demand tends to be more sensitive to production cycles, capital investment patterns, and formulation changes. This creates a market where some segments behave as steady industrial consumables, while others are more cyclical or innovation-driven.
A notable shift in purchasing behavior is the growing preference for suppliers who can support application-specific needs rather than simply offer the lowest unit price. Procurement teams are increasingly weighing specification consistency, availability, technical communication, and delivery reliability. This trend rewards suppliers with stronger customer-facing capabilities and creates an opportunity for manufacturers to differentiate through service, not just chemical grade.
Supply Chain and Cost Structure Dynamics
Cost structure remains one of the most important market levers, and feedstock economics are central to that picture. Hydrofluoric acid, a primary input for fluorozirconic acid production, has experienced meaningful price movements in recent periods. In the Chinese domestic market, prices moved upward over the course of 2025, reflecting broader input cost pressures and regional supply conditions. By early 2026, fluorozirconic acid-linked feedstock pricing in China was observed in a higher range than historical norms, tightening cost calculations for producers and affecting the economics of export-oriented supply. In Europe, intra-EU hydrofluoric acid transaction prices remained elevated at the start of 2026, sitting substantially above pre-2019 levels and reinforcing cost challenges for regional manufacturers.
At the same time, upstream zirconium mineral availability has provided a degree of feedstock foundation for zirconium-based chemicals. Global mine production of zirconium mineral concentrates rose to an estimated 1.5 million tonnes in 2024, supporting broader feedstock availability for downstream chemical processing. This does not eliminate cost volatility, but it does indicate that the raw material base underpinning zirconium chemistry remains functional and, in aggregate, expanding. The market implication is nuanced: availability is not the primary constraint, but price transmission from feedstock markets to finished fluorozirconic acid is a persistent factor that operators must manage through pricing strategy, contract structuring, and production efficiency.
Competitive Landscape and Strategic Positioning
The competitive environment in fluorozirconic acid is defined by a mix of established manufacturers, regional producers, and distribution-focused suppliers. Market concentration is significant, with a relatively small set of participants capturing a majority share of industry revenue. This structure reflects the importance of production experience, specification reliability, and established commercial relationships in a market where downstream users place high value on consistency.
European-based manufacturers continue to hold a recognized position in the market, particularly where high-quality production standards and long-standing supply track records matter. Companies operating from Spain and the broader European region have built reputations around industrial-grade reliability and global distribution capability, often aligning their commercial positioning with compliance, product consistency, and established customer relationships. Their strategic advantage typically lies in perceived quality assurance and the ability to serve industrial customers that prioritize specification stability over aggressive price competition.
Hydro Fluoric Acid Market
Chinese manufacturers represent a substantial portion of the supply landscape, reflecting both domestic demand and export-oriented production. Several firms based in Foshan, Nantong, Hunan, Yixing, and other industrial centers supply fluorozirconic acid for metal surface treatment, optical glass, fluorozirconate production, and related industrial applications. These producers often compete on a combination of pricing, production scale, and the ability to serve multiple downstream verticals. Their market role is shaped by access to feedstock inputs, production flexibility, and the capacity to support both wholesale and industrial-grade requirements. In many cases, Chinese suppliers have become integral to global supply chains by offering a broad range of concentration options and application-aligned product formats.
Outside of Europe and China, other regional players contribute to the market's diversity. Indian manufacturers supplying multiple concentration grades for technical applications have built export-oriented businesses that serve a range of international buyers. In the United States, certified distributors and global raw material suppliers provide fluorozirconic acid through established logistics and quality management frameworks, often positioning themselves as reliable intermediaries for industrial customers that need documented compliance and consistent availability. In the United Kingdom, distributors focused on bulk industrial packaging and customer-specific delivery configurations add further supply chain flexibility, particularly for buyers that prioritize handling convenience and large-volume order execution.
The strategic differences among these participants are instructive. Some compete primarily through production efficiency and price competitiveness; others differentiate through certification, documentation, technical support, or specialized packaging and logistics. The most resilient players tend to combine several of these strengths rather than rely on a single attribute. A manufacturer that can offer consistent specifications, maintain dependable lead times, and respond to application-specific requirements is better positioned than one competing on price alone, especially in a market where feedstock cost volatility can quickly erode thin margins.
Market evolution is likely to continue along two parallel paths. On one hand, consolidation pressure may intensify among smaller operators facing rising compliance costs, feedstock volatility, and the need for stronger quality systems. On the other hand, the market retains space for specialized or regional entrants that can serve distinct application needs, offer differentiated concentration grades, or provide strong local service and logistics. New entry is not impossible, but success will increasingly depend on credible production capability, clear quality assurance, and the ability to integrate into downstream procurement systems. The overall pattern suggests a landscape that is concentrated at the top, active in the middle, and selective at the edges.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape how the fluorozirconic acid market develops and where commercial opportunities emerge.
One important trend is the continued elevation of supply chain reliability as a competitive differentiator. As feedstock costs remain sensitive and regulatory expectations persist, buyers will place greater weight on suppliers that can deliver predictable availability and consistent specifications. This will favor organizations that invest in production discipline, inventory planning, and transparent communication with customers. For suppliers, the opportunity lies in building long-term account trust rather than competing transaction-by-transaction.
A second trend is gradual application-driven demand evolution. Metal surface treatment is expected to remain a core demand anchor, but growth will be influenced by industrial maintenance cycles, coating performance expectations, and the willingness of manufacturers to standardize on reliable chemical inputs. In ceramics, glass, and catalyst-related uses, demand will likely track more closely with specialty production activity and formulation innovation. This creates an environment where companies with stronger application knowledge and closer customer collaboration can capture more resilient demand than those relying solely on commodity-style selling.
Zirconium Oxychloride Market
A third trend is the ongoing pressure on cost management and pricing strategy. Feedstock volatility, regional price divergence, and compliance-related operating costs will continue to shape margin dynamics. Businesses that succeed will need to combine efficient production, disciplined commercial pricing, and flexible contract structures. There is also an opportunity for suppliers to create value through concentration specialization, packaging optimization, and technical service, all of which can support healthier margin profiles in a market where pure price competition is increasingly risky.
Potential risks should not be overlooked. Feedstock price shocks, changes in regulatory interpretations, trade friction, or abrupt shifts in downstream demand could disrupt otherwise steady market conditions. In addition, overconcentration of supply dependence on a limited number of sources can heighten vulnerability for buyers and create pricing leverage for suppliers during tight periods. Organizations that monitor these risks early and build contingency options will be better prepared to navigate periods of uncertainty.
Strategic Guidance for Decision-Makers
Market participants should approach fluorozirconic acid with a clear understanding of where value is created and where exposure accumulates. For manufacturers and suppliers, the priority is to strengthen production consistency, compliance readiness, and customer-facing technical capability. Differentiation through specification reliability and service responsiveness is likely to be more durable than competing on price alone, especially given ongoing feedstock cost volatility and the importance of long-term buyer trust.
For investors and corporate development teams, the market warrants attention to companies with credible production bases, diversified application exposure, and the ability to manage input cost transmission. The most attractive positions are often those that combine scale with application relevance and supply chain discipline, rather than those that depend on a single thin-margin commodity pathway. Monitoring feedstock trends, regional pricing divergence, and capacity changes will be essential for assessing where competitive advantage is likely to intensify or erode.
For procurement and operations leaders, supplier selection should be treated as a strategic function. Evaluating suppliers on specification consistency, availability, documentation, and technical support can reduce downstream risk and improve overall process stability. Diversifying supply options where feasible, understanding regional feedstock dynamics, and aligning purchasing terms with realistic cost conditions can help organizations avoid overreliance on fragile supply arrangements.
Detailed segment-level data, regional demand patterns, concentration-grade breakdowns, and application-specific volume dynamics can materially improve planning quality, but they require a more granular view than market-level indicators alone can provide. Decision-makers seeking to translate these trends into precise sourcing, investment, or product strategy will benefit from fuller market detail, including the kind of segmented analysis that supports scenario planning and competitive benchmarking. For teams that need deeper visibility into submarket size, application demand splits, regional pricing context, and company-level positioning, the complete PW Consulting research report provides the structured detail necessary to move from directional insight to operational decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Fluorozirconic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Construction Smart Wearables: Why an 11.5% CAGR Reshapes Safety and Productivity Through 2032
By pmarketresearch, 2026-09-18
The Worldwide Construction Smart Wearable Market: Strategic Shifts and Commercial Opportunities (2025–2032)
The global construction industry is undergoing a quiet but profound transformation. After years of incremental adoption, smart wearable technologies have crossed a strategic inflection point. From connected hard hats that detect fatigue and hazardous gases to exoskeletons that reduce musculoskeletal strain and wrist-worn devices that track lone-worker safety in real time, these tools are shifting from experimental pilots to mission-critical operational infrastructure. The market trajectory reflects this maturation. Revenue climbed steadily from 350.0 million in 2020 to 780.0 million in 2025, with the growth curve accelerating into the forecast period. By 2032, the sector is projected to reach 1,671.17 million, expanding at a compound annual growth rate of 11.5 percent from 2025 through 2032. This is not merely a hardware procurement cycle; it represents a structural reorientation of how construction firms manage risk, productivity, and workforce welfare.
The scale of this expansion masks several structural frictions that determine which players will capture value and which will face margin compression. The market remains moderately fragmented, with the top three players holding approximately 25.5 percent of revenue and the top five reaching 34.2 percent. Such concentration leaves substantial runway for consolidation, but it also underscores that scale alone does not guarantee defensibility. The real competitive moats are being built through data integration, regulatory alignment, and site-level operational fit. Meanwhile, the sector is navigating a set of intertwined challenges that will shape investment priorities and product roadmaps over the next half-decade.
Operational Realities and Structural Friction Points
Three interlocking challenges are defining the current market environment. The first centers on rugged reliability versus technological ambition. Construction environments impose extreme thermal cycling, dust exposure, vibration, and continuous physical stress. Hardware designs must balance sensor richness with field durability, and the tension is most visible in power architecture. Continuous biometric and environmental monitoring draws substantial current, and battery endurance in many deployed units remains constrained to roughly 12–24 hours under real-site conditions. For contractors running multi-day shifts or remote operations with limited charging infrastructure, this creates a practical adoption ceiling that no amount of feature marketing can override.
The second challenge lies in data utility and workflow integration. A wearable that streams location, impact, vitals, or environmental readings generates data, but data does not automatically become operational value. Site supervisors, safety managers, and project controls teams are overloaded with fragmented inputs. Devices that cannot push contextual alerts into existing safety management, scheduling, or field execution platforms tend to become underutilized assets rather than risk-mitigation multipliers. The organizations gaining traction are those treating the wearable not as a standalone gadget but as a sensor node within a broader site intelligence stack.
Worldwide Military Smart Wearable Devices Market
The third challenge is regulatory and ethical complexity. Compliance expectations are tightening on multiple fronts simultaneously. Occupational safety rules increasingly expect hazard detection and personal protective equipment that meets documented performance thresholds. Standardization frameworks are incorporating connected monitoring into occupational health and safety management practices. Wireless deployments must satisfy electromagnetic compatibility and certification requirements to avoid interference on dense job sites. At the same time, biometric and location tracking raise worker privacy questions, especially in jurisdictions where consent and data minimization are enforced stringently. Companies that treat compliance as a checkbox will face adoption friction; those embedding privacy-by-design and clear governance models will reduce procurement hesitation.
Key Drivers Reshaping the Market
Underlying these challenges is a set of forces that are accelerating adoption and redefining what “smart PPE” must deliver to justify procurement budgets.
Technology Innovation Moving From Detection to Prediction
The technology stack is shifting along a clear trajectory: from passive monitoring toward predictive and context-aware capability. Early-generation devices excelled at logging falls, man-down events, exposure excursions, or location drift. The next wave integrates onboard analytics and tighter sensor fusion so that devices can flag deteriorating conditions before they become incidents. In practice, this means combining heart-rate variability, motion signatures, environmental gas readings, and site-specific hazard maps into a single risk signal. Suppliers that operationalized this shift in mid-2025 have shown how predictive safety analytics can move the conversation from incident response to proactive intervention.
Worldwide Military Wearable Market
Equally important is the maturation of PPE-adjacent electronics. Miniaturized inertial sensors, improved low-power radios, and more robust enclosure designs are allowing manufacturers to embed intelligence without compromising the primary protective function of helmets, vests, gloves, and belts. The commercial implication is significant: value is migrating from the physical shell toward the sensing and analytics layer. That migration changes product economics, service models, and upgrade cycles.
Policy and Standards as Adoption Accelerators
Regulation and standardization are no longer external constraints to be managed; they are becoming adoption accelerators. Occupational safety expectations increasingly mandate hazard detection and personal protective equipment suited to modern site risks. At the same time, occupational health and safety management frameworks are evolving to treat connected monitoring as a legitimate input for risk control and continuous improvement. When structured correctly, these expectations reduce the burden of internal justification for adoption. Safety leadership can point to external baselines for equipment performance, interoperability, and data governance.
Certification requirements also shape market access. Wireless construction wearables must clear regulatory hurdles around electromagnetic compatibility to coexist with radios, signaling systems, and dense equipment fleets on active sites. Meanwhile, biometric and location data collection invites consent and privacy obligations, particularly across European markets. The firms that design for these requirements from the outset are shortening procurement cycles and reducing legal review friction.
PW Consulting
Demand-Side Shifts: Workforce, Liability, and Site Complexity
The demand picture is being rewritten by three operational pressures. First, labor dynamics continue to strain site productivity. Skills shortages, turnover, and an aging workforce elevate the cost of preventable injuries and downtime. Smart wearables directly address this by reducing exposure to high-risk behaviors and by improving situational awareness for both workers and supervisors. Second, liability and insurance expectations are becoming more data-driven. Insurers and risk managers increasingly look for evidence that site operators are actively monitoring conditions, enforcing protocols, and responding faster to incidents. Connected wearables provide auditable signals that can strengthen risk profiles. Third, construction sites are growing more complex, with concurrent trades, tighter schedules, and tighter safety perimeters. In that environment, knowing where people are, whether they have taken a fall, and whether environmental thresholds are being breached becomes a coordination tool, not just a safety tool.
Supply-Side and Cost Structure Evolution
On the supply side, the economics of smart wearables are normalizing as sensors, connectivity modules, and rugged enclosures move down the cost curve. Yet the more important shift is in total cost of ownership. Procurement teams are increasingly evaluating devices through the lens of integration costs, maintenance downtime, battery replacement logistics, and training burden rather than sticker price alone. That perspective favors designs that minimize site friction: longer practical runtime, simpler charging routines, durable components that reduce failure rates, and firmware that can be updated without pulling devices out of service. It also favors vendors that can document reliability under harsh conditions, since failure in a safety-critical device has consequences far beyond warranty claims.
Another evolving dynamic is the relationship between hardware and software. As more devices feed into site platforms, the marginal value of a unit rises when it interoperates smoothly with scheduling, safety incident management, and field coordination tools. That creates an incentive for partnerships and platform-level integration rather than purely device-level competition.
Competitive Landscape and the Logic of Differentiation
The current market is shaped by a mix of specialized wearable firms, industrial safety incumbents, and large electronics and industrial groups applying their sensor and manufacturing expertise to construction contexts. The strategic positions vary, but a few patterns are clear.
Differentiated Positions Across the Field
Several companies have built identities around specific use cases rather than broad commodity wearables. One U.S.-based firm has focused on connected hard hats that combine vital-sign monitoring, environmental hazard detection, and lone-worker protection, recently extending the concept with onboard predictive analytics for proactive risk flagging. Another U.S. player has concentrated on a rugged wearable tag that tracks location, fall events, and impact signals, with strong emphasis on integrating those outputs into safety management workflows. A UK supplier has carved out a clear niche in lone-worker protection, pairing duress alarms, no-motion detection, and GPS tracking for environments where personnel may operate in isolation.
On the industrial PPE side, a major gas detection and safety technology provider has extended its connected portfolio into construction-relevant monitoring, leveraging brand trust in hazardous-environment sensing. A large diversified materials and safety company has advanced connected welding helmets and PPE that embed arc-flash detection and worker health monitoring, including recent certification-aligned updates for construction-grade protection. Further along the value chain, a South Korean manufacturer has emphasized smart helmets with IoT sensors for fall detection, fatigue monitoring, and environmental hazard alerts, while a Japanese industrial group has focused on wearable safety devices such as positioning and fall-prevention belts for site coordination.
What separates these players is not the presence of sensors alone, but the clarity of the operational problem they solve and the strength of their integration story. A device that addresses a well-scoped risk and slots neatly into existing site processes tends to gain faster traction than a generic multi-feature offering with weak workflow fit.
Recent Moves That Signal Where Value Is Being Built
Three recent developments illustrate how the field is evolving. A connected hard-hat supplier extended its platform with AI-driven predictive safety analytics designed to turn continuous site data into earlier risk intervention. A wearable tracking provider announced deeper integration with a widely used construction management platform, reinforcing the idea that device value multiplies when it feeds into project execution systems. A large PPE and welding-helmet manufacturer updated a flagship connected helmet to align with recognized construction safety standards, signaling that regulatory alignment remains a commercialization prerequisite as much as a technical specification.
Beyond these specific moves, the broader pattern is a shift toward ecosystems. Vendors are increasingly judged on how well their devices connect with site safety platforms, incident management tools, and field coordination workflows. That reality is reshaping competitive advantage: hardware quality still matters, but interoperability, data governance, and platform relationships are becoming the sharper differentiators.
Consolidation, Fragmentation, and the Opening for New Entrants
The market structure suggests room for both consolidation and targeted fragmentation. Moderate concentration among leading players leaves substantial opportunity for larger safety, connectivity, or industrial hardware firms to acquire specialized capabilities and accelerate platform play. At the same time, fragmentation persists at the application layer, where niche providers can thrive by solving narrow, high-value problems exceptionally well, such as lone-worker protection in remote environments or fatigue monitoring in continuous-shift operations.
New entrants face a meaningful barrier in rugged validation and site adoption, but the barrier is not insurmountable if they enter with a tightly defined use case, strong regulatory posture, and a plan for platform interoperability. The more dangerous strategic mistake is entering as a generic device maker without a clear path to data use, consent management, and integration. In a market where procurement teams care deeply about total cost of ownership and operational fit, the winners will be those who can demonstrate reliability in the field and value in the workflow.
Forward Outlook: Three Trends to Watch (2026–2032)
The next several years will likely be defined by the transition from device adoption to system-level value creation. Three trends stand out.
Predictive and context-aware safety becomes the baseline expectation. As sensor fusion and onboard analytics mature, the market will increasingly reward devices that can anticipate risk rather than merely log it. This trend will shift procurement conversations toward accuracy, false-alarm management, and response integration. The commercial opportunity lies in combining wearable data with site schedules, environmental inputs, and incident history to create actionable risk views. The uncertainty is in operational overload: if predictive signals are noisy or poorly prioritized, adoption can stall regardless of technical sophistication.
Platform interoperability becomes a commercial prerequisite. Construction firms are unlikely to build entirely new data ecosystems around wearables. They will expect devices to connect cleanly with safety management, field coordination, and project controls tools. This creates a durable advantage for suppliers that invest early in integration pathways and data-export flexibility. The risk is fragmentation of integration standards, which could raise implementation costs and slow procurement if buyers must manage multiple bespoke connections across vendors.
Regulatory and privacy expectations become a competitive filter. Compliance around emissions, equipment performance, and biometric data handling will continue to harden. Organizations that build consent workflows, data minimization, and clear retention policies into their products will reduce deployment friction. Those that treat privacy and certification as afterthoughts will face increasing procurement resistance, particularly in multi-jurisdiction operations. The commercial upside is that well-governed products can become preferred choices for risk-averse buyers, turning compliance into differentiation rather than cost.
Together, these trends point to a market where success is less about selling more hardware and more about enabling safer, faster, better-coordinated site operations. That shift opens opportunities for product-led service models, analytics add-ons, integration partnerships, and subscription-style support that reduces the operational burden on contractors.
Strategic Recommendations for Decision-Makers
For manufacturers and product developers, the priority is to anchor innovation in operational reality. Design for rugged runtime, simple charging, and durable construction first; then layer predictive analytics and integration capabilities that solve a clearly defined site problem. Validation under harsh conditions and transparent data governance should be treated as core product features rather than compliance extras.
For investors, the most compelling value creation will likely come from firms that combine reliable hardware with defensible data workflows and platform relationships. Evaluate potential targets and partnerships not only on sensor count or feature breadth, but on site adoption likelihood, integration readiness, and the ability to reduce total cost of ownership for contractors. Look particularly closely at companies that can demonstrate repeatable deployment patterns in complex, multi-trade environments.
For procurement and construction operators, the practical path is to treat smart wearables as part of a site intelligence strategy rather than a safety-equipment purchase in isolation. Prioritize devices that integrate with existing safety management and field coordination tools, that have credible field durability, and that provide clear data-use and consent frameworks. Pilot in high-value risk scenarios where faster detection or better coordination has measurable impact, then scale based on operational evidence rather than feature lists.
Detailed segmentation data, regional revenue breakdowns, product-type splits, connectivity preferences, company-level profiles, and scenario-based forecasts can sharpen these decisions considerably. Readers seeking a deeper, numbers-backed view of growth corridors, competitive positioning, and tailored strategic options can review the full PW Consulting report, which compiles the underlying market sizing, segmentation, and company intelligence behind the trends outlined here.
For detailed analysis of this topic, please visit the official page: Worldwide Construction Smart Wearable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Flexible Intermediate Bulk Containers Market: Why 6.15% CAGR Reshapes Demand by 2032
By pmarketresearch, 2026-09-18
Navigating the Global Flexible Intermediate Bulk Containers Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Landscape and Critical Inflection Points
The worldwide flexible intermediate bulk containers (FIBC) market has demonstrated resilient growth, expanding from approximately $4.6 billion in 2020 to an estimated $6.2 billion in 2025. This trajectory reflects a compound annual growth rate of 6.15%, projecting the market to surpass $9.4 billion by 2032. The steady expansion underscores FIBCs' entrenched role in bulk material logistics, bridging the gap between rigid containers and loose bulk handling while offering cost efficiency, transport optimization, and adaptable load capacities.
Despite the upward baseline, the industry stands at a structural crossroads. The first challenge lies in raw material price volatility and supply chain fragility. Woven polypropylene remains the dominant fabrication material, capturing roughly 78 percent of volume share. However, regional pricing divergences have intensified. North American polypropylene prices climbed to $1.43 per kilogram in early 2026, marking a 20.2 percent increase, while European markets faced steeper pressure at $2.1 per kilogram. Such cost asymmetry compresses margins for manufacturers heavily reliant on virgin resin and complicates procurement planning for end-users operating across multiple geographies.
The second inflection point is regulatory tightening around circularity and extended producer responsibility. The European Union's Packaging and Packaging Waste Regulation, effective from February 2025 and applicable from August 2026, mandates EPR schemes with fees directly modulated by recyclability performance. This legislation extends to plastic-based packaging, including FIBCs, compelling manufacturers and brand owners to rethink design-for-recycling, material traceability, and end-of-life management. Companies that treat compliance as a checkbox risk higher fee exposure, while those embedding circularity into product architecture can translate regulatory pressure into cost advantages and procurement preference.
A third challenge emerges from trade policy friction. US imports of bulk bags under HTS Code 6305.32.0010 currently encounter approximately 8.4 percent tariffs alongside ancillary fees. This framework reshapes regional cost competitiveness, incentivizing localized production, supply chain dual-sourcing, or design modifications that reduce import dependency. For multinational buyers and manufacturers, tariff exposure is no longer a peripheral concern but a core variable influencing capacity siting, inventory strategy, and product mix decisions.
Core Drivers Reshaping the FIBC Value Chain
Technological Innovation in Material Performance and Circular Design
Material engineering continues to redefine what FIBCs can deliver beyond conventional load containment. The adoption of advanced woven polypropylene structures, reinforced lifting loops, and multi-layer barrier liners is addressing longstanding performance gaps in food safety, pharmaceutical compliance, and chemical containment. Recent product introductions illustrate how performance and circularity are converging rather than competing. In January 2025, Greif introduced the GCUBE Flex intermediate bulk container, featuring an enhanced aseptic liner and a two-layer polypropylene construction tailored for food and pharmaceutical handling. This launch signals a broader industry direction: FIBCs are evolving from commoditized bulk sacks into engineered packaging systems that meet stringent hygiene, traceability, and contamination-control requirements.
Simultaneously, recycled-content engineering is moving from pilot initiatives to commercial scale. Packem Umasree commissioned India's first fully integrated bottle-to-bag rPET FIBC manufacturing plant in Ahmedabad in 2025, achieving a capacity of 3.5 million bags. This facility demonstrates that post-consumer recycled inputs can be integrated into FIBC production at meaningful volumes without sacrificing structural integrity. Such capability expansion is critical because it creates upstream supply of recycled resin tailored to bulk bag specifications, reducing reliance on virgin resin price swings and enabling manufacturers to offer lower-carbon alternatives to procurement teams under internal or regulatory sustainability mandates.
Regulatory Momentum Accelerating Circular Economy Adoption
Policy is no longer a distant backdrop; it is actively reallocating competitive advantage. The EU PPWR's fee modulation based on recyclability performance creates a financial gradient that rewards designs with higher recycled content, simpler material assemblies, and documented end-of-life pathways. This regulatory logic is reinforced by growing market expectations that packaging should incorporate post-consumer recycled material wherever technically feasible. The result is a dual pressure: manufacturers must redesign products for recyclability while simultaneously securing reliable recycled feedstock streams.
Market reactions confirm this shift. Gravis launched the Sustainabulk 100 percent recycled PET FIBC in May 2025, claiming up to a 70 percent carbon footprint reduction compared with virgin polypropylene bags. This product positioning reflects an emerging commercial logic in which environmental performance becomes a procurement differentiator, particularly for chemical, food, and pharmaceutical users who must report on lifecycle emissions or comply with customer sustainability clauses. For producers, the opportunity lies in certifying recyclability claims, standardizing recycled-content grades, and aligning product documentation with audit requirements from downstream buyers.
Demand-Side Transformation in Application Sectors
End-user behavior is shifting from viewing FIBCs as interchangeable transport units to selecting them based on sector-specific performance, compliance, and sustainability criteria. Chemicals remain a major application area, driven by the need for reliable bulk handling of dry flowable materials, powders, and granular substances. Food and pharmaceutical demand is intensifying around contamination control, liner integrity, and inspection-friendly designs. Agriculture and construction continue to generate steady volume, yet even these traditional segments increasingly evaluate bulk bag suppliers on total cost of ownership, delivery reliability, and environmental footprint.
Worldwide Industrial Flexible Hose Market
This segmentation is reshaping procurement behavior. Buyers are more willing to pay for engineered features such as Type C and Type D conductive configurations, custom spout and top designs, or aseptic liners when those features reduce operational risk, improve handling efficiency, or satisfy regulatory expectations. For manufacturers, the implication is clear: competitive differentiation is migrating from unit price toward specification reliability, compliance documentation, and lifecycle performance. Suppliers that can articulate application-specific value and evidence-based sustainability attributes are gaining preference in tenders and long-term supply agreements.
Cost Structure Reconfiguration and Regional Production Dynamics
Cost structures are being recalibrated by the intersection of raw material inflation, energy differentials, and trade policy. Polypropylene price divergence between North America and Europe creates uneven cost bases across manufacturers, prompting some to optimize production footprints, adjust pricing mechanisms, or shift toward blended or recycled resin mixes where feasible. At the same time, tariff exposure on bulk bag imports into the United States encourages regional capacity expansion or nearshore sourcing strategies. Several US-based manufacturers have emphasized standard and custom FIBC production with domestic or regional supply chains, aligning cost predictability with faster fulfillment and lower logistics risk.
For the broader market, this dynamic favors players that can balance scale with flexibility. Large producers with integrated recycling loops, diversified resin sourcing, and multi-region manufacturing can better absorb input volatility and tariff effects. Smaller or highly specialized manufacturers can compete by offering rapid customization, food-grade certifications, and application-engineered solutions that larger generalist players may standardize away. The net effect is a market in which cost leadership and differentiation are increasingly interdependent rather than mutually exclusive.
Competitive Landscape and Strategic Positioning
The FIBC industry remains moderately fragmented, with a five-firm concentration ratio of about 24 percent and a three-firm ratio near 18 percent. This fragmentation provides room for regional specialists, application-focused manufacturers, and export-oriented producers, but it also intensifies the need for clear strategic positioning. Leading companies are not competing solely on bag specifications; they are building value through service architecture, recycling infrastructure, and sector-specific credibility.
Greif exemplifies a strategy centered on circular reconditioning and engineered product platforms. By reporting the reconditioning or recycling of over 4.5 million containers across its global industrial packaging network in September 2025, Greif has reinforced a circular economy narrative that links reuse capability with cost recovery and sustainability metrics. Combined with the GCUBE Flex launch targeting food and pharmaceutical performance, this dual emphasis on circularity and specialized containment illustrates how incumbents can defend scale while moving up the value curve. Berry Global maintains a broad flexible packaging portfolio, leveraging durable woven polypropylene designs across industrial, chemical, food, and construction segments. Its breadth supports cross-segment supply resilience, though it also requires disciplined specification management to avoid commoditization.
FIBC (Flexible Intermediate Bulk Container) Market
Several producers are building differentiation through application focus and manufacturing localization. Conitex Sonoco emphasizes US-based BulkSak and FIBC production, offering standard, custom, food-grade, and on-demand inventory programs that appeal to industrial buyers prioritizing responsiveness and compliance. LC Packaging International BV anchors its positioning in European and global distribution with standard and customized bulk bags, benefiting from proximity to markets facing stringent recyclability expectations. Global-Pak Inc. and Palmetto Industries International Inc. concentrate on high-performance woven polypropylene containers and tailored top and spout configurations for industrial use, respectively, reflecting demand for load stability and handling efficiency. JohnPac, LLC extends its differentiation across the full FIBC specification range, including 4-panel, baffle, circular, food-grade, Type C, and Type D bags, enabling customers to source multiple technical variants from a single supplier relationship.
Export-oriented manufacturers from India and Turkey are expanding their relevance by combining cost efficiency with growing specification capabilities. Rishi FIBC Solutions Pvt. Ltd. serves chemical, food, pharmaceutical, and agricultural applications with an export focus, while Isbir Sentetik Dokuma Sanayi A.S. produces woven polypropylene fabrics and FIBCs with significant export-oriented production. These players benefit from relative input cost advantages and scale flexibility, though sustained competitiveness depends on consistent quality, certification reliability, and the ability to meet increasingly demanding recycled-content and traceability expectations. Codefine's emphasis on sustainable options, including recycled PET bulk bags, reflects another competitive vector: offering lower-carbon alternatives within a standard product portfolio. In the United States, manufacturers such as Bulk Lift International LLC, Langston Companies Inc., Halsted Corporation, and Dewitt Company maintain specialized bulk bag production for industrial, chemical, food, and construction markets, often competing on customization, capacity reliability, and regional fulfillment speed.
The competitive outlook points toward selective consolidation in mature regions alongside continued emergence of niche specialists. Larger players may pursue acquisitions to secure recycling infrastructure, geographic coverage, or application expertise. Mid-tier manufacturers may differentiate by depth in food-grade, conductive, or aseptic solutions. New entrants are most likely to succeed where they solve a specific procurement pain point: verified recycled content, improved liner performance, faster custom turnaround, or documented compliance with evolving EPR requirements. The market is moving toward a landscape in which scale, circular capability, and application credibility must be managed together rather than in isolation.
Forward Outlook: Trends, Opportunities, and Risks
Over the next three to five years, the FIBC market is likely to be shaped by three interconnected trends. First, circular design and recycled-content integration will shift from optional features to baseline expectations in many procurement categories. As EPR fee modulation takes effect and customer sustainability requirements deepen, manufacturers that can reliably supply certified recycled-content FIBCs and document recyclability performance will gain preference in competitive bidding. This creates opportunities for producers with access to rPET or post-consumer recycled polypropylene streams, as well as for service models that combine bulk bag supply with reconditioning or return logistics.
Second, regulatory and tariff divergence will accelerate regionalized supply chains and segmented product strategies. The EU PPWR implementation timeline and ongoing US import duties make it increasingly important to align production footprints, resin sourcing, and product specifications with destination-market requirements. Manufacturers that can offer region-appropriate grades, adjusted recycled-content mixes, and transparent compliance documentation will reduce friction for multinational buyers and protect margin stability in volatile input environments. This trend favors suppliers with multi-region capacity or strong partner networks that can localize fulfillment without sacrificing specification consistency.
Third, application-engineered FIBCs will capture a growing share of value as buyers prioritize performance reliability and compliance over lowest unit cost. Food and pharmaceutical segments will continue to drive demand for aseptic liners, contamination-control features, and inspection-friendly designs. Chemical and construction sectors will reward durable woven structures, tailored lifting configurations, and consistent load integrity. The commercial opportunity lies in defining clear grade families, linking them to documented performance attributes, and supporting procurement teams with specification guidance that reduces risk and simplifies vendor consolidation. At the same time, uncertainty persists around resin price trajectories, the pace of recycled feedstock availability, and the practical interpretation of EPR fee modulation across jurisdictions. Companies that monitor these variables closely and build flexible sourcing and product architectures will be better positioned to manage downside risk while capturing upside from sustainability-driven demand.
Strategic Actions for Decision Makers
For FIBC manufacturers, the priority is to translate circularity and application performance into repeatable product architectures rather than isolated launches. Establish clear recycled-content grades, secure traceable feedstock arrangements, and align product documentation with EPR and customer audit expectations. Where feasible, integrate reconditioning or return pathways that convert sustainability claims into operational value and improve total cost positioning. At the same time, protect margin resilience by diversifying resin sourcing and aligning production footprints with the regulatory and tariff realities of key destination markets.
PW Consulting
For investors, the most attractive opportunities are likely in companies that combine scale with circular capability or that occupy strong positions in high-specification segments such as food-grade, pharmaceutical, and conductive FIBCs. Due diligence should focus on recycled-content supply security, certification integrity, regional cost structures, and exposure to tariff or EPR-related cost shifts. Capital allocation should favor businesses that can demonstrate sustainable differentiation beyond commodity bag pricing, particularly where sustainability attributes are already influencing procurement decisions.
For procurement and supply chain leaders, the strategic task is to move beyond unit-price comparison toward total-cost and risk-based evaluation. Assess suppliers on specification reliability, compliance documentation, recycled-content options, and fulfillment consistency across regions. Where possible, consolidate categories around suppliers that can provide multiple FIBC types with clear performance grades and verified sustainability attributes, reducing vendor complexity while improving traceability. Procurement teams should also pressure-test supply continuity plans against raw material volatility and tariff exposure, ensuring that lower headline pricing does not obscure logistics risk or future compliance costs.
For decision makers seeking to translate these dynamics into actionable plans, detailed segmentation data, regional cost modeling, specification benchmarking, and supplier evaluation frameworks can materially accelerate strategy development. Access to granular market intelligence supports more precise capacity planning, product mix decisions, and procurement negotiations, particularly in a market where regulatory timelines, resin pricing, and circular-content expectations are changing simultaneously.
For detailed analysis of this topic, please visit the official page: Worldwide Flexible Intermediate Bulk Containers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Customer Churn Software Market’s 2026–2032 Trajectory: Decoding a 20% CAGR
By pmarketresearch, 2026-09-18
Navigating the Boom: Strategic Trends and Commercial Opportunities in the Customer Churn Software Market
Market Dynamics: Scale, Trajectory, and Core Challenges
The customer churn software market has evolved from a niche retention tool into a core component of enterprise revenue operations. Between 2020 and 2025, the sector transitioned from a relatively concentrated ecosystem into a high-growth, multi-billion-dollar infrastructure market. Revenue expanded from approximately 742 million USD to over 1.8 billion USD by 2025, reflecting a compound annual growth rate of 20% across the forecast window. This acceleration is not merely a function of renewed demand; it signals a structural shift in how organizations view retention as a measurable, technology-driven discipline rather than an ad hoc customer service function. Cloud-based deployments now account for the overwhelming majority of revenue, with large enterprises driving more than two-thirds of total spend. Industry adoption remains concentrated in financial services, retail and e-commerce, and IT and telecommunications, though healthcare, media, and other verticals are expanding their footprint as subscription and recurring-revenue models proliferate across the economy.
Despite this momentum, the market faces several structural inflection points. The first is the paradox of data abundance versus actionable insight. Organizations now capture more behavioral, transactional, and engagement data than ever, yet many churn solutions struggle to translate fragmented signals into timely, prescriptive interventions. Without tight integration between data unification, predictive modeling, and workflow execution, tools risk becoming analytical dashboards rather than retention engines. The second challenge lies in economic and operational pressure. Rising compute and cloud hosting costs, particularly for workloads reliant on public IP exposure and high-throughput inference, are compressing margins for both vendors and enterprise buyers. At the same time, labor dynamics are shifting: automation and AI agents are reducing manual administrative burdens for customer success teams, but this reallocation moves cost from human labor to cloud infrastructure, demanding careful total cost of ownership planning. The third pressure is regulatory complexity. As privacy frameworks expand and enforcement intensifies around AI-driven data processing, vendors must balance predictive accuracy with compliance rigor, particularly for cross-border data flows and consent management. These forces are reshaping what it means to deliver durable retention value.
Customer Support Training Software Market
Key Drivers Reshaping the Market
Technological innovation is the most immediate catalyst. AI-driven churn prediction has moved beyond static health scores into real-time, event-triggered risk detection. Vendors are embedding AI agents capable of sentiment analysis, engagement scoring, and automated workflow recommendations directly into customer success and support environments. The recent introduction of no-code predictive AI agents illustrates how organizations are lowering the barrier to production-grade models without relying on internal data science teams, accelerating time-to-value for mid-market and enterprise deployments. This shift is particularly relevant for subscription-heavy businesses where early warning signals must be acted on within hours, not weeks. By unifying telemetry from product usage, support interactions, billing cycles, and communication channels, these platforms are transforming churn from a lagging metric into a continuous operational loop.
Policy and regulatory developments are simultaneously reshaping data strategies. New comprehensive privacy laws across multiple U.S. states have introduced stricter requirements for customer data processing, consent, and retention, while European enforcement activity has intensified around AI and advertising-related data practices. For churn platforms, this means data governance is no longer a back-office concern but a product design constraint. Vendors that embed privacy-by-design architectures, granular consent controls, and transparent model explainability are better positioned to scale across regulated industries such as financial services and healthcare. Conversely, tools that over-collect or obscure how behavioral data fuels predictions face growing procurement friction, particularly in sectors with elevated audit and compliance expectations.
Demand-side behavior is also evolving. Customers now expect seamless, personalized experiences across touchpoints, and they are quicker to disengage when value delivery feels inconsistent. In subscription and usage-based models, the lifetime value equation is increasingly sensitive to early-stage engagement, making the first 90 days of a customer journey a critical retention window. Enterprise buyers are consequently prioritizing platforms that connect churn prediction to actual retention actions—automated playbooks, in-product guidance, and cross-functional escalations—rather than standalone analytics. This behavior is reinforced by executive pressure to demonstrate retention ROI in uncertain macro conditions, where expanding existing relationships is often more capital-efficient than pursuing new logos.
Finally, cost and supply-side dynamics are influencing procurement and product architecture. Cloud cost pressures, including incremental charges tied to public IP usage, are prompting IT and finance leaders to scrutinize SaaS spend and optimize instance placement, data egress, and inference pipelines. At the same time, the broader shift from manual CS operations to AI-assisted workflows is redistributing cost structures. Organizations that once staffed large pools of administrators for health score maintenance and alert triage are reallocating budget toward cloud compute and integration work. Vendors that offer efficient model serving, flexible deployment options, and transparent pricing are gaining an edge, especially as buyers compare churn platforms against broader CX and revenue systems.
Competitive Landscape: Positioning, Differentiation, and Evolution
The market is defined by a mix of specialized customer success platforms, CX incumbents, and AI-native analytics providers. Gainsight has established a strong enterprise footprint by combining AI-powered churn prediction, health scoring, lifecycle analytics, and retention tooling within a broader customer success ecosystem. Its positioning emphasizes cross-functional orchestration for large, complex organizations that need to align product, support, and success teams around a unified view of customer health. ChurnZero has focused on subscription-oriented businesses, delivering AI-driven engagement scoring, real-time risk alerts, and churn prevention workflows tailored to recurring-revenue models. Its recent product updates reflect a clear emphasis on embedding AI agents for sentiment analysis, churn prediction, and engagement scoring directly into day-to-day CS operations, supported by leadership events that reinforce community and best-practice sharing among revenue and success leaders. Zendesk brings a different angle: an AI-powered CX platform that integrates churn prediction, analytics, and retention features into support and experience workflows, appealing to organizations that want retention signals to flow naturally from service interactions. Totango targets SaaS businesses with predictive revenue intelligence, churn reduction tools, and customer journey management, while Vitally combines data unification, automation, health scoring, and churn reduction into a platform designed for B2B SaaS teams seeking operational simplicity. Pecan AI stands apart as a no-code predictive analytics specialist, enabling business teams to convert questions into production-grade churn models without heavy data science investment, which broadens access to predictive retention capabilities across functions.
Differentiation increasingly hinges on three dimensions: integration depth, actionability, and accessibility. Platforms that connect predictive signals to automated workflows and existing CRM, support, and product stacks reduce the operational lag between detection and intervention. Those that simplify model creation and maintenance lower the skills barrier, enabling faster deployment and broader adoption beyond central data teams. Meanwhile, incumbents with extensive CX and support footprints can offer retention insights in the context of real-time service interactions, while specialist players can move faster on niche models and vertical-specific use cases. The market is evolving along two parallel tracks: consolidation among larger CX and customer success suites that seek to own the retention loop end to end, and continued entry by AI-native and no-code entrants that compress the path from data to decision. This duality creates both convergence risk and partnership opportunity, depending on how vendors handle data interoperability, model transparency, and pricing flexibility.
Forward Outlook: Trends Shaping 2026–2032
Over the next three to five years, churn software will increasingly function as an operational layer embedded within revenue and customer experience workflows, not a standalone analytics module. AI agents and automation will become standard for triage, early warning, and recommended interventions, allowing customer success teams to focus on high-value relationship moments while routine risk management is handled systematically. This transition will accelerate adoption in mid-market and growth-stage companies that previously lacked the data science capacity to operationalize prediction. At the same time, predictive accuracy will be judged not only by model performance but by the quality of the actions those models trigger, pushing vendors to invest in workflow design, playbook libraries, and integration breadth.
Customer Insights Marketing Platform Market
Data governance and compliance will become competitive differentiators rather than baseline requirements. As privacy regulation expands and enforcement tightens, platforms that provide consent-aware data processing, regional data handling options, and explainable prediction frameworks will be preferred in regulated verticals and multinational deployments. This creates an opportunity for vendors that can demonstrate measurable retention outcomes while maintaining auditable data practices. A parallel trend is the growing emphasis on total cost efficiency: organizations will increasingly evaluate churn platforms based on compute footprint, integration effort, and the degree to which automation replaces manual overhead. Solutions that combine strong prediction with economical inference and flexible deployment will be better positioned for long-term expansion.
The principal uncertainty lies in the balance between capability and complexity. As platforms accumulate more AI features, there is a risk of alert fatigue and fragmented toolchains if predictive outputs are not tightly aligned with operational realities. Economic volatility could also slow discretionary software investment, favoring vendors that can clearly tie retention gains to revenue protection and expansion. Finally, regulatory trajectories remain fluid, and any shift in data usage expectations for AI-driven analytics could reshape procurement timelines and feature requirements. Companies that plan for these variables—by prioritizing interoperability, governance, and measurable actionability—will be better prepared to capture durable value.
PW Consulting Information & Electronics Research Center
Actionable Guidance for Decision-Makers
For enterprise buyers evaluating churn software, the priority should be to connect prediction with execution. Select platforms that unify customer data across product, support, billing, and engagement channels, and that embed retention actions directly into daily workflows. Assess total cost of ownership with attention to cloud compute implications, integration effort, and the extent to which automation reduces manual overhead. In regulated environments, verify consent management, data handling options, and model transparency before scaling deployment.
For investors and strategic partners, the most promising opportunities lie in vendors that combine accessible model creation with strong workflow integration and defensible data governance. Differentiate between flashy AI features and repeatable retention outcomes by examining how quickly customers can move from risk detection to intervention, how broadly the solution fits across verticals, and how efficiently it operates at scale. Vertical specialization, no-code accessibility, and CX-centric integration are all viable paths, provided they are sustained by clear unit economics and customer success metrics.
For vendors and product leaders, the strategic imperative is to reduce friction between insight and action while maintaining compliance-ready data practices. Investments in interoperable data models, efficient inference, explainable predictions, and configurable playbooks will strengthen positioning as the market consolidates around platforms that can demonstrate measurable retention impact. As the market matures, detailed segmentation data, procurement benchmarks, and customized adoption scenarios can help refine go-to-market and investment decisions. Comprehensive research reports that break down deployment modes, organization sizes, industry verticals, regional dynamics, and competitive benchmarks offer the granularity needed to translate these trends into precise action plans.
For detailed analysis of this topic, please visit the official page: Customer Churn Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Aluminium Tert Butoxide Market: 5.48% CAGR and Regional Shifts
By pmarketresearch, 2026-09-18
Navigating the Aluminium Tert-Butoxide Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for aluminium tert-butoxide has entered a period of structured expansion, driven by its indispensable role as a catalyst and reagent in high-performance chemical synthesis. Valued at approximately 112.55 million USD in the base year, the market has demonstrated steady growth from its 2020 baseline of 86.25 million, reflecting consistent demand pull across industrial and scientific applications. Projections indicate a compound annual growth rate of 5.48 percent, positioning the sector to reach 163.51 million USD by 2032. This trajectory is not merely a function of incremental volume increases; it represents a structural shift toward specialized organometallic intermediates that enable precision manufacturing in emerging technology sectors. The convergence of advanced materials development, regulatory tightening around legacy chemical processes, and the globalization of specialty chemical supply chains has created a favorable environment for sustained commercial activity.
Despite the favorable growth outlook, industry participants are navigating a complex landscape defined by cost volatility, concentration dynamics, and evolving application requirements. One of the most pressing challenges lies in the sensitivity of production economics to raw material pricing. The cost structure for aluminium alkoxides is inherently tied to upstream inputs, and recent market movements have introduced significant uncertainty into margin forecasting. Simultaneously, the market exhibits a moderate-to-high degree of concentration, with the top three participants capturing over half of total industry revenue and the top five controlling nearly seventy percent. Such concentration creates both stability for established players and barriers for new entrants, while also raising questions about supply resilience and pricing power in an increasingly fragmented demand environment. A second critical juncture involves the divergence in purity requirements across end-use sectors. High-purity grades now dominate commercial activity, reflecting the needs of advanced electronics and precision catalysis, while standard grades maintain relevance in broader industrial applications. This bifurcation requires manufacturers to maintain distinct production protocols, quality assurance frameworks, and inventory strategies, complicating operational scaling.
The third challenge centers on geographic demand distribution and the corresponding need for localized supply capabilities. While demand is dispersed across multiple regions, the Asia Pacific corridor continues to account for the largest share of commercial activity, reflecting both manufacturing density and accelerating industrial modernization. Europe and North America maintain substantial footholds, supported by established laboratory networks and specialized chemical synthesis ecosystems. Latin America and the Middle East and Africa represent smaller but growing nodes of activity, often tied to regional industrial initiatives and imported specialty chemical demand. This geographic footprint necessitates a nuanced approach to distribution, regulatory compliance, and customer engagement. Companies must balance centralized production efficiency with regional responsiveness, particularly as procurement teams increasingly prioritize supply reliability over pure cost minimization. The interplay between demand concentration, purity segmentation, and regional cost structures defines the current market reality and will shape competitive positioning in the years ahead.
Key Drivers: What Is Really Moving the Market
Technological innovation continues to serve as the primary engine of commercial expansion, particularly in the realm of catalytic precision and materials science. Aluminium tert-butoxide functions as a critical reagent in esterification, transesterification, and the synthesis of advanced polymers and fine chemicals. Recent advancements in process chemistry have amplified its utility, enabling more efficient reaction pathways and reduced byproduct formation. In the semiconductor and electronics domain, the compound's role in precursor chemistry and surface treatment processes has gained renewed attention as device architectures become increasingly complex. Manufacturers that invest in controlled-atmosphere handling, particle-size consistency, and trace-metal reduction are capturing premium positioning, particularly among customers operating at the intersection of research and pilot-scale production. The shift toward continuous flow chemistry and automated synthesis platforms is also reshaping demand patterns, favoring suppliers capable of delivering consistent batch-to-batch performance and technical documentation that aligns with modern quality management expectations.
Regulatory and policy environments are simultaneously reweighting the competitive landscape, particularly around chemical safety, environmental compliance, and procurement transparency. Stricter handling requirements for organometallic compounds have elevated the importance of supplier documentation, safety data alignment, and packaging integrity. In several major markets, procurement frameworks now prioritize vendors that can demonstrate robust traceability, controlled storage specifications, and compliance with evolving occupational exposure standards. These requirements do not merely add administrative burden; they function as de facto barriers to entry that reward established players with mature quality systems and disciplined distribution networks. At the same time, sustainability mandates are influencing formulation choices across downstream industries, indirectly supporting demand for reagents that enable cleaner reaction pathways and reduced waste streams. The policy environment is therefore not simply a constraint but a catalyst for differentiation, favoring companies that integrate compliance into their core operating model rather than treating it as an afterthought.
PW Consulting
Supply-side economics present a further layer of strategic complexity. The cost structure for aluminium tert-butoxide is highly responsive to fluctuations in aluminium-based precursors and alcohol feedstocks. Recent market data underscores this sensitivity: aluminium metal prices reached 3,484.20 USD per tonne in late April 2026, representing a year-over-year increase of 44.45 percent and directly pressuring the production economics of aluminium alkoxides. In parallel, isobutanol, a key alcohol feedstock for tert-butoxide synthesis, traded in the range of 1,640 to 1,750 USD per tonne in Northwest European FOB terms during the same period. Aluminium oxide prices displayed notable regional dispersion, ranging from 0.42 USD per kilogram in Northeast Asia to 0.57 USD per kilogram in India, reflecting divergent local cost environments for aluminium-based precursors. These dynamics create a volatile input environment that rewards manufacturers with flexible sourcing strategies, regional production footprints, and the ability to pass through cost adjustments without sacrificing market share. Companies that rely on single-source procurement or rigid pricing models face heightened margin compression risk, particularly during periods of rapid commodity repricing.
Demand-side behavior is evolving in tandem with these supply and regulatory forces. Procurement teams across chemical synthesis, electronics, and pharmaceutical intermediary sectors are increasingly prioritizing supply reliability, technical support, and format flexibility over lowest-unit-cost acquisition. The compound is consumed across a broad application spectrum, with chemical synthesis and catalysis representing the largest commercial share, followed closely by semiconductor and electronics applications. Pharmaceutical intermediates and specialized industrial uses account for the remainder, each demanding different packaging scales, purity assurances, and delivery cadences. This diversification means that suppliers must operate multi-tiered service models, accommodating both catalog-grade research purchases and bulk industrial deliveries. Customers are also showing greater willingness to engage with suppliers that offer clear documentation, predictable lead times, and responsive technical guidance, particularly when qualifying materials for new production lines or scaling laboratory processes into pilot operations.
Competitive Landscape and the Strategies Defining Leadership
The competitive environment for aluminium tert-butoxide is characterized by a mix of global specialty chemical suppliers, regional distributors, and niche organometallic specialists. American Elements, headquartered in Los Angeles, California, has positioned itself around a broad organometallic portfolio, offering aluminium tert-butoxide in multiple purity grades for non-aqueous applications that span solar energy and water treatment. Its strategic emphasis on application breadth and product availability allows it to serve customers who require consistent supply across varied technical contexts. Ereztech, operating in the United States, focuses on manufacturing and selling aluminium(III) tert-butoxide in both small and bulk volumes, with packaging options that include glass ampules, bottles, and metal bubblers. This flexibility in pack size and delivery format addresses a practical pain point for laboratory and pilot-scale users who need controlled quantities without compromising handling safety.
TCI Chemicals, based in Japan with U.S. operations in Philadelphia, offers aluminium tert-butoxide with purity exceeding 98 percent for laboratory and research use, available in catalog quantities with regional stocking. Its positioning reflects a strong emphasis on research-grade reliability and logistical proximity to scientific customers. Sigma-Aldrich, now part of Merck, supplies technical-grade aluminium-tri-tert-butoxide for chemical synthesis and reagent applications, leveraging a globally recognized brand and extensive distribution infrastructure. Thermo Scientific Chemicals, formerly Alfa Aesar, provides aluminium tert-butoxide at 97 percent purity in various pack sizes, catering to both laboratory and industrial reagent needs with an emphasis on standardized quality and broad catalog availability. ProChem, Inc., operating in the United States, manufactures and supplies aluminium t-butoxide as part of its broader specialty chemical product line, appealing to customers who value integrated sourcing and established industrial relationships.
In the Asia Pacific corridor, Sinochem Nanjing Corporation functions as an industrial supplier and factory manufacturer, offering aluminium tert-butoxide in wholesale quantities and reflecting the region's emphasis on scale and cost-competitive supply. Alfa Chemistry, based in the United States, provides aluminium tert-butoxide for experimental and research use with supporting documentation, targeting customers who prioritize traceability and technical clarity. These companies collectively illustrate a market where differentiation is achieved through a combination of purity assurance, packaging flexibility, regional availability, and application-specific support rather than through price competition alone.
The strategic positioning of leading players reveals several recurring advantages. First, companies that maintain distinct quality tiers and clear documentation protocols are better equipped to serve the divergent needs of research, pilot, and industrial customers. Second, suppliers with flexible packaging and delivery options reduce friction for buyers who require precise quantities or specialized handling formats. Third, organizations that combine manufacturing capability with reliable distribution networks are better positioned to manage supply continuity during periods of raw material volatility. The market concentration pattern, with the top three firms holding over half of revenue and the top five controlling nearly seventy percent, suggests that scale, brand trust, and compliance maturity remain powerful moats. At the same time, the presence of multiple regional and specialty suppliers indicates room for targeted differentiation, particularly for companies that can serve niche purity requirements or offer responsive local logistics.
Looking ahead, the competitive landscape is likely to evolve through selective consolidation, regional supply network expansion, and increased emphasis on technical service. Larger players may pursue acquisitions or partnerships to broaden purity-grade coverage, strengthen geographic reach, or integrate downstream application support. Mid-tier and regional suppliers may differentiate by offering faster turnaround, customized documentation, or specialized handling for sensitive applications. New entrants will face the dual challenge of meeting stringent quality expectations while competing against established distribution channels and customer relationships. The net effect is a market that rewards operational discipline, technical credibility, and customer-centric flexibility over undifferentiated volume competition.
Forward View: Three Trends Shaping the Next Three to Five Years
The first major trend is the continued elevation of purity and consistency as commercial imperatives. As semiconductor, electronics, and advanced catalysis applications mature, downstream customers will increasingly view material variability as a process risk rather than a tolerable compromise. Suppliers that invest in tighter control over trace impurities, moisture sensitivity, and particle uniformity will capture disproportionate value, particularly in applications where reagent performance directly influences yield, device reliability, or regulatory acceptance. This trend will likely accelerate the separation between premium-grade supply chains and standard-grade commodity channels, with margin differentiation widening accordingly.
The second trend is the growing importance of supply chain resilience and regional responsiveness. Given the sensitivity of input costs and the geographic dispersion of demand, procurement teams will continue to favor suppliers that can demonstrate multi-source procurement, regional inventory positioning, and transparent lead-time management. Companies that build flexible sourcing arrangements and maintain buffer strategies for critical feedstocks will be better positioned to navigate commodity repricing events without disrupting customer commitments. This resilience will become a competitive differentiator in its own right, particularly as customers seek to reduce exposure to single-point supply failures.
The third trend involves the expanding intersection of technical service and commercial growth. As applications become more specialized, customers will expect suppliers to provide not only material but also applicable documentation, handling guidance, and qualification support. Suppliers that can align their commercial offerings with the practical needs of research, pilot scaling, and industrial production will build deeper customer relationships and reduce churn. At the same time, potential risks remain. Raw material volatility, regulatory changes around organometallic handling, and shifts in downstream procurement budgets could introduce periodic demand softness or margin pressure. Companies that treat these factors as manageable variables rather than external shocks will be better prepared to sustain growth through cyclical disruptions.
Worldwide Aluminum Alkyls Market
Actionable Guidance for Decision-Makers
For manufacturers and suppliers, the priority is to align production and quality systems with the diverging requirements of high-purity and standard-grade segments while maintaining cost flexibility in the face of input volatility. Diversifying feedstock sourcing, regionalizing inventory where feasible, and investing in documentation and handling protocols will strengthen both margin resilience and customer trust. Differentiation should focus on reliability, technical support, and format flexibility rather than on price alone, particularly as downstream customers increasingly value supply continuity and qualification speed.
For investors, the market presents opportunities in companies with disciplined quality systems, flexible procurement models, and clear application-focused positioning. Attention should be directed toward suppliers that can demonstrate consistent performance across purity tiers, manage raw material exposure effectively, and serve high-growth application corridors without overextending into undifferentiated commodity competition. Due diligence should weigh not only current revenue profiles but also the ability to sustain supply reliability and technical credibility through periods of input cost fluctuation.
For procurement and supply chain leaders, the strategic focus should be on qualifying multiple capable suppliers, establishing clear purity and packaging requirements, and building contingency plans for feedstock-driven price movements. Engaging suppliers that offer transparent documentation, predictable lead times, and responsive technical support will reduce qualification risk and improve operational continuity. Evaluating total cost of ownership, including handling, storage, and qualification overhead, will yield better outcomes than focusing solely on unit price. Detailed segment-level data, regional cost structures, and customized procurement scenarios can further sharpen these decisions, and the full research report provides the granular breakdowns and scenario analysis needed to translate these strategic directions into specific operational plans.
Worldwide Aluminum Dimethyl Isopropoxide Market
For detailed analysis of this topic, please visit the official page: Worldwide Aluminium Tert Butoxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Modified Phenolic Resins Market: Why Asia Pacific’s 5.29% CAGR Drives Strategic Shifts
By pmarketresearch, 2026-09-18
Navigating the Modified Phenolic Resins Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The modified phenolic resins market has demonstrated steady expansion over the past five years, evolving from a mature specialty chemical segment into a strategically important enabler for higher-performance industrial applications. Total market revenue reached approximately $1,980.5 million in 2025, reflecting a compound annual growth rate of 5.29 percent across the forecast horizon extending through 2032. This trajectory signals more than incremental volume growth; it indicates a structural shift toward formulations that balance thermal resistance, adhesion strength, and environmental compliance across multiple downstream sectors. The expansion is particularly visible in application categories such as printing inks, coatings and varnishes, adhesives and sealants, friction materials, and foundry and abrasives, where end-users increasingly demand tailored resin architectures rather than commodity-grade alternatives.
Despite this positive momentum, the market is navigating several structural pressures that will define competitive positioning in the coming years. First, formulation complexity is rising as performance specifications tighten across automotive, electronics, and construction sectors. Traditional novolac and resol systems are being pushed to their limits in terms of curing speed, moisture resistance, and volatile organic compound management, forcing manufacturers to invest in modification chemistries that add technical and operational overhead. Second, feedstock volatility remains a persistent margin pressure point. Phenol pricing dynamics are closely tied to benzene and propylene fundamentals, and while recent price movements have provided temporary relief, regional cost disparities and logistics constraints continue to influence production economics. Third, regulatory and customer-driven sustainability mandates are reshaping procurement criteria. Lower formaldehyde emissions, biomass-derived inputs, and measurable carbon footprint reductions are transitioning from optional differentiators to baseline expectations in many end markets.
Together, these pressures create a clear inflection point: companies that treat modification as a cost center will face margin compression and customer attrition, while those that embed formulation agility, feedstock flexibility, and sustainability credentials into their operating models can capture premium positioning. The market is no longer rewarding scale alone; it is rewarding the ability to deliver modified systems that solve specific performance and compliance problems without disrupting downstream processing conditions.
Key Drivers of Market Evolution
Technical Innovation and Formulation Breakthroughs
Innovation in modification chemistry is one of the most meaningful value-creation levers in this market. Rather than relying on standard phenolic backbones, leading developers are integrating rosin, epoxy, cashew nut shell liquid, rubber-based modifiers, and lignin-derived inputs to tune rheology, heat resistance, and curing behavior. These modifications are not incremental tweaks; they enable resins to perform in environments where conventional systems struggle, such as high-temperature friction applications, moisture-exposed coatings, and bonding interfaces that require low emission profiles. The commercialization of lignin-modified resol-type resins illustrates how biomass substitution can reduce fossil resource dependence while maintaining structural integrity. When a lignin-modified formulation achieves a lower carbon footprint and meets recognized industrial standards for plywood and laminated wood products, it demonstrates that sustainability and performance can be aligned rather than traded off.
PW Consulting Chemical & Energy Research Center
Policy, Regulation, and Compliance Pressure
Regulatory environments and customer sustainability programs are accelerating adoption of modified resins that address emission limits and material sourcing expectations. Formaldehyde management remains a central focus across construction, wood products, and consumer-facing applications, while broader decarbonization goals are influencing procurement decisions in automotive and industrial supply chains. Compliance is increasingly viewed as a design parameter rather than a post-production checkpoint. Manufacturers that proactively develop low-emission and biomass-integrated formulations gain a smoother path through certification requirements and a stronger narrative for downstream customers facing their own reporting obligations. This dynamic is particularly impactful in regions where construction and wood composite standards are tightening, as modified resins that satisfy those specifications can secure longer-term qualification status and reduce the risk of formulation swaps.
Rosin Modified Phenolic Resin Market
Demand-Side Shifts in End-Use Sectors
Demand behavior is changing as end-users look for resins that do more than bind or coat. Printing ink formulators seek modifiers that improve gloss, adhesion, and drying consistency on diverse substrates. Coatings and varnishes customers require enhanced weatherability and chemical resistance without sacrificing application properties. Adhesive and sealant producers need systems that cure predictably across varying humidity and temperature conditions while maintaining bond strength. Meanwhile, friction material and foundry applications continue to demand heat stability, wear resistance, and reliable performance under mechanical stress. This multifaceted demand profile pushes suppliers to offer more granular product portfolios and to engage earlier in customer development cycles. The practical implication is that revenue growth is increasingly tied to solution-level engagement, not just volume sales of standard grades.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by feedstock behavior, regional production economics, and the operational footprint required for modified formulations. Phenol pricing has shown downward movement through 2025, and near-term outlooks suggest a range that remains sensitive to benzene supply, demand recovery in downstream derivatives, and regional differentials. At the same time, Northeast Asia and other key production zones exhibit their own cost baselines, meaning that competitiveness is partly determined by location, logistics, and feedstock access. For modified resins specifically, the cost equation also includes additional processing steps, quality control for consistency, and the ability to handle solvent-based, water-based, or solid-form outputs without sacrificing throughput. Companies that can manage these layers efficiently gain room to invest in higher-margin custom grades while maintaining competitive base pricing.
Competitive Landscape and Leading Strategies
The competitive environment in modified phenolic resins is characterized by a mix of global specialists, regional manufacturers, and custom toll producers, with a meaningful portion of market value concentrated among a relatively small group of established players. This concentration reflects the importance of formulation expertise, application testing, consistent quality, and long qualification cycles in end markets such as electronics, automotive, abrasives, and wood composites. At the same time, the landscape is not static; differentiation is becoming more pronounced as companies pursue distinct strategic positions.
Several themes define how leading companies are positioning themselves. One is biomass and sustainability integration. Companies that have introduced lignin-modified or other biomass-linked phenolic systems are signaling a shift from incremental improvement to feedstock-level differentiation. This strategy is especially relevant where customers need measurable carbon footprint reductions and certification support, because it combines technical performance with a credible sustainability story. Another theme is application specialization. Manufacturers with deep roots in friction materials, abrasives, refractory products, insulation, and industrial bonding are expanding their modified portfolios to serve those sectors with tailored resol and novolac options. This approach reduces exposure to commoditization and builds stickier relationships with customers that rely on specific processing characteristics. A third theme is format and service flexibility. Offering pastilles, powders, flakes, lumps, solvent-based, and water-based forms allows suppliers to match downstream handling requirements and reduce conversion friction for buyers. Custom toll manufacturing and certified quality systems further strengthen this value proposition by enabling smaller or more specialized buyers to access modified grades without building their own formulation infrastructure.
The market is also showing signs of both consolidation and fragmentation, depending on the segment. Larger global participants are well placed to invest in broader application portfolios and international distribution, while regional manufacturers can compete on responsiveness, local feedstock dynamics, and custom formulation services. New or expanding entrants often find opportunity in niche modifications, contract production, or region-specific compliance needs rather than attempting to compete directly on scale. Overall, the trajectory favors companies that combine technical credibility with commercial flexibility. Price competition remains present, but the more decisive battles are being fought over qualification speed, consistency, emission performance, and the ability to co-develop modified systems that fit specific end-use conditions.
Forward-Looking Trends for the Next Three to Five Years
One of the clearest near-term trends is the continued integration of sustainable feedstocks and lower-emission formulations into mainstream product lines. Modified phenolic resins that incorporate biomass-derived inputs or deliver measurable carbon footprint reductions are likely to move from specialty offerings toward broader commercial adoption, especially in wood composites, coatings, and industrial adhesives where sustainability credentials influence procurement decisions. The commercial opportunity here lies in pairing formulation performance with certification support and transparent lifecycle messaging, enabling suppliers to command preference in qualified supply chains.
A second trend is the growing importance of application-specific customization over standardized volume supply. As end-use requirements become more varied, buyers will increasingly seek resin systems optimized for curing behavior, emission limits, substrate compatibility, and processing conditions. This creates opportunities for manufacturers that can shorten development cycles, provide robust technical support, and maintain consistent quality across smaller batch sizes or custom formats. Companies that build modular modification platforms will be better positioned to scale these solutions without sacrificing margin.
A third trend involves feedstock cost and regional supply dynamics remaining a strategic variable rather than a background condition. Even with recent price moderation, phenol-related economics will continue to influence margin structures and sourcing decisions. Businesses that diversify input strategies, optimize regional production footprints, and maintain flexibility across solvent-based and water-based systems will be better equipped to manage cost fluctuations while preserving performance standards. The primary risk is that feedstock volatility, regulatory changes, or formulation compliance failures could disrupt pricing stability and qualification timelines, particularly for newer biomass-integrated products that still require broad market acceptance.
Strategic Actions for Decision Makers
For resin manufacturers and formulators, the priority is to treat modification capability as a core commercial asset. Building a broader library of proven modified grades, strengthening application testing, and offering format flexibility can improve qualification success and protect margins. Investing in low-emission and biomass-linked options should be paired with credible certification and customer-facing documentation so that sustainability claims translate into procurement advantage rather than remaining symbolic.
For investors and corporate development teams, the most compelling opportunities lie in capabilities that combine formulation expertise with application proximity. Assets that enable custom toll production, regional compliance support, or rapid co-development with end-users are likely to hold strategic value as buyers seek more tailored solutions. Due diligence should focus on technical depth, consistency records, feedstock flexibility, and the ability to scale modified systems without eroding quality or cost discipline.
For procurement and sourcing leaders, the practical move is to qualify modified suppliers earlier and evaluate them on more than unit price. Consistency, emission performance, processing compatibility, and sustainability documentation increasingly affect total cost and operational risk. Developing a shortlist of partners with demonstrated modification breadth and reliable technical support can reduce reformulation churn and improve supply resilience across printing inks, coatings, adhesives, friction materials, and foundry applications. Given the pace of change in feedstock economics, regulatory expectations, and formulation options, timely access to detailed market segmentation and company-level intelligence can sharpen these decisions and reduce uncertainty in planning cycles.
Phenolic Resins Market
For detailed analysis of this topic, please visit the official page: Modified Phenolic Resins Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Rodder Machine Market: Why 5.01% CAGR Rewires the $608M 2032 Outlook
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Rodder Machine Market
Market Overview and Core Challenges
The global rodder machine market has demonstrated steady expansion over the past half-decade, evolving from a mature, cyclical maintenance sector into a strategically significant equipment segment driven by aging infrastructure and operational efficiency mandates. Recent historical trajectories show consistent revenue growth, with the market surpassing initial estimates as municipalities and industrial operators prioritize mechanical cleaning over chemical or high-pressure alternatives. The compound annual growth rate through the mid-2030s is projected at approximately 5 percent, signaling a transition from flat, maintenance-only spending to more structured capital allocation cycles. This growth trajectory reflects not merely inflationary adjustments but a fundamental shift in how utility operators approach pipeline integrity, wastewater transport reliability, and underground utility access.
Despite the positive momentum, the industry navigates several structural friction points that will define competitive positioning over the next cycle. First, the sector faces a pronounced technological inflection point as municipalities and contractors increasingly evaluate battery-electric and autonomous-assisted rodding platforms. Traditional diesel-driven continuous and sectional rodder systems are being stress-tested by noise ordinances, indoor operating constraints, and evolving emissions standards in dense urban environments. Operators must balance the proven torque and runtime reliability of legacy powertrains against the operational advantages of zero-emission alternatives that demand new servicing protocols, battery lifecycle management, and higher upfront capital outlays.
Second, supply chain volatility in critical input materials directly pressures manufacturing economics and end-user pricing stability. Rodder frames, drive components, and transmission cables rely heavily on steel and aluminum, meaning commodity price swings translate rapidly into cost-of-goods uncertainty. Manufacturers with lean inventory practices or exposure to single-source component suppliers face margin compression during procurement disruptions, while end customers encounter elongated delivery timelines and unpredictable total cost of ownership calculations. This dynamic is forcing both OEMs and procurement departments to reevaluate supplier diversification, long-term service agreements, and equipment financing models.
Third, the market is experiencing a geographic and application-level divergence that complicates consolidated go-to-market strategies. Infrastructure renewal programs in developed regions emphasize compliance-driven preventive maintenance and inspection-linked cleaning cycles, whereas rapidly urbanizing regions focus on capacity expansion and new utility network deployment. Simultaneously, end-use demand patterns are shifting: routine municipal sewer cleaning remains the largest consumption driver, but specialized industrial pipe maintenance and telecommunications ducting workflows are adopting lighter, precision-oriented rodding configurations. Navigating this divergence requires equipment providers and service operators to avoid one-size-fits-all positioning and instead align product portfolios, distribution partnerships, and service capabilities with distinct operational realities.
Key Demand Drivers Shaping Market Direction
Technological Innovation and Platform Evolution
The most consequential driver reshaping competitive expectations is the ongoing transformation of rodder machine architecture. Continuous rodders continue to dominate heavy-duty mainline applications because their uninterrupted cable path delivers consistent torque penetration over extended runs, making them indispensable for bulk debris removal, root cutting, and silt disruption in large-diameter lines. At the same time, sectional rodder platforms retain a strong footprint in scenarios requiring maneuverability, tool interchangeability, and targeted cleaning in constrained access points or shorter pipe segments. The real strategic shift lies in how power delivery, control systems, and cable management are being redesigned. Manufacturers are integrating torque feedback logic, improved drum tensioning, and ergonomic operator controls to reduce fatigue and improve cleaning consistency across varying soil and obstruction conditions. These refinements are not cosmetic; they directly affect cycle time, repeat-clearing incidents, and equipment utilization rates, which are critical metrics for municipal departments managing large route schedules and contractors billing by job efficiency.
Regulatory Pressure and Compliance-Driven Maintenance
Environmental and public health regulations are functioning as a powerful demand anchor, particularly in North America and Europe. Strict wastewater inspection mandates and sanitary sewer overflow prevention requirements are compelling municipalities to maintain more frequent cleaning and inspection cycles. In practice, this means rodding equipment is no longer treated as a discretionary repair tool but as part of a compliance-linked asset management strategy. On the European side, directives favoring non-invasive cleaning methods are accelerating adoption of precision rodder configurations that minimize pipe stress and reduce the need for excavation. The regulatory environment effectively sustains baseline demand while pushing operators toward equipment that can document performance, withstand inspection schedules, and operate within tighter environmental constraints. This creates a durable purchasing rationale even during budget compression cycles, because deferred cleaning can trigger regulatory penalties and higher remediation costs downstream.
Demand-Side Behavior and Operational Priorities
End-user behavior is evolving as municipalities, industrial facilities, and telecommunications contractors recalibrate how they balance labor, downtime, and equipment flexibility. Municipal water and sewer departments are increasingly seeking equipment that can handle mixed debris profiles—stones, grit, sludge, and root intrusion—without switching between multiple specialized machines. This operational reality favors flexible drive configurations, durable cable systems, and tool kits that support rapid attachment changes. Industrial pipe maintenance teams are prioritizing machines capable of reaching longer runs and larger diameters with controlled feed force to avoid damaging sensitive process piping. Meanwhile, ducting and telecom contractors are leaning toward lightweight rodding and pulling systems that support tracer functions and conduit access without disrupting active service corridors. Across these segments, the common theme is predictable performance under variable operating conditions, which elevates the importance of machine reliability, service availability, and operator training support over pure purchase price.
Supply Chain Realities and Cost Structure Pressures
Manufacturing economics are being reshaped by material intensity and component complexity. Steel and aluminum remain foundational to rodder frames, reel structures, and cable assemblies, so raw material price fluctuations directly influence production costing and pricing stability. Beyond commodities, the broader supply chain context is encouraging manufacturers to reconsider sourcing strategies, inventory buffers, and aftermarket parts availability. Service networks are becoming a competitive differentiator because downtime during a peak cleaning season or an emergency blockage event carries disproportionate operational and reputational costs. This environment rewards manufacturers that can provide responsive parts logistics, clear maintenance intervals, and deployable field support. It also encourages fleet operators to evaluate total cost of ownership more carefully, weighing fuel or battery management costs, expected cable life, and servicing lead times rather than focusing solely on sticker price.
Competitive Landscape and Leading Strategies
The competitive field in the rodder machine market is shaped by a mix of established equipment manufacturers, specialized regional players, and emerging suppliers targeting adjacent cleaning and conduit workflows. Market concentration indicates that a handful of leading firms capture a meaningful share of revenue, yet the presence of multiple capable manufacturers suggests room for differentiation through product architecture, powertrain strategy, and service execution rather than pure scale. Leaders are not competing solely on machine size or maximum run length; they are competing on how well their platforms fit the operational environment of the buyer.
Strategic Positioning and Differentiation
Leading manufacturers are defining their advantage through targeted capability sets and clear end-user alignment. RIDGID, for example, has built recognition around heavy-duty sectional rodder systems designed for straight main line work in larger-diameter sewer and drain lines, emphasizing torque delivery, tool kit breadth, and suitability for municipal, institutional, and industrial applications. General Pipe Cleaners has reinforced its position through sectional drain cleaning machines engineered for tough clogs in long runs and larger pipes, with two-way operation supporting professional and municipal use cases. Electric Eel Manufacturing Company continues to serve professional, rental, and municipal markets with drum and continuous cable cleaning platforms that emphasize long-standing product familiarity and broad market accessibility. Sewer Equipment Co. of America positions its rodder series within a broader sewer cleaning lineup, highlighting mechanical rodding approaches that align with water-conserving operational priorities. Spartan Tool rounds out the field by providing rodding machines aimed at professional contractors and municipal users, competing on practical usability and service reach.
Diverging Product and Powertrain Strategies
TSE International illustrates how product strategy is responding to evolving operational constraints. The company continues to promote its diesel OK Champion S660 alongside the battery-electric S660E, positioning the electric variant as a quiet, emission-free option for sewer and conduit maintenance. This dual-track approach reflects a practical market reality: many fleets still require diesel horsepower for demanding heavy-duty work, while certain municipalities and enclosed-site operators increasingly value emission-free, low-noise alternatives that can also serve as complements or substitutes for vacuum truck deployments in specific workflows. The availability of a self-contained battery power source is not merely a product feature; it represents a strategic bet on the growing demand for operational flexibility in areas where noise, emissions, and site access restrictions influence equipment selection. Similarly, Hebei Sinta FRP Co., Ltd. demonstrates how international suppliers are expanding the competitive boundary by focusing on fiberglass duct rodders, cobra cable pullers, and traceable duct rodding accessories for cable laying and pipeline cleaning applications, broadening the competitive conversation beyond traditional sewer cleaning into utility and telecom ducting workflows.
Worldwide Shaper Machine Market
Market Evolution and Structural Shifts
The competitive landscape appears to be moving along two parallel tracks. On one track, established manufacturers are deepening their positions through product refinements, service coverage, and targeted municipal procurement engagement. On the other, new entrants and adjacent-market suppliers are introducing specialized configurations that blur the line between sewer rodding, conduit cleaning, and cable pulling. This combination of deepening incumbency and specialized encroachment is likely to increase segmentation intensity. Expect more emphasis on bundling equipment with accessory ecosystems, training, and service agreements, as well as greater competition around procurement responsiveness, as evidenced by recent municipal bidding activity for integrated truck-mounted rodder systems. Competitive advantage will increasingly belong to organizations that can align hardware, powertrain choice, parts logistics, and bid-ready specification support with the specific operational requirements of each buyer segment.
Forward Trends and Commercial Implications
Over the next three to five years, the rodder machine market is likely to be defined by a small number of intersecting trends that carry clear commercial implications. First, electrification and low-emission platform adoption will broaden beyond niche applications. Battery-electric rodders will continue to gain traction in urban environments, enclosed facilities, and jurisdictions with restrictive noise or emission policies. The commercial opportunity lies not simply in selling electric machines, but in developing battery management services, charging logistics guidance, and application-specific sizing expertise that help buyers avoid underpowered purchases or unrealistic runtime expectations. Manufacturers that bridge the gap between electric capability and real-world job conditions will capture a premium position in an increasingly segmented market.
Second, infrastructure spending and urbanization-driven utility expansion will sustain demand while shifting the purchase rationale toward lifecycle performance. As municipal wastewater networks, storm drain systems, and underground utility corridors receive renewed attention, rodding equipment will be evaluated through the lens of route efficiency, repeatability, and reduced repeat-clearing incidents. This trend favors suppliers and service providers that can demonstrate how machine design, cable durability, and operator ergonomics contribute to measurable operational outcomes. The upside for dealers and manufacturers is stronger aftermarket relevance: spare parts, cable replacement programs, and preventive maintenance contracts will gain importance as fleets look to stabilize uptime across seasonal demand peaks.
Third, procurement processes will become more specification-driven and integrated. Recent municipal bid activity for truck-mounted jet rodder platforms indicates that buyers increasingly view rodding capability as part of a broader vehicle and service configuration rather than an isolated tool purchase. This shift creates opportunities for equipment providers that can support bid documentation, performance specifications, and configuration flexibility tailored to specific debris profiles and line sizes. However, the same trend introduces uncertainty: budget timing, procurement lead times, and evolving municipal priority lists can delay purchase cycles, and commodity-driven cost pressure may complicate pricing commitments. Stakeholders that build flexibility into their supply planning and maintain clear communication around specification trade-offs will be better positioned to convert demand into closed deals.
Strategic Recommendations for Decision-Makers
For equipment manufacturers, the priority is to align product roadmaps with the dual reality of diesel-dependent heavy-duty demand and accelerating interest in low-emission, low-noise operation. Rather than treating electrification as a separate product line, integrate powertrain options into a coherent platform strategy that clarifies application fit, runtime constraints, and service requirements. Invest in parts availability, field support coverage, and configuration guidance that help procurement teams specify the right machine for each use case, because specification confidence is becoming a decisive factor in municipal and contractor purchasing.
PW Consulting
For investors and strategic buyers, the most valuable signals are not headline growth rates alone but the structural durability of demand drivers and the competitive differentiation potential of service ecosystems. Equipment segments tied to compliance-driven maintenance, utility expansion, and specialized ducting workflows offer defensible revenue logic, especially where aftermarket parts, cable replacement cycles, and service responsiveness create recurring value. Evaluate exposure to raw material volatility and assess whether target companies have pricing strategies, supplier diversification, or value-added service models that can protect margins through procurement cycles.
For municipal operators, contractors, and procurement teams, the immediate focus should be on total cost of ownership alignment rather than unit price comparison. Match machine type, cable configuration, and power source to the actual debris mix, pipe diameter range, and site access constraints of the job portfolio. Where possible, structure purchasing decisions to include service response expectations, parts lead times, and operator training support, since these operational factors often determine whether equipment delivers its intended efficiency over multiple seasons. Anticipate tighter specification requirements and longer procurement cycles by engaging early with equipment providers who can translate operational needs into bid-ready configurations.
Worldwide Die Sorters Market
Detailed segmentation data, procurement mapping, and company-specific capability assessment can sharpen these decisions further, particularly when evaluating regional demand intensity, product fit by application, and competitive positioning across the largest revenue pools. More granular analysis is available in the PW Consulting report on the worldwide rodder machine market for teams that need to translate these strategic trends into procurement timing, product portfolio decisions, or investment prioritization.
For detailed analysis of this topic, please visit the official page: Worldwide Rodder Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com