
Blogs
Strategic Intelligence for the Pseudomonas Aeruginosa Infection Treatment Market: Navigating a $2.8 Billion Horizon (2026-2032)
The global landscape for treating Pseudomonas aeruginosa infections is undergoing a profound transformation, driven by the relentless pressure of antimicrobial resistance, evolving regulatory frameworks, and a shifting clinical consensus on the management of difficult-to-treat Gram-negative pathogens. Plasmid-mediated resistance mechanisms, carbapenem-sparing strategies, and the emergence of novel beta-lactam/beta-lactamase inhibitor combinations have collectively redefined the therapeutic armamentarium available to hospitalists, infectious disease specialists, and critical care teams. Against this backdrop, PW Consulting is proud to present our comprehensive Worldwide Pseudomonas Aeruginosa Infection Treatment Market research, a strategic intelligence asset designed to equip pharmaceutical executives, investors, and healthcare strategists with the precise, forward-looking insights necessary to make confident decisions in 2026 and beyond.
This report does not merely catalog historical revenue streams. It constructs a multidimensional view of where the market stands at its 2025 baseline of approximately 1,942.4 million USD, how it reached that threshold through a disciplined progression from 1,484.2 million USD in 2020, and how it is projected to breach the 2,000 million USD mark in 2026 before charting a sustained upward arc through 2032. Executives operating in the antibiotic and anti-infective space require more than top-line figures. They need to understand which therapeutic classes are consolidating market share, which clinical indications are absorbing the heaviest treatment volumes, how reimbursement philosophies are recalibrating across major healthcare systems, and which competitive moves will define the next wave of portfolio optimization. Our analysis is built to answer those questions with surgical precision while preserving the confidentiality of the granular data that drives our forecasting engine.
A Data-Rich Foundation for Executive Decision-Making
Any credible market evaluation begins with a disciplined historical lens. Over the 2020 to 2025 assessment window, the global Pseudomonas Aeruginosa Infection Treatment Market expanded from 1,484.2 million USD to 1,942.4 million USD, reflecting a compounding trajectory shaped by rising hospital-acquired infection rates, increased adoption of newer antipseudomonal agents in stewardship-aligned protocols, and persistent demand across both branded and generic channels. The forward-looking narrative extends through 2032, with the market projected to reach approximately 2,825.5 million USD by the close of the forecast horizon. This pathway implies a compound annual growth rate of 5.51 percent, a figure that captures both organic volume expansion and the continuous rotation toward higher-value combination therapies that address resistant phenotypes.
Rather than treating this growth as a monolithic trend, our research decomposes the market into clinically and commercially meaningful dimensions. We analyze how different drug classes are navigating shifting susceptibility patterns, how regional healthcare infrastructures are modulating access and adoption, and how specific infection sites are driving differentiated prescribing behaviors. The report deliberately preserves these structural splits within our proprietary analytical framework, requiring stakeholders to engage directly with the complete dataset to fully map the terrain. This approach ensures that the intelligence you receive is not diluted into generic commentary but delivered as an actionable, decision-grade resource.
What This Report Delivers: Operational Depth for Strategic Planning
The Worldwide Pseudomonas Aeruginosa Infection Treatment Market research is structured to function as a working document for strategy, business development, and competitive intelligence teams. Every section has been engineered to translate epidemiological and pharmacological complexity into commercial clarity. The following components form the backbone of the analysis:
- Macro-market sizing and historical reconstruction spanning 2020 to 2025, with full-year revenue trajectories that anchor the 2025 baseline and set the stage for the 2026 to 2032 forecast window.
- A segmented evaluation of therapeutic classes, mapping the relative commercial weight of each category while highlighting the interplay between legacy antipseudomonal agents and next-generation beta-lactam/beta-lactamase inhibitor platforms.
- An indication-level breakdown that examines how respiratory tract infections, urinary tract infections, bacteremia, skin and soft tissue infections, and other clinical scenarios contribute to overall treatment demand and prescribing conventions.
- A regional analysis that contextualizes market dynamics across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, incorporating differences in formulary access, reimbursement structures, and local resistance epidemiology.
- Detailed company profiles that map the operational footprint, pipeline positioning, and recent strategic developments of the leading players shaping the competitive battlefield.
- A forward-looking competitive landscape assessment that integrates market concentration metrics, portfolio overlap analysis, and the strategic implications of recent regulatory and clinical milestones.
Throughout these sections, we maintain a disciplined separation between illustrative market architecture and the core quantitative splits that power our projections. Readers seeking the exact revenue contributions of each therapeutic category, each indication, and each geographic zone will find those figures embedded within the complete research instrument, accessible through our full report portal.
Competitive Landscape: Navigating a Concentrated but Dynamic Field
The Pseudomonas Aeruginosa Infection Treatment Market operates within a highly active competitive environment where a relatively concentrated set of large-cap pharmaceutical organizations coexist alongside specialized anti-infective developers and global generic manufacturers. Our concentration analysis indicates that the top three participants collectively command a meaningful share of total market revenue, while the top five extend their footprint to a dominant aggregate position. This structural reality does not imply a static hierarchy. Instead, it reflects a landscape in which established beta-lactam platforms, combination inhibitor strategies, siderophore cephalosporins, and a steady stream of generic entrants are continuously redefining share dynamics through clinical differentiation, regulatory approvals, and stewardship-aligned positioning.
Several anchor organizations define the strategic contours of this market. Pfizer Inc. maintains a deep-rooted presence in hospital and critical care settings through its antipseudomonal antibiotic portfolio, including its longstanding piperacillin-tazobactam platform, reinforcing its relevance in severe infection management. Merck & Co., Inc. has strengthened its positioning through imipenem-cilastatin-relebactam for complicated urinary tract infections, intra-abdominal infections, and hospital-acquired or ventilator-associated bacterial pneumonia, broadening its appeal in resistant Gram-negative contexts. AbbVie Inc., through its Allergan affiliation, continues to expand its ceftazidime-avibactam footprint while extending its reach with the recent approval of aztreonam-avibactam, an asset designed to address scenarios where treatment options are constrained by multidrug resistance.
Shionogi & Co., Ltd. has emerged as a distinctive force with cefiderocol, a siderophore cephalosporin engineered to target carbapenem-resistant and otherwise difficult-to-treat Pseudomonas aeruginosa. The company has advanced this platform through robust real-world evidence generation, including clinical presentations that underscore the role of cefiderocol in serious infection settings where Pseudomonas aeruginosa represents a substantial proportion of monomicrobial cases. Across 2025 and 2026, Shionogi's data disclosures have reinforced clinical cure rates and in vitro activity profiles that support the agent's positioning in complicated Gram-negative disease management. Teva Pharmaceutical Industries Ltd. and Lupin Pharmaceuticals continue to anchor the generic tier by supplying widely utilized antipseudomonal agents across multiple classes, sustaining access while exerting price and availability pressure on established product lines. AstraZeneca remains active with ceftazidime and broader anti-infective initiatives relevant to Gram-negative resistance, while Bristol Myers Squibb, Johnson & Johnson through Janssen, Novartis AG, Sanofi, and Baxter International Inc. each contribute distinct capabilities ranging from supportive injectable therapies to stewardship-focused programs and established antibiotic portfolios.
The strategic significance of this competitive architecture lies not in static market shares, but in the sequencing of innovation, the pace of generic infiltration, and the extent to which newer combination therapies align with guideline-driven prescribing. Our report unpacks these dynamics in detail, but the core percentage contributions and exact revenue alignments that determine relative competitive weight are reserved for clients accessing the full dataset.
The Regulatory and Clinical Context Shaping 2026 Strategy
No market assessment of this kind can be separated from the regulatory and clinical environment in which treatment decisions are made. Between January and February 2025, the U.S. Food and Drug Administration reinforced its recognition of standardized susceptibility testing frameworks for several antipseudomonal agents, including amikacin, cefepime, and ceftazidime, while reevaluating its position on polymyxin breakpoints in light of limited pharmacokinetic and clinical outcome data. These actions matter because they influence how laboratories report susceptibility, how clinicians interpret MIC values, and how manufacturers position their compounds within diagnostic and therapeutic workflows.
Simultaneously, clinical guidance continues to shape demand patterns. The 2024 IDSA antimicrobial resistance guidance, which remains active through 2025 and 2026, recommends a preferential approach to newer beta-lactam/beta-lactamase inhibitors for difficult-to-treat resistant Pseudomonas aeruginosa. This guidance elevates the strategic relevance of agents such as ceftolozane-tazobactam, ceftazidime-avibactam, imipenem-relebactam, and cefiderocol in treatment algorithms where resistance narrows the therapeutic window. At the same time, the European Commission's earlier authorization of aztreonam-avibactam for infections with limited treatment options illustrates how regulatory pathways in major markets are opening doors for combination therapies designed to address resistant Gram-negative organisms, including Pseudomonas contexts.
On the supply and manufacturing side, antibiotic production for beta-lactams and aminoglycosides continues to rely on globally distributed active pharmaceutical ingredient networks. Generic producers play an essential role in maintaining availability, but they also influence margin structures, tender dynamics, and the speed at which new branded entrants can capture share in hospital formularies. These are precisely the kinds of interdependencies that our report maps in depth, while withholding the specific quantitative allocations that would allow competitors to reverse-engineer our forecasting assumptions.
Why This Research Is Critical for 2026 Decision-Making
As pharmaceutical companies, investors, and healthcare strategists plan their next moves, three structural questions dominate the agenda. First, how will the balance between branded combination therapies and generic antipseudomonal agents evolve as resistance patterns continue to shift and stewardship programs refine prescribing behavior. Second, where will clinical demand concentrate across infection sites, and which therapeutic categories will be best positioned to capture that demand under evolving guideline recommendations. Third, how should organizations interpret the competitive actions of major players who are simultaneously defending legacy franchises, expanding into newer combination platforms, and integrating real-world evidence to support adoption in high-acuity settings.
Our analysis is built to address these questions directly. The 2026 market projection of approximately 2,033.6 million USD serves as a strategic inflection point, marking the beginning of a forecast period in which growth is expected to be driven by sustained clinical reliance on antipseudomonal therapies, continued uptake of newer agents in resistant infection pathways, and the ongoing interplay between premium combination products and cost-sensitive generic alternatives. The trajectory from 2026 through 2032 is not a straight line; it reflects the influence of regulatory decisions, guideline updates, manufacturing realities, and the pace at which clinicians adopt next-generation options in the face of limited-treatment scenarios.
Worldwide Pseudomonas Aeruginosa Infection Treatment Market
Worldwide Buruli Ulcer Treatment Market
Executives who engage with this research will emerge with a clearer understanding of where value is accumulating, where pressure is intensifying, and how to prioritize engagements across geographies, indications, and drug classes. The market concentration environment, the prominence of major hospital-focused portfolios, and the steady rhythm of regulatory and clinical updates all point toward a landscape that rewards organizations with precise, forward-looking intelligence rather than reactive assumptions.
Access the Full Strategic Blueprint
This article is intended as a gateway, not a substitute for the complete research product. The Worldwide Pseudomonas Aeruginosa Infection Treatment Market study contains the granular segmentation data, regional revenue architectures, therapeutic class splits, indication-level demand distributions, and company-specific strategic assessments required to build defensible plans in 2026 and beyond. Those elements are intentionally held within the full report to preserve analytical integrity and deliver actionable exclusivity to our clients.
For leadership teams that need to align R&D priorities, portfolio strategy, market access planning, and competitive positioning with a rigorously constructed view of this market, the complete research instrument offers the depth and precision that high-stakes decisions demand. The forecast window ahead will be shaped by resistance evolution, stewardship policy, regulatory milestones, and the strategic choices of globally active pharmaceutical organizations. PW Consulting's latest market research provides the structured intelligence necessary to navigate that environment with confidence, discipline, and strategic clarity.
For detailed analysis of this topic, please visit the official page: Worldwide Pseudomonas Aeruginosa Infection Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global TPS Cable Market Hits $52.2B in 2025, 6.29% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the 2026 Market Landscape: Inside the Worldwide Thermoplastic-Sheathed Cable Market
The worldwide thermoplastic-sheathed cable market stands at a critical juncture as enterprises navigate a decade defined by infrastructure modernization, energy transition mandates, and shifting supply chain architectures. Our latest Worldwide Thermoplastic-sheathed Cable Market study delivers a comprehensive strategic foundation for decision-makers operating across manufacturing, procurement, and capital allocation functions. Designed for immediate deployment in 2026 planning cycles, this research translates multi-year trajectory data, regulatory inflection points, and competitive maneuvers into actionable intelligence. Below, we outline the analytical architecture, contextual drivers, and competitive mapping that position this report as an essential reference for enterprise strategy.
Market Trajectory and Structural Shifts
Over the historical observation window from 2020 through 2025, the sector demonstrated consistent expansion, moving from approximately 38,450 million USD to a baseline of 52,150 million USD by the close of the reference period. This progression reflects sustained deployment across power distribution, building wiring, and industrial control environments, underpinned by steady urbanization and grid modernization programs.
The forward-looking horizon from 2026 through 2032 outlines a continued upward path, advancing toward a projected 79,981 million USD by the terminal forecast year. The compound annual growth rate of 6.29 percent signals a mature but resilient demand environment, where volume expansion is increasingly coupled with specification upgrades, compliance-driven material substitutions, and regional sourcing realignments. For executives mapping capacity investments, inventory strategies, or market entry plans, this trajectory provides a calibrated baseline against which internal forecasts and scenario models can be stress-tested.
Importantly, the market structure reveals meaningful differentiation across product architectures, application channels, and geographic corridors. Flat configurations continue to command substantial share within mainstream wiring deployments, while circular and multi-core variants maintain specialized relevance in power routing, instrumentation, and complex harness assemblies. On the application side, residential construction and commercial building projects represent the dominant consumption corridors, with industrial infrastructure providing a steady, specification-sensitive demand layer that rewards manufacturers capable of delivering compliance-ready, durable solutions. Regionally, Asia Pacific anchors the largest consumption base, followed by North America and Europe, while Middle East and Africa and Latin America present growth corridors shaped by infrastructure spending cycles and import-dependency dynamics. These structural patterns are examined in depth within the full report, where segmentation interplay, demand elasticity, and regional procurement behaviors are mapped without the simplifications typically found in high-level summaries.
Regulatory Forces and Supply Chain Reconfiguration
The competitive and operational environment for thermoplastic-sheathed cables is being reshaped by overlapping regulatory, material, and trade dynamics. International standards such as IEC 60227-5 govern thermoplastic-insulated cables rated up to 450/750V, and the 2024 amendments that enhanced flame retardancy requirements have elevated the compliance burden for manufacturers serving building and infrastructure end markets. In parallel, the AS/NZS 5000.2:2022 specification continues to define performance expectations for thermoplastic-sheathed cables used in Australian electrical installations, reinforcing the importance of region-specific certification strategies for suppliers targeting Oceania and export-aligned markets.
These technical standards intersect with broader policy momentum. The global push for energy-efficient buildings under frameworks such as the EU Green Deal is accelerating demand for low-smoke zero-halogen thermoplastic cables, creating an estimated uplift of 5 to 7 percent annually in relevant demand segments. This shift rewards manufacturers that can align product portfolios with stricter emission, fire-safety, and sustainability expectations while maintaining cost competitiveness.
Material economics further complicate planning. PVC resin prices, which are central to thermoplastic sheathing production, averaged 1,200 USD per metric ton in the fourth quarter of 2025 amid relatively stable supply from Asia. While this provided near-term cost visibility, commodity volatility, logistics constraints, and regional availability differences continue to require active procurement hedging and supplier diversification. At the same time, trade policy has introduced meaningful sourcing realignment. US tariffs on Chinese thermoplastic cables increased to 25 percent under Section 301 in 2025, prompting buyers and distributors to shift sourcing toward Mexico and Vietnam. For manufacturers and channel partners, these developments are not merely cost variables; they are strategic determinants of plant location, inventory positioning, contract structure, and long-term market access.
Worldwide Thermoplastic-sheathed Cable Market
Competitive Architecture and Recent Industry Moves
The market remains moderately fragmented, with the top three firms accounting for approximately 18.45 percent of revenue and the top five reaching roughly 24.8 percent. This concentration profile suggests that while scale players hold meaningful influence, there is substantial room for specialized differentiation, regional execution strength, and specification-driven wins. The competitive field includes globally integrated manufacturers and sector-focused specialists, each pursuing distinct routes to advantage through product engineering, certification breadth, distribution reach, and project-level pipeline development.
Prysmian Group, headquartered in Milan, Italy, operates as a leading global manufacturer of thermoplastic-sheathed cables, including TPS power cables for residential, commercial, and industrial applications compliant with AS/NZS 5000.2 standards. Its recent showcase of new thermoplastic-sheathed low voltage cables for renewable energy at the Wire 2025 exhibition signals continued alignment with electrification and clean-energy infrastructure demand.
Nexans, based in Paris, France, produces thermoplastic insulated and sheathed cables such as NYY and similar TPS types for power distribution, mining, and construction worldwide. Its September 2025 launch of enhanced thermoplastic-sheathed cables with improved fire resistance for building applications underscores a product strategy centered on compliance and safety performance in construction end markets.
Southwire Company, located in Carrollton, USA, is a major US producer of thermoplastic-sheathed cables including THHN/THWN with PVC/thermoplastic sheathing for electrical installations. The June 2025 UL certification update for new thermoplastic-sheathed SIMpull cables reflects an ongoing emphasis on specification approval, channel readiness, and installer-friendly product design in the North American market.
LS Cable & System, headquartered in Seoul, South Korea, supplies thermoplastic-sheathed power and control cables for global energy and infrastructure projects. Its April 2025 contract award for an Australian data center project illustrates how infrastructure-linked demand and international project pipelines can create targeted growth opportunities for capable exporters.
In Japan, Sumitomo Electric Industries manufactures thermoplastic-insulated and sheathed cables for automotive, power, and industrial uses, while Furukawa Electric produces PVC/thermoplastic sheathed cables for power transmission and distribution. Both firms leverage strong engineering heritage and broad application coverage to sustain position across demanding performance environments.
NKT A/S, based in Brøndby, Denmark, offers thermoplastic-sheathed medium and low voltage cables for offshore and onshore applications, aligning its portfolio with energy-sector and harsh-environment requirements. Leoni AG, headquartered in Nuremberg, Germany, specializes in thermoplastic-sheathed cables for automotive and industrial sectors, differentiating through application-specific engineering and mission-critical reliability expectations.
In the Americas and Europe, Belden Inc., based in St. Louis, USA, provides thermoplastic-sheathed data, control, and power cables for harsh environments, while the Lapp Group, headquartered in Stuttgart, Germany, serves as a global supplier of ÖLFLEX thermoplastic-sheathed cables for machinery and automation. These players reinforce the importance of specialization, brand equity in industrial and connectivity segments, and the ability to support complex specification processes.
The competitive picture is not static. Recent launches, certification updates, trade-show positioning, and project awards indicate that leading participants are actively reshaping portfolios around fire performance, renewable-energy compatibility, installer efficiency, and project-scale supply reliability. For companies evaluating partnership, sourcing, or competitive response strategies, tracking these moves in the context of regional compliance requirements and procurement shifts is essential.
Research Architecture and Practical Utility
This study is structured to support both strategic planning and operational decision-making. Beyond aggregate market sizing and forward projections, the report examines the interplay between product types, application verticals, and regional demand patterns, enabling readers to identify where volume concentration, specification premiums, and growth accelerations are most likely to emerge. The segmentation analysis is designed to clarify not only where demand currently resides, but also how structural factors such as building codes, infrastructure spending, and procurement geography influence consumption behavior over the forecast period.
The competitive assessment extends beyond simple vendor listing. It maps corporate positioning, geographic coverage, application focus, and recent strategic developments to help stakeholders interpret who is gaining traction, where certification and product launches may alter specification outcomes, and how supply chain realignments could influence procurement choices. By embedding recent industry events within the broader market context, the report helps readers distinguish transient announcements from durable shifts in competitive dynamics.
Operational planners will also find value in the integration of material, regulatory, and trade considerations. The analysis addresses how PVC resin pricing dynamics, flame-retardancy amendments, low-smoke zero-halogen demand pull, and tariff-driven sourcing migration interact to shape cost structures, product design choices, and channel strategy. This multidisciplinary framing is intended to reduce the gap between market intelligence and executable plans, whether those plans involve capacity allocation, product roadmap decisions, distributor expansion, or risk-managed sourcing.
Implications for 2026 Decision-Making
As enterprises move into 2026 planning, the thermoplastic-sheathed cable market offers a case study in how mature demand growth, regulatory tightening, and trade reconfiguration can combine to create both risk and opportunity. The projected trajectory toward the 2032 horizon suggests that scale alone will not determine success; rather, competitive advantage will increasingly depend on compliance agility, specification alignment, regional sourcing competence, and the ability to respond to evolving building and infrastructure standards.
Thermoplastic Composites Market
For manufacturers, the imperative is to reconcile product development with the dual demands of performance upgrading and cost discipline, particularly as flame retardancy, low-smoke characteristics, and installer efficiency become more decisive in specification wins. For distributors and procurement teams, the challenge is to balance cost stability against geopolitical and tariff-related sourcing shifts, while maintaining access to certified, regionally appropriate product assortments. For investors and strategy teams, the opportunity lies in identifying where demand concentration, project pipeline momentum, and competitive positioning converge to support durable margin profiles and market-share gains.
The full Worldwide Thermoplastic-sheathed Cable Market report expands each of these dimensions with detailed segmentation interpretation, regional demand narratives, competitive benchmarking, and forward scenario context. It is designed to serve as a working reference for teams that need more than headline figures: teams that require a coherent, evidence-based view of how the market is structured, how it is changing, and where strategic leverage can be created in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Thermoplastic-sheathed Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Indoor Lighting Control Market to Hit $25.67B by 2032 at 8.52% CAGR
By pmarketresearch, 2026-09-16
Illuminating the Future: Strategic Imperatives in the Global Indoor Lighting Control Systems Market
Executive Perspective
The transition from conventional illumination to intelligent, connected indoor lighting control systems represents one of the most tangible yet complex operational shifts in modern facility management. As organizations across commercial, industrial, and residential sectors confront rising energy costs, stringent sustainability mandates, and the operational demands of hybrid work environments, the strategic deployment of lighting controls has evolved from a peripheral efficiency upgrade into a core infrastructure investment. This analysis introduces our latest comprehensive study, Worldwide Indoor Lighting Control Systems Market, and outlines why its findings carry direct decision-making value for executive teams, procurement leaders, and technology strategists navigating the 2026 landscape.
Market Trajectory and Macro-Scale Context
Over the past half-decade, the indoor lighting control sector has demonstrated consistent annual expansion, reflecting a structural acceleration rather than a cyclical upturn. The global market, valued at approximately 8,900 million USD in 2020, has steadily climbed through a 2025 base year valuation near 14,500 million USD. The trajectory through the 2026-2032 forecast window projects sustained growth, with total market size expected to reach roughly 25,667 million USD by the close of the decade. This expansion is underpinned by a compound annual growth rate of 8.52 percent, indicating durable demand across geographies and deployment types. Several structural forces explain this momentum. First, the rapid overhaul of commercial interiors to support flexible occupancy patterns has made networked lighting controls a prerequisite for both energy optimization and occupant experience. Second, regulatory frameworks in major industrial economies have shifted lighting controls from optional best practices toward default compliance requirements. Third, the convergence of lighting infrastructure with broader building management ecosystems has expanded the addressable scope of control platforms, transforming them from isolated switching mechanisms into data-generating nodes within integrated smart building architectures. Importantly, the market's growth profile does not suggest a homogeneous environment. Deployment preferences, technology adoption curves, and regional regulatory pacing create distinct prioritization matrices for stakeholders. Our research isolates these vectors without relying on top-line generalizations, enabling readers to map investment and product roadmaps against actionable market realities rather than aggregate industry narratives.
What the Study Delivers: Operational Intelligence for 2026 Decision-Making
The Worldwide Indoor Lighting Control Systems Market report is designed as a working reference rather than a high-level market overview. It provides structured, forward-looking intelligence that aligns with the planning cycles of hardware manufacturers, system integrators, facility operators, and capital allocators. The study's architecture prioritizes clarity in three operational dimensions: technology evolution, deployment contexts, and competitive positioning. At the technology layer, the analysis examines the ongoing interplay between wired and wireless control architectures. While traditional wired frameworks continue to anchor large-scale retrofits and mission-critical commercial environments due to their established reliability and deterministic performance, wireless and hybrid configurations are capturing disproportionate attention in renovation scenarios, modular commercial spaces, and multi-tenant residential properties. The study tracks how protocol standardization, mesh networking capabilities, and low-latency sensor integration are reshaping the practical trade-offs between installation complexity, scalability, and lifecycle cost. The application dimension extends beyond categorical labels to assess how control requirements diverge across environment types. Commercial facilities increasingly demand centralized management, daylight harvesting, and occupancy-responsive scheduling that can interface with broader operational systems. Industrial settings prioritize robustness, fault tolerance, and energy performance across expansive, high-bay environments. Residential deployments, meanwhile, are shaped by user experience expectations, retrofit feasibility, and the growing integration of lighting controls into home automation ecosystems. By mapping these distinctions against market dynamics, the report equips decision-makers with a clearer sense of where product positioning, service models, and pricing strategies will encounter the most friction or opportunity. The regional dimension provides a framework for evaluating demand maturity, regulatory exposure, and competitive intensity across major geographic markets. Rather than presenting isolated figures, the analysis connects regional trajectories to underlying drivers such as construction activity, renovation pipelines, energy policy enforcement, and local vendor ecosystems. This approach allows organizations to calibrate geographic expansion, supply chain planning, and partnership strategies in alignment with real-world market pacing.
Competitive Landscape: Positioning, Innovation, and Ecosystem Control
The competitive landscape in indoor lighting control systems is characterized by a moderate concentration of established players, interspersed with technology specialists and protocol-driven component suppliers. The combined market share of the top three firms sits at approximately 32.5 percent, while the top five collectively account for around 42.8 percent of total industry revenue. This structure signals a market that is neither dominated by a single platform monopoly nor so fragmented that differentiation becomes meaningless. Instead, competition hinges on technology interoperability, ecosystem integration, brand trust in large-scale commercial deployments, and the ability to move quickly into emerging protocol and sensor-driven use cases. Several leading organizations illustrate how competitive advantage is being constructed in this environment. Signify has advanced its Interact IoT-based control portfolio for commercial buildings, combining sensor intelligence, gateway architecture, and cloud management to support scalable indoor deployments. Lutron Electronics continues to emphasize flexible wired and wireless control lines for office and residential automation, with a strong track record in dimming, sensor integration, and system-level automation platforms. Acuity Brands has expanded its nLight platform presence by strengthening compatibility between wired and wireless controls and networked indoor management tools. Schneider Electric has positioned its EcoStruxure Building IoT approach as a convergence point for lighting control, HVAC, and security systems within smart building frameworks, emphasizing operational integration over standalone lighting performance. Legrand contributes through residential and commercial control solutions built around recognized protocols, supporting hotel, multi-family, and indoor commercial applications. ABB's Ability Smart Buildings offering extends the conversation further into energy-efficient indoor management with DALI and KNX integration. Meanwhile, component and control specialists such as ams-OSRAM, Tridonic, and Helvar focus on enabling technologies—smart control modules, DALI-2 and wireless-compatible drivers, and sensor-integrated DALI-based systems—allowing broader system designers to assemble interoperable indoor installations at scale. Additional players including Eaton, Delta Electronics, and Hubbell Lighting reinforce the market's breadth, each contributing distinct control architectures, wireless nodes, and commercial/industrial LED-focused solutions. Recent product and certification activity reinforces the strategic importance of interoperability and intelligent sensing. Signify showcased an updated Interact Office offering with AI-based occupancy sensing for commercial spaces. Lutron introduced a node-based wireless control line targeting indoor commercial environments. Acuity Brands achieved DALI-2 certification for its wireless sensors and controls, while Tridonic expanded thread-compatible wireless control support for indoor mesh networking. These developments are not isolated product announcements; they reflect a broader market transition toward standardized communication, plug-and-play compatibility, and occupancy-aware automation. Organizations evaluating vendor relationships, partnership structures, or internal R&D priorities should treat these shifts as early indicators of where cycle times, integration burdens, and end-user expectations are heading.
Industry Dynamics: Standards, Policy, and Cost Realities
The indoor lighting control market is shaped as much by external conditions as by technological innovation. Regulatory and standardization developments have increasingly functioned as market accelerators by reducing ambiguity around performance expectations and interoperability requirements. The EU Ecodesign Directive establishes performance expectations for lighting controls in non-residential buildings, reinforcing the financial and compliance case for control deployment. In parallel, the DALI-2 standard has become a critical reference point for indoor lighting control interoperability, introducing improved error handling and predictable device communication across multi-vendor environments. The KNX protocol continues to provide a widely certified foundation for multi-vendor indoor compatibility, supporting product breadth across thousands of certified implementations. At the regional level, policy frameworks such as the US Energy Policy Act have codified automatic shutoff control expectations for large buildings, embedding lighting controls into baseline operational compliance. Cost dynamics also play a central role in procurement and deployment decisions. Sensor hardware, particularly occupancy-sensing components used in commercial installations, has settled into a recognizable cost band that strongly influences total system economics during retrofits and new construction. While sensor pricing alone does not determine project viability, it interacts with labor intensity, commissioning complexity, and long-term energy savings to shape the adoption curve for different control architectures. The report uses these operational realities to help readers assess where system-level savings are most achievable and where installation friction may offset anticipated efficiency gains.
Why the 2026 Outlook Matters Now
The 2026-2032 forecast window is particularly consequential because it captures the intersection of several simultaneous transitions. Markets are moving beyond early adoption arguments and toward scale execution. Building operators are asking not whether to install controls, but how to standardize across portfolios, manage vendor diversity, and integrate lighting data into broader energy and space-utilization strategies. Technology providers, meanwhile, must navigate protocol evolution, sensor intelligence, cloud-based management, and the commercial realities of wired-versus-wireless deployment trade-offs. For executives, the strategic question is no longer centered on overall market size alone. The more valuable inquiries concern growth composition, competitive pressure points, technology substitution risk, and regional readiness. Where are wireless and hybrid models accelerating fastest? Which application segments are most exposed to standard-driven adoption? How are leading vendors differentiating around integration, service, and protocol support? And how should organizations interpret the balance between established incumbents and specialists competing in niche architectural or protocol-driven segments? The report provides the analytical scaffolding to answer these questions with greater confidence. By examining market structure, competitive moves, regulatory tailwinds, and deployment considerations together, it supports more disciplined planning for product strategy, procurement timing, partnership development, and market entry or expansion decisions.
Conclusion: Turning Market Intelligence into Actionable Advantage
Indoor lighting control systems have matured into an essential infrastructure category that sits at the crossroads of energy management, occupant experience, and smart building integration. The growth trajectory through 2032 reflects sustained structural demand, but the strategic opportunities within that trajectory are uneven and highly dependent on technology readiness, regulatory context, and application-specific requirements. Our Worldwide Indoor Lighting Control Systems Market study is designed to give organizations the depth they need to act, not just the summary they need to brief. It translates broad market momentum into operational insight, helping leadership teams evaluate where to invest, where to standardize, and where to differentiate. For readers seeking a fuller examination of segmentation behavior, vendor positioning, protocol adoption, regional pacing, and forward-looking scenario analysis, the complete report provides the comprehensive intelligence required to align strategy with the realities of the 2026 market.
Worldwide Indoor Lighting Control Systems Market
Worldwide Emergency Lighting Controller Market
For detailed analysis of this topic, please visit the official page: Worldwide Indoor Lighting Control Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Wood Gas Generator Market Hits $696.8M in 2025, 6.54% CAGR to $1,085.8M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence: Navigating the Wood Gas Generator Market Landscape in 2026
As the global energy paradigm shifts toward decentralized renewable solutions, the wood gas generator sector stands at a critical inflection point. For strategic leaders and industry stakeholders, understanding the trajectory of this market is not merely an academic exercise but a operational imperative. This article serves as an executive briefing on the findings contained within our latest Worldwide Wood Gas Generator Market research, outlining the macroeconomic forces, competitive dynamics, and technological trends that will define investment and operational decisions throughout the forecast period ending in 2032.
The urgency for this analysis stems from the accelerating convergence of regulatory support, raw material availability, and the economic necessity of energy independence. Our research provides a granular look at how these factors intersect, offering a roadmap for navigating the complexities of biomass gasification technology deployment.
Macro Market Trajectory and Growth Drivers
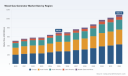
The historical performance of the wood gas generator market demonstrates a consistent upward trend, reflecting the global commitment to reducing carbon footprints while maintaining energy security. Our analysis tracks revenue performance from 2020 through the base year of 2025, revealing a sector that has resiliently navigated supply chain fluctuations and varying policy landscapes. In 2020, the market valuation stood at approximately 512.45 million USD. By 2025, this figure had grown to 696.84 million USD, indicating a robust rate of adoption across key industrial and residential sectors.
Worldwide Wood Gas Generator Market
Looking forward, the forecast period from 2026 to 2032 projects sustained expansion. The market is expected to initiate this phase at roughly 700.53 million USD in 2026, climbing steadily to reach an estimated 1085.75 million USD by 2032. This trajectory suggests a Compound Annual Growth Rate (CAGR) of 6.54 percent over the forecast window. Such growth is underpinned by several critical drivers, including the increasing demand for decentralized heat and power generation solutions that reduce reliance on centralized grids and fossil fuel imports.
Stakeholders must interpret these figures not just as historical records but as indicators of momentum. The transition from the mid-600 million USD range in 2024 to nearly 700 million USD in 2025 highlights a sector gaining traction. The subsequent years show an acceleration in value accumulation, suggesting that economies of scale and technological maturation are beginning to yield tangible financial results for manufacturers and operators alike.
Technological Segmentation and Regional Distribution
The market is not monolithic; it is defined by distinct technological approaches and geographic concentrations that dictate strategy. Our research delves deeply into the types of gasifiers driving this revenue, analyzing the performance and deployment trends of Downdraft, Updraft, Cross-draft, and Fluidized Bed gasifiers. Each technology offers specific advantages regarding feedstock flexibility, tar content in the producer gas, and operational scale. The comprehensive data within the full report breaks down how these technologies are prioritized across different use cases, allowing engineering and procurement teams to align hardware selection with specific project requirements.
Geographically, the market exhibits a clear hierarchy of maturity and demand. Europe remains a dominant force in terms of market contribution, driven by stringent EU emissions targets and strong incentives for decentralized biomass Combined Heat and Power (CHP) systems. Asia Pacific follows as a significant region, reflecting rapid industrialization and growing energy needs in emerging economies. North America also represents a substantial portion of the market, supported by both commercial applications and rural development initiatives. Latin America and the Middle East and Africa contribute to the global total, often focusing on specific industrial thermal applications or off-grid power solutions where diesel displacement is economically critical.
Micro Gas Generator Market
Understanding the spatial distribution of demand is vital for logistics, supply chain planning, and local partnership development. Our report details the regional nuances that influence market penetration rates, including local regulatory frameworks and the availability of woody biomass feedstocks such as pellets and chips.
Application Verticals and Operational Efficiency
The utility of wood gas generators spans a diverse range of application verticals, each with unique economic drivers. The largest share of market activity is concentrated in Electric Power Generation, where the ability to convert woody biomass into electricity supports everything from micro-grids to larger industrial power needs. Industrial Thermal Energy represents another major pillar, utilizing the heat output from gasification processes for manufacturing and processing applications. Residential Heating markets also show significant activity, particularly in regions where households seek alternatives to traditional heating oils or electric heating systems.
Additionally, the Bio-Chemical Production sector is emerging as a niche but growing area, where syngas produced from wood gasification serves as a feedstock for chemical processes. The full study provides detailed insights into the revenue contributions and growth rates of each application segment, helping investors identify high-yield verticals.
Economic efficiency remains a primary motivator for adoption. Sector analysis indicates that on-site biomass gasification from wood waste can reduce electricity costs significantly compared to diesel generation. Reported examples in the industry highlight drops in energy costs from approximately 0.38 USD per kWh to as low as 0.07 USD per kWh, with project payback periods ranging from 3 to 6 years. These economic metrics are crucial for feasibility studies and investment committee approvals.
Competitive Dynamics and Key Players
The competitive landscape is characterized by a mix of established European manufacturers, innovative North American developers, and expanding players in Asia. The market concentration remains relatively fragmented yet competitive, with the top three companies holding a combined market share of approximately 18.45 percent and the top five holding 28.12 percent. This structure suggests room for consolidation but also indicates a healthy level of competition that drives innovation.
Key companies analyzed in depth within our report include Burkhardt GmbH, based in Mühlhausen, Germany, which manufactures wood gasifier V3.90 and V4.50 series CHP plants using wood pellets or chips for decentralized heat and power generation. Their focus on modular solutions and ongoing process optimization positions them strongly in the European market. Similarly, Spanner Re² GmbH, also headquartered in Germany, provides wood gasification systems and decentralized biomass CHP plants producing CO2-neutral energy from wood waste and biomass. Their installations worldwide include cascades for businesses and heating networks, reflecting a scalable approach to deployment.
In North America, ALL Power Labs, located in Berkeley, California, develops small-scale biomass gasification systems including Power Pallet and GEK Gasifier kits for converting woody biomass into electricity and heat, with a focus on modular, automated solutions. This focus on accessibility and automation appeals to a different segment of the market compared to large-scale industrial plants.
On the industrial scale, Powermax Renewable Energy (Wuxi Powermax), based in Wuxi, Jiangsu, China, offers biomass gasification power plants and wood gas generator systems with over 30 years of experience and over 100 global projects. They specialize in converting wood waste, chips, and residues into electricity, often offering industrial-scale solutions from 50 kW upwards. Other notable entities include Ankur Scientific Energy Technologies in India, known as a commercial producer of wood gasifier systems for stationary power generation applications, and GASEK in Finland, which manufactures commercially available wood gasifier systems primarily for electricity production.
The competitive landscape also includes Holzenergie Wegscheid GmbH and Volter in Finland, both providing specialized biomass gasification-based CHP solutions using wood. Vulcan Gasifier LLC in the USA and Community Power Corporation also remain active in biomass gasification and wood gas generator systems, contributing to the diverse ecosystem of providers.
Strategic Implications of Recent Developments
Market dynamics are heavily influenced by recent financial and regulatory developments. In March 2026, the USDA Rural Business-Cooperative Service approved a 25 million USD loan guarantee for a 3 MW biomass gasification plant converting forestry biomass waste into synthetic natural gas. This event underscores the role of public financing in de-risking large-scale projects and supporting rural renewable energy infrastructure. Such interventions signal to the private sector that government backing is available for projects that align with national forestry and energy goals.
Furthermore, regulatory environments in Europe and national incentives for decentralized biomass CHP continue to contribute to the deployment of wood gasifiers as part of CO2-neutral energy strategies. These incentives reduce the capital expenditure burden and improve the internal rate of return for projects. Companies like Powermax Renewable Energy continue to promote and availability of wood waste gasification power plants and biomass gas generator sets, ensuring that industrial-scale offerings remain accessible to a broad range of clients.
Fuel consistency remains a technical challenge that industry leaders are addressing. Wood pellets and wood chips serve as primary fuels for commercial wood gasifiers in CHP plants, with systems optimized for consistent feedstock quality to maintain gasification efficiency. Operators must consider supply chain stability for these raw materials when planning long-term projects.
Report Scope and Decision Support
Our Worldwide Wood Gas Generator Market research is designed to function as a comprehensive decision-support tool. The full report extends beyond the high-level trends summarized here to provide detailed historical data tables, precise segmentation splits across region, type, and application, and exclusive competitor profiling. We examine the market concentration metrics, supply chain vulnerabilities, and the specific impact of regulatory changes on profitability across different jurisdictions.
For corporate strategy teams, the report offers a benchmark against which internal projections can be validated. For investors, it provides the due diligence necessary to assess the risk-reward profile of entry into this sector. The inclusion of recent developments, such as specific loan guarantees and product updates from key players, ensures that the data remains current and actionable.
The analysis covers the historical period from 2020 to 2025 and provides forecasts through 2032, allowing for long-term strategic planning. By integrating data on market size, growth rates, and competitive positioning, the study enables stakeholders to identify whitespace opportunities and potential threats. Whether evaluating a partnership with a manufacturer like Burkhardt or Spanner Re², or assessing the viability of a local project supported by USDA financing, the intelligence contained herein is structured to reduce uncertainty.
Conclusion: The Path Forward
The wood gas generator market is poised for continued expansion, driven by the dual imperatives of decarbonization and energy security. The growth from roughly 512 million USD in 2020 to a projected 1085 million USD by 2032 reflects a sector that is maturing and integrating deeply into the global energy mix. However, success in this environment requires more than general awareness; it demands precise data on segmentation, competitor capabilities, and regulatory tailwinds.
Stakeholders who leverage detailed market intelligence will be better positioned to capture value in this evolving landscape. We invite you to access the full Worldwide Wood Gas Generator Market research report to unlock the complete dataset and strategic recommendations necessary to navigate the opportunities of 2026 and beyond. The detailed breakdowns of regional performance, specific technology adoption rates, and granular competitor analysis are available exclusively through the full study, providing the depth required for high-stakes decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Wood Gas Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polycarbonate Glazing Market Hits $1,832M in 2025, Projected 5.19% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Horizons: Navigating the Worldwide Polycarbonate Glazing Market Through 2032
The global market for polycarbonate glazing stands at a pivotal inflection point. As industries from automotive to construction demand materials that balance transparency, impact resistance, and sustainability, polycarbonate has cemented its role as a foundational material for modern light transmission and protective applications. Our latest Worldwide Polycarbonate Glazing Market research delivers a comprehensive, data-grounded roadmap for executives, investors, and supply chain strategists who must navigate this evolving landscape with precision.
Set against a five-year historical baseline spanning 2020 to 2025 and a forward-looking forecast window from 2026 through 2032, this study is engineered to inform capital allocation, product roadmap decisions, and competitive positioning in the year ahead and beyond.
The Market Trajectory: Growth, Consolidation, and Strategic Timing
The polycarbonate glazing market has demonstrated resilient expansion over the past half-decade, recovering from mid-cycle adjustments to reach a base-year valuation of 1,832.03 million USD in 2025. Looking forward, the trajectory points to sustained momentum with a compound annual growth rate of 5.19 percent across the forecast horizon. By 2032, the market is projected to approach 2,612.42 million USD, reflecting steady demand pull from high-volume structural and specialized transparency applications.
This growth is not uniform across time or geography. Early forecast years show measured expansion, with the market moving from 1,946.39 million USD in 2026 to 2,066.15 million USD in 2027, before a sharper acceleration toward the decade's end as capacity comes online and end-use adoption broadens. Understanding these inflection points is critical for timing capacity investments, inventory planning, and regional expansion strategies.
Polycarbonate Sheet Market
Concentration patterns further illuminate the competitive reality. The top three players account for 38.4 percent of market revenue, while the top five capture 52.15 percent. This concentrated structure means that scale advantages, feedstock partnerships, and technological differentiation carry outsized weight. For challengers and new entrants, the path to meaningful share lies in targeted application niches, regional specialization, or sustainability credentials that resonate with procurement mandates.
Segment-Level Dynamics: Type, Application, and the Shape of Demand
Polycarbonate glazing demand is shaped by a clear hierarchy of product types and end-use sectors, each with distinct performance requirements and cost sensitivities. Solid polycarbonate leads the type segmentation, reflecting its broad applicability in architectural facades, security glazing, and transportation transparencies where baseline clarity and impact resistance are paramount. Multiwall polycarbonate follows, driven by its insulating properties and growing use in construction and agricultural enclosures. Corrugated polycarbonate rounds out the type mix, serving cost-sensitive and high-durability applications where structural profile matters as much as optical performance.
On the application side, automotive remains the dominant demand engine, fueled by lightweighting imperatives, electrification-related redesigns, and the need for high-clarity, UV-stabilized glazing in passenger and commercial vehicles. Construction ranks closely, supported by building energy codes, retrofits, and the substitution of heavier or less durable materials in roofing, skylights, and transparent wall systems. Security and protection applications represent a specialized but high-value segment, while agriculture and other end-use categories provide additional growth nodes where durability and cost efficiency intersect.
Importantly, the interplay between type and application is not static. Buyers increasingly evaluate multiwall versus solid formats through the lens of thermal performance, fabrication complexity, and total installed cost. Procurement teams in construction and transportation are also weighing recycled-content and mass-balance resins as part of broader ESG procurement policies. These cross-cutting considerations make segment-level analysis essential for product managers and sales strategists who must align material grades with purchasing criteria.
Regional Realities: Where Growth Is Concentrated and Why
Regional demand patterns reveal a market where Asia Pacific anchors volume, Europe drives specification-led and regulation-conscious adoption, and North America combines large-scale construction and industrial demand with a mature distribution ecosystem. Latin America and the Middle East and Africa contribute meaningful but smaller shares, often expanding through infrastructure projects, agricultural modernization, and import-dependent supply chains.
These regional profiles are not merely size differences; they reflect divergent procurement behaviors, regulatory environments, and logistics realities. In Europe, compliance with evolving substance restrictions and energy-performance expectations shapes grade selection and supplier qualification. In Asia Pacific, rapid industrial capacity additions and localized fabrication networks influence price dynamics and lead-time expectations. In North America, large project pipelines and a preference for domestically sourced or regionally distributed materials affect fulfillment strategies. Understanding these regional fingerprints allows companies to prioritize go-to-market investments, distribution partnerships, and compliance readiness where they will yield the greatest return.
Competitive Landscape: Incumbents, Specialists, and the Ecosystem of Scale
The competitive field blends global resin and sheet producers with regional formulators and specialized glazing manufacturers. Covestro AG continues to anchor its position through Makrolon-branded polycarbonate resins and sheets tailored for architectural glazing, automotive glazing, and high-impact transparent applications, with an emphasis on UV stabilization and impact resistance. Its January 2025 announcement of a major capacity expansion at its Hebron, Ohio facility signals a deliberate push to serve custom grades across automotive, electronics, and specialty film and glazing demand.
SABIC complements this landscape with LEXAN polycarbonate sheets and resins spanning solid, multiwall, and architectural systems, with a clear focus on durability, clarity, and energy efficiency. The recent integration activity involving POLYVANTIS, including the launch of a new LEXAN sheet series with enhanced lightweight properties and mechanical performance for rail and glazing applications, illustrates how product innovation is being directed at demanding mobility and transparency use cases.
Alongside these global players, a robust set of specialists and regional manufacturers competes on application focus, fabrication capability, and regional service. Palram Industries Ltd. specializes in polycarbonate glazing products including flat solid sheets, multiwall sheets, and corrugated panels for construction, agricultural, and transportation uses. Trinseo supplies polycarbonate resins and sheets with a growing emphasis on sustainable and recycled-content solutions for building and industrial applications. Teijin Limited manufactures high-performance polycarbonate materials, including optical and impact-resistant grades for architectural and specialty applications, while Mitsubishi Gas Chemical Company, Inc. has advanced its sustainability positioning through ISCC PLUS certification for polycarbonate resin at its Kashima plant, using a mass-balance approach for sustainable raw materials applicable to glazing sheet production.
The North American and European markets also feature strong regional contributors. Plaskolite, Inc. offers polycarbonate sheets with emphasis on impact resistance and fabrication for North American construction and industrial markets. EXOLON GROUP, derived from former Covestro European sheet operations, supplies high-quality polycarbonate and thermoplastic sheets targeting construction and industrial sectors. 3A Composites GmbH provides polycarbonate sheets under established brand names for transportation, construction, and renewable energy glazing applications, while Arlaplast focuses on European glazing markets with sustainable processing capabilities. In Asia, LG Chem produces polycarbonate resins suitable for conversion into high-performance glazing sheets for automotive and architectural uses, and LOTTE Chemical CORPORATION supplies polycarbonate materials for sheet extrusion and glazing applications addressing global construction and electronics-related transparency needs.
Finally, Deepak Advanced Materials Limited's March 2025 opening of a new manufacturing facility in Gujarat, India, focused on polycarbonate and engineering polymer compounds for construction and industrial applications including glazing, underscores the expanding manufacturing footprint in the region and the intensifying competition for regional share.
Industry Dynamics: Feedstock Volatility, Regulation, and Trade Realities
Strategic decision-making in this market cannot be separated from the operational and regulatory forces shaping supply and demand. The primary feedstock for polycarbonate, Bisphenol A, experienced mixed price trajectories in Asia Pacific during the second quarter of 2025, with April increases linked to plant maintenance and restocking. These fluctuations ripple through resin pricing, margin planning, and procurement timing, making feedstock visibility a core input for commercial strategy.
Regulatory developments add another layer of complexity. EU regulation banning Bisphenol A and its salts in food contact materials entered into force on 20 January 2025, impacting certain polycarbonate applications while maintaining specific migration limits for non-infant uses. Complementary EU regulations impose stricter Bisphenol A migration limits in food contact plastics effective in 2025, requiring compliance statements for polycarbonate materials. While these restrictions primarily target food-contact applications such as infant feeding bottles and certain containers, they are also driving development of alternative or low-migration grades for broader uses, including non-food glazing, and reshaping supplier qualification processes.
Trade policy introduces further uncertainty. U.S. reciprocal tariffs in 2025, including potential impacts on imports from South Korea, the European Union, and Thailand, affect polycarbonate supply chains with baseline duties applied amid ongoing negotiations. For manufacturers and distributors, these dynamics influence landed-cost calculations, sourcing diversification, and inventory positioning. Companies that map tariff exposure and evaluate alternate supply paths will be better positioned to protect margins and maintain service levels.
Inside the Study: What Decision-Makers Will Find
This market research is built for execution, not just observation. It translates macro trends into an actionable framework covering market sizing and forecast logic, segmentation analysis by type and application, regional demand profiles, and competitive intelligence on the companies shaping pricing, innovation, and capacity. The study details recent developments that matter for near-term planning, including capacity expansions, new facility openings, product launches, and sustainability certifications that signal where supply and differentiation are heading.
Worldwide Polycarbonate Glazing Market
Beyond the numbers, the report connects market structure to commercial implications. It examines how concentration influences pricing power and partnership strategy, how regulatory and feedstock dynamics affect cost structures and qualifying criteria, and how regional demand fingerprints should inform sales coverage and distribution design. The analysis also addresses the practical questions procurement and product teams face: which material grades align with performance and compliance requirements, where multiwall and solid formats create value tradeoffs, and how sustainability credentials are increasingly integrated into purchasing decisions.
The report's structure allows users to move from high-level strategic context to targeted insights without losing rigor. Whether the objective is to evaluate entry opportunities, refine capacity planning, benchmark competitor moves, or build a sourcing and compliance roadmap, the study provides a consistent evidence base and clear analytical pathways.
Why This Research Matters for 2026 Decisions
In a market projected to grow steadily yet unevenly, with concentrated incumbents, evolving regulation, and feedstock and trade volatility, decisions made in 2026 will shape competitive standing through the end of the decade. Companies that align product portfolios with application-led demand, anticipate regional procurement behavior, and prepare for regulatory and cost fluctuations will capture disproportionate value. Those that treat polycarbonate glazing as a commodity category risk missing the specificity that now drives specification, qualification, and repeat purchasing.
This Worldwide Polycarbonate Glazing Market research is designed to reduce ambiguity and accelerate better decisions. It provides the market context, segment logic, competitive mapping, and dynamic intelligence needed to prioritize investments, sharpen go-to-market execution, and build resilience into supply and sourcing strategies.
To access the full dataset, detailed segmentation breakdowns, complete company profiles, regional demand estimates, and the full set of recent developments informing this analysis, visit the source page for the complete report. The comprehensive intelligence is available to support strategic planning, investment review, and operational decision-making across the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Polycarbonate Glazing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Mobile Music Rhythm Games Revenue Hits $1.65B in 2025, Nearing $2.68B by 2032
By pmarketresearch, 2026-09-16
Global Mobile Music Rhythm Games Market 2026: Strategic Outlook and Competitive Landscape
The mobile gaming sector continues to evolve at a rapid pace, with music rhythm games emerging as a resilient and highly engaged niche within the broader ecosystem. As players increasingly seek immersive, interactive experiences that blend audio and visual stimuli, the demand for sophisticated rhythm-based mechanics on smartphones has solidified. This article introduces the Worldwide Mobile Music Rhythm Games Market research, a comprehensive study designed to equip stakeholders with the actionable intelligence needed for strategic decision-making in 2026 and beyond. By analyzing revenue trajectories, competitive positioning, and technological shifts, this report serves as a critical tool for publishers, investors, and developers navigating a complex market environment.
Understanding the nuances of this segment requires more than surface-level metrics. It demands a granular look at how monetization strategies interact with player behavior across different platforms and regions. The following analysis outlines the macro-economic backdrop, details the specific contents of the market study, and examines the key players shaping the industry. The goal is to highlight the strategic value of deep-dive research in an era where data-driven choices determine market leadership.
Market Dynamics and Revenue Trajectory
The economic foundation of the mobile music rhythm games market has shown consistent expansion, driven by a combination of growing smartphone penetration, improved audio processing capabilities, and a vibrant culture of community engagement. Historical data indicates a steady compounding of revenue, with the market valued at approximately USD 1,210.45 Million in 2020. This figure grew to USD 1,272.37 Million in 2021, followed by a significant jump to USD 1,450.7 Million in 2022.
While 2023 saw a slight adjustment to USD 1,440.83 Million, the market regained momentum, reaching USD 1,601.62 Million in 2024 and stabilizing at an estimated USD 1,650.0 Million in 2025. This trajectory sets the stage for the forecast period spanning 2026 to 2032. Current projections suggest that the market will reach USD 1,711.88 Million in 2026, continuing its upward climb to USD 1,837.18 Million in 2027 and USD 2,017.22 Million in 2028. By the end of the forecast horizon in 2032, the market is anticipated to approach USD 2,684.41 Million.
This growth pattern reflects a Compound Annual Growth Rate (CAGR) of 7.2 Percent over the forecast period, signaling a healthy expansion rate that outpaces many broader gaming segments. For stakeholders, this CAGR offers a reliable benchmark for internal budgeting and external investment pitches. The consistency of revenue growth, despite macroeconomic fluctuations, underscores the sticky nature of rhythm game communities. Players frequently return to these titles for daily challenges, event participation, and social competition, ensuring predictable cash flow for operators who maintain high engagement standards.
Furthermore, the revenue streams within this market are diversified, though heavily weighted toward specific models. The data indicates a dominant preference for Freemium and In-App Purchases, which constitute the largest share of the revenue pie. Premium and Paid Downloads represent a smaller but stable fraction, while Ad-Supported Services contribute a supplementary layer. This hierarchy suggests that while upfront payment models retain a loyal user base, the long-term scalability of the market relies on continuous content updates, battle passes, and character gacha mechanisms typical of the freemium ecosystem.
Worldwide Mobile Music Rhythm Games Market
Platform distribution also reveals critical strategic insights. iOS and Android remain the primary conduits for revenue generation. The split between these platforms often informs technical development priorities and monetization tuning, as user demographics and spending behaviors can vary significantly between the two ecosystems. Understanding the relative weight of each platform is essential for allocating marketing spend and optimizing user acquisition costs.
Geographically, the market is not uniformly distributed. Certain regions demonstrate higher density of players and spending power, influencing where publishers prioritize localization efforts and server infrastructure. While detailed regional percentages are reserved for the full report, the macro data confirms that a few key territories drive the majority of global volume, making regional strategy a non-negotiable component of success.
Industry Dynamics and Recent Developments
The operational landscape for mobile rhythm games is shaped by a mix of technical standards, regulatory frameworks, and cultural trends. Mobile games, including rhythm titles, operate under app store policies from Apple and Google governing in-app purchases, age ratings, and data privacy compliance such as GDPR and CCPA equivalents in major markets. Compliance with these regulations is not merely a legal requirement but a trust signal that impacts user retention and brand reputation. Publishers must navigate age classification systems carefully, especially when featuring music content that may vary by region, and ensure that data collection practices remain transparent to avoid regulatory penalties.
Recent product launches and platform expansions highlight the innovation occurring within the sector. In January 2026, Cover Corporation unveiled hololive Dreams, a new mobile rhythm game featuring falling notes gameplay. Planned for global release in 2026, the title leverages the popularity of hololive talent songs and covers, illustrating the trend of integrating established IP and virtual talent into rhythm mechanics to drive immediate user interest. This move signals a broader industry shift toward leveraging community-driven fandoms to accelerate market entry.
Earlier in October 2025, Crunchyroll announced the launch of Spin Rhythm XD Mobile, set to launch exclusively on the Crunchyroll Game Vault in Q4 2025. This platform-specific launch demonstrates the strategic value of integrating rhythm games into larger entertainment ecosystems. By bundling rhythm experiences with anime and media content platforms, publishers can access cross-demographic audiences and enhance user lifetime value through ecosystem lock-in. These developments suggest that the boundary between standalone games and broader media platforms is blurring, creating new opportunities for partnership and content synergy.
The industry context also points to a maturation of gameplay mechanics. Developers are increasingly experimenting with laneless formats, falling note challenges, and dimension-blending styles to differentiate their titles in a crowded market. Innovation in user interface and audio synchronization remains a key differentiator, as players demand precision and responsiveness that rivals dedicated console experiences. As hardware capabilities on mobile devices improve, the ceiling for visual fidelity and audio complexity continues to rise, allowing developers to create more immersive experiences without sacrificing portability.
Report Scope and Operational Content
The Worldwide Mobile Music Rhythm Games Market research is structured to provide a 360-degree view of the industry, enabling stakeholders to move from high-level trends to granular execution plans. The report covers the historical period from 2020 to 2025 and extends the forecast through 2032, offering a long-term perspective essential for strategic planning. The analysis is anchored in primary and secondary research methodologies, ensuring that the data reflects actual market conditions rather than theoretical models.
Racing Games Market
Key components of the report include a detailed market size analysis that breaks down revenue by major classification axes while maintaining the confidentiality of sensitive granular data. Readers will find a comprehensive segmentation analysis that dissects the market by region, business model, and platform. While the full report provides the exact split and dollar values for each segment, the executive overview highlights the relative dominance of key regions and the preference for freemium monetization, guiding readers to dive deeper for the precise numbers required for financial modeling.
Beyond size and segmentation, the report delivers an extensive competitive landscape analysis. This section profiles the core companies driving the market, examining their headquarters, business focus, and strategic positioning. The analysis covers a diverse set of players, ranging from major global publishers and tech conglomerates to specialized developers known for specific titles. Companies such as Tencent, with significant presence in the music rhythm genre via distribution and development support, and T3 Entertainment, focused on music and rhythm games for mobile platforms, are examined for their impact on market dynamics.
The report also details the activities of regional specialists and niche innovators. This includes Rayark Inc., developer of the major Cytus and Cytus II series; Colorful Palette, creator of the leading Project SEKAI COLORFUL STAGE! feat. Hatsune Miku; and Lowiro Limited, developer of the prominent new dimension rhythm game Arcaea. Developers like PigeonGames, known for the laneless mobile rhythm game Phigros, and DRIMAGE Co., Ltd., developer of the official HYBE rhythm game Rhythm Hive featuring BTS and other artists, are analyzed for their unique value propositions. Additionally, the landscape includes contributions from entities such as C4Cat, Baidu, 7th Beat Games, Maniacs s.r.o., Tiger Tang, Digixart, and Konami, the latter bringing rhythm game heritage including mobile adaptations.
Competitive metrics such as market concentration are included to assess the level of competition. Data on CR3 and CR5 percentages provides insight into the consolidation of the market, helping stakeholders understand the balance between dominant incumbents and emerging challengers. A highly concentrated market may suggest barriers to entry and the importance of partnership strategies, while a fragmented landscape could indicate opportunities for differentiation and niche capture.
The report further incorporates a section on industry dynamics, addressing the regulatory and operational factors that influence market behavior. This includes a discussion of app store policies, age rating compliance, and data privacy requirements across major markets. Understanding these constraints is vital for risk management and for designing monetization structures that comply with platform rules while maximizing revenue.
Recent developments are tracked to capture the pulse of the market. By analyzing product announcements, platform launches, and partnership news, the report helps readers stay ahead of trends that could disrupt the status quo. For example, the analysis of how virtual talent IPs are being integrated into rhythm games or how media platforms are hosting exclusive rhythm titles provides early signals for where investment and development focus should shift.
Strategic Implications for Decision-Makers
For business leaders and investors, the value of this research lies in its ability to translate data into strategy. The projected growth to USD 2,684.41 Million by 2032 suggests a market with substantial room for expansion, but capturing that growth requires precise execution. The dominance of the freemium model implies that success depends on robust content pipelines, balanced monetization, and community management. Publishers must invest in regular updates, event cycles, and social features that keep players engaged over the long term.
The platform dynamics further inform resource allocation. With iOS and Android sharing the revenue base, developers need to tailor their technical and marketing strategies to the nuances of each ecosystem. This might involve optimizing store presence, adjusting pricing tiers, or leveraging platform-specific advertising tools. Regional insights, though high-level in the preview, point to the necessity of localization. Expanding into high-value territories requires not just translation but cultural adaptation of music selections, events, and marketing messaging.
Competitive analysis offers a roadmap for positioning. By studying the profiles of key companies like Tencent, Konami, and Rayark, as well as specialized developers like PigeonGames and Colorful Palette, stakeholders can identify best practices in game design, IP utilization, and user acquisition. The presence of large tech companies like Baidu alongside dedicated rhythm game studios illustrates the variety of approaches to market entry and growth. New entrants can learn from the strengths of established players while looking for gaps in the market that allow for differentiation, such as innovative gameplay mechanics or unique IP partnerships.
The report's coverage of market concentration metrics helps in assessing the competitive intensity. A market with significant concentration may favor incumbents with established brands and large user bases, making it crucial for new players to secure strong differentiators or strategic partnerships. Conversely, areas of lower concentration may present opportunities for agile developers to gain traction with superior products or targeted marketing. Understanding the CR3 and CR5 dynamics allows for a realistic assessment of the barriers to scale and the potential for market disruption.
Finally, the inclusion of recent developments such as the hololive Dreams announcement and the Crunchyroll Game Vault launch underscores the importance of agility. The ability to capitalize on trends like IP integration and ecosystem partnerships can accelerate growth and reduce customer acquisition costs. Stakeholders who monitor these signals and adapt their strategies accordingly will be better positioned to capture emerging opportunities.
Conclusion and Call to Action
The Worldwide Mobile Music Rhythm Games Market is poised for sustained growth, supported by a dedicated player base, evolving monetization models, and continuous innovation in gameplay and content. The trajectory from USD 1,650.0 Million in 2025 to a projected USD 2,684.41 Million by 2032 reflects a market that is both resilient and expanding. However, realizing the full potential of this growth requires more than general awareness. It demands precise data, competitive intelligence, and a deep understanding of regional and platform-specific dynamics.
This article has provided a strategic overview of the market landscape, highlighting key revenue trends, recent industry developments, and the scope of analysis available. It has touched upon the dominance of freemium models, the distribution across platforms, the concentration of market share, and the diverse array of companies vying for leadership. Yet, the macro view only scratches the surface. The exact segmentation splits, detailed regional revenue figures, precise platform shares, and comprehensive competitive profiles contain the granular insights necessary for accurate forecasting and targeted strategy formulation.
To access the full spectrum of intelligence, including the confidential data cuts, detailed company profiles, and actionable recommendations, stakeholders are encouraged to consult the complete Worldwide Mobile Music Rhythm Games Market report. The full study offers the depth required to make informed decisions, mitigate risks, and capitalize on the opportunities within this dynamic sector. Explore the comprehensive research to transform market knowledge into competitive advantage.
Access the full report at: https://www.globemarketresearch.com/report/mobile-music-rhythm-games-market
Contact Information:
Email: info@globemarketresearch.com
Website: https://www.globemarketresearch.com
For detailed analysis of this topic, please visit the official page: Worldwide Mobile Music Rhythm Games Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Telecom Security Software to Hit $15.5B in 2025, Grow at 13% CAGR Through 2032
By pmarketresearch, 2026-09-16
Global Telecom Security Software Market: Strategic Intelligence for 2026 Decision-Making
The telecommunications industry is currently navigating a transformative period defined by rapid technological shifts and escalating security challenges. As networks evolve toward 5G standalone architectures and beyond, the surface area for potential cyber threats expands proportionally. In this environment, security software is no longer a peripheral utility but a core component of network infrastructure and business strategy. PW Consulting's latest Worldwide Security Software in Telecom Market research provides a comprehensive lens through which enterprises and investors can understand these dynamics. This report is designed to equip decision-makers with the actionable intelligence required to navigate the forecast period from 2026 through 2032.
The market trajectory observed over the past five years indicates a robust growth pattern, driven by the urgent need to secure digital infrastructure against sophisticated attacks. Historical data from 2020 to 2025 shows a consistent upward trend in market valuation, reflecting the increasing prioritization of cybersecurity within telecom operations. Looking forward, the market is projected to continue this momentum, with a compound annual growth rate of approximately 13 percent across the forecast horizon. This growth is not merely a function of inflation or expanded connectivity but represents a fundamental structural shift in how security is integrated into network design, deployment, and management.
Market Scale and Growth Trajectory
Understanding the magnitude of this opportunity is essential for capital allocation and strategic planning. The global revenue for security software in telecom has seen significant expansion, moving from a baseline in the mid-eight thousands millions USD in 2020 to surpassing the fifteen thousands millions USD mark by 2025. This historical performance sets the stage for a forecast period where valuations are expected to climb substantially, reaching over thirty-six thousands millions USD by 2032. Such figures underscore the critical nature of security investments as telecom operators transition into techco models, offering cybersecurity offerings alongside traditional connectivity, cloud, and IoT services.
This growth trajectory is supported by several converging factors. The proliferation of edge computing and network slicing creates new vulnerabilities that require specialized software interventions. Furthermore, the regulatory landscape is tightening globally, with governments implementing cybersecurity regulations, trusted vendor policies, and data localization requirements. These compliance drivers compel operators to invest heavily in compliant security software solutions, thereby fueling market expansion. The report details how these macroeconomic and regulatory forces interact to shape demand curves over the next seven years.
Segmentation and Deployment Dynamics
While the overall market size provides a high-level view, the underlying segmentation reveals where the greatest opportunities and risks lie. The market is divided across various dimensions, including deployment mode and solution type. The shift toward cloud-based security solutions is prominent, reflecting the industry's broader migration to virtualized network functions and cloud-native architectures. This deployment mode accommodates the flexibility required for modern telecom environments, though on-premise solutions remain significant for specific high-security or latency-sensitive use cases.
Solution types vary from network security and endpoint protection to identity and access management and cloud security solutions. Each category addresses distinct threat vectors within the telecom ecosystem. For instance, network security remains a dominant focus area given the criticality of protecting the core infrastructure from intrusion. However, as service providers expand their B2B portfolios, identity management and cloud security are gaining traction. The report provides deep dives into each segment, analyzing adoption rates, technological maturity, and regional preference patterns without exposing sensitive proprietary estimates in this summary.
Geography also plays a crucial role in market dynamics. Different regions exhibit varying levels of maturity, regulatory pressure, and investment capacity. North America, Europe, and Asia Pacific represent significant portions of the market, each driven by unique local factors such as digital sovereignty initiatives or infrastructure modernization plans. Latin America and the Middle East and Africa are also contributing to the growth, albeit at different scales. The full research document breaks down these regional nuances, offering specific insights into local market conditions, key regulatory frameworks like the EU Digital Networks Act, and the impact of legal shifts such as recent court rulings on net neutrality that may influence service provider strategies.
Competitive Landscape and Key Players
The competitive environment in telecom security software is characterized by a mix of specialized security vendors and large telecommunications infrastructure providers. Market concentration indicates that a handful of major players command a significant share of the revenue, yet there is ample room for niche innovators and regional specialists. The top five companies collectively hold a substantial portion of the market, reflecting the importance of scale, brand reputation, and integrated solution portfolios in this sector.
Key companies such as Cisco Systems, Palo Alto Networks, and Fortinet are central to the landscape, offering comprehensive solutions ranging from secure firewalls to AI-driven security platforms tailored for 5G and enterprise networks. These vendors are continuously innovating, with recent developments highlighting a focus on sovereign AI security frameworks and fabric-based AI agents. For example, recent product releases in early 2026 have introduced new innovations for AI and modern networks, emphasizing secure AI controls and simplified SD-WAN for telecom environments. Such movements signal a trend where security vendors are embedding intelligence directly into the network fabric to handle evolving threats autonomously.
Telecom infrastructure giants like Ericsson and Nokia also play a pivotal role, providing 5G core security solutions and cloud packet core security integrated directly into the hardware and software stacks operators rely on. Their approach often focuses on built-in security features for RAN, core, and transport networks, ensuring security is baked into the infrastructure from the outset. Meanwhile, companies like Huawei Technologies and Juniper Networks contribute extensive portfolios covering everything from cloud fabric security to AI-driven routing solutions optimized for service providers.
The landscape also includes specialized players focusing on specific telecom security niches. Check Point Software Technologies offers advanced threat prevention suitable for network perimeters, while Allot specializes in traffic management and DDoS protection for mobile networks. P1 Security stands out with a focus exclusively on telecom security software for 5G, 4G, and OpenRAN attack simulation. Additionally, firms like F5 Networks and Trend Micro provide application security and hybrid cloud security solutions applicable to telecom environments. The report profiles these companies in detail, analyzing their recent partnership expansions, product launches, and strategic positioning. For instance, recent announcements at major industry events have highlighted expanded security ecosystems aimed at protecting AI factories in telecom networks, indicating a strategic pivot toward securing the artificial intelligence infrastructure that powers modern networks.
Telecommunications Market
Industry Dynamics and Regulatory Context
Macro-level dynamics are reshaping the market just as much as technological innovation. The shift toward techco models means telecom operators are increasingly competing with traditional IT security firms, blurring the lines between connectivity and security services. This convergence creates both opportunities for revenue diversification and challenges in maintaining operational focus. Furthermore, the threat landscape remains volatile. Threat intelligence reports from late 2025 warned that telecom threats observed involving new technologies are expected to persist into 2026, necessitating proactive rather than reactive security postures.
Regulatory pressure is a critical driver in this environment. In Europe, advancements in the Digital Networks Act aim to stimulate investment in next-generation networks while addressing digital sovereignty and cybersecurity requirements. Simultaneously, the EU has set targets for the transition to quantum-safe cryptography in telecommunications, pushing vendors and operators to future-proof their encryption standards. Globally, governments are implementing trusted vendor policies and data localization requirements that affect how security software is deployed and sourced. In the United States, legal challenges regarding net neutrality rules have added layers of complexity to network management strategies, indirectly influencing security architecture decisions.
These regulatory and dynamic shifts create a complex operating environment. Companies must navigate compliance hurdles while ensuring their security solutions remain effective against evolving threats. The research report analyzes how these factors influence market growth, vendor selection criteria, and deployment strategies across different regions. It provides a framework for understanding how regulatory compliance can be turned into a competitive advantage rather than viewed solely as a cost center.
Worldwide Security Software in Telecom Market
Strategic Value for 2026 Decision-Makers
For enterprises operating in or investing in the telecom sector, access to granular, forward-looking data is vital. This research offers more than just high-level numbers; it delivers an operational blueprint for the forecast period. Decision-makers can utilize the insights to refine their product development roadmaps, identify partnership opportunities, and assess market entry risks. The detailed segmentation analysis helps in pinpointing high-growth niches, while the competitive profiling allows organizations to benchmark their strategies against leading players.
The inclusion of recent developments, such as partnership expansions and product releases from key vendors, ensures that the intelligence is current and actionable. Understanding the timing and nature of these moves can provide early signals of market shifts. For example, the focus on sovereign AI security frameworks suggests a growing demand for localized, trusted security solutions that protect AI workloads within telecom networks. Recognizing such trends early allows strategies to align with emerging demands before the market becomes saturated.
Furthermore, the report addresses the consolidation trends reflected in market concentration metrics. Knowing the share held by the top three or five players helps investors and competitors understand the barriers to entry and the potential for disruption by smaller, agile firms. The balance between established incumbents and specialized innovators is a key theme explored in the analysis, offering guidance on where collaboration or acquisition might yield the highest returns.
Ultimately, the Worldwide Security Software in Telecom Market research is designed to reduce uncertainty. In a sector defined by rapid change, regulatory flux, and sophisticated threat actors, having a reliable source of comprehensive data is a strategic asset. The report enables stakeholders to move beyond intuition and make evidence-based decisions that align with long-term growth objectives.
Accessing Complete Intelligence
This overview serves as a preview of the depth and breadth contained within the full PW Consulting report. While the macro trends and competitive dynamics outlined here provide a solid foundation for understanding the market, the detailed data required for precise planning is available in the complete document. The full report includes granular segmentation splits, specific regional revenue estimates, detailed company profiles with financial and strategic metrics, and extensive analysis of the regulatory landscape across all covered regions.
Readers are encouraged to access the source webpage to download the complete study. There, you will find the specific data points necessary to validate assumptions, build financial models, and craft targeted go-to-market strategies. In an industry where timing and accuracy are paramount, the complete intelligence offered by this research provides the clarity needed to navigate the complex telecom security landscape from 2026 through 2032. The insights contained within are updated to reflect the latest developments and market conditions, ensuring that your strategic decisions are based on the most current information available.
For detailed analysis of this topic, please visit the official page: Worldwide Security Software in Telecom Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Urethritis Drugs Market Hits $2.15B in 2025, Projected 4.85% CAGR Through 2032
By pmarketresearch, 2026-09-16
Global Urethritis Drugs Market Outlook 2026: Strategic Imperatives in a Shifting Therapeutic Landscape
Executive Overview
The worldwide urethritis drugs market stands at a critical inflection point as it moves through the 2026-2032 forecast period. Driven by evolving treatment guidelines, persistent antimicrobial resistance patterns, and a maturing generic ecosystem, the sector is projected to expand from an estimated 2.15 billion USD in 2025 to approximately 2.99 billion USD by 2032, reflecting a compound annual growth rate of 4.85 percent over the forecast horizon. This trajectory is neither linear nor guaranteed. It is shaped by regulatory recalibrations, formulary decisions, supply chain dynamics, and the strategic positioning of incumbent innovators alongside generic manufacturers. For executives navigating product portfolios, commercial planning, and market entry, the 2026 landscape demands a disciplined reading of where volume is migrating, which therapeutic categories are gaining policy tailwinds, and how distribution channels are being reconfigured by reimbursement realities.
This article previews our comprehensive Worldwide Urethritis Drugs Market research, a decision-grade intelligence asset designed to translate macro momentum into actionable commercial strategy. The full study delivers granular segmentation, competitive profiling, pricing and volume trajectories, channel-level dynamics, and scenario frameworks. What follows is a strategic orientation: the structural forces at work, the competitive contours, the regulatory currents, and the analytical architecture that decision-makers will need in 2026 and beyond.
Market Architecture and Growth Logic
Across the historical window of 2020 through 2025, the market consolidated around a core set of widely prescribed antibiotics and standardized treatment protocols, reaching a baseline that positioned the sector for measured expansion. The forecast period from 2026 through 2032 anticipates a broad-based uplift, underpinned by steady demand for first-line agents, incremental uptake of newer options where clinically indicated, and the continued role of public health programs that embed key therapies into STI management pathways.
Growth is not uniform across therapeutic categories. The market bifurcates between gonococcal and non-gonococcal indications, each governed by distinct clinical protocols, resistance considerations, and reimbursement exposure. At the same time, distribution channels reflect a pragmatic mix of institutional procurement, community dispensing, and digital fulfillment pathways, with each channel responding differently to formularies, prescription behaviors, and patient access programs. The interplay among these dimensions determines where commercial opportunity concentrates and where margin pressure intensifies.
Beyond the headline trajectory, the research decomposes the market into operationally meaningful layers:
- Therapeutic segmentation that distinguishes treatment pathways by pathogen type and guideline positioning
- Channel-level analysis capturing how hospital, retail, and online pathways differ in volume mix, reimbursement exposure, and growth elasticity
- Geographic framing that isolates high-volume markets and emerging demand centers without overstating localized statistics
- Competitive benchmarking mapped to product positioning, portfolio breadth, and pipeline relevance
This architecture enables teams to move from aggregate growth narratives to channel-level and category-level decision-making, aligning sales coverage, supply planning, pricing strategy, and partnership logic with where value is actually created.
Competitive Landscape: Innovators, Generics, and Positioning Realities
The competitive field blends global innovators with high-volume generic manufacturers, each exercising distinct commercial leverage. A small set of leading firms commands a meaningful share of total market value, while a broader cohort competes on cost, supply reliability, and regional access. Concentration metrics indicate that the top three players account for roughly 28.5 percent of market value, and the top five reach approximately 39.2 percent, signaling a landscape that is neither fully consolidated nor fragmented beyond strategic coherence. For commercial leaders, this structure has direct implications for pricing power, tender dynamics, and partnerships.
Bacterial Vaginosis Drug Market
Pfizer Inc. maintains a recognized presence through azithromycin-based offerings indicated for urethritis and cervicitis, alongside ceftriaxone products relevant to dual-therapy protocols for gonococcal infections. Its positioning is anchored in established brand recognition, clinical heritage, and broad distribution reach, making it a reference point in both institutional and community settings.
GlaxoSmithKline plc has advanced the competitive frontier with newer antibiotic options, including Blujepa for gonococcal infections. The introduction of differentiated therapies in this space is significant because it can shift treatment conversations, influence guideline interpretations, and create premium positioning where resistance management and tolerability matter. GSK’s broader anti-infective portfolio also supports cross-utilization and formularies that span multiple STI indications.
On the generic side, Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Cipla Ltd., and Dr. Reddy's Laboratories Ltd. collectively sustain the supply backbone for widely used agents such as azithromycin and doxycycline. Their commercial relevance lies in affordability, availability, and the ability to serve public health programs and private channels alike. In many markets, these manufacturers determine the practical accessibility of first-line regimens and influence the cost floor for competing products.
AbbVie Inc. and Merck & Co., Inc. contribute through antibiotic and anti-infective portfolios that intersect with broader bacterial infection management. While their direct exposure to urethritis-specific prescriptions varies, their commercial footprint, R&D orientation, and collaboration potential can influence supply resilience, pipeline optionality, and cross-indication utilization patterns.
Recent industry developments reinforce how quickly competitive positioning can shift when clinical evidence and regulatory milestones intersect. The 2025 approval landscape for newer gonorrhea-focused therapies, together with late-stage trial readouts for single-dose oral regimens, signals a market in which innovation may reframe standard-of-care discussions over the forecast period. At the same time, generic competition continues to compress price points in core categories, placing a premium on supply reliability, quality assurance, and channel relationships. The research evaluates each major player’s product relevance, geographic reach, pipeline implications, and likely strategic maneuvers so that clients can benchmark their own positioning and identify whitespace or defensive priorities.
Industry Dynamics Shaping 2026 and Beyond
Market performance in the urethritis drugs space is tightly coupled to clinical guidance, resistance trends, procurement structures, and reimbursement policy. These dynamics do not merely influence demand; they redefine which products are preferred, where volume concentrates, and how durable margin profiles can be.
Clinical practice standards remain foundational. Public health guidance continues to emphasize doxycycline-based regimens as preferred therapy for non-gonococcal urethritis, with azithromycin serving as an alternative in defined scenarios. For gonococcal infections, treatment conversations increasingly account for dual-therapy considerations in response to rising antimicrobial resistance. These protocols shape prescribing behaviors, formulary placement, and the relative pull-through of competing products. As stewardship expectations intensify, the ability to align product positioning with guideline-concordant use becomes a commercial advantage, not just a compliance matter.
Antimicrobial resistance is a persistent structural pressure. Emerging resistance patterns in pathogens associated with non-gonococcal urethritis, including Mycoplasma genitalium and Haemophilus spp., are driving interest in resistance-guided therapy and updated stewardship approaches. This trend has two strategic consequences. First, it increases the clinical value of diagnostic alignment and targeted treatment logic, which can shift demand toward therapies that fit resistance-aware protocols. Second, it creates a backdrop in which new or differentiated options may command greater attention where standard regimens face efficacy or tolerability limitations.
Reimbursement and access frameworks further condition the market. Many standard antibiotics used for urethritis are incorporated into public health formularies and STI treatment programs across multiple regions, which supports stable baseline demand but also reinforces price discipline. In parallel, API supply chains for widely used antibiotics depend on established global manufacturing routes, with generic competition driving cost efficiencies in production. For commercial teams, these realities mean that volume growth can be paired with margin compression unless product strategy accounts for channel economics, tender dynamics, and programmatic procurement.
Supply-side resilience is also increasingly strategic. The market relies on mature production ecosystems, but demand timing, regional availability, and regulatory expectations can create localized constraints or opportunity pockets. In this context, the research evaluates not only what is sold, but how products move through institutional and retail ecosystems, which channels are expanding, and where access models may shift as patient behavior and digital fulfillment continue to evolve.
What the Full Study Delivers: Decision-Oriented Intelligence
Our Worldwide Urethritis Drugs Market research is built for practitioners who need more than top-line forecasts. It is structured to support product strategy, commercial planning, market entry evaluation, and competitive response. The study translates epidemiological and regulatory context into market-level implications, then drills into the segments and channels that matter for operational execution.
Inside the report, readers will find:
- A full market sizing and forecast framework spanning the 2020-2025 historical period and the 2026-2032 outlook, with USD-denominated valuation and growth decomposition
- Segment-level analysis across therapeutic categories and distribution channels, with emphasis on volume pathways, channel economics, and adoption dynamics
- Geographic assessment that identifies where demand is concentrated, where expansion is most plausible, and how regional protocols and programs shape market behavior
- Competitive profiling of leading global and generic manufacturers, covering product relevance, portfolio orientation, and strategic positioning within guideline-driven treatment environments
- Analysis of recent regulatory and clinical developments and their likely influence on treatment standards, formulary decisions, and competitive differentiation
- Scenario-based considerations that help teams evaluate uncertainty around resistance trends, guideline updates, reimbursement shifts, and supply chain conditions
The study is designed to answer 2026-specific questions: Where should sales and market access resources be prioritized? Which categories are most exposed to pricing pressure, and which may support stronger positioning? How should companies interpret evolving STI treatment guidance in commercial terms? Which competitors are likely to defend share through cost leadership, and which are positioned to create differentiation through newer options or portfolio breadth? By connecting market structure with competitive behavior and policy context, the research gives teams a defensible basis for planning across short-term execution and mid-term strategy.
Strategic Implications for 2026 Decision-Making
Entering 2026, successful participation in the urethritis drugs market will depend on three capabilities: reading guideline-driven demand accurately, managing channel and pricing dynamics with discipline, and anticipating where innovation or resistance trends alter the value map. Aggregate growth is supportive, but the real differentiator is how well a company aligns its portfolio, access strategy, and supply posture with the way treatment protocols and reimbursement structures are evolving.
For innovators, the opportunity lies in converting clinical differentiation into durable positioning. Where newer options address resistance concerns, tolerability, or dosing convenience, the strategic task is to demonstrate fit with stewardship expectations and to secure the formulary and procurement relationships that convert clinical relevance into realized demand. For generic manufacturers, the priority is to protect availability, manage cost structures, and navigate programmatic procurement without eroding quality or reliability. For all participants, channel strategy matters: hospital, retail, and online pathways are not interchangeable, and each responds differently to prescription behavior, reimbursement policy, and access programs.
The wider lesson is that market intelligence in this space must be multidimensional. A single growth rate or total market figure is insufficient for planning. Decision-makers need to understand how therapeutic segmentation interacts with channel economics, how resistance trends influence preferred regimens, how guidelines steer volume, and how competitor portfolios shape negotiation dynamics. The full study is built to provide that integrated view.
Access the Full Intelligence
This article has outlined the strategic logic behind the Worldwide Urethritis Drugs Market research and the major forces shaping the 2026-2032 outlook. The detailed segmentation, competitive profiles, channel analysis, and scenario frameworks necessary for concrete commercial decisions are developed in the full report. For executives seeking to translate market momentum into targeted action, the complete study provides the depth required to plan with confidence.
To access the complete worldwide urethritis drugs market research, including full segmentation detail, competitive benchmarking, and forecast breakdowns, visit the PW Consulting report page for this study.
Worldwide Urethritis Drugs Market
For detailed analysis of this topic, please visit the official page: Worldwide Urethritis Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: TRIS Buffer Market Size Hits $324.47M in 2025, 6.32% CAGR to $498.29M by 2032
By pmarketresearch, 2026-09-16
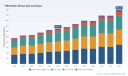
Strategic Imperatives in the Global TRIS Buffer Market: Navigating Growth, Regulation, and Supply Chain Resilience Through 2032
The worldwide TRIS buffer market stands at a critical inflection point. As life sciences, biopharmaceutical manufacturing, and diagnostic applications continue to scale, the demand for reliable, high-purity buffering solutions has become a foundational requirement for research and commercial production alike. For executive teams, procurement leaders, and R&D directors, understanding the trajectory of this market is no longer optional. It is a strategic necessity. PW Consulting's latest Worldwide TRIS Buffer Market research report delivers the comprehensive intelligence required to make informed decisions in 2026 and beyond.
This article serves as a preview of the depth and rigor embedded in our full analysis. It outlines the macro-level dynamics, competitive forces, regulatory headwinds, and operational considerations that will shape the market through the forecast period ending in 2032. The complete report, however, contains the granular segmentation, regional breakdowns, application-level revenue splits, and actionable scenario models that decision-makers require. Access the full intelligence to equip your organization with the precision data needed for 2026 planning.
Market Trajectory: Sustained Expansion Anchored by Life Sciences Demand
The TRIS buffer market has demonstrated consistent growth over the past half-decade, reflecting the broader expansion of biotechnology, molecular diagnostics, and pharmaceutical development. Our historical analysis captures a market that has moved from a baseline of approximately 238.15 million USD in 2020 to an estimated 324.47 million USD by 2025. This upward trajectory is projected to continue, with the market expected to reach 339.71 million USD in 2026 and accelerate toward 498.29 million USD by 2032.
The compound annual growth rate of 6.32 percent across the 2026 to 2032 forecast window underscores a market that is both mature enough to offer stable returns and dynamic enough to present meaningful opportunities for strategic positioning. Growth is being propelled by several structural drivers: the increasing complexity of nucleic acid analysis workflows, the rising adoption of protein purification in bioprocessing pipelines, and the ongoing expansion of cell culture applications in research and commercial manufacturing.
At the same time, the market is not without its tensions. Capacity constraints, raw material cost volatility, and shifting regulatory frameworks introduce variables that can disrupt pricing stability and supply continuity. Our report dissects these dynamics in detail, providing leaders with the context needed to anticipate disruptions and structure resilient procurement strategies.
Competitive Landscape: A Fractured Ecosystem with Concentrated Influence
The TRIS buffer market is characterized by a diverse array of participants, ranging from global life sciences conglomerates to specialized fine chemical manufacturers and regional producers with significant production capacity. This diversity creates both opportunities and challenges. Buyers benefit from multiple sourcing options, but the lack of uniformity in quality standards, production capabilities, and geographic reach can complicate vendor selection and long-term supply agreements.
Market concentration metrics indicate that the top three players account for a substantial share of total market revenue, while the top five collectively command a majority of the market. This concentration suggests that scale, integrated production, and established distribution networks provide meaningful competitive advantages. Yet, the presence of numerous mid-tier and regional manufacturers ensures that niche applications, custom formulations, and price-sensitive segments remain highly contested.
Several key companies illustrate the breadth of strategies currently shaping the market. Advancion Corporation, operating as the world's only fully integrated manufacturer of TRIS AMINO and TRIS HCl buffers, has built a dual-site production footprint spanning the United States and Germany. Its ISO 9001:2015-certified operations deliver Standard, ACS, and advanced crystal grades tailored for bioprocessing and life sciences. In recent months, Advancion has moved aggressively to strengthen its supply chain position, expanding U.S. manufacturing capabilities at its Sterlington, Louisiana facility with the commercial launch of MOPS buffer production, and broadening its North American distribution agreement for TRIS AMINO buffers and related life science ingredients.
Hopax Fine Chemicals, based in Taiwan, supplies TRIS and TRIS HCl buffers at purity levels of 99 percent or higher, with analytical testing for DNase, RNase, protease, and heavy metals. Its focus on bulk quantities for cell culture media, diagnostic tests, and biochemical applications positions it as a relevant supplier for customers prioritizing tested purity at scale. Suzhou Yacoo Science Co., Ltd. and Jiangsu Tianjiayi Chemical Co., Ltd. represent the significant production capacity emanating from China, with Yacoo specifically emphasizing high-purity grades for life science and research use. Desheng, also based in China, has built a global customer base for TRIS base biological buffers.
On the global supplier side, Merck KGaA (Sigma-Aldrich) offers an extensive range of TRIS base, TRIS HCl, and pre-made buffer solutions for electrophoresis, chromatography, ELISA, and molecular biology. Thermo Fisher Scientific supplies TRIS buffers and solutions, including 1.0M formulations at various pH levels, supporting nucleic acid and protein stabilization in research and bioprocessing. Avantor provides TRIS buffers and solutions through its VWR and J.T.Baker brands, targeting life science, biopharma, and laboratory applications. Bio-Rad Laboratories, Boston BioProducts, Promega Corporation, and FUJIFILM Wako Pure Chemical Corporation each contribute specialized offerings, from cGMP-quality custom buffers to research-grade reagents for electrophoresis and molecular biology workflows.
Understanding the strategic positioning, capability gaps, and recent moves of these players is essential for competitive sourcing, partnership evaluation, and market entry planning. Our full report provides detailed company profiles, capability comparisons, and an analysis of how recent developments are reshaping the competitive hierarchy.
Regulatory and Supply Chain Headwinds: Navigating a Complex Environment
The TRIS buffer market operates within an evolving regulatory and trade environment that demands close attention. In April 2026, Advancion Corporation filed antidumping and countervailing duty petitions on Tris (hydroxymethyl)aminomethane and Tris HCl from China, alleging dumping margins of up to 965.62 percent. The petitions cover all grades, purities, and forms, and the potential tariffs could significantly impact imports into the United States. For buyers with exposure to Chinese-sourced TRIS products, this development introduces a new layer of uncertainty that must be factored into sourcing strategies, inventory planning, and cost modeling.
Beyond trade policy, raw material dynamics are exerting pressure on production and pricing. Industry data indicates that global production capacity for tris(hydroxymethyl)aminomethane reached approximately 25,000 metric tons in 2023, with actual consumption estimated at 22,400 metric tons. Biological-buffer applications account for a substantial portion of total usage, reflecting the centrality of TRIS to life sciences workflows. However, approximately 28.7 percent of producers report that raw material cost fluctuations are a significant factor limiting production and pricing stability. This volatility can cascade through the value chain, affecting lead times, contract pricing, and the feasibility of long-term supply agreements.
Quality standards further complicate the landscape. TRIS and TRIS HCl products are primarily supplied for research use, bioprocessing, diagnostics, and pharmaceutical intermediates, and they are subject to quality standards such as ACS, ISO 9001:2015, and multicompendial cGMP grades depending on the application. Buyers must therefore align supplier capabilities with end-use requirements, ensuring that purity, testing protocols, and documentation meet the demands of their specific workflows. Our report provides a structured framework for evaluating these requirements across applications and regulatory contexts.
Report Contents: Actionable Intelligence for 2026 Decision-Making
The full Worldwide TRIS Buffer Market report is designed to translate macro-level trends into operational guidance. It moves beyond high-level summaries to deliver the specific insights that procurement teams, R&D leaders, and strategy professionals need to act with confidence. Below is an overview of the core components included in the analysis.
Comprehensive Market Sizing and Forecast Modeling
The report provides historical market sizing from 2020 through 2025, establishing a verified baseline for trend analysis, and extends into a detailed forecast through 2032. Revenue projections are presented in USD millions, enabling direct integration into financial models and budgeting processes. The forecast methodology accounts for demand drivers, capacity constraints, and regulatory variables, offering a range of scenarios that help leaders stress-test their assumptions.
Segmentation Analysis Across Demand Drivers
While the full report contains detailed segmentation data, it is structured around the key dimensions that matter most to buyers and strategists. Analysis covers demand patterns by purity grade, distinguishing between biological-grade and industrial-grade applications, and examines how usage varies across major application areas including nucleic acid analysis, protein purification, cell culture, and biopharmaceutical manufacturing. Regional breakdowns are also provided, mapping demand and supply dynamics across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each segmentation is analyzed not only in terms of current value but also in terms of growth trajectory, competitive intensity, and strategic relevance.
Competitive Intelligence and Company Profiles
The report includes in-depth profiles of the key companies shaping the market. Each profile examines production capabilities, product portfolios, quality certifications, geographic reach, and recent strategic moves. The analysis is supplemented by a review of recent industry developments, including capacity expansions, distribution agreements, and product launches that signal shifting competitive dynamics. This section is intended to help buyers evaluate vendor reliability, compare alternatives, and identify potential partnership or sourcing opportunities.
Regulatory, Trade, and Raw Material Dynamics
Given the potential impact of trade policy and input cost volatility, the report dedicates significant attention to regulatory and supply chain factors. This includes an analysis of the implications of antidumping and countervailing duty petitions, the status of raw material cost fluctuations, and the quality standards that govern product selection across different applications. The report also contextualizes these factors within broader industry trends, helping leaders anticipate how policy changes and input market conditions may affect availability and pricing.
Worldwide TRIS Buffer Market
Bio Pharma Buffer Market
Strategic Recommendations and Scenario Planning
Beyond descriptive analysis, the report offers actionable guidance for navigating the market. This includes recommendations for sourcing strategy, risk mitigation, supplier evaluation, and capacity planning. Scenario-based discussions help leaders consider how different regulatory outcomes, cost environments, and demand shifts could affect their operations, enabling more robust decision-making in an uncertain landscape.
Why the Full Report Matters for 2026 Strategy
The macroeconomic trends and competitive dynamics outlined in this preview illustrate a market that is growing steadily but is also subject to significant variables that can disrupt planning. The antidumping petitions targeting Chinese-origin TRIS products, the reported raw material cost pressures affecting nearly a third of producers, and the capacity expansions underway at key manufacturing sites all signal that the market is in flux. For organizations that rely on TRIS buffers for research, bioprocessing, diagnostics, or manufacturing, these variables carry real consequences for cost, continuity, and compliance.
Partial information is insufficient for making high-stakes decisions. Leaders need detailed segmentation data to understand where growth is concentrated, regional analysis to identify supply risks and opportunities, company-level intelligence to evaluate vendors and track competitive moves, and scenario models to prepare for multiple futures. The full Worldwide TRIS Buffer Market report delivers this depth, providing the intelligence required to structure procurement strategies, evaluate market entry or expansion opportunities, and align R&D and production planning with realistic demand forecasts.
The base year of 2025 and the forecast window extending to 2032 position this research as a timely resource for 2026 planning cycles. Whether your organization is optimizing its supplier base, assessing the impact of trade policy on sourcing costs, or evaluating the growth potential of specific application segments, the complete report offers the structured, data-driven insight needed to move forward with confidence.
To access the full analysis, including detailed segmentation figures, regional breakdowns, competitive profiles, and scenario models, visit the source page for the Worldwide TRIS Buffer Market report. Equip your team with the intelligence required to navigate this evolving market and make strategic decisions that support long-term resilience and growth.
For detailed analysis of this topic, please visit the official page: Worldwide TRIS Buffer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plastic Bracket Market to Grow at 5.82% CAGR to $369.37M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Global Motorcycle Headlight Bracket Market
The motorcycle component ecosystem is undergoing a period of structural transformation. As manufacturers and aftermarket suppliers alike recalibrate their product portfolios, the headlight bracket segment has emerged as a critical nexus of engineering precision, regulatory compliance, and consumer customization. Our latest market research offers a comprehensive, data-driven blueprint of the Worldwide Motorcycle Headlight Bracket Market, designed specifically to equip executive teams with the foresight required for 2026 decision-making. This analysis moves beyond surface-level trends to dissect the mechanical, economic, and competitive forces that will shape revenue trajectories through the end of the decade.
Macro Trajectory: A Baseline of Sustained Expansion
The market has demonstrated resilient upward momentum across the historical review window. From a baseline of approximately 185.3 million USD in 2020, revenue progression has accelerated steadily, crossing the 220 million USD threshold by 2023 and reaching an estimated 248.6 million USD by the 2025 base year. Forward projections indicate continued growth, with the market expected to expand to 268.76 million USD in 2026 before ascending toward a peak valuation of roughly 370.41 million USD by 2031. The forecast period through 2032 reflects a compound annual growth rate of 5.82 percent, signaling a mature yet dynamically expanding sector that rewards manufacturers and distributors who align their strategies with underlying demand drivers.
This trajectory is not merely a function of unit sales growth. It reflects deeper structural shifts: the integration of advanced lighting architectures, the proliferation of custom and semi-custom motorcycle builds, and the ongoing migration toward lightweight, corrosion-resistant mounting solutions. For strategic planners, these numbers provide a quantitative anchor. Yet the real strategic value lies in understanding what forces are compressing or expanding margins, how material science is reshaping product specifications, and which distribution channels will capture disproportionate value as the market matures.
Market Architecture: Material, Channel, and Application Dimensions
The competitive landscape is fundamentally shaped by how manufacturers segment their offerings across material specifications, sales channels, and motorcycle classifications. Aluminum alloy has firmly established itself as the dominant structural material for headlight brackets, driven by its favorable strength-to-weight ratio, inherent corrosion resistance, and compatibility with precision machining processes. Steel continues to occupy specific durability-focused applications, while stainless steel and carbon fiber composites serve niche performance and aesthetic segments. The interplay between material cost volatility, particularly in aluminum markets, introduces a critical variable for production cost modeling and pricing architecture.
Worldwide Automotive Bracket Market
Distribution dynamics further complicate the landscape. The OEM channel maintains a substantial footprint, anchored by original equipment suppliers who integrate headlight mounting solutions directly into factory assembly lines. Simultaneously, the aftermarket segment is expanding rapidly, fueled by the rise of custom motorcycle culture, the increasing popularity of electric two-wheelers requiring adapted lighting configurations, and consumer demand for CNC-machined, adjustable mounting platforms. This bifurcation between factory-integrated and post-purchase modification channels creates distinct opportunity zones for suppliers capable of serving both volume-driven production environments and high-mix, low-volume customization workflows.
Application segmentation reveals additional layers of complexity. Standard and commuter motorcycles continue to represent a significant volume base, while cruisers, choppers, sport bikes, and off-road or adventure platforms each impose different geometric, thermal, and load-bearing requirements on bracket designs. Understanding which application segments are expanding fastest, and how mounting geometries are adapting to varying fork diameters and integrated wiring harnesses, is essential for firms developing product roadmaps or evaluating acquisition targets.
Competitive Landscape: A Fragmented Field with Strategic Chokepoints
The market exhibits a moderate degree of concentration, with the top three players collectively commanding a substantial share of total revenue and the top five firms consolidating a broader portion of industry output. This structure indicates a competitive environment where scale, engineering capability, and channel relationships serve as meaningful barriers to entry, even as specialized manufacturers carve out defensible niches through material innovation and regional specialization.
Leading European manufacturers have built reputations around precision engineering and premium material finishes. Italian operations have focused on fork-mounted bracket designs that actively mitigate road-induced vibrations, frequently utilizing brushed aluminum construction to balance aesthetic refinement with functional durability. German suppliers have emphasized individually adjustable premium brackets engineered for common fork diameters, leveraging CNC-machined aluminum to deliver certified quality standards and design-forward configurations. These European capabilities reflect a broader industry emphasis on vibration dampening, aesthetic consistency, and adherence to rigorous quality protocols.
North American manufacturers have pursued a different strategic emphasis, often targeting the custom motorcycle and direct-replacement segments. US-based producers have developed brackets machined from high-grade aluminum alloys specifically for secure fork tube mounting, with design philosophies that minimize installation friction, such as eliminating the need for top clamp removal during retrofitting. Parallel US operations have expanded into LED lighting ecosystems, offering compatible brackets and mounts across major legacy brands while emphasizing durable replacement and conversion solutions for aging fleets.
Asian manufacturing hubs have scaled rapidly by combining precision fabrication with competitive cost structures. Taiwanese operations have introduced standardized and premium CNC aluminum bracket series designed for both auxiliary lighting and primary headlight mounting, emphasizing straightforward installation and long-term durability. Chinese metal fabricators have expanded production of high-strength carbon steel and alternative alloy brackets, while specialized accessory suppliers have broadened their portfolios to capture cross-border distribution channels. These regional capabilities have steadily increased their influence across both OEM supply networks and global aftermarket channels.
Tier-one motorcycle OEMs remain influential anchors within the ecosystem. Major manufacturers supply genuine headlight brackets and relocation kits as original equipment components, establishing baseline specifications that aftermarket innovators must navigate. Premium OEMs continue to release updated mounting hardware across refreshed model cycles, reinforcing the importance of technical alignment between factory designs and aftermarket adaptation kits. The interplay between OEM specification control and aftermarket innovation creates a dynamic tension that rewards firms capable of rapid prototyping, materials engineering, and regulatory-aware design.
Regulatory and Supply Chain Dynamics: Navigating Constraints and Catalysts
Regulatory frameworks have become an increasingly salient factor in bracket design and qualification. In the United States, Federal Motor Vehicle Safety Standard FMVSS 108 specifies requirements for motorcycle headlighting systems, including mounting and performance criteria that indirectly shape bracket geometry, durability expectations, and attachment methodologies. Stringent safety standards across multiple jurisdictions mandate the use of high-quality, durable brackets that satisfy specific mounting integrity and impact-resistance criteria. Compliance is no longer a peripheral concern; it is a core engineering parameter that influences material selection, fastening mechanisms, and testing protocols.
Worldwide Motorcycle Headlight Bracket Market
Supply chain volatility introduces an additional strategic layer. Fluctuations in raw material pricing, particularly within aluminum markets, directly impact production cost structures and short-term margin planning. Firms that maintain diversified sourcing strategies, implement forward-contracting Discipline, or invest in lightweight design optimization are better positioned to absorb commodity volatility without compromising competitive pricing. The intersection of material science, manufacturing efficiency, and regulatory compliance creates a multi-variable optimization challenge that separates reactive operators from strategically agile manufacturers.
What the Full Report Delivers: Operational Intelligence for Executive Teams
This market research publication is structured to translate macro trends into actionable strategic inputs. The report provides a detailed segmentation framework that maps revenue distribution across material categories, sales channels, and motorcycle applications, enabling readers to identify high-growth subsegments without relying on generalized market narratives. Regional performance is assessed through a comparative lens that highlights leading demand centers, supply base maturity, and growth acceleration patterns, offering a geographic roadmap for capacity planning, distribution expansion, and partnership evaluation.
Competitive profiling extends beyond basic company descriptions to examine positioning strategies, material and manufacturing capabilities, product architecture philosophies, and channel orientations. Profiles covering Italian, German, US, Taiwanese, Chinese, and French operations, alongside tier-one OEM participants, provide a panoramic view of how incumbents are competing on quality certification, customization flexibility, installation efficiency, and aftermarket support. This multi-dimensional competitor mapping allows strategy teams to benchmark their own capabilities, identify white-space opportunities, and anticipate competitive responses as the market consolidates around quality and engineering differentiation.
The research also integrates regulatory context and supply chain dynamics into a unified market dynamics assessment. Readers gain clarity on how safety standards shape design requirements, how raw material price movements influence cost structures, and how the expanding aftermarket ecosystem interacts with OEM specification cycles. This synthesis is particularly valuable for product managers evaluating new bracket architectures, procurement teams modeling input cost scenarios, and commercial leaders assessing channel mix strategies across OEM and aftermarket segments.
Importantly, the full report preserves analytical depth while protecting proprietary segmentation figures and region-specific revenue allocations. This deliberate structure ensures that the intelligence remains decision-ready and commercially sensitive, encouraging stakeholders to engage with the complete dataset for precise forecasting, scenario modeling, and investment justification.
Strategic Imperatives for 2026 Decision-Making
As the market advances toward its projected mid-decade expansion, several strategic imperatives become evident. Firms should prioritize engineering investments that reduce dependency on volatile commodity inputs while maintaining structural integrity and aesthetic quality. Expanding compatibility across common fork diameters and streamlining installation procedures will continue to differentiate aftermarket suppliers in an increasingly crowded field. OEM-adjacent players should evaluate how updated factory specifications and LED-integrated lighting architectures may reshape bracket attachment requirements and aftermarket retrofit demand.
Distribution strategy also warrants renewed focus. The coexistence of high-volume OEM supply and customization-driven aftermarket demand creates an opportunity for hybrid commercial models that balance production efficiency with engineering flexibility. Companies that can anticipate regional demand shifts, align material procurement with forecasted growth, and position themselves within both factory supply chains and independent distributor networks will capture disproportionate value as the market matures.
Accessing the Complete Intelligence Framework
This overview establishes the analytical foundation and strategic relevance of the Worldwide Motorcycle Headlight Bracket Market research. The complete report extends far beyond these thematic highlights, providing detailed segmentation data, region-specific growth assessments, competitive capability comparisons, and forward-looking scenario analysis designed for 2026 planning cycles and beyond. For executives, product leaders, and investment teams seeking precise, defensible market intelligence, the full dataset offers the granularity necessary to convert directional insight into executable strategy. We invite stakeholders to access the complete report to unlock the full breadth of segmentation breakdowns, competitive evaluations, and forecast modeling tools that will inform critical decisions in the year ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Motorcycle Headlight Bracket Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com